
 Squeeze Pouch Market | 2026-2036
Squeeze Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Squeeze Pouch Market Analytics
Aftermarket recycling and collection service revenue is narrowing as brand owners internalize circularity obligations. Amcor leverages its global film extrusion network to control substrate supply for North American pouch converters. Berry Global anchors its position through vertical integration into injection-molded spout and cap production. Huhtamaki competes with specialized high-barrier coating technologies that extend shelf life for retort-sensitive food applications.
A squeeze pouch is a flexible laminated package with a sealed bottom and a fitment-attached opening, typically constructed from coextruded polyethylene, polyester, or aluminum oxide-coated films, designed for single-handed dispensing of semi-liquid or viscous contents. Spout closure configurations now dominate infant nutrition and adult beverage applications where controlled portioning determines consumer preference. Compostable material grades represent the fastest-expanding product type segment as European retailers enforce packaging reduction mandates. The food application category sustains the deepest margin pools, particularly in organic puree and ready-to-drink smoothie formats where premium pricing offsets higher barrier film costs.
The FDA regulates contact-layer polymer safety under 21 CFR 177 while the EPA oversees post-consumer recycling infrastructure development that directly affects pouch end-of-life economics. The EU Green Deal and REACH chemical compliance frameworks are forcing substrate reformulation across export-oriented converters. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in mono-material recyclable structures or advanced compostable barrier technologies before regulatory thresholds harden.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate reformulation across the squeeze pouch value chain, compelling converters to choose between mono-material recyclable structures and compostable barrier technologies before compliance deadlines harden.
Growth Catalysts
- Retort-compatible high-barrier coatings:Advanced aluminum oxide and silicon oxide deposition technologies enable shelf-stable baby food without foil laminates, satisfying retailer sustainability mandates while maintaining 18-month shelf life.
- Single-serve beverage demand:Adult nutrition and functional drink brands are adopting spouted pouches for gym and workplace consumption, displacing rigid bottles in grab-and-go retail formats.
- Extended Producer Responsibility schemes:France, Germany, and Italy are implementing fee-modulated EPR frameworks that financially reward recyclable or compostable pouch designs over multi-material alternatives.
Market Restraints
- Ethylene and propylene feedstock volatility:Coextruded polyethylene films constitute 60-70% of pouch mass, exposing converters to petrochemical price swings that compress margin on fixed-price retail contracts.
- Aluminum foil supply concentration:High-barrier retort pouches depend on foil sourced from a limited number of European and Asian rolling mills, creating input bottlenecks during energy price spikes.
- Mechanical recycling incompatibility:Multi-layer PET/PE/foil laminates lack viable sortation streams in most municipal MRF infrastructure, forcing reliance on niche chemical recycling capacity that remains geographically sparse.
Strategic Opportunities
- Compostable substrate certification:TÜV Austria and BPI-certified home-compostable films command 15-25% price premiums in German and Benelux retail channels where organic food brands prioritize circular packaging claims.
- Pharmaceutical liquid dosing:Unit-dose oral medication and nutraceutical pouches remain underdeveloped relative to food applications, offering white space for barrier technologies validated to USP Class VI standards.
- Direct-to-subscription fulfillment:Meal kit and pediatric nutrition subscription services are specifying custom pouch formats with resealable fitments, bypassing traditional retail slotting fee structures entirely.
Industry Challenges
- Barrier coating technician scarcity:Vacuum deposition and atomic layer deposition processes require specialized operators whose training pipelines lag equipment installation timelines by 18-24 months.
- Migration testing timeline compression:FDA 21 CFR 177 compliance for new coextruded structures demands 6-12 month stability studies, delaying product launches behind faster-moving competitors with approved material libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squeeze Pouch Market |
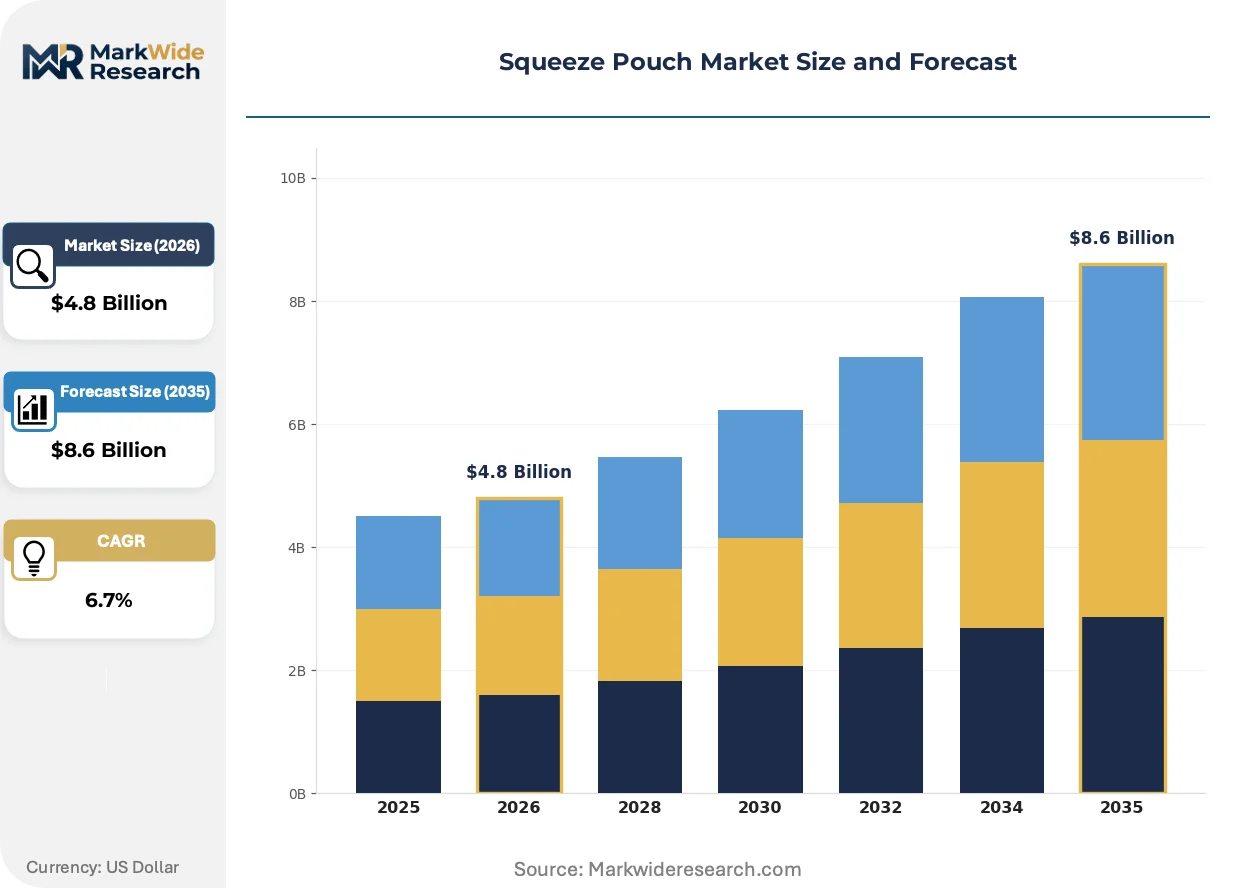
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Compostable, Hybrid Closure Type: Spout, Screw Cap, Slider, Zipper Application: Food, Beverage, Personal Care, Cosmetics End User: Household, Food Service, Retail, Institutional |
| Companies Covered | Coveris, Berry Global, Amcor, Constantia Flexibles, Huhtamaki, Mondi Group, Sonoco Products Company, Sealed Air Corporation, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squeeze Pouch Market Evolving Landscape
Digital printing and smart packaging integration are collapsing minimum order quantities and enabling lot-level traceability, transforming how brands manage SKU proliferation and recall risk across fragmented retail channels.
Digital flexographic and inkjet printing systems are virtualizing plateless production workflows for short-run seasonal and promotional pouch designs. Organic food startups with 10,000-unit campaign needs now access print economics previously reserved for million-unit food conglomerates. This capability is virtualizing the traditional volume barrier between national brands and private label entrants.
REACH chemical compliance frameworks are restricting per- and polyfluoroalkyl substance use in grease-resistant coatings, forcing converters to validate silicone and clay-based alternatives for oily food applications. The regulatory pressure is most acute in German retail channels, where REWE and EDEKA have advanced their own 2025 PFAS elimination deadlines ahead of EU-wide restrictions.
Retail buyer consolidation is compressing supplier qualification cycles and demanding real-time inventory visibility through EDI-linked vendor-managed inventory programs. Discounters Aldi and Lidl now specify four-week replenishment horizons with penalty clauses for stockouts, shifting working capital burden upstream to pouch converters and their film suppliers.
Squeeze Pouch Market Segmentation
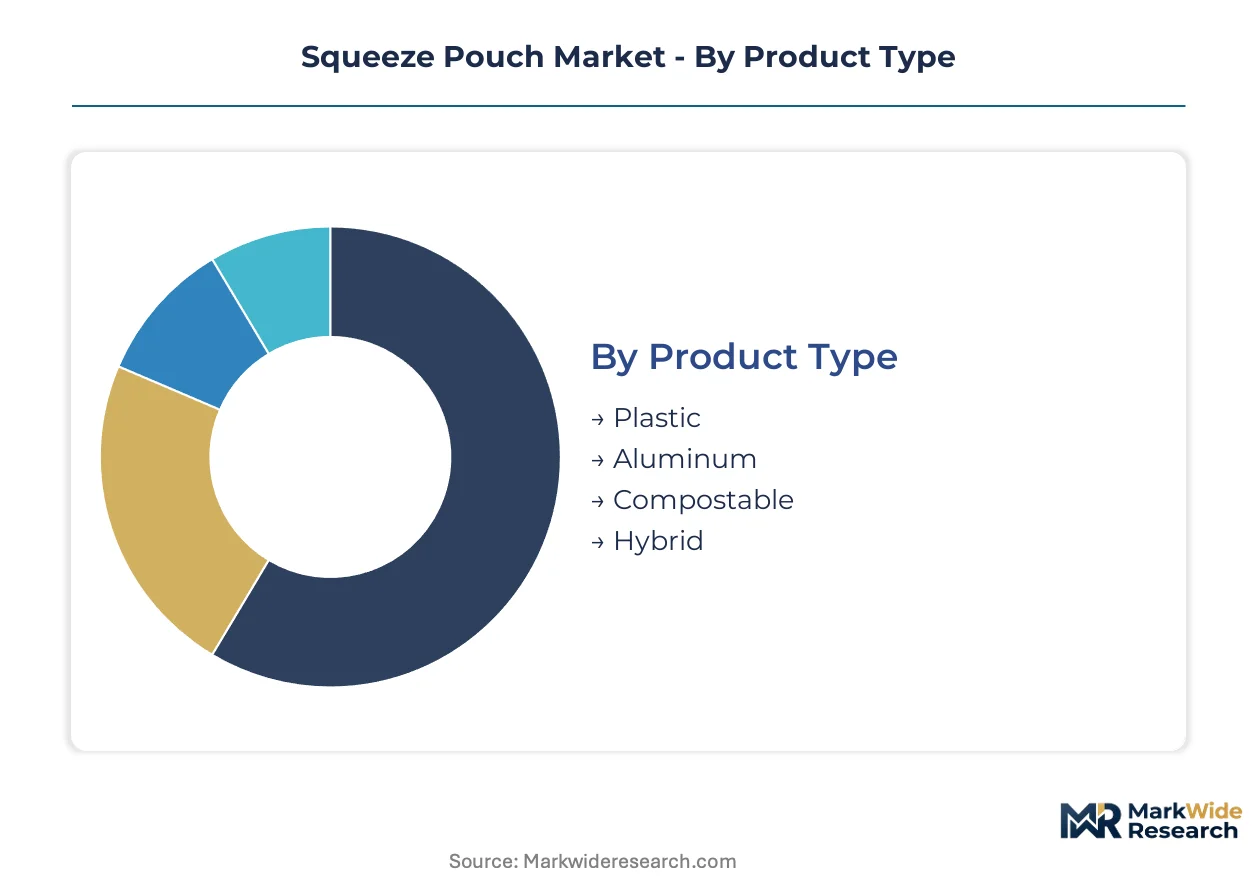
Squeeze pouch segmentation reveals how substrate chemistry, closure mechanics, and channel economics create distinct margin pools. Understanding these divisions helps converters allocate capital between barrier technology investments and format flexibility.
Product Type:
Cost tier differentiation separates commodity substrates from certified sustainable alternatives, with pricing spreads widening as European retailers enforce packaging reduction mandates.
- Plastic:Coextruded polyethylene and polyester laminates dominate volume through retort-compatible multi-layer structures. Baby food brands in the United States specify these for 18-month shelf stability despite mechanical recycling incompatibility.
- Compostable:TÜV Austria and BPI-certified home-compostable films command price premiums in German and Benelux organic retail channels. Demand concentrates where REWE and EDEKA have advanced PFAS-free packaging deadlines ahead of EU-wide restrictions.
- Aluminum:Foil-containing high-barrier laminates serve oxygen-sensitive applications requiring extended ambient storage.
- Hybrid:Aluminum oxide or silicon oxide coated films enable foil-free barrier performance for sustainability-positioned brands.
Plastic holds installed capacity. Compostable is rotating up the share rankings.
Closure Type:
Application mechanics determine which dispensing interface dominates—controlled portioning drives spout adoption while resealability favors slider and zipper formats in multi-serve contexts.
- Spout:Injection-molded fitments with tamper-evident bands anchor infant nutrition and adult beverage applications where single-handed operation matters. Gym and workplace consumption patterns in the United States favor this format for grab-and-go functional drinks.
- Screw Cap:Threaded closures suit larger-volume household refills and industrial food service pouches requiring secure transport.
- Slider:Track-based reseal mechanisms serve multi-serve food applications where repeated access preserves freshness.
- Zipper:Interlocking profile closures compete in personal care and cosmetic segments where premium unboxing experience justifies higher component cost.
Spout configurations lead volume share. Slider mechanisms are climbing the fastest in meal kit subscription channels.
Application:
Margin concentration varies sharply by contents—food and beverage sustain premium pricing while personal care and cosmetics operate on different certification and aesthetic requirements.
- Food:Organic puree and ready-to-drink smoothie formats generate the deepest margin pools where barrier film costs are offset by premium retail positioning. Retort-sensitive baby food applications demand the most sophisticated substrate engineering.
- Beverage:Single-serve functional and adult nutrition drinks displace rigid bottles in workplace and fitness-oriented retail formats. This segment shows steepest expansion trajectory as brands bypass traditional slotting fees through direct subscription fulfillment.
- Personal Care:Unit-dose lotions, shampoos, and sanitizers leverage pouch convenience for travel and hospitality channels.
- Cosmetics:Sample-sized serum and mask pouches serve premium beauty trial programs and airline amenity kits.
Food commands production scale. Beverage is gaining share fastest among format-flexible contract manufacturers.
End User:
Customer type shapes order economics—retail and food service drive volume while household and institutional segments impose distinct specification and replenishment requirements.
- Retail:Branded and private label shelf placement demands real-time inventory visibility through EDI-linked vendor-managed programs. Aldi and Lidl in Germany now specify four-week replenishment horizons with stockout penalties.
- Food Service:Bulk dispensing pouches for commercial kitchens and catering operations prioritize cost efficiency over aesthetic finish.
- Household:Direct-to-consumer subscription services specify custom formats with resealable fitments, bypassing traditional retail slotting structures entirely.
- Institutional:Healthcare and educational facility procurement runs on extended contract cycles with standardized specifications.
Retail anchors converter capacity utilization. Household subscription channels are expanding most quickly as meal kit services scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France show low price elasticity for compostable-certified pouches, while converters in India and Mexico face acute margin compression from feedstock volatility. The United States sits in the middle—premium single-serve beverage demand sustains pricing power, yet mass-market baby food segments resist pass-through of film cost increases.
United States
Single-serve functional beverages and organic baby food pouches drive premium format adoption through gym, workplace, and direct-to-subscription channels. FDA 21 CFR 177 compliance timelines for new coextruded structures create six-to-twelve month entry barriers for substrate innovators. Chicago and Minneapolis anchor converter capacity serving national retail chains with real-time EDI-linked inventory programs.
Germany
REWE and EDEKA have advanced PFAS-free packaging deadlines to 2025, accelerating demand for TÜV Austria-certified home-compostable films. The EU Packaging and Packaging Waste Regulation forces converters to choose between mono-material recyclable and compostable barrier technologies before 2030 compliance thresholds. The Düsseldorf-Cologne corridor concentrates flexible packaging R&D and high-barrier coating pilot lines.
France
Fee-modulated Extended Producer Responsibility frameworks financially reward recyclable pouch designs, shifting procurement specifications for private-label organic puree brands. ECHA REACH restrictions on per- and polyfluoroalkyl substances in grease-resistant coatings compel silicone and clay-based alternative validation. The Lyon-Grenoble cluster houses specialized vacuum deposition equipment serving retort-sensitive food applications.
India
Domestic baby food brands are shifting from rigid jars to flexible pouches for urban retail and e-commerce fulfillment, though price sensitivity limits barrier film upgrades. FSSAI food contact safety standards and BIS polymer specifications create dual compliance burdens for imported substrate formulations. The Mumbai-Pune industrial corridor hosts emerging converter capacity targeting quick-commerce replenishment cycles.
Mexico
Nearshoring demand from US meal kit and pediatric nutrition subscription services drives custom pouch format specification with resealable fitments. PROFEPA environmental enforcement and evolving extended producer responsibility discussions create regulatory uncertainty for multi-material laminate disposal economics. Querétaro and Guadalajara concentrate thermoforming and injection-molded spout production for North American supply chain integration.
Squeeze Pouch Market Competitive Landscape
Integrated film extruders and specialized high-barrier coaters split the market between substrate supply control and technical differentiation. Three archetypes dominate: global packaging conglomerates with captive polymer supply, regional converters with vertical integration into fitment molding, and technology-focused specialists in aluminum oxide and silicon oxide deposition. Competitive moves center on backward integration into resin compounding and strategic partnerships with compostable film certification bodies.
Among global packaging conglomerates, Amcor exemplifies substrate supply control through film extrusion network ownership, while Berry Global anchors converter positioning through in-house production of injection-molded spouts and caps. Huhtamaki occupies a specialist tier focused on high-barrier coating technologies for retort-sensitive applications.
| Leading Market Players |
|---|
| Coveris |
| Berry Global |
| Amcor |
| Constantia Flexibles |
| Huhtamaki |
| Mondi Group |
| Sonoco Products Company |
| Sealed Air Corporation |
| ProAmpac |
| Others |
Value Network & Pricing Analysis
The Rotterdam-Antwerp petrochemical corridor channels polyethylene resin flows that determine converter margin structures across Northern Europe, with freight cost volatility amplifying price spreads between certified compostable substrates and commodity multi-layer laminates.
Pricing Analysis
Aftermarket collection service revenue streams are narrowing as brand owners internalize circularity obligations under Extended Producer Responsibility schemes. Pricing stratifies across TÜV Austria-certified compostable films, FDA-compliant retort barriers, and standard polyethylene laminates. Cost compression in commodity grades is intensifying because fixed-price retail contracts prevent ethylene feedstock pass-through. Mass-market baby food brands in the United States exhibit highest price sensitivity, while German organic retailers show lowest elasticity for certified sustainable alternatives.
Supply Chain Analysis
Ethylene and propylene feedstock supply draws from concentrated petrochemical complexes in Belgium, the Netherlands, and Germany, with coextruded polyethylene films comprising the dominant input mass. Aluminum foil for high-barrier retort applications sources from limited European and Asian rolling mills. Single-source vulnerability in foil supply creates bottlenecks during energy price spikes. Distribution runs through converter networks anchored in Chicago, Minneapolis, Düsseldorf-Cologne, and Mumbai-Pune corridors serving retail and subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostable substrate certification services represent a service-attach opportunity expanding faster than base film production, as European retailers advance PFAS-free packaging deadlines ahead of regulatory mandates.
For Market Incumbents: Harden barrier coating technician pipelines through apprenticeship partnerships with technical institutes, addressing the 18-24 month training lag behind equipment installation timelines. Consolidate control over injection-molded spout supply through backward integration or long-term capacity reservations, defending against emerging regional converters in Mexico and India. Prioritize mono-material recyclable structure R&D to meet hardening EU Packaging and Packaging Waste Regulation thresholds. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical liquid dosing pouches, where USP Class VI barrier validation requirements have kept competition sparse relative to food applications. Target direct-to-subscription fulfillment channels for meal kit and pediatric nutrition services, bypassing traditional retail slotting fee structures entirely. Lead with digital printing capabilities enabling 10,000-unit campaign economics for organic food startups. For Investors and Strategic Acquirers: Specialized vacuum deposition equipment operators with atomic layer deposition capabilities represent the priority acquisition archetype, given technician scarcity and coating pilot line concentration in the Lyon-Grenoble and Düsseldorf-Cologne clusters. Long-term viability hinges on substrate reformulation timing ahead of 2030 EU compliance thresholds. Watch for inflection when REWE and EDEKA advance PFAS-free deadlines beyond current 2025 commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Substrate Certification | TÜV Austria and BPI certifications command 15-25% price premiums in German retail channels. |
| Backward Integration into Resin Compounding | Captive polyethylene supply insulates converters from ethylene feedstock volatility. |
| Digital Printing Platform Deployment | Plateless production collapses minimum order quantities for seasonal promotional campaigns. |
| High-Barrier Coating Pilot Line Expansion | Aluminum oxide deposition capacity addresses retort-compatible baby food demand. |
| Direct-to-Subscription Format Development | Resealable fitment customization bypasses Aldi and Lidl stockout penalty structures. |
Research Methodology
Desk research of EU regulatory filings, customs trade data, and flexible packaging industry association reports preceded structured interviews with converter operations directors, retail category buyers, barrier coating technicians, and compostable film certification auditors. Primary fieldwork across the Rotterdam-Antwerp corridor, Chicago-Minneapolis hub, and Mumbai-Pune industrial zone was cross-checked against secondary validation from SEC 10-K disclosures and BIS polymer specifications. Bottom-up capacity assessments and top-down demand segmentation were triangulated to reconcile volume estimates.
Assumptions regarding EU Packaging and Packaging Waste Regulation enforcement timelines, ethylene feedstock price bands, and retailer PFAS elimination deadlines were held fixed across baseline scenarios while varying subscription channel growth rates and chemical recycling capacity buildout in sensitivity cases. Segmentation dimensions modeled include substrate chemistry tier, closure mechanism type, application category, and end-user channel structure. CAGRs were derived from regression analysis of historical volume trajectories against regulatory milestone timing and petrochemical input cost indices.
Stress conditions across ethylene price volatility, aluminum foil supply disruptions, and EPR fee modulation schemes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and could revise if REACH chemical restrictions accelerate or if municipal mechanical recycling infrastructure expands unexpectedly. Cross-checking against flexible packaging trade association capacity surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Flat Bottom Pouch Market
Pouch
Clear Pouches Market
Pouch
Pouch Equipment Market
Pouch
Pouch Dispensing Fitment Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Stand Up Paper Pouches Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
North America Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
Feed Pouches Market
Pouch
Slider Pouches Market
Pouch
Stick Pouches Packaging Market
Pouch
Liquid Pouch Market