
 Pillow Pouch Packaging Market | 2026-2036
Pillow Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pillow Pouch Packaging Market Analytics
Capital-intensity divergence between large-scale film extruders and regional converters is rotating competitive dynamics across the pillow pouch supply base. Amcor leverages integrated resin-to-pouch manufacturing across multiple continents to sustain margin stability. Mondi Group anchors its position through fiber-based barrier innovations that compete with conventional multi-layer plastics. ProAmpac differentiates via specialized high-barrier metallized structures for oxygen-sensitive food applications.
Pillow pouch packaging refers to flexible, sealed containers formed from flat or tubular film webs, typically constructed from polyethylene, BOPP, or metallized laminates with thicknesses ranging from 60 to 150 microns, designed for horizontal or vertical form-fill-seal operations that protect contents from moisture, oxygen, and light. Stand-up pouches with press-to-close zippers command premium positioning in the food and beverages end-use segment, where shelf differentiation and resealability justify higher unit economics. Flat pouches in heat-seal configurations occupy mature volume pools in homecare and single-serve pharmaceutical sachets, while gusseted formats in metallized film are gaining traction in premium coffee and specialty snack channels.
FDA food contact regulations in the United States, EU REACH compliance for adhesive and ink constituents, and China's GB standards for plastic food packaging collectively shape material selection, migration testing protocols, and market access requirements across major production hubs. ECHA's evolving restrictions on per- and polyfluoroalkyl substances are forcing laminate suppliers to reformulate barrier coatings without sacrificing shelf-life performance. Stakeholders must monitor regulatory divergence between jurisdictions while accelerating mono-material recyclable structures that satisfy both performance specifications and emerging extended producer responsibility frameworks.
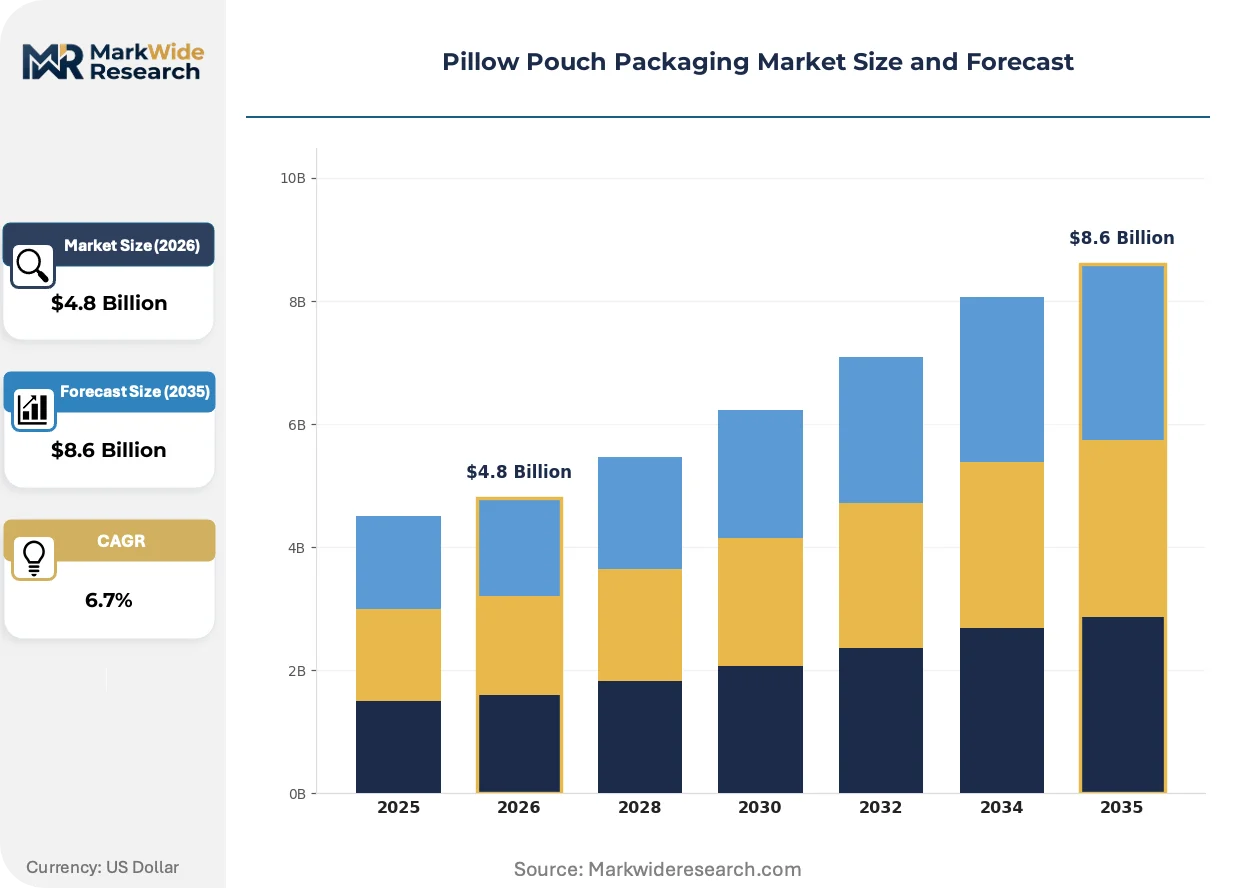
Market Dynamics
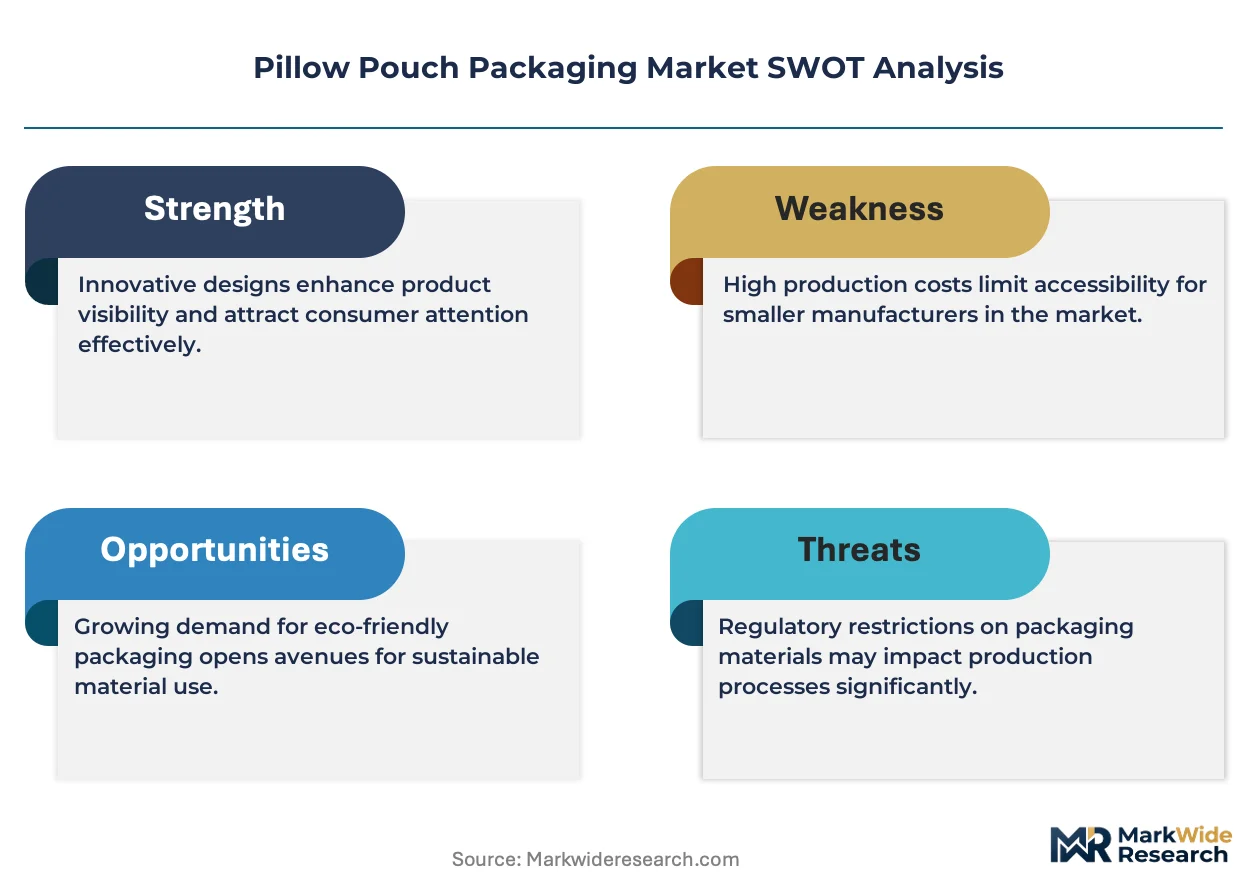
The EU Packaging and Packaging Waste Regulation is forcing laminate suppliers to eliminate multi-layer structures and deploy mono-material alternatives without sacrificing barrier performance, compressing converter margins while opening positions for chemistry specialists.
Growth Catalysts
- EU PPWR Recyclability Mandates:The regulation's 2030 targets for flexible packaging recyclability are accelerating investment in polyethylene-based mono-material films across German and French food processing operations.
- Stand-up Pouch Conversion:Coffee roasters and premium snack brands are replacing rigid cans and glass jars with metallized gusseted pouches featuring press-to-close zippers for shelf differentiation.
- Ready-to-Eat Meal Expansion:Shelf-stable protein bowls and ethnic cuisine kits are driving demand for high-barrier retortable pillow pouches in North American and Asian retail channels.
Market Restraints
- Ethylene Feedstock Volatility:Polyethylene resin prices fluctuate with crude oil and natural gas liquid markets, squeezing film extruder margins and complicating long-term contract pricing.
- Barrier Coating Reformulation Costs:ECHA restrictions on per- and polyfluoroalkyl substances are forcing adhesive and coating suppliers to validate alternative chemistries through extensive migration testing.
- Aluminum Foil Substitution Pressure:Metallized polymer films are displacing conventional aluminum foil laminates in oxygen-sensitive applications, threatening legacy foil converter volumes.
Strategic Opportunities
- Indian Processed Food Penetration:FSSAI compliance requirements and organized retail expansion are creating entry points for pre-qualified international pouch suppliers in Mumbai and Delhi NCR markets.
- Pharmaceutical Sachet Automation:Unit-dose oral solid dosage packaging for emerging market generics is driving demand for ultra-high-speed form-fill-seal lines with vision inspection integration.
- Extended Producer Responsibility Credits:Germany's Verpackungsgesetz and France's AGEC law are creating financial incentives for brands adopting mono-material recyclable structures with established sorting and reprocessing pathways.
Industry Challenges
- Migration Testing Bottlenecks:FDA and EU 10/2011 compliance for novel adhesive systems requires 6-18 month validation cycles, delaying product launches and freezing formulation innovation.
- Legacy Equipment Retrofit Costs:Converting horizontal form-fill-seal lines from multi-ply to mono-material sealing parameters demands capital expenditure in heating element and jaw design modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pillow Pouch Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Gusseted Pouches Material: polyethylene, BOPP, Metallized Film, Nylon End User: Food & Beverages, Personal Care, Pharmaceuticals, Homecare Closure Type: Heat Seal, Zipper, Tear Notch, Press-to-Close |
| Companies Covered | Amcor, Mondi Group, Berry Global, Sealed Air, Coveris, ProAmpac, Huhtamaki, Glenroy, Winpak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pillow Pouch Packaging Market Evolving Landscape
Barrier coating chemistry and sealing technology are converging to enable mono-material polyethylene structures that match multi-layer performance, while digital printing and smart packaging integration are rewriting brand-retailer relationships.
Water-based and solventless adhesive systems for high-barrier metallized laminates are fragmenting the incumbent solvent-borne polyurethane market. European coffee and pet food brands are piloting these structures at commercial scale. The shift is fragmenting traditional adhesive supplier relationships and compressing the addressable market for conventional solvent-based systems.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating oil-and-grease-resistant coatings from food contact applications. Laminate suppliers must validate silicone dioxide or bio-based alternatives through EFSA migration protocols. Snack and bakery segments in Germany and the Netherlands are experiencing the most acute reformulation pressure.
Brand procurement teams are consolidating supplier panels and demanding recycled content certificates under EU Green Deal sourcing guidelines. Major European retailers are replacing fragmented regional converter relationships with preferred supplier agreements tied to verified post-consumer recycled polyethylene inclusion rates. This concentration is most visible in German private-label snack and frozen food categories.
Pillow Pouch Packaging Market Segmentation
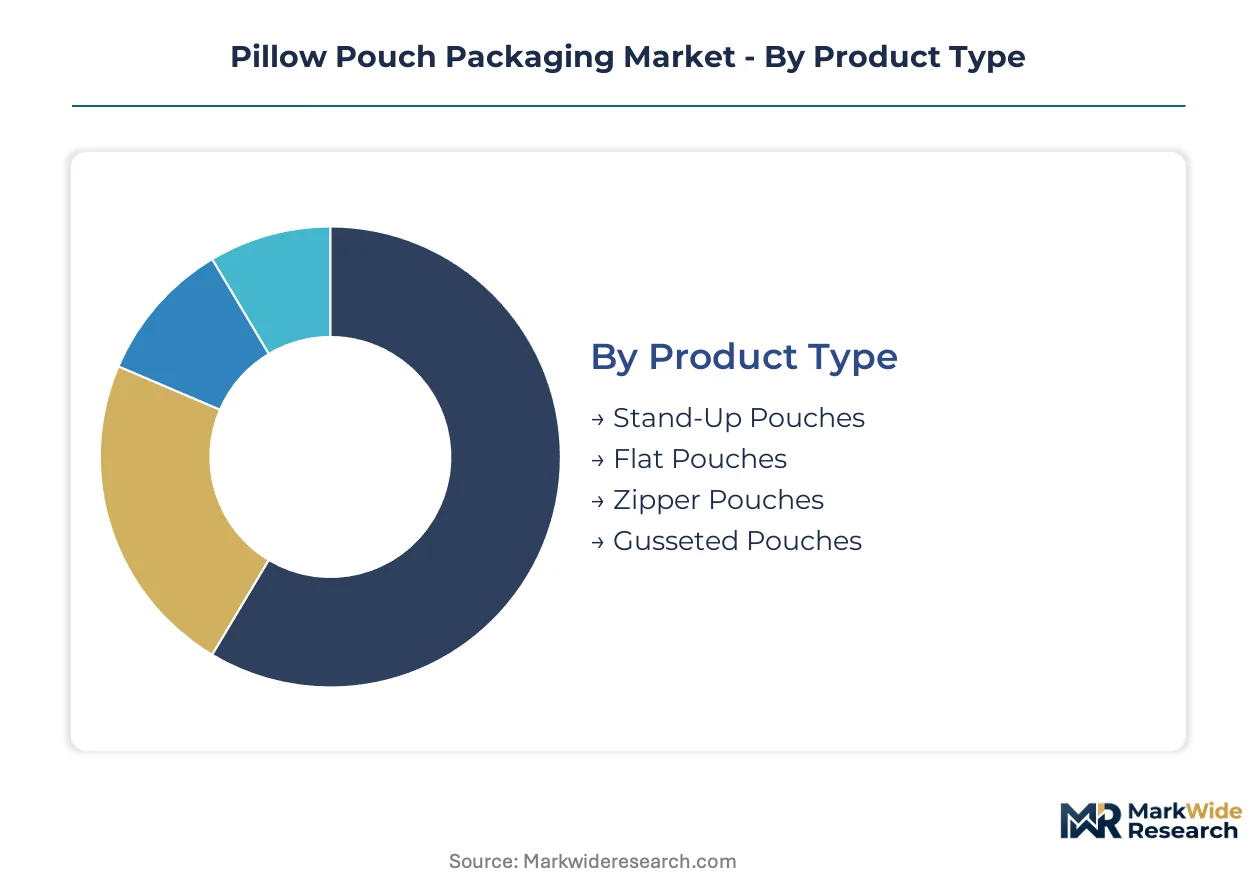
Pillow pouch packaging segments reflect divergent technical requirements across food preservation, shelf differentiation, and automation compatibility. Material selection and closure mechanics determine regional manufacturing footprints and export viability.
Product Type:
German and French food processors dominate demand for premium formats, while Asian converters supply high-volume flat pouch exports to emerging markets.
- Stand-Up Pouches:Self-supporting structures with bottom gussets enable vertical shelf display. Coffee roasters in Italy and premium snack brands in Germany are converting from rigid containers to metallized stand-up formats with press-to-close zippers.
- Flat Pouches:Two-dimensional sealed envelopes in 60-100 micron polyethylene or BOPP laminates. Single-serve pharmaceutical sachets in India and homecare detergent pods in China represent mature volume pools with established form-fill-seal automation.
- Zipper Pouches:Integral resealable closures extending shelf life after opening. Demand concentrates in North American retail channels for shelf-stable snacks.
- Gusseted Pouches:Side or bottom folded expansions increasing volumetric capacity. Specialty coffee channels in the Netherlands and Belgium are adopting these for premium positioning.
Flat pouches command the established base. The steepest expansion runs through stand-up configurations.
Material:
Cost tiers separate commodity polyethylene from engineered barrier laminates, with metallized films occupying the premium position.
- Polyethylene:Mono-material PE films are gaining share as EU PPWR recyclability mandates eliminate multi-layer alternatives. German private-label retailers are specifying post-consumer recycled content rates.
- BOPP:Biaxially oriented polypropylene delivers clarity and moisture resistance at mid-tier pricing. Indian processed food penetration is expanding BOPP demand for spice and snack packaging.
- Metallized Film:Vacuum-deposited aluminum layers on polymer substrates provide oxygen and light barriers. Premium coffee and pet food brands in France and Germany are piloting these at commercial scale.
- Nylon:Polyamide layers supply puncture resistance and thermoformability. Retortable meal applications in Japan and South Korea utilize nylon coextrusions for high-temperature processing.
Polyethylene structures anchor volume production. Metallized films are climbing the fastest as barrier requirements tighten.
End User:
Application requirements dictate material complexity, with food contact regulations imposing the strictest migration testing protocols.
- Food & Beverages:Largest addressable segment spanning shelf-stable snacks, ready-to-eat meals, and specialty coffee. EU EFSA and US FDA compliance requirements shape laminate specifications.
- Personal Care:Single-use sachets for shampoos and conditioners in emerging markets. Mumbai and Delhi NCR organized retail expansion is creating demand for pre-qualified international suppliers.
- Pharmaceuticals:Unit-dose oral solid dosage packaging demands ultra-high barrier properties. CDSCO compliance in India and FDA validation in the US create dual regulatory pathways.
- Homecare:Detergent pods and cleaning wipes in water-soluble or standard laminates. Automation-focused procurement favors standardized pouch dimensions.
Food and beverage applications command the established base. Pharmaceutical sachets are expanding most quickly as generics manufacturing shifts to emerging markets.
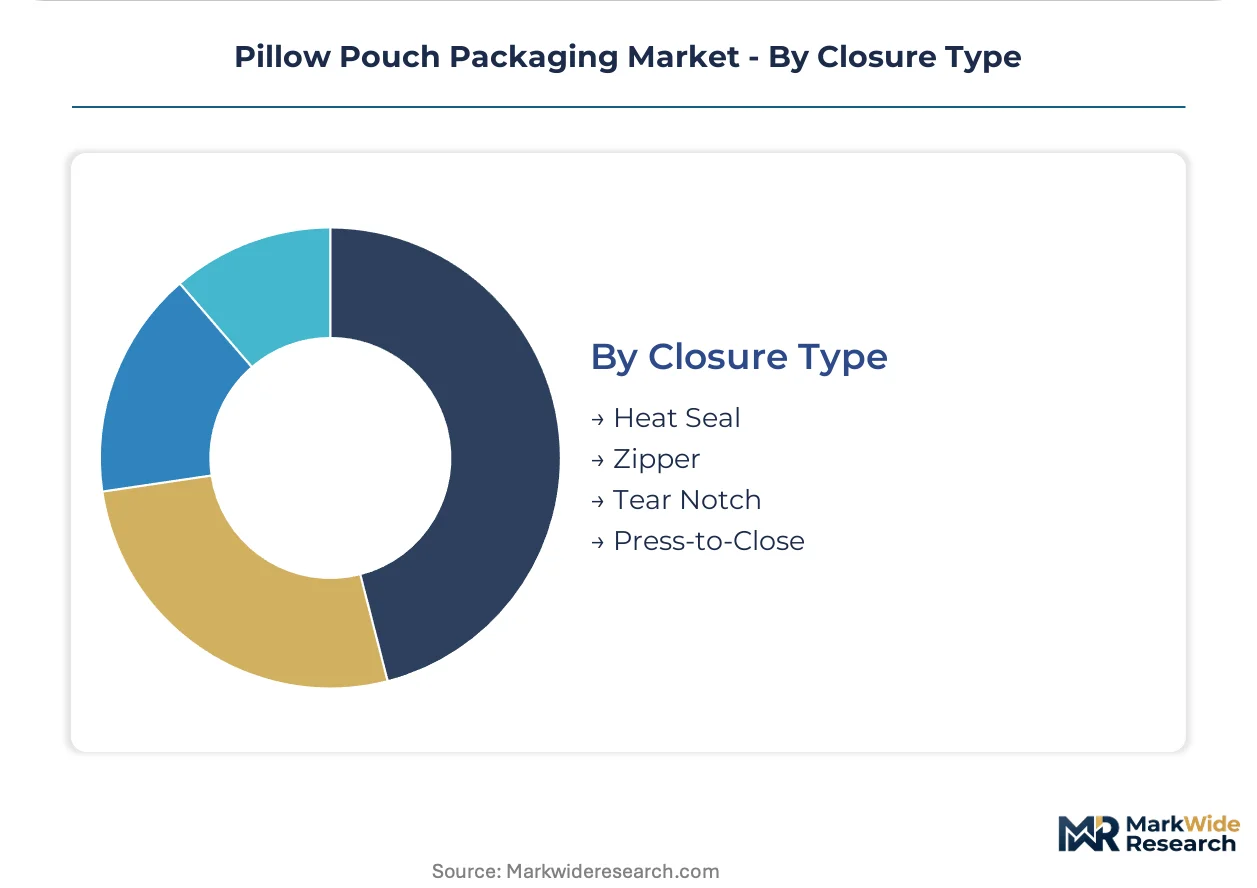
Closure Type:
Customer type separates industrial bulk packaging from consumer-facing resealable formats, with margin structures diverging accordingly.
- Heat Seal:Permanent fusion bonding via jaw sealing equipment. Lowest unit cost configuration dominates pharmaceutical and homecare bulk applications.
- Zipper:Integral interlocking profiles enabling repeated opening and closing. Premium snack brands in Germany specify these for private-label differentiation.
- Tear Notch:Pre-scored initiation points for clean opening without tools. Standard for single-serve food and personal care sachets across Asian export markets.
- Press-to-Close:Slider-integrated or pressure-activated reseal mechanisms. Coffee roasters in Italy and premium pet food brands are adopting these for shelf differentiation.
Heat seal configurations command the established base. Press-to-close systems are gaining share fastest as premium positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reshape regional positioning as German converters supply premium barrier films to French and Italian food processors, while Asian manufacturers push standardized flat pouches into emerging markets at compressed margins.
Germany
Private-label retailers and food processors drive conversion from rigid trays to lightweight flexible alternatives. The Verpackungsgesetz mandates extended producer responsibility credits for mono-material recyclable structures. The Rhine-Ruhr industrial corridor hosts integrated film extrusion and pouch converting operations serving pan-European distribution.
United States
Ready-to-eat meal brands and coffee roasters expand metallized gusseted pouch adoption for shelf differentiation. FDA food contact regulations impose migration testing protocols on novel adhesive systems. The Midwest manufacturing belt concentrates form-fill-seal equipment suppliers and regional converter networks.
China
Homecare detergent pods and single-serve personal care sachets sustain high-volume flat pouch production. GB standards for plastic food packaging govern material selection and testing requirements. The Yangtze River Delta anchors export-oriented converting capacity serving Southeast Asian and Middle Eastern markets.
India
Organized retail expansion in Mumbai and Delhi NCR creates entry points for pre-qualified international pouch suppliers. FSSAI compliance requirements shape laminate specifications for processed food penetration. Gujarat and Maharashtra industrial zones develop domestic extrusion and converting capabilities for spice and snack packaging.
France
Premium pet food and specialty coffee brands pilot high-barrier metallized structures at commercial scale. The AGEC law creates financial incentives for brands adopting mono-material recyclable formats. The Lyon-Auvergne-Rhône-Alpes cluster concentrates barrier coating chemistry specialists reformulating for ECHA restrictions.
Pillow Pouch Packaging Market Competitive Landscape
Concentration sits with integrated resin-to-pouch manufacturers and specialized barrier chemistry firms. Large-scale film extruders compete against regional converters on capital intensity and margin stability. Three archetypes dominate: integrated multinationals with captive resin supply, fiber-based barrier innovators, and metallized structure specialists. Competitive moves center on mono-material film R&D partnerships and preferred supplier agreements with consolidated retail procurement panels.
Among the integrated multinational tier, Amcor exemplifies geographic diversification across multiple continents. Mondi Group and ProAmpac occupy positions within the specialized barrier and metallized film segments respectively. These three anchors represent divergent strategic postures—resin integration, fiber-based competition with conventional plastics, and high-barrier oxygen-sensitive applications—without specific claims about individual product portfolios or financial performance.
| Leading Market Players |
|---|
| Amcor |
| Mondi Group |
| Berry Global |
| Sealed Air |
| Coveris |
| ProAmpac |
| Huhtamaki |
| Glenroy |
| Winpak |
| Others |
Value Network & Pricing Analysis
Metallized film substitution for aluminum foil laminates is redrawing procurement geography as German and French converters capture premium barrier volumes while Asian suppliers absorb commodity polyethylene pricing pressure. This displacement simultaneously concentrates high-margin chemistry expertise in the Lyon-Auvergne-Rhône-Alpes and Rhine-Ruhr corridors while fragmenting standard film extrusion across China's Yangtze River Delta export zones.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with metallized high-barrier structures commanding substantial premiums over mono-material polyethylene. Price differentiation hinges on EFSA compliance tier and post-consumer recycled content certification under Germany's Verpackungsgesetz. Cost compression in standard-grade flat pouches is intensifying because Chinese exporters are absorbing ethylene feedstock volatility to maintain volume share. Private-label retailers at Aldi and Lidl specifications demonstrate highest price sensitivity, while premium coffee roasters exhibit lowest elasticity due to shelf-differentiation requirements.
Supply Chain Analysis
Strategic stockpiling of polyethylene resin dominates converter inventory strategy in Germany and France, whereas Chinese manufacturers maintain just-in-time raw material turnover for export flexibility. Raw material sourcing draws from Saudi Arabian and Qatari ethylene supply, South Korean BOPP film, and domestic Chinese metallized substrate production. Single-source vulnerability concentrates in European adhesive chemistry suppliers facing ECHA reformulation mandates. Distribution runs through pan-European logistics hubs serving private-label retail consolidation, with direct mill relationships dominating Asian export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized barrier coating formulation capabilities have become the constraining asset in this market, with fewer than a dozen suppliers globally qualified to validate mono-material alternatives under EU PPWR migration protocols. This scarcity elevates chemistry R&D partnerships above commodity capacity expansion as the decisive competitive variable.
For Market Incumbents: Shield margin stability by securing captive polyethylene extrusion capacity in the Rhine-Ruhr corridor before resin volatility compresses converter economics further. Prioritize EFSA pre-validation partnerships with Lyon-based adhesive specialists to accelerate mono-material barrier coating deployment ahead of 2030 recyclability mandates. Lock in preferred supplier status with consolidated German retail procurement panels that are replacing fragmented regional converter relationships. For New Entrants and Emerging Players: Anchor in Indian organized retail expansion across Mumbai and Delhi NCR, where FSSAI compliance requirements create qualification barriers that favor pre-certified international suppliers over domestic converters. Target pharmaceutical sachet automation for emerging market generics, where CDSCO validation pathways and ultra-high-speed form-fill-seal integration demands exceed local technical capacity. Lead with metallized film barrier expertise rather than commodity polyethylene to escape Chinese export pricing compression. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors chemistry-specialist acquisitions over commodity film assets. Long-term viability over the next decade rests on barrier coating IP and established migration testing relationships rather than extrusion scale. Watch for ECHA publication of finalized PFAS restriction lists as the inflection signal that will trigger urgent reformulation demand and consolidate supplier panels around qualified alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film R&D Partnership | EU PPWR mandates force elimination of multi-layer structures by 2030 recyclability deadlines. |
| Backward Integration into Resin Extrusion | Ethylene feedstock volatility threatens converter margins without captive polyethylene supply. |
| EFSA Pre-Validation Investment | Migration testing bottlenecks delay product launches for novel adhesive coating formulations. |
| Preferred Supplier Agreement with Retail Consolidation | German private-label procurement panels are replacing fragmented regional converter relationships. |
| Metallized Barrier Capacity Expansion | Premium coffee and pet food brands in France and Germany pilot high-oxygen-barrier structures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from packaging multinationals, and EU regulatory gazettes. Primary interviews engaged film extrusion plant managers, retail category buyers at German and French private-label chains, adhesive R&D directors, and food processor packaging engineers. Secondary validation drew from ECHA restriction proposals, EFSA migration testing protocols, and FSSAI compliance circulars. Bottom-up capacity estimates triangulated against top-down demand modeling across end-use segments.
Segmentation dimensions modeled include product format hierarchy, material chemistry tier, closure mechanism complexity, and end-use regulatory intensity. Volume and value trajectories across the projection horizon reflect installed form-fill-seal equipment capacity, brand conversion timelines from rigid to flexible formats, and regional recyclability infrastructure maturity. CAGRs were derived from elasticity-adjusted demand curves and substitution rate assumptions for metallized versus aluminum foil barriers.
Decision-makers should treat outputs as directional under sustained EU PPWR implementation and stable ethylene feedstock pricing; material deviation would warrant model refresh. Revision becomes warranted when ECHA PFAS restriction scope crosses thresholds that invalidate current barrier coating formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Colombia Pouch Packaging Market
Pouch
Twin Pouch Packaging Market
Pouch
Foil Pouch Packaging Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Child Resistant Pouches Market
Pouch
Canada Pouch Packaging Market
Pouch
Portion Control Packs Market
Pouch
United States Retort Pouches Market
Pouch
China Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Japan Pouch Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Flat Bottom Pouch Market