
 Acute Migraine Treatment Market | 2026-2036
Acute Migraine Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Migraine Treatment Market Outlook
Small-molecule CGRP receptor antagonists are hardening their position against traditional triptans in acute migraine care. Eli Lilly and Company leverages its manufacturing scale to supply oral gepants across North American hospital networks. Pfizer Inc competes through sustained investment in nasal spray delivery platforms that target faster onset times. AbbVie anchors its portfolio with dual-market exposure across both preventive and acute migraine segments.
Acute migraine treatment encompasses pharmacological interventions designed to abort or substantially reduce headache intensity, typically targeting serotonin 5-HT1B/1D receptors or calcitonin gene-related peptide pathways, with onset-of-action parameters under two hours serving as the critical functional benchmark for clinical acceptance. The primary commercial purpose centers on reducing emergency department utilization while restoring patient functional capacity within a single dosing episode. Triptans retain the largest revenue pool among product types despite erosion at the premium tier, while injectable CGRP antagonists represent the fastest-expanding delivery mode as hospitals prioritize reliable bioavailability over patient convenience. Home care channels are gaining share among end users as telehealth protocols expand prescription authority for non-narcotic acute therapies.
The FDA's breakthrough therapy designation and EMA's priority medicines scheme are compressing development timelines for novel acute migraine mechanisms, while the FDA's Risk Evaluation and Mitigation Strategy requirements for certain ergot derivatives constrain legacy product distribution. These regulatory frameworks create asymmetric access conditions where newer molecular entities capture hospital formulary slots faster than older compounds can defend retail pharmacy positioning. Stakeholders must monitor how payer step-therapy protocols evolve in response to accumulating real-world evidence on gepant versus triptan outcomes.
Market Dynamics
The acute migraine treatment market pivots on FDA breakthrough therapy designations compressing development timelines, while hospital formulary committees prioritize injectable CGRP antagonists with proven bioavailability over oral alternatives with variable absorption profiles.
Growth Catalysts
- Breakthrough Therapy Pathways:The FDA's accelerated approval mechanisms truncate clinical trial phases for novel CGRP-targeting mechanisms, enabling faster hospital formulary adoption compared to standard NDA routes.
- Telehealth Prescription Authority:Expanded remote diagnostic protocols in the United States authorize specialist headache centers to prescribe non-narcotic acute therapies without in-person visits, widening patient access windows.
- Hospital Injectable Preference:Neurology departments in tertiary care settings increasingly stock subcutaneous CGRP receptor antagonists to guarantee consistent plasma levels during severe migraine episodes.
Market Restraints
- REMS Constraints on Ergot Derivatives:The FDA's Risk Evaluation and Mitigation Strategy requirements impose distribution restrictions on dihydroergotamine, limiting retail pharmacy stocking and forcing patients toward hospital infusion centers.
- Specialist Concentration in Urban Clusters:Board-certified headache specialists concentrate in metropolitan medical corridors, leaving rural and exurban populations dependent on general neurology practices with limited acute therapy familiarity.
- Step-Therapy Payer Protocols:Commercial insurers mandate triptan failure documentation before authorizing gepant reimbursement, creating administrative friction that delays access to premium acute interventions.
Strategic Opportunities
- Home Care Channel Expansion:Self-administered nasal spray platforms targeting faster onset kinetics are capturing share from clinic-based injections as patients prioritize convenience without sacrificing speed.
- Dual-Indication Portfolio Positioning:Developers with molecules effective in both preventive and acute migraine segments can leverage single-prescription loyalty programs to capture lifetime patient value across the full treatment continuum.
- Real-World Evidence Generation:Payer formulary committees increasingly weight head-to-head gepant versus triptan outcome data from integrated health system registries when designing prior authorization criteria.
Industry Challenges
- Headache Specialist Training Bottlenecks:Fellowship programs produce fewer than 150 new headache medicine specialists annually in the United States, constraining prescriber capacity for complex acute therapy selection.
- Formulary Integration Complexity:Hospital pharmacy and therapeutics committees require extensive pharmacoeconomic modeling to justify premium CGRP antagonist stocking against generic triptan availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Migraine Treatment Market |
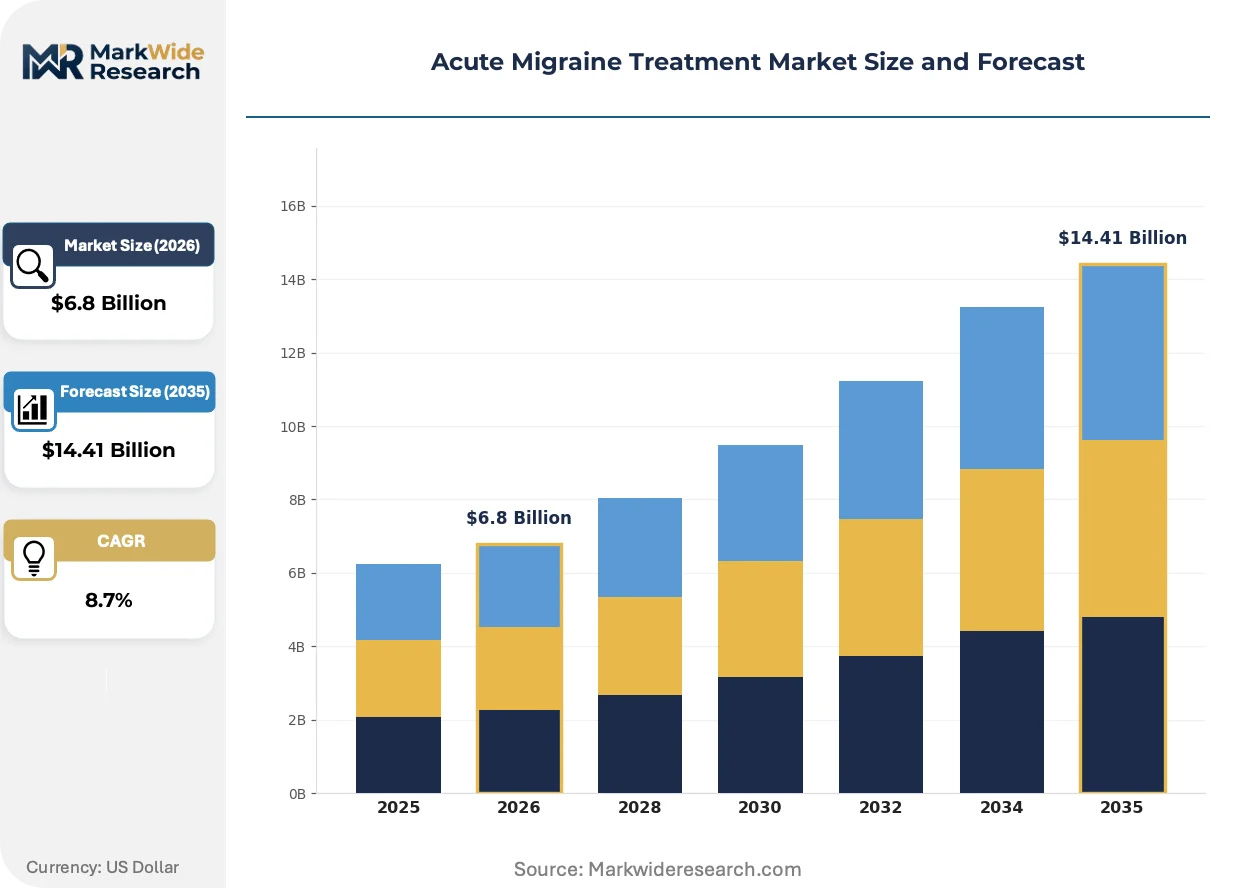
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triptans, NSAIDs, Ergots, Anti-nausea medications Delivery Mode: Pills, Injections, Nasal sprays, Transdermal patches End User: Hospitals, Clinics, Home care, Pharmacies Therapy Area: Neurology, Pain management, Emergency medicine, Acute care |
| Companies Covered | Teva Pharmaceutical, Hoffmann-La Roche Ltd, Johnson and Johnson, Amgen, Pfizer Inc, Eli Lilly and Company, AbbVie, Novartis AG, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Migraine Treatment Market Strategic Shifts
Injectable CGRP receptor antagonists are converging with digital patient monitoring platforms to reshape acute migraine care delivery, while regulatory acceleration mechanisms and shifting site-of-care preferences compress traditional treatment pathways.
Subcutaneous CGRP receptor antagonist delivery systems are converging with Bluetooth-enabled injection devices that log dosing timestamps and symptom severity scores. Hospital neurology departments pilot these connected platforms to build real-world efficacy datasets. The technology is converging with payer demands for outcome documentation, creating competitive separation between device-enabled and conventional injection offerings.
The FDA's breakthrough therapy designation pathway truncates Phase II-to-approval timelines for novel acute migraine mechanisms by permitting surrogate endpoint acceptance. This regulatory compression favors developers with robust biomarker strategies over those dependent on traditional pain-scale endpoints. Hospital formulary committees respond by establishing expedited review tracks for designated therapies, accelerating uptake in acute care settings.
Specialist headache centers increasingly unbundle acute migraine intervention from longitudinal preventive care, creating discrete reimbursement codes for single-episode management. Telehealth platforms capture these episodes through asynchronous symptom reporting and e-prescribing protocols. The United States exhibits the most pronounced channel fragmentation, where commercial insurers now distinguish between virtual acute consults and in-person preventive evaluations in benefit design.
Acute Migraine Treatment Market Segmentation
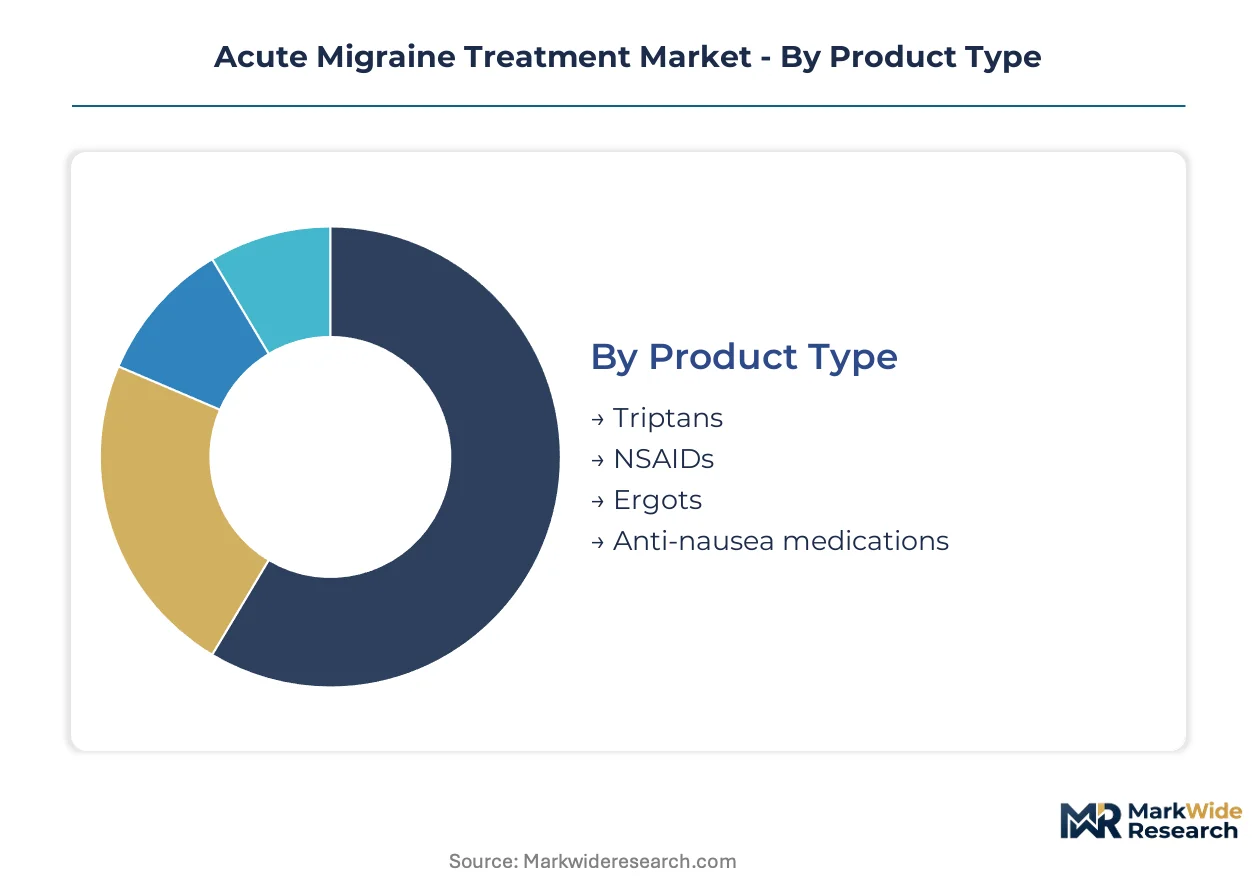
Acute migraine treatment segmentation reflects divergent clinical priorities across emergency stabilization versus outpatient self-management. Product formulation, delivery mechanism, and site of care each create distinct competitive battlegrounds with unique margin profiles and regulatory exposure.
Product Type:
Standardization dominates at the mass-market tier while premium molecular innovation commands specialist channels.
- Triptans:Serotonin 5-HT1B/1D receptor agonists available in oral, nasal, and injectable formulations. Demand concentrates in retail pharmacy networks where generic sumatriptan dominates prescription volume; step-therapy protocols require triptan trial before gepant authorization.
- NSAIDs:Non-steroidal anti-inflammatory drugs including ibuprofen, naproxen, and aspirin combinations. These agents capture first-line acute episodes in primary care settings where patients lack specialist diagnosis; OTC availability constrains prescription revenue.
- Ergots:Dihydroergotamine and ergotamine derivatives with potent vasoconstrictive properties. FDA REMS requirements limit distribution to certified infusion centers and hospital pharmacies.
- Anti-nausea medications:Metoclopramide, prochlorperazine, and ondansetron administered as adjunctive therapy. Emergency departments combine these with primary abortive agents to address migraine-associated gastroparesis.
Leading the category by volume: Triptans. Growing fastest: Anti-nausea medications as combination protocols expand.
Delivery Mode:
Speed-to-onset separates premium positioning from commodity substitution.
- Pills:Oral tablets and capsules representing the most mature administration route. Patient preference for discretion and portability sustains dominance in home care channels despite variable gastric absorption during migraine episodes.
- Injections:Subcutaneous and intravenous delivery systems guaranteeing bioavailability. Hospital neurology departments prioritize subcutaneous CGRP antagonists for severe attacks; Bluetooth-enabled devices now capture dosing data for payer documentation.
- Nasal sprays:Intranasal absorption bypassing gastrointestinal delays. Faster onset kinetics capture patients seeking clinic-equivalent speed without facility visits; Pfizer's sustained investment reflects strategic priority.
- Transdermal patches:Dermal absorption systems offering sustained release. Limited commercial penetration due to unpredictable absorption rates and skin irritation concerns.
Injections command the highest revenue per dose. Nasal sprays gain share fastest as telehealth prescribing expands.
End User:
Site-of-care migration is redistributing prescribing authority across institutional and ambulatory settings.
- Hospitals:Tertiary care centers with 24-hour neurology coverage and infusion capabilities. Injectable CGRP antagonists stock pharmacy formularies; emergency departments track reduction in migraine-related admissions as quality metric.
- Clinics:Outpatient specialist headache centers and general neurology practices. Board-certified headache specialists concentrate in metropolitan corridors; fellowship training bottlenecks constrain prescriber expansion.
- Home care:Self-administered therapy with remote monitoring support. Telehealth protocols now authorize asynchronous prescribing for non-narcotic acute agents; patients prioritize convenience without sacrificing efficacy.
- Pharmacies:Retail dispensing with pharmacist consultation. Generic triptan availability and OTC NSAID access define competitive dynamics; REMS constraints block ergot distribution.
Hospitals lead by revenue per patient. Home care channels expand most quickly as digital health infrastructure matures.
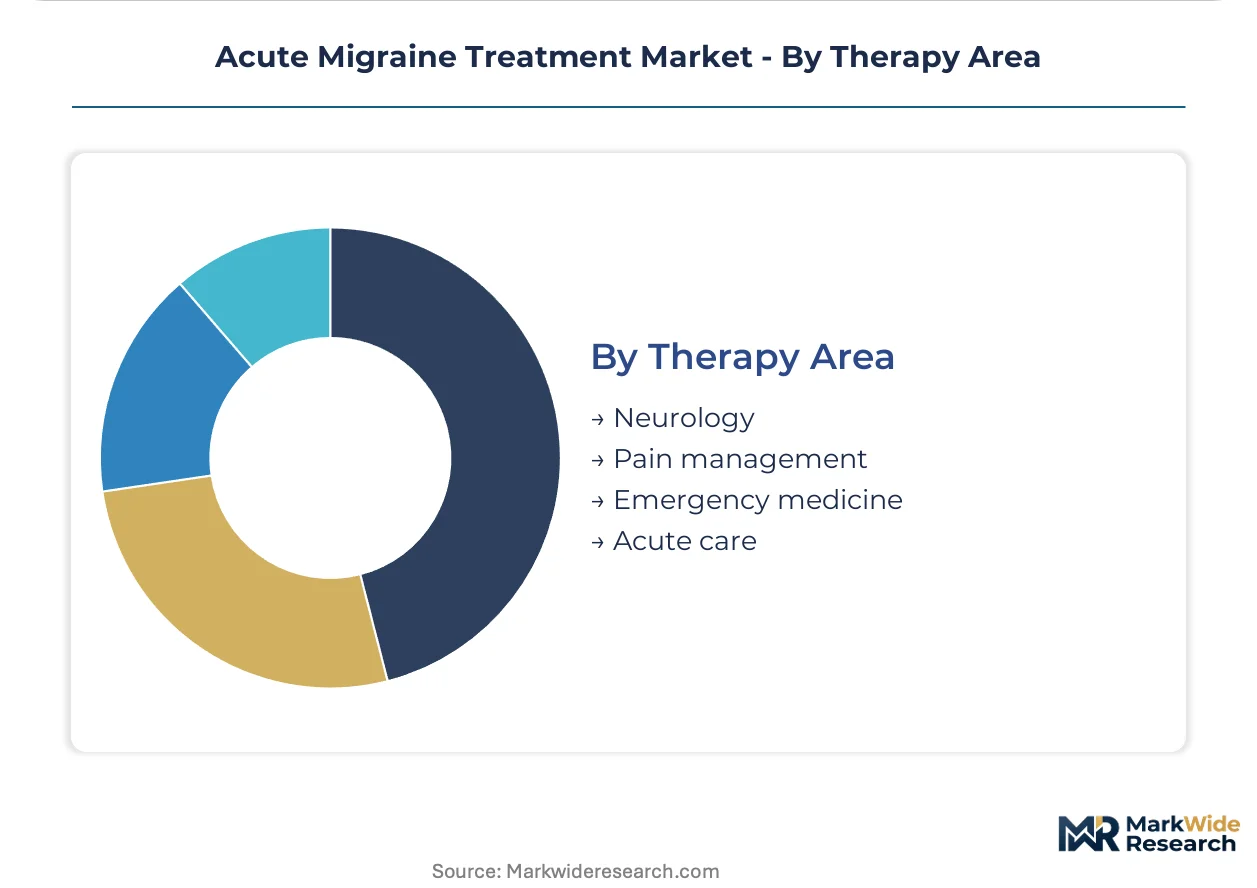
Therapy Area:
Specialist depth versus generalist breadth determines formulary access and reimbursement rates.
- Neurology:Dedicated headache medicine and general neurology practices with diagnostic expertise. CGRP-targeting mechanisms achieve fastest formulary adoption here; real-world evidence generation concentrates in academic medical center registries.
- Pain management:Multidisciplinary clinics addressing refractory headache syndromes. Opioid-sparing protocols drive non-narcotic acute therapy preference; prior authorization requirements vary by payer.
- Emergency medicine:Hospital-based acute stabilization protocols. Dihydroergotamine infusion and anti-emetic combinations standard; admission avoidance metrics influence therapeutic selection.
- Acute care:Urgent care centers and same-day clinics with limited neurology backup. Diagnostic uncertainty favors NSAID-first approaches; referral networks to specialist centers remain underdeveloped in exurban regions.
Neurology commands premium pricing. Emergency medicine shows steepest expansion trajectory as admission-avoidance incentives intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States concentrates acute migraine treatment demand through its network of specialist headache centers and favorable reimbursement frameworks for premium CGRP-targeting therapies. Hospital neurology departments and telehealth prescribing protocols drive prescription volume concentration in metropolitan medical corridors.
United States
Specialist headache centers in Boston, New York, and Chicago anchor prescription authority for injectable CGRP antagonists. FDA breakthrough therapy designations compress development timelines for novel mechanisms. The Mayo Clinic Rochester and Cleveland Clinic generate real-world evidence datasets that influence payer prior authorization criteria.
Germany
Headache medicine specialists concentrate in university hospitals across Berlin, Munich, and Hamburg. EMA priority medicines scheme accelerates market access for gepant-class therapies. Baden-Württemberg's pharmaceutical cluster supports manufacturing scale for European supply of nasal spray delivery platforms.
Japan
PMDA fast-track reviews enable earlier hospital formulary adoption of subcutaneous CGRP receptor antagonists. Tokyo and Osaka metropolitan areas host the highest density of board-certified headache specialists. Kansai region medical centers pilot Bluetooth-enabled injection devices for real-world outcome documentation.
United Kingdom
NICE technology appraisals determine NHS reimbursement thresholds for acute migraine interventions. London's National Hospital for Neurology and Neurosurgery anchors specialist referral networks. Greater Manchester and Birmingham clinical commissioning groups experiment with telehealth prescribing protocols for non-narcotic acute therapies.
Canada
Health Canada priority review pathways align with FDA timelines for CGRP-targeting mechanisms. Ontario and Quebec concentrate headache medicine fellowship programs and specialist density. Toronto's University Health Network generates pharmacoeconomic models that inform hospital pharmacy and therapeutics committee decisions.
Acute Migraine Treatment Market Competitive Environment
Portfolio diversification dominates the current landscape as developers seek dual-indication exposure across preventive and acute migraine segments. The market structure consolidates around large-cap pharmaceutical groups with manufacturing scale and established hospital formulary relationships. Three archetypes define competitive positioning: diversified biopharmaceutical conglomerates with neurology franchises, mid-cap specialists with single-molecule focus, and generic manufacturers capturing triptan volume at the commoditized tier. M&A activity and strategic partnerships represent the dominant competitive moves, with technology licensing agreements for novel delivery platforms gaining frequency.
Within the diversified biopharmaceutical tier, Eli Lilly and Company, Pfizer Inc, and AbbVie exemplify scale-driven positioning across the acute migraine treatment continuum. Eli Lilly anchors manufacturing supply for oral gepants across North American hospital networks. Pfizer occupies a position centered on nasal spray delivery innovation. AbbVie represents dual-market exposure archetype with portfolio spanning both preventive and acute therapeutic categories.
| Leading Market Players |
|---|
| Teva Pharmaceutical |
| Hoffmann-La Roche Ltd |
| Johnson and Johnson |
| Amgen |
| Pfizer Inc |
| Eli Lilly and Company |
| AbbVie |
| Novartis AG |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Bluetooth-enabled injection devices with real-time dosing capture are compressing per-unit manufacturing costs while concentrating component sourcing among FDA-registered medical device suppliers in the United States and Germany. This technology shift simultaneously reduces quality-control overhead for pharmaceutical manufacturers and tightens supplier qualification requirements, creating asymmetric pricing power for device-integrated therapy platforms against conventional injection alternatives.
Pricing Analysis
Volume concentrates in generic oral triptans where pharmacy benefit managers extract maximum rebate capture, while margins accrue to subcutaneous CGRP antagonists stocked by hospital formularies. Price differentiation hinges on bioavailability certification and FDA breakthrough therapy designation tier. Cost compression in the retail pharmacy channel intensifies as step-therapy protocols delay gepant access. General neurology practices exhibit highest price sensitivity; tertiary headache centers prioritize efficacy over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologics require specialized cold-chain returns infrastructure that few distributors maintain, concentrating certified partners in the United States, Germany, and Switzerland. Active pharmaceutical ingredient production draws from Indian and Chinese chemical synthesis hubs, with final formulation captive to Lilly, Pfizer, and AbbVie manufacturing networks. Single-source vulnerability persists for novel CGRP receptor antagonist starting materials. Distribution runs through hospital purchasing cooperatives and specialty pharmacy channels with REMS-mandated tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute migraine treatment market functions as a cost-of-compliance story where FDA Risk Evaluation and Mitigation Strategy requirements for ergot derivatives and breakthrough therapy designation pathways for CGRP antagonists erect regulatory moats that only well-capitalized developers can surmount.
For Market Incumbents: Deploy manufacturing scale as the primary defensive lever. Expand subcutaneous CGRP antagonist production capacity in North American FDA-registered facilities to preempt supply constraints. Deepen backward integration into peptide synthesis starting materials to insulate against API price volatility from Indian and Chinese suppliers. For New Entrants and Emerging Players: Enter via nasal spray delivery platform specialization targeting telehealth prescribing protocols. White-space opportunity concentrates in home care channels where patients seek clinic-equivalent onset kinetics without facility visits. Pursue 505(b)(2) regulatory pathways leveraging existing safety data to compress development timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified biopharmaceutical conglomerates seeking dual-indication migraine exposure. Five-to-ten-year viability favors developers with both preventive and acute therapeutic assets. Monitor FDA breakthrough therapy designation grants as inflection indicators for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated review compresses Phase II-to-approval timelines for novel CGRP mechanisms. |
| Hospital Formulary Partnership | Pharmacy and therapeutics committee relationships secure preferred stocking for injectable antagonists. |
| Real-World Evidence Registry Development | Academic medical center datasets influence payer prior authorization criteria for gepant therapies. |
| Dual-Indication Portfolio Expansion | Single-molecule preventive and acute exposure captures lifetime patient value across treatment continuum. |
| Telehealth Prescription Infrastructure | Asynchronous diagnostic protocols widen patient access windows for non-narcotic acute therapies. |
Study Parameters
Independent corroboration across FDA regulatory filings, EMA submission documents, and ClinicalTrials.gov protocols underwrites the qualitative findings in this study. Primary interviews with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists combined with secondary validation from SEC 10-K disclosures, formulary databases, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates.
Comparable-period anchoring to historical triptan launch trajectories informed growth rate assumptions across the projection horizon. Segmentation modeling incorporated treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs derived from patent expiry impact analysis, generic erosion curves, and novel mechanism adoption S-curves. Forecast inputs included headache specialist fellowship graduation rates and telehealth prescribing authority expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA regulatory delay scenarios or CGRP antagonist safety signal emergence. Forecasts reflect documented assumptions regarding step-therapy protocol evolution and hospital formulary budget allocation trends. Practitioners should monitor FDA advisory committee outcomes and integrated health system real-world evidence publication schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Scabies Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Radiation Proctitis Treatment Market
Medical Treatment
Avian Flu Treatment Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Rabies Treatment Market
Medical Treatment
Vulvovaginal Candidiasis Treatment Market
Medical Treatment
Bloch-Sulzberger Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Peripheral Nerve Injuries Market