
 Dengue Fever Treatment Market | 2026-2036
Dengue Fever Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dengue Fever Treatment Market Outlook
The WHO dengue vaccine prequalification pathway is expanding access benchmarks for manufacturers serving endemic regions. Sanofi leverages its established flavivirus research infrastructure to sustain competitive positioning in vaccine development. Takeda Pharmaceutical Company Limited anchors its portfolio through differentiated live-attenuated vaccine platforms targeting pediatric and adolescent populations. Merck & Co., Inc. competes via manufacturing scale advantages that support cost-efficient supply to national immunization programs.
Dengue fever treatment encompasses pharmaceutical and biological interventions designed to manage or prevent infection by the dengue virus, including antiviral compounds that inhibit viral replication, vaccines formulated with attenuated or recombinant antigens to induce neutralizing antibodies, and supportive care products addressing thrombocytopenia and plasma leakage. Its primary purpose is reducing mortality and morbidity in endemic regions while enabling safe travel and emergency response. Vaccines command structural attention due to long development cycles and high regulatory barriers that create durable margin pools for approved products. Antivirals represent a growing segment as direct-acting compounds advance through clinical pipelines. Supportive care products occupy a stable position driven by recurrent epidemic patterns requiring immediate hospital intervention.
The US FDA, the WHO, and national regulators across endemic countries shape demand through divergent efficacy and safety standards for dengue vaccines, with some jurisdictions restricting use to seropositive populations while others pursue universal immunization frameworks. These regulatory configurations directly determine market access timelines, labeling requirements, and reimbursement pathways for manufacturers. Stakeholders must monitor evolving serostatus screening protocols and post-market surveillance mandates that will define commercial viability in high-burden geographies.
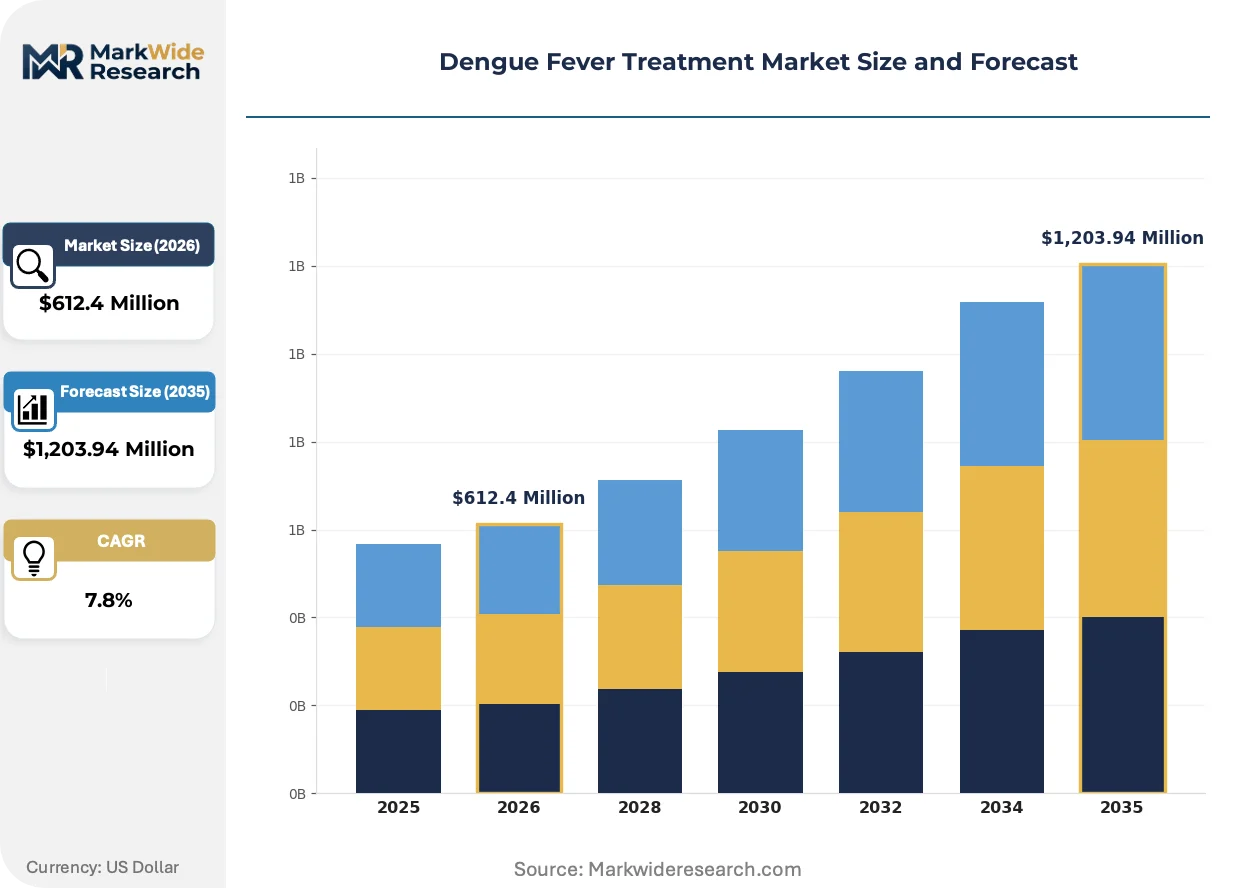
Market Dynamics
Hospital procurement of dengue therapeutics is intensifying across tropical zones as vector-borne disease burden concentrates in Southeast Asian metropolitan corridors. WHO prequalification pathways for dengue vaccines are compressing registration timelines and reshaping competitive access benchmarks for manufacturers.
Growth Catalysts
- WHO Prequalification Pathway:The WHO prequalification program accelerates market entry for vaccines in endemic regions by streamlining regulatory review and enabling Gavi procurement eligibility.
- Vector Control Integration:Municipal health departments in Brazil, Indonesia, and Thailand are bundling vaccine campaigns with larval source reduction programs, expanding addressable patient populations.
- Live-Attenuated Platform Advances:Tetravalent vaccine formulations demonstrating balanced immunogenicity against all four serotypes are gaining preference over monovalent predecessors in pediatric immunization schedules.
Market Restraints
- Serostatus-Dependent Labeling:FDA and EMA restrictions limiting first-dose administration to seropositive individuals create screening infrastructure burdens and access inequities in low-resource settings.
- Plasma-Derived Product Concentration:Intravenous immunoglobulin and platelet concentrate supply chains depend heavily on US and European blood collection networks, exposing tropical markets to cold-chain disruption risks.
- Antiviral Development Attrition:High clinical trial failure rates for direct-acting antivirals targeting NS5 polymerase have compressed private R&D investment and extended reliance on supportive care protocols.
Strategic Opportunities
- Philippines Universal Immunization Framework:The Philippine Department of Health's phased school-based vaccination program creates a template for population-wide dengue vaccine adoption in middle-income endemic countries.
- Point-of-Care Diagnostics Convergence:Integration of rapid NS1 antigen tests with mobile health platforms enables same-day serostatus verification and vaccine eligibility determination at peripheral clinics.
- Thermal-Stable Formulation Development:Lyophilized vaccine presentations eliminating frozen storage requirements unlock last-mile distribution to rural Indonesia and sub-Saharan African markets lacking cold-chain infrastructure.
Industry Challenges
- Flavivirus Serology Cross-Reactivity:Diagnostic laboratories struggle to distinguish dengue from Zika and chikungunya infections using IgM-based assays, complicating surveillance accuracy and vaccine targeting.
- Hospital Pharmacy Integration:Public sector procurement systems in Vietnam and Myanmar require multi-year tender commitments that conflict with vaccine manufacturers' preference for annual price adjustments based on epidemiological forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dengue Fever Treatment Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Vaccines, Supportive Care Products, Diagnostics Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Hospitals, Clinics, Homecare, Community Health Centers Therapy Area: Infectious Diseases, Tropical Medicine, Travel Medicine, Emergency Care |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Sanofi, Panacea Biotec Ltd., F. Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, Merck & Co., Inc., Biological E. Limited, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dengue Fever Treatment Market Strategic Shifts
RNA-based vaccine platforms and mRNA manufacturing infrastructure originally scaled for COVID-19 are now being repurposed for dengue immunization programs. This technological pivot is compressing development timelines and attracting new entrants from the infectious disease vaccine space.
Recombinant subunit vaccines incorporating envelope domain III antigens are absorbing development resources from traditional live-attenuated approaches. The US NIH and select biotech developers are prioritizing these candidates for seronegative populations excluded from current licensed products. This platform shift is enabling safer pediatric vaccination but compressing near-term revenue potential due to longer immunization schedules.
The European Medicines Agency's accelerated assessment pathway for vaccines addressing unmet medical needs in tropical diseases is compressing regulatory review timelines from 210 to 150 days. Manufacturers submitting dossiers for dengue vaccines are leveraging this mechanism alongside scientific advice procedures to align clinical endpoints with European immunization policy. Pediatric hospital networks in France and Spain are preparing implementation studies to inform national recommendation committees.
Public hospital procurement in Thailand and Malaysia is migrating from single-source annual contracts to multi-year framework agreements with performance-linked pricing. Distributors serving these institutions are consolidating logistics capabilities and investing in temperature-monitoring infrastructure to meet stricter vendor qualification standards. This procurement evolution is most visible in Bangkok and Kuala Lumpur metropolitan health systems, where centralized purchasing authorities now dominate volume allocation decisions.
Dengue Fever Treatment Market Segmentation
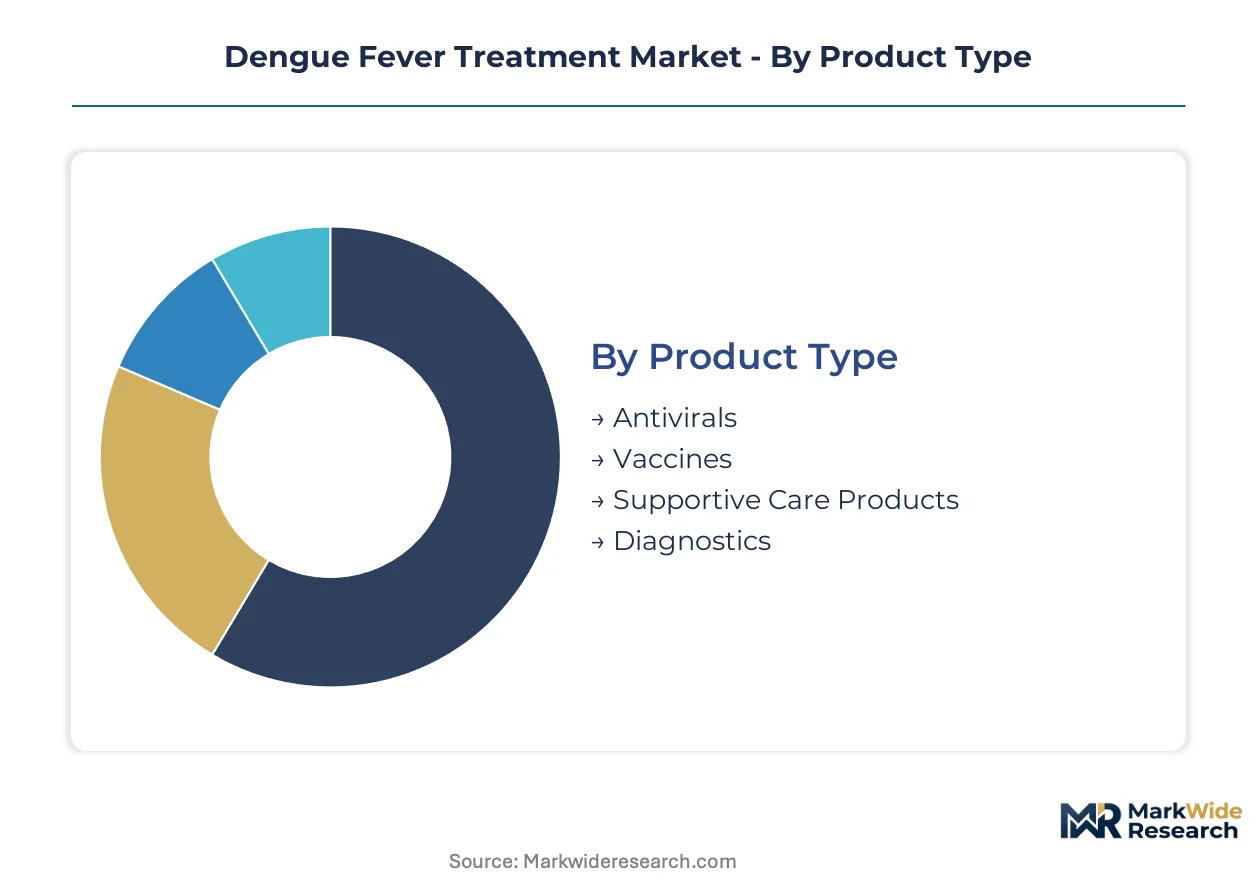
Product architecture in dengue therapeutics splits between preventive and curative modalities, with vaccine platforms commanding development investment while antivirals address unmet treatment needs. Delivery infrastructure and care settings further stratify procurement patterns across endemic regions.
Product Type:
Vaccines operate as standalone preventive systems requiring cold-chain distribution, while antivirals and supportive care products embed within hospital treatment protocols.
- Vaccines:Live-attenuated tetravalent formulations induce neutralizing antibodies against all four dengue serotypes through single-dose or multi-dose regimens. Procurement concentrates in Philippine and Thai national immunization programs where school-based delivery infrastructure exists. WHO prequalification status determines Gavi eligibility and shapes manufacturer prioritization.
- Antivirals:Direct-acting compounds targeting viral NS5 polymerase or NS3 helicase interrupt replication cycles during acute infection. Clinical pipeline attrition has compressed near-term availability, leaving supportive care as the dominant hospital intervention in Brazilian and Vietnamese tertiary centers.
- Supportive Care Products:Intravenous fluids, platelet concentrates, and analgesics manage plasma leakage and thrombocytopenia in severe dengue cases.
- Diagnostics:NS1 antigen detection and IgM/IgG serology kits enable rapid case confirmation and serostatus screening.
Volume placements concentrate in Vaccines; the faster expansion belongs to Antivirals.
Delivery Mode:
Route selection tracks disease severity and care setting, with injectable platforms dominating preventive campaigns while intravenous delivery anchors hospital-based severe case management.
- Injectable:Subcutaneous or intramuscular administration of vaccines enables mass immunization in Indonesian and Malaysian municipal health campaigns. Lyophilized presentations reducing cold-chain dependency are gaining preference for last-mile distribution to rural Philippines.
- Intravenous:Fluid resuscitation and blood product transfusion constitute standard-of-care for dengue hemorrhagic fever in Thai and Vietnamese public hospitals. Plasma-derived product supply chains remain vulnerable to US and European collection network disruptions.
- Oral:Antipyretics and hydration salts support outpatient management of uncomplicated cases.
- Topical:Insect repellents and vector control agents complement pharmaceutical interventions in community settings.
Procurement volume tilts toward Injectable; Intravenous captures the steepest expansion trajectory amid rising severe case hospitalization.
End User:
Care setting segmentation reflects disease severity distribution and infrastructure maturity across Southeast Asian health systems.
- Hospitals:Tertiary centers in Bangkok, Ho Chi Minh City, and Manila manage severe dengue with intensive care capabilities and blood banking infrastructure. Centralized procurement authorities in these metropolitan systems now dominate volume allocation through multi-year framework agreements.
- Clinics:Urban primary care facilities in Jakarta and Kuala Lumpur handle moderate cases with rapid diagnostic support.
- Community Health Centers:Peripheral facilities in rural Indonesia and Myanmar conduct initial screening and referral.
- Homecare:Self-administered hydration and fever management addresses mild infections in resource-constrained settings.
Demand aggregates in Hospitals; Community Health Centers are climbing the fastest as diagnostic convergence enables decentralized screening.
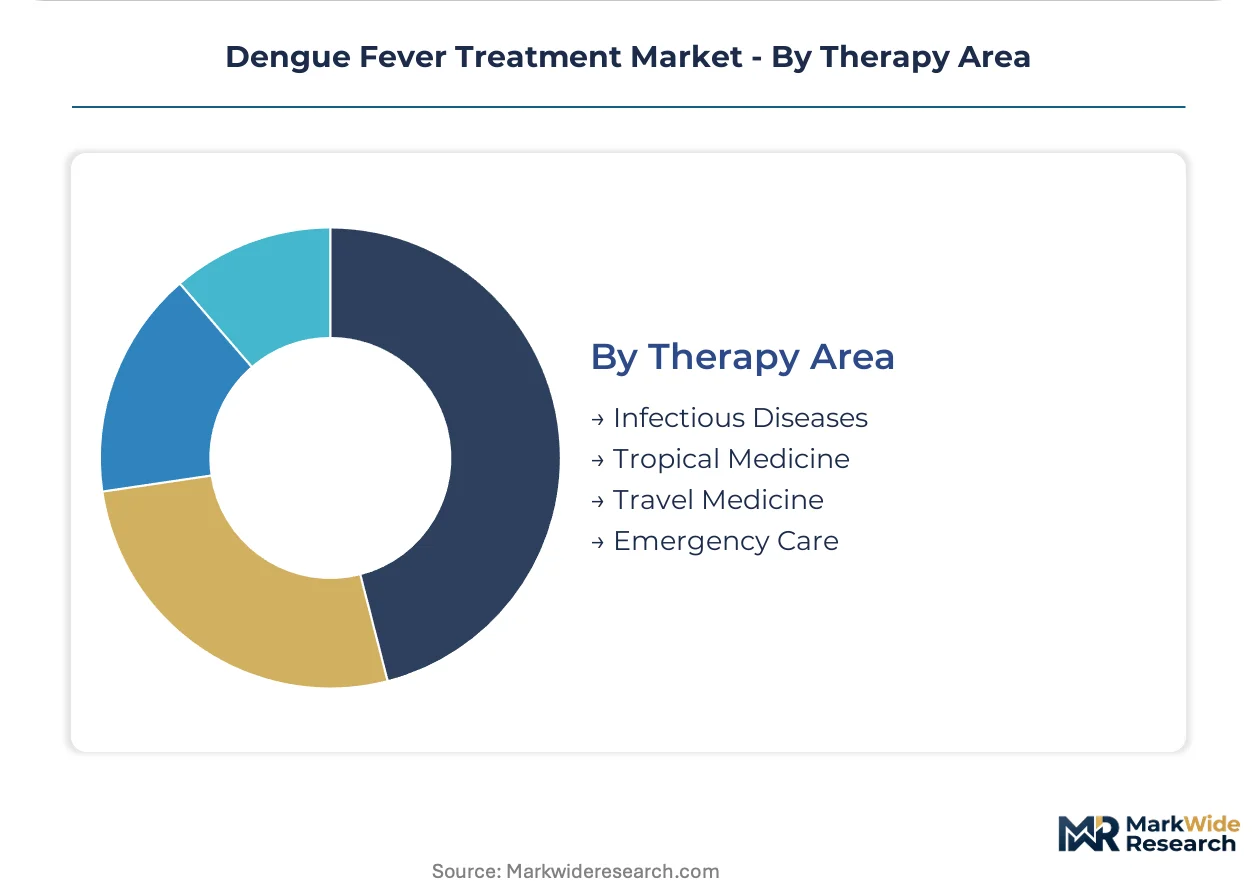
Therapy Area:
Clinical application scope spans endemic disease management, traveler protection, and emergency outbreak response with distinct regulatory and procurement pathways.
- Infectious Diseases:Pediatric and adolescent immunization schedules in endemic countries anchor routine vaccine demand. Brazilian Ministry of Health campaigns integrate dengue vaccination with yellow fever and measles programs in Amazonian municipalities.
- Tropical Medicine:Research institutions in Thailand and Vietnam conduct implementation science studies informing national guideline development.
- Travel Medicine:Pre-travel consultation clinics in Europe and North America administer vaccines to seropositive travelers visiting endemic regions.
- Emergency Care:Surge capacity protocols activate during seasonal epidemic peaks in Philippines and Indonesia.
Programmatic investment centers on Infectious Diseases; Travel Medicine is gaining share fastest as serostatus screening protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vaccine production concentrates in European and Japanese manufacturing corridors, while consumption clusters in Southeast Asian metropolitan health systems where dengue burden drives hospital procurement intensity.
Philippines
School-based immunization programs and seasonal epidemic surges anchor vaccine demand in Metro Manila and Cebu. The Department of Health's phased universal framework shapes procurement timelines for public sector tenders. Philippine General Hospital in Manila anchors severe case management protocols that inform national treatment guidelines.
Thailand
Pediatric immunization schedules and tourist corridor protection programs drive dual-track vaccine procurement in Bangkok and Chiang Mai. The Thai FDA accelerates registration reviews for WHO-prequalified products through streamlined assessment pathways. Siriraj Hospital in Bangkok concentrates tertiary care capacity and blood banking infrastructure for hemorrhagic fever management.
Brazil
Amazonian municipality campaigns and urban epidemic response protocols generate demand in São Paulo and Manaus. ANVISA maintains serostatus-dependent labeling requirements that restrict first-dose administration protocols. Butantan Institute in São Paulo anchors regional vaccine manufacturing and clinical trial infrastructure for tropical disease candidates.
Indonesia
Municipal health department bundling of vector control with immunization campaigns expands addressable populations in Jakarta and Surabaya. The national pharmaceutical regulator enforces cold-chain verification standards for lyophilized vaccine distribution. Hasan Sadikin Hospital in Bandung serves as a referral hub for severe dengue cases across West Java province.
Vietnam
Hospital pharmacy integration requirements and multi-year tender commitments structure procurement in Ho Chi Minh City and Hanoi. The Ministry of Health mandates post-market surveillance reporting for all imported biological products. Cho Ray Hospital in Ho Chi Minh City manages the highest severe dengue caseloads in the Mekong Delta corridor.
Dengue Fever Treatment Market Competitive Environment
The competitive structure tilts toward multinational pharmaceutical conglomerates with established flavivirus research infrastructure. Consolidation around vaccine platforms persists due to high regulatory barriers and lengthy development cycles that deter new entrants. Two strategic archetypes dominate: diversified pharmaceutical majors leveraging manufacturing scale, and specialized biologics developers focusing on live-attenuated formulations. Competitive moves center on WHO prequalification pursuit and thermal-stable formulation development to unlock last-mile distribution.
Within the diversified pharmaceutical tier, GlaxoSmithKline plc and Novartis AG occupy positions anchored by broad infectious disease portfolios and established tropical medicine capabilities. Sanofi represents the European vaccine development archetype with deep flavivirus research heritage. Takeda Pharmaceutical Company Limited exemplifies the Asia-Pacific biologics specialist model. Merck & Co., Inc. anchors the manufacturing scale-driven competitive position serving national immunization programs.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Sanofi |
| Panacea Biotec Ltd. |
| F. Hoffmann-La Roche Ltd. |
| Takeda Pharmaceutical Company Limited |
| Merck & Co., Inc. |
| Biological E. Limited |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Multinational pharmaceutical conglomerates with sovereign-backed manufacturing footprints in Japan and Europe anchor supply-side pricing discipline through vertically integrated vaccine production. Their captive control over live-attenuated platform development and WHO prequalification pathways insulates premium tier positioning from commodity pressure in Southeast Asian tender markets.
Pricing Analysis
Margin tightening in public sector tenders reflects multi-year framework agreements that lock manufacturers into fixed-price commitments against volatile plasma-derived input costs. Three-tier pricing structure across WHO-prequalified, nationally registered, and investigator-initiated product levels stratifies procurement in Philippine and Thai hospital systems. Cost compression in lyophilized vaccine presentations accelerates because municipal health departments in Indonesia prioritize cold-chain elimination over brand premium. National immunization programs exhibit highest price sensitivity; private travel medicine clinics demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from the Philippine Department of Health and Thai FDA mandate qualified backup suppliers for all biological products entering national immunization programs. Manufacturing concentrates in Japan, France, and Belgium for live-attenuated platforms, while plasma-derived supportive care products draw from US and European blood collection networks. Bovine serum albumin, specialized cell culture media, and pharmaceutical-grade sucrose constitute critical raw material dependencies. Single-source vulnerability in cold-chain logistics exposes tropical markets to distribution failure. Distribution runs through centralized purchasing authorities in Bangkok and Manila metropolitan health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into thermal-stable formulation development and point-of-care diagnostic convergence represents the decisive upstream race, as manufacturers who capture both vaccine production and serostatus verification infrastructure will dominate procurement decisions in decentralized Indonesian and Vietnamese markets.
For Market Incumbents: Anticipate RNA-platform entrants repurposing COVID-19 manufacturing infrastructure by locking multi-year exclusive supply agreements with Gavi-eligible countries before competitor products reach WHO prequalification. Prioritize backward integration into lyophilization capacity in Singapore or Thailand to reduce third-party toll manufacturing exposure and defend margin position against emerging biologics specialists.
For New Entrants and Emerging Players: Recombinant subunit platform specialization targeting seronegative pediatric populations excluded from current live-attenuated labels offers the most penetrable white space. Target community health center channels in rural Indonesia and Myanmar where rapid diagnostic integration enables same-day vaccine eligibility determination without hospital infrastructure. Pursue technology licensing from US NIH-funded envelope domain III research programs to accelerate clinical validation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biologics developers with Philippine or Vietnamese regulatory dossiers already submitted but awaiting manufacturing scale-up capital. Long-term viability over the next decade hinges on thermal-stable formulation portfolios that unlock sub-Saharan African expansion. Watch for EMA accelerated assessment pathway approvals as the inflection signal indicating European market access timelines compressing from 210 to 150 days.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks Gavi procurement eligibility and shapes competitive access benchmarks in endemic regions. |
| Thermal-Stable Formulation Development | Eliminates frozen storage requirements and enables last-mile distribution to rural Indonesian markets. |
| Point-of-Care Diagnostic Integration | Combines rapid NS1 antigen testing with mobile health platforms for same-day serostatus verification. |
| Multi-Year Framework Agreement Negotiation | Secures volume commitments from Thai and Malaysian centralized purchasing authorities. |
| Live-Attenuated Platform Diversification | Expands tetravalent coverage to capture pediatric immunization schedules in Philippine schools. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced against WHO prequalification status databases and national regulatory gazettes from the Philippines, Thailand, and Indonesia. Primary interviews with vaccine development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at tertiary centers in Bangkok, Manila, and Ho Chi Minh City validated demand assumptions. Bottom-up patient volume estimates and top-down national immunization program budget allocations were triangulated to constrain forecast variance.
Bottom-up modeling tracked product-level placements across treatment line, delivery mode, and end-user setting, while top-down analysis anchored aggregate market size to national health expenditure patterns and Gavi disbursement schedules across the projection horizon. CAGRs were derived from epidemiological burden projections and immunization coverage targets. Modeled dimensions included preventive versus curative modality, cold-chain dependency tier, and regional regulatory cluster alignment.
Several conditions sit outside the modeled scope, including abrupt serostatus labeling restrictions by the FDA or EMA, vector control program effectiveness in reducing transmission rates, and competitor product safety signals triggering post-market surveillance expansion. Forecasts reflect documented assumptions about WHO prequalification timelines and Gavi funding continuity. Deviation in national immunization program budget allocations or cold-chain infrastructure investment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Cysticercosis (Taeniasis) Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Facial Spasm Treatment Market
Medical Treatment
Vulvodynia Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Lice Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Global Radiodermatitis Treatment Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Mexico Hair Transplant Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Cytokine Release Syndrome Management Market
Medical Treatment
Molluscum Contagiosum (MC) Treatment Market