
 Cutaneous Squamous Cell Carcinoma Market | 2026-2036
Cutaneous Squamous Cell Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Cutaneous Squamous Cell Carcinoma Market Outlook
Biologics manufacturing capacity in North America is recalibrating around immune-oncology output. Sanofi leverages its dermatology heritage to sustain topical portfolio relevance alongside systemic pipelines. Amgen anchors its position through R&D intensity in bispecific antibody platforms for skin malignancies. Regeneron Pharmaceuticals differentiates via co-development alliances that extend its reach into checkpoint modulation.
Cutaneous squamous cell carcinoma denotes a malignant neoplasm arising from epidermal keratinocytes, characterized by invasive growth potential and metastatic risk in advanced stages, with histopathological grading based on differentiation, depth, and perineural invasion. Its primary purpose centers on clinical management through surgical excision, radiation, or systemic therapy to prevent local destruction and distant spread. Immunotherapy drugs command the fastest expansion within product type segments as PD-1 inhibitors reshape adjuvant and metastatic protocols. Dermatology clinics represent the highest-velocity end user channel, though specialized oncology centers capture the deepest margin pools for complex cases requiring multidisciplinary coordination.
FDA oncology center standards and EMA's MDR framework govern clinical evidence requirements and post-market surveillance for novel therapeutics, while HIPAA and GDPR shape patient data flows in trial recruitment and real-world evidence generation. These regulatory layers create asymmetric market access timelines across jurisdictions, favoring sponsors with established regulatory affairs infrastructure. Stakeholders must monitor evolving biomarker-defined trial endpoints and companion diagnostic linkages that will determine future reimbursement positioning and prescriber adoption thresholds.
Market Dynamics
The FDA's accelerated approval pathway for oncology biologics is compressing commercial timelines and forcing sponsors to front-load manufacturing capacity investments before confirmatory trial completion.
Growth Catalysts
- Immunotherapy Protocol Expansion:PD-1 inhibitors are displacing chemotherapy in adjuvant settings across dermatology clinics and hospital outpatient departments. Hospital outpatient departments are expanding adoption of combination therapy protocols.
- EMA MDR Framework Clarity:The Medical Device Regulation framework is streamlining companion diagnostic linkages for biomarker-defined patient stratification. This accelerates prescriber confidence in precision oncology approaches.
- Aging Population Screening Density:Germany, Japan, and the United States maintain intersecting dermatology screening programs and expanding elderly demographics. These countries concentrate demand for advanced systemic therapies.
Market Restraints
- Cold Chain Biologics Distribution Cost:Temperature-controlled logistics for checkpoint inhibitors impose 15-25% cost premiums versus small-molecule alternatives. Rural and community oncology centers face access inequities.
- Clinical Trial Recruitment Saturation:Competing PD-1/PD-L1 programs fragment eligible patient pools across overlapping trial protocols. This elongates enrollment timelines for novel bispecific antibody candidates.
- Perioperative Immunotherapy Toxicity Management:Immune-related adverse events require specialized multidisciplinary coordination unavailable in standard dermatology practice settings. This limits community penetration.
Strategic Opportunities
- Neoadjuvant Therapy White Space:Pre-surgical immunotherapy protocols remain underdeveloped versus adjuvant and metastatic settings. Sponsors with surgical oncology relationships can establish first-mover positioning.
- Real-World Evidence Infrastructure:HIPAA-compliant patient data flows enable post-market surveillance and label expansion. Dermatology registries in the United States and Japan support accelerated regulatory submissions.
- Topical-Systemic Combination Platforms:Convergence of intralesional cytokine therapies with systemic checkpoint modulation offers localized toxicity profiles. Dermatology clinics represent the highest-velocity channel for such innovations.
Industry Challenges
- Biomarker Assay Standardization:PD-L1 expression scoring discordance across diagnostic platforms creates prescriber confusion and reimbursement friction. Pathology laboratories require harmonized training protocols.
- Manufacturing Scale-Up Complexity:Bispecific antibody production demands specialized single-use bioreactor configurations. Capacity constraints at contract manufacturing organizations delay commercial launch readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutaneous Squamous Cell Carcinoma Market |
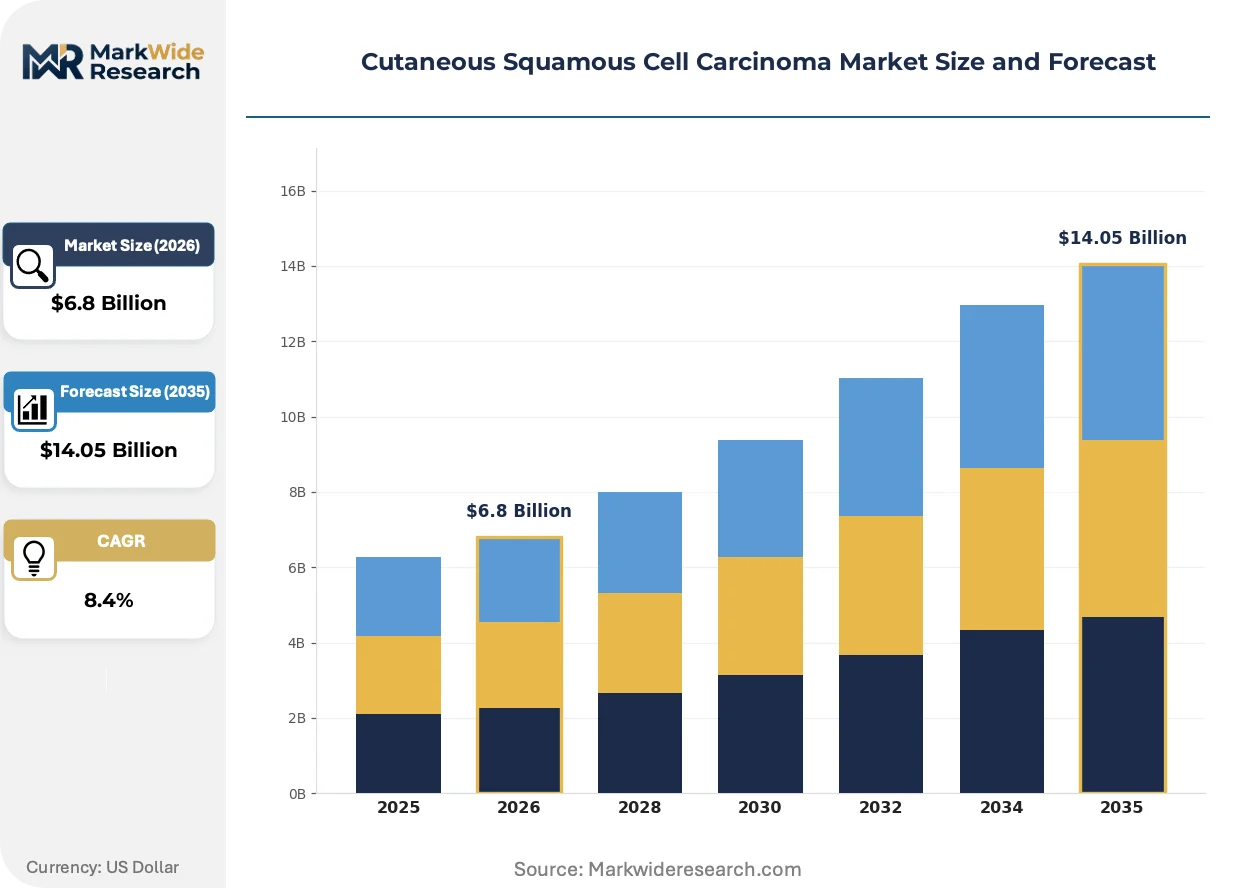
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Devices, Radiation Equipment, Immunotherapy Drugs, Chemotherapy Agents, Targeted Therapy Medicines Therapy Area: Skin Oncology, Dermatologic Surgery, Photodynamic Therapy, Immunomodulation, Radiation Oncology End User: Dermatology Clinics, Specialized Oncology Centers, Ambulatory Surgical Centers, Diagnostic Laboratories Delivery Mode: Topical Application, Intravenous Administration, Oral Medication, Local Injection, External Beam Radiation |
| Companies Covered | Sanofi, Amgen, Sun Pharma, LEO Pharma, Eli Lilly and Company, Checkpoint Therapeutics, Merck & Co., Cadila Healthcare, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutaneous Squamous Cell Carcinoma Market Strategic Shifts
Checkpoint modulation is unifying previously distinct treatment lines while companion diagnostics are collapsing the boundary between dermatology and medical oncology practice workflows.
Neoadjuvant PD-1 blockade is unifying surgical and medical oncology decision-making through pre-operative tumor response assessment. Academic medical centers in the United States and Germany are adopting this paradigm fastest. The approach is compressing time-to-definitive therapy while expanding multidisciplinary tumor board complexity.
EMA's MDR framework is mandating enhanced post-market clinical follow-up for novel therapeutics with accelerated approvals. Manufacturers must maintain active safety surveillance systems across European Economic Area jurisdictions. High-risk device-drug combinations face tightened notified body scrutiny and extended conformity assessment timelines.
Patient self-advocacy through social media channels is fragmenting traditional physician referral patterns for advanced cutaneous malignancies. Individuals diagnosed with regionally metastatic disease increasingly seek second opinions at specialized oncology centers. This behavioral shift concentrates case volume at NCI-designated cancer centers in the United States and university hospitals in Germany.
Cutaneous Squamous Cell Carcinoma Market Segmentation
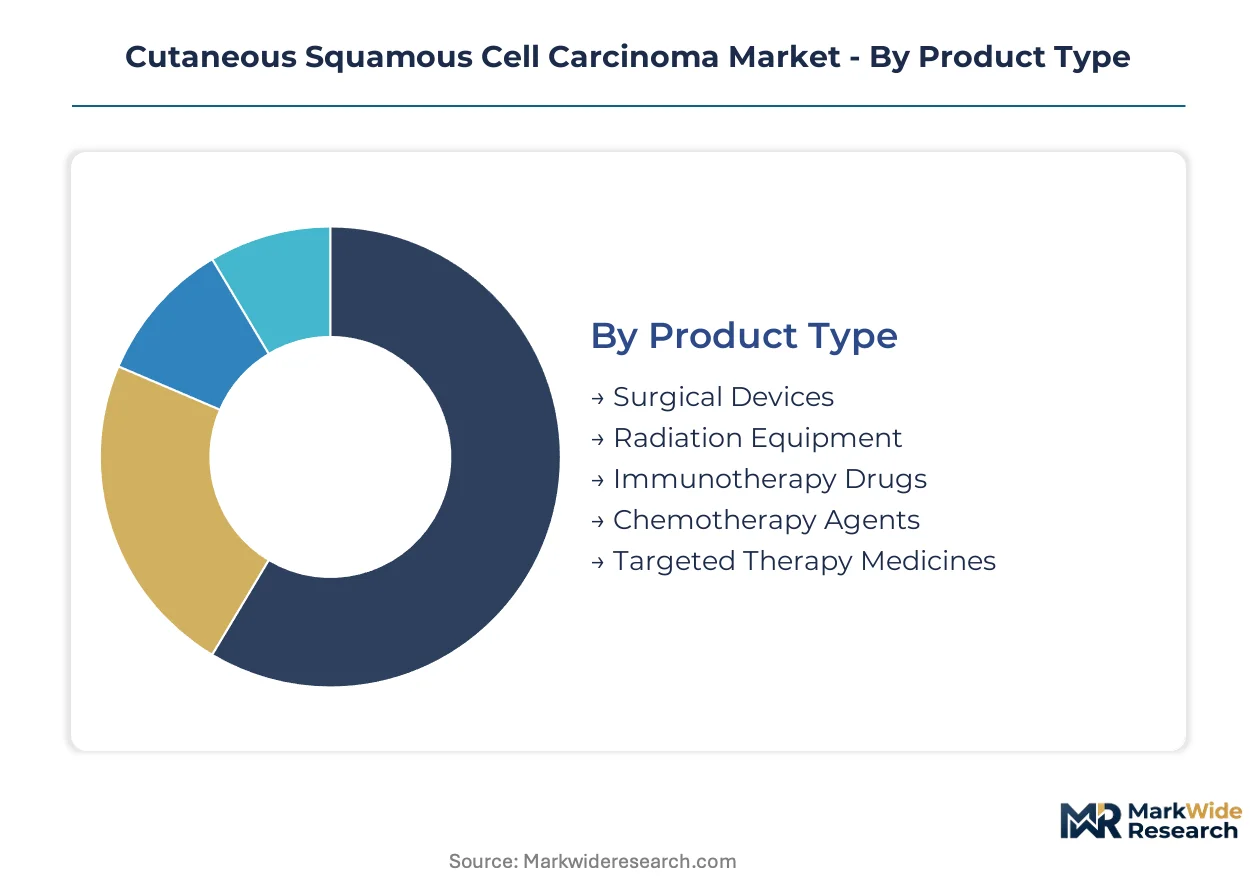
Cutaneous squamous cell carcinoma treatment selection hinges on tumor staging, patient comorbidity profiles, and institutional capability matrices. Segmentation reveals how immunotherapy is collapsing traditional boundaries between dermatology and medical oncology practice settings.
Product Type:
Procurement patterns diverge sharply between capital equipment buyers and pharmaceutical purchasers.
- Immunotherapy Drugs:PD-1 checkpoint inhibitors require cold chain infrastructure and specialized toxicity monitoring protocols. Hospital outpatient departments in the United States and Germany are expanding adjuvant immunotherapy protocols fastest.
- Surgical Devices:Mohs micrographic surgery instruments and margin assessment tools enable same-day definitive excision. Dermatology clinics concentrate demand for precision excision platforms with integrated histopathology capabilities.
- Radiation Equipment:Superficial orthovoltage units and electronic brachytherapy systems serve non-surgical candidates.
- Chemotherapy Agents:Cisplatin and 5-fluorouracil regimens retain niche utility in platinum-responsive metastatic disease.
- Targeted Therapy Medicines:EGFR inhibitors address select molecular subpopulations with advanced cutaneous involvement.
Volume sits with surgical devices; growth tilts toward immunotherapy drugs.
Therapy Area:
Institutional capability depth determines which therapy lines a facility can operationalize profitably.
- Skin Oncology:Multidisciplinary tumor boards coordinate systemic and local therapy sequencing. NCI-designated cancer centers in the United States capture complex case referrals through integrated diagnostic and therapeutic infrastructure.
- Dermatologic Surgery:Mohs surgery fellowship training programs constrain specialist supply. Academic medical centers in Germany maintain the deepest surgical oncology integration with dermatologic surgery departments.
- Photodynamic Therapy:Aminolevulinic acid protocols serve superficial and field-disease presentations.
- Immunomodulation:Intralesional cytokine therapies and topical immune response modifiers address localized disease.
- Radiation Oncology:External beam and brachytherapy approaches serve non-surgical candidates and adjuvant settings.
Revenue concentrates in skin oncology; capability expansion is accelerating fastest in dermatologic surgery.
End User:
Site-of-care economics and reimbursement density shape channel strategy.
- Dermatology Clinics:High-velocity diagnosis and initial excision drive patient throughput. United States-based dermatology groups are consolidating through private equity roll-ups to capture integrated pathology and Mohs surgery revenue streams.
- Specialized Oncology Centers:Multidisciplinary coordination for advanced disease commands premium reimbursement. University hospitals in Japan maintain the deepest integration of head-and-neck surgical oncology with dermatologic malignancy protocols.
- Ambulatory Surgical Centers:Lower-acuity excisions shift to outpatient surgical settings.
- Diagnostic Laboratories:PD-L1 companion diagnostic testing and molecular profiling support precision therapy selection.
Case volume flows through dermatology clinics; margin capture concentrates in specialized oncology centers.
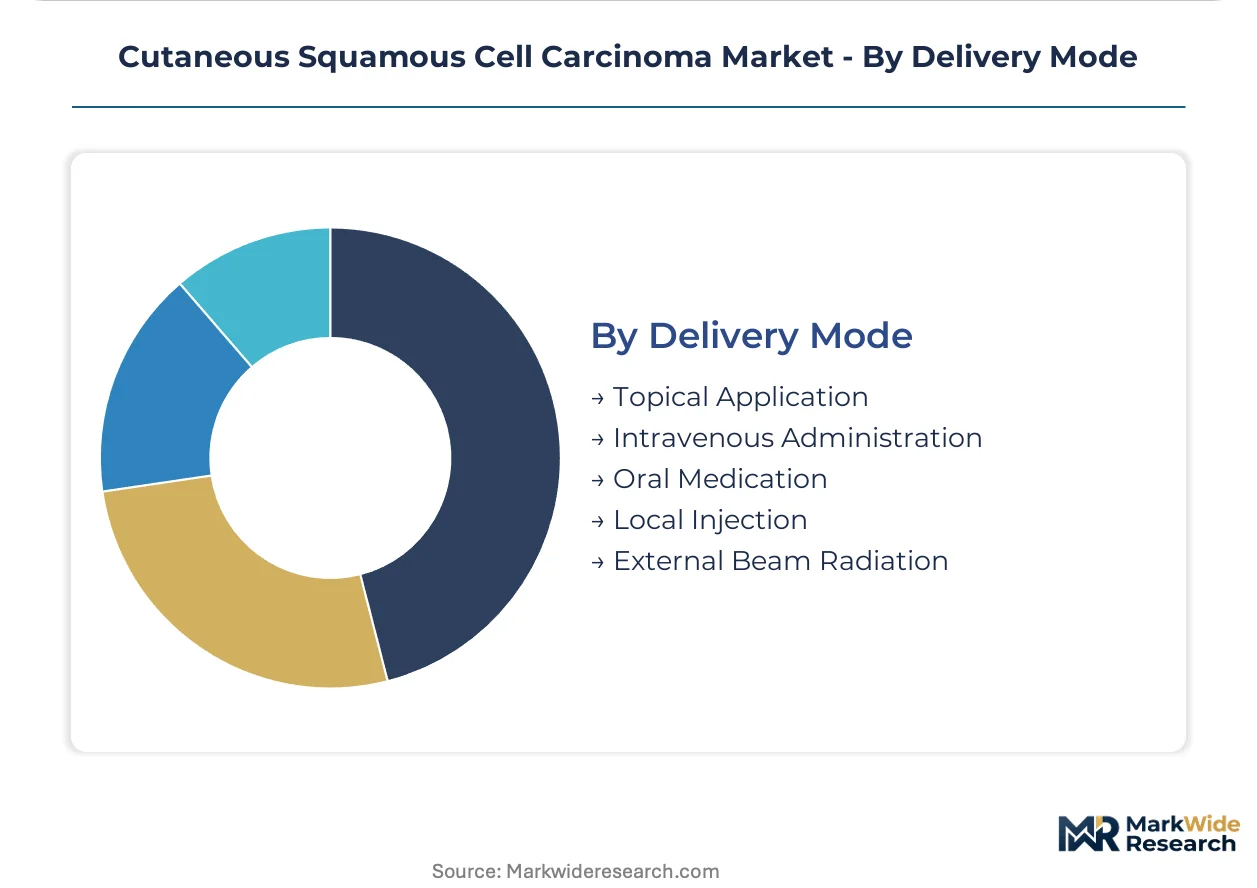
Delivery Mode:
Route selection determines prescriber specialty and monitoring intensity requirements.
- Intravenous Administration:Checkpoint inhibitors require infusion center infrastructure and immune-related adverse event management protocols. Hospital outpatient departments in Germany are standardizing pre-medication and monitoring protocols to reduce admission rates.
- Local Injection:Intralesional therapies enable targeted delivery with reduced systemic exposure. Dermatology clinics in the United States are piloting combination protocols pairing intralesional cytokines with systemic checkpoint blockade.
- Topical Application:Field-directed therapies address superficial and pre-malignant disease.
- Oral Medication:Targeted agents offer outpatient convenience for molecularly selected patients.
- External Beam Radiation:Fractionated protocols serve non-surgical candidates and adjuvant settings.
Utilization clusters around intravenous administration; innovation investment is shifting fastest toward local injection modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Keratinocyte biology research clusters anchor geographic demand for advanced cSCC therapeutics. Academic medical centers with integrated dermatologic surgery and medical oncology programs concentrate patient referral flows. Regulatory pathway efficiency varies sharply across jurisdictions, reshaping commercial sequencing decisions.
United States
NCI-designated cancer centers drive adoption of neoadjuvant PD-1 protocols for locally advanced disease. FDA's accelerated approval pathway compresses timelines for checkpoint inhibitors, with confirmatory trial requirements shaping post-market investment. The Greater Boston corridor hosts dense concentrations of immuno-oncology biotechs developing bispecific platforms.
Germany
University hospitals in Bavaria and North Rhine-Westphalia maintain Europe's deepest integration of dermatologic surgery with head-and-neck oncology. EMA's MDR framework mandates enhanced post-market surveillance for device-drug combinations, extending conformity assessments. The Heidelberg-Mannheim cluster advances companion diagnostic harmonization for PD-L1 scoring standardization.
Japan
Aging demographics and universal screening programs concentrate demand for advanced systemic therapies in Tokyo and Osaka metropolitan areas. PMDA's Sakigake designation system accelerates review timelines for breakthrough oncology products. National cancer center hospitals in Kashiwa and Tsukuba pioneer multidisciplinary tumor board models for complex cutaneous malignancies.
United Kingdom
Specialized skin cancer multidisciplinary teams in London and Manchester coordinate systemic therapy sequencing for metastatic patients. MHRA's post-Brexit regulatory autonomy enables divergence from EMA timelines for certain accelerated approvals. The Cambridge-Oxford corridor supports real-world evidence infrastructure through linked electronic health records.
India
CDSCO's streamlined oncology approval pathways attract biosimilar development for PD-1 inhibitors targeting cost-sensitive segments. Corporate hospital chains in Mumbai and Hyderabad expand dermatologic surgery capacity alongside medical oncology services. Sun Pharma and Cadila Healthcare anchor domestic manufacturing of immunotherapy and supportive care agents.
Cutaneous Squamous Cell Carcinoma Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bispecific antibody and neoadjuvant protocol white spaces. The market structure tilts toward R&D-intensive biopharmaceuticals with dermatology heritage, though pure-play oncology specialists capture premium positioning in checkpoint modulation. Three archetypes dominate: legacy dermatology houses with systemic pipeline extensions, immuno-oncology platforms with skin malignancy indications, and regional generics manufacturers with biosimilar strategies. Competitive moves center on co-development alliances for combination protocols and manufacturing capacity pre-commitments ahead of confirmatory data.
Within the dermatology heritage tier, Sanofi leverages topical portfolio cash flows to fund systemic biologic development. Amgen and Regeneron Pharmaceuticals exemplify the immuno-oncology platform archetype, with the latter's co-development alliances extending reach into checkpoint modulation. Sun Pharma and Cadila Healthcare occupy the emerging market manufacturing tier, supplying cost-optimized immunotherapy access across Asia-Pacific and Middle East jurisdictions. These five entities collectively represent the competitive spectrum from discovery-stage biologics to commercial-scale generic substitution.
| Leading Market Players |
|---|
| Sanofi |
| Amgen |
| Sun Pharma |
| LEO Pharma |
| Eli Lilly and Company |
| Checkpoint Therapeutics |
| Merck & Co. |
| Cadila Healthcare |
| Regeneron Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Cold-chain logistics cost indices for biologics distribution cascade through hospital outpatient departments and dermatology clinics into three distinct pricing tiers for checkpoint inhibitors. Temperature-controlled transport premiums concentrate pricing power with sponsors possessing integrated distribution infrastructure, while community oncology centers face access inequities that reshape procurement patterns across United States, Germany, and Japan.
Pricing Analysis
Service bundling separates cold-chain assurance and immune-related adverse event management from base pharmaceutical pricing in most contract structures. Three-tier pricing structure across premium, standard, and economy levels reflects institutional capability depth, with NCI-designated cancer centers capturing bundled multidisciplinary coordination while dermatology clinics negotiate unbundled per-dose arrangements. Cost compression in community settings is intensifying because cold-chain infrastructure requirements impose fixed cost burdens on lower-volume purchasers. Hospital outpatient departments in Germany exhibit the highest price sensitivity due to EMA MDR framework compliance costs, while specialized oncology centers in the United States demonstrate the least.
Supply Chain Analysis
Single-use bioreactor components rest on specialized manufacturing clusters in the United States, Germany, and Switzerland for bispecific antibody production. Stainless steel bioreactor systems, gamma-irradiated tubing assemblies, and proprietary cell culture media formulations feed from concentrated supplier bases near Boston and Basel. Single-source vulnerability in gamma-irradiation sterilization capacity creates chokepoint exposure for commercial launch readiness. Distribution runs through temperature-controlled third-party logistics providers with validated cold-chain documentation for checkpoint inhibitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward integration into biologics manufacturing capacity determines competitive survival. Sponsors pre-commit to specialized single-use bioreactor configurations before confirmatory trial completion to secure launch readiness.
For Market Incumbents: Hedge against biosimilar substitution by locking long-term capacity agreements with contract manufacturing organizations in North America and Europe. Amgen and Regeneron Pharmaceuticals exemplify defensive positioning through R&D intensity in bispecific antibody platforms. Manufacturing scale-up complexity represents the primary margin pressure point; sponsors should prioritize in-house production of critical cell culture media formulations to reduce supplier dependency.
For New Entrants and Emerging Players: Launch via neoadjuvant therapy protocols in academic medical centers with established surgical oncology relationships. The white space in pre-surgical immunotherapy offers the most penetrable entry point against entrenched adjuvant and metastatic competitors. Checkpoint Therapeutics and similar emerging entities should target co-development alliances with dermatology heritage firms to access established prescriber networks.
For Investors and Strategic Acquirers: The window for entry favors mid-cap biopharmaceuticals with differentiated bispecific platforms and neoadjuvant clinical data packages. Long-term viability over the next decade hinges on manufacturing capacity ownership rather than pure discovery-stage assets. Watch FDA accelerated approval pathway decisions for novel checkpoint modulators as the critical inflection indicator for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Pre-commitment to single-use bioreactor capacity ahead of confirmatory data secures commercial launch timelines. |
| Neoadjuvant Protocol Development | First-mover positioning in pre-surgical immunotherapy unifies surgical and medical oncology decision-making. |
| Companion Diagnostic Harmonization | PD-L1 scoring standardization across pathology laboratories reduces prescriber confusion and reimbursement friction. |
| Co-Development Alliance | Partnerships between immuno-oncology platforms and dermatology heritage firms extend reach into checkpoint modulation. |
| Real-World Evidence Infrastructure | HIPAA-compliant patient data flows enable post-market surveillance and accelerated label expansion submissions. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation validated segment-level estimates.
Data-stream reconciliation across treatment line, administration route, patient population, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from modeled patient incidence curves and therapy penetration assumptions across the projection horizon. Biosimilar entry timelines and accelerated approval pathway success rates served as industry-specific forecast inputs.
Regulatory pathway delays, manufacturing scale-up failures, and biomarker assay standardization setbacks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about therapy adoption curves and reimbursement positioning. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Global Dermatology Cro Market
Dermatology
Global Radiodermatitis Market
Dermatology
Japan Scar Treatment Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Folliculitis Market
Dermatology
Acne Vulgaris Market
Dermatology
Keloid Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Europe Scar Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Skin Excision Market