
 Angelman Syndrome Treatment Market | 2026-2036
Angelman Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Angelman Syndrome Treatment Market Outlook
Antisense oligonucleotide chemistry is pivoting toward next-generation backbone modifications that improve central nervous system penetration and durability. Ultragenyx Pharmaceutical leverages its rare disease infrastructure to sustain clinical momentum across multiple neurogenetic indications. GeneTx Biotherapeutics anchors its position through a focused partnership strategy targeting UBE3A gene reactivation. Ionis Pharmaceuticals differentiates via its proprietary ligand-conjugated antisense platform, which competes for investigator attention in academic medical centers.
Angelman syndrome treatment encompasses therapeutic interventions designed to address the genetic and neurological manifestations of UBE3A imprinting defects, including antisense-mediated unsilencing of paternal allele expression and symptomatic management of seizures, motor dysfunction, and communication deficits. Gene therapy approaches target vectorized delivery to the central nervous system with specificity for neuronal populations, while symptomatic treatment remains the current commercial mainstay encompassing anticonvulsant and behavioral intervention protocols. Anticonvulsants occupy the largest existing revenue pool due to immediate prescriber familiarity and established reimbursement pathways, whereas gene therapy represents the fastest-expanding segment as clinical-stage candidates advance through registrational trials. The treatment stage segmentation reveals FDA Approved therapies commanding stable margins while clinical trials activity concentrates investment flow toward proof-of-concept readouts.
The FDA Orphan Drug Designation and Rare Pediatric Disease Priority Review Voucher programs shape development economics by compressing regulatory timelines and enhancing commercial exclusivity value. EMA's parallel orphan designation framework and the EU's Paediatric Regulation create complementary market access pathways for sponsors pursuing transatlantic development strategies. Stakeholders must monitor biomarker qualification progress and payer evidence requirements for one-time gene therapies versus chronic symptomatic management paradigms.
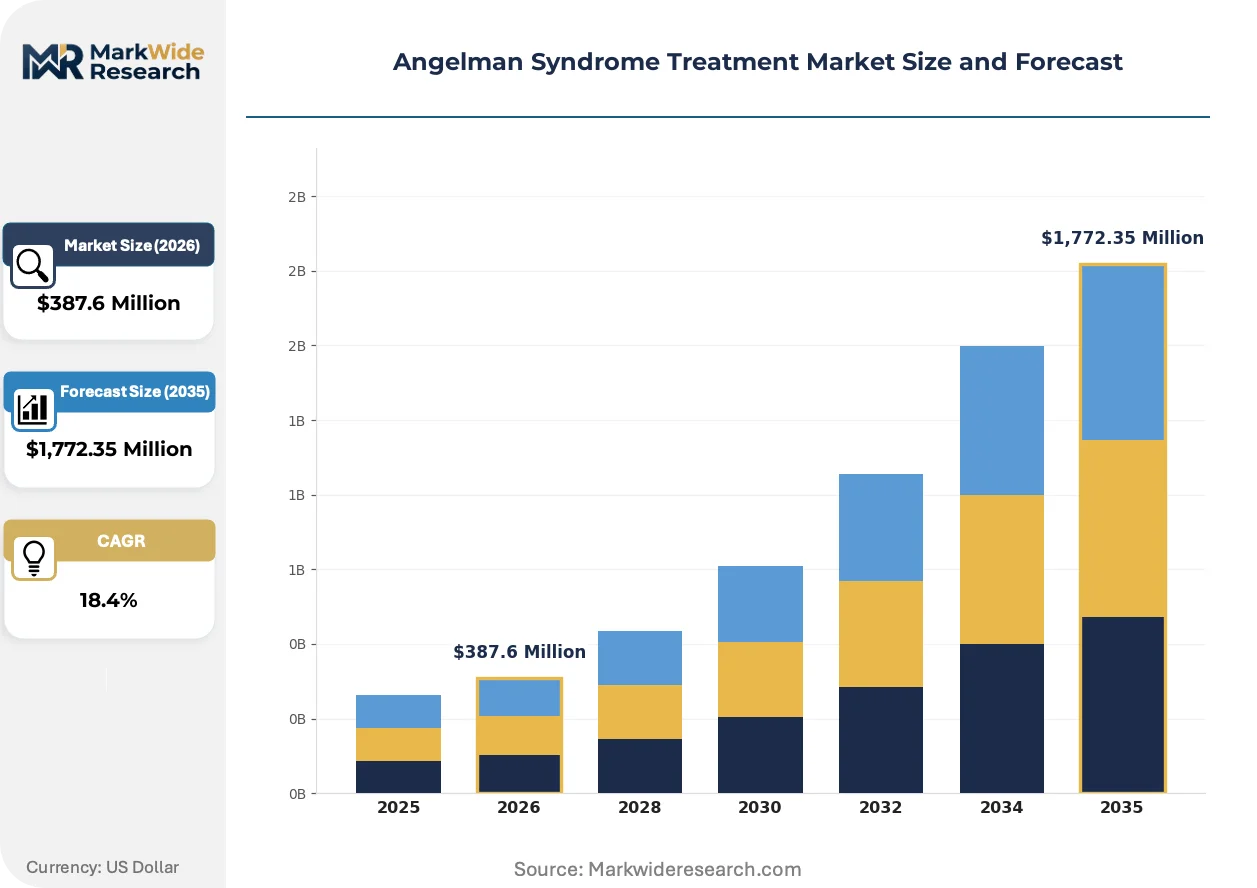
Market Dynamics
The FDA's Rare Pediatric Disease Priority Review Voucher program is compressing development timelines for Angelman syndrome therapeutics, while academic medical centers concentrate clinical trial capacity in a handful of metropolitan research clusters.
Growth Catalysts
- FDA Orphan Drug Designation:This framework accelerates regulatory review timelines and extends commercial exclusivity periods for sponsors addressing UBE3A imprinting defects.
- Antisense oligonucleotide platforms:Next-generation backbone modifications are improving central nervous system penetration and therapeutic durability in neurogenetic indications.
- Pediatric neurology clinic expansion:Dedicated Angelman programs at children's hospitals are consolidating patient access and trial enrollment infrastructure.
Market Restraints
- Central nervous system delivery costs:Vector manufacturing and blood-brain barrier penetration technologies impose substantial cost burdens on gene therapy development.
- Single-source vector supply:Viral vector production concentrates among contract manufacturers in the United States and Europe, creating supply vulnerability.
- Biomarker qualification gaps:The absence of validated surrogate endpoints for UBE3A unsilencing complicates registrational trial design and regulatory submissions.
Strategic Opportunities
- EMA parallel orphan designation:Sponsors pursuing transatlantic development strategies gain complementary market access pathways through the EU's Paediatric Regulation framework.
- Gene therapy reimbursement innovation:Outcomes-based payment models for one-time interventions are emerging as alternatives to chronic symptomatic management paradigms.
- Academic medical center networks:Investigator-initiated studies at specialized research institutions are generating real-world evidence to support payer negotiations.
Industry Challenges
- Neurogenetic clinical trial expertise:Patient recruitment and retention in Angelman populations requires specialized nursing and behavioral support capabilities that remain scarce.
- Gene therapy manufacturing scale-up:Viral vector production capacity constraints are extending lead times for clinical-grade material supply.
- Payer evidence requirements:Health technology assessment bodies demand longer follow-up data for one-time therapies than current clinical trial designs provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angelman Syndrome Treatment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Enzyme Replacement Therapy, Symptomatic Treatment, Anticonvulsants Treatment Stage: Clinical Trials, Post-Marketing, Preclinical, FDA Approved Care Setting: Hospital, Specialized Clinic, Home Care, Rehabilitation Center End User: Pediatric Patients, Caregivers, Healthcare Professionals, Research Institutions |
| Companies Covered | Ultragenyx Pharmaceutical, Ovid Therapeutics, GeneTx Biotherapeutics, Ionis Pharmaceuticals, Neuren Pharmaceuticals, Biogen, Elesion Therapeutics, PTC Therapeutics, Taysha Gene Therapies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angelman Syndrome Treatment Market Strategic Shifts
Antisense chemistry is advancing toward durable paternal allele unsilencing, while regulatory frameworks adapt to accommodate one-time gene interventions. These shifts are reconfiguring competitive positioning around manufacturing scale and biomarker validation capabilities.
Ligand-conjugated antisense platforms are electrifying therapeutic access to neuronal populations previously considered unreachable. Academic medical centers are adopting these chemistries for investigator-initiated protocols. The technology is electrifying debate around optimal dosing intervals and durability benchmarks that will define commercial viability.
The EU's Paediatric Regulation is mandating pediatric investigation plans for all novel therapeutics in development, regardless of initial indication. This requirement is expanding the addressable patient population for sponsors with Angelman programs. European regulatory submissions now demand earlier integration of pediatric pharmacokinetic data than historical adult-first paradigms allowed.
Caregiver advocacy organizations are consolidating purchasing influence through foundation-backed patient registries. These registries are displacing traditional physician-driven trial recruitment with direct-to-family enrollment platforms. The United States exhibits the most pronounced shift, where early-access protocols and expanded compassionate use frameworks have concentrated demand among research-intensive institutions.
Angelman Syndrome Treatment Market Segmentation
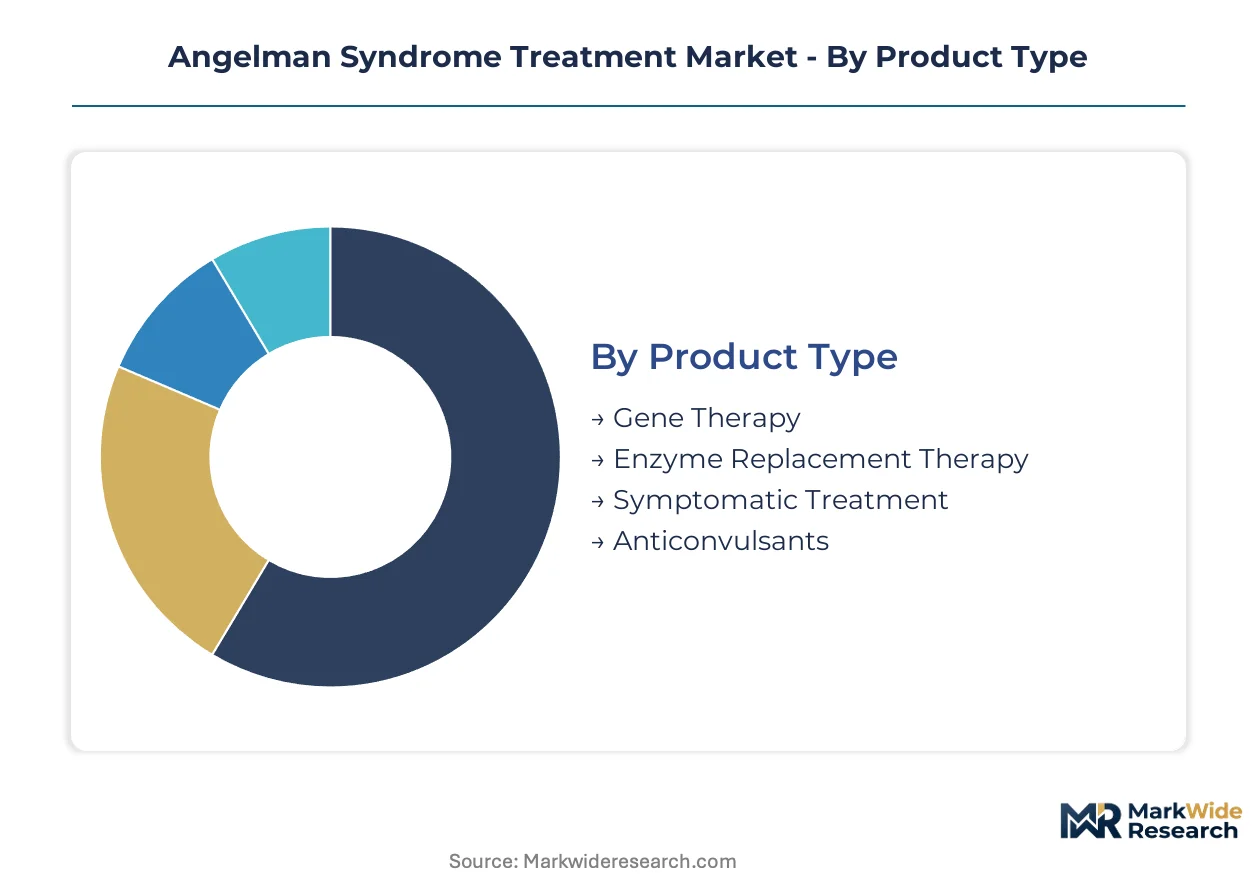
Segmentation in Angelman syndrome therapeutics reveals how development-stage technologies, care delivery infrastructure, and patient access pathways compete for capital allocation. Each category exposes different margin structures and regulatory dependencies that shape sponsor strategy.
Product Type:
Standardization dominates gene therapy manufacturing while symptomatic treatments permit formulation customization across patient phenotypes.
- Gene Therapy:Vectorized delivery systems target UBE3A gene reactivation through intrathecal or intravenous administration. Demand concentrates at academic medical centers in the United States with established neurogenetic surgery programs, constrained by viral vector manufacturing bottlenecks and CNS delivery cost structures.
- Anticonvulsants:Small-molecule seizure management compounds constitute the current commercial backbone with immediate prescriber familiarity and established pharmacy benefit reimbursement. Prescription volume clusters among pediatric neurologists managing comorbid epilepsy, driven by formulary inclusion and generic substitution patterns.
- Symptomatic Treatment:Behavioral and motor dysfunction interventions span physical therapy protocols and communication augmentation devices.
- Enzyme Replacement Therapy:Protein-based approaches addressing downstream metabolic consequences of UBE3A deficiency remain investigational.
Most installed capacity flows through Anticonvulsants. Expansion is steepest in Gene Therapy.
Treatment Stage:
Margin profiles invert across the maturity curve, with approved therapies capturing stable reimbursement while clinical-stage assets absorb development risk.
- FDA Approved:Commercialized therapies command predictable pharmacy and medical benefit coverage with established prior authorization pathways. Revenue concentrates among anticonvulsant prescribers at children's hospitals with dedicated Angelman programs, supported by specialty pharmacy distribution networks.
- Clinical Trials:Active investigational programs in Phases 1-3 generate site fees and patient travel reimbursement flows while consuming substantial R&D capital. Enrollment demand clusters at metropolitan research institutions with neurogenetic nursing expertise, driven by caregiver advocacy organization referrals.
- Preclinical:Discovery-stage assets in IND-enabling studies absorb toxicology and manufacturing investment without near-term revenue potential.
- Post-Marketing:Phase 4 commitments and real-world evidence generation extend regulatory obligations beyond initial approval.
Investment flow concentrates in Clinical Trials. Value capture is deepest in FDA Approved.
Care Setting:
Acuity gradients determine staffing requirements and reimbursement codes across delivery sites.
- Specialized Clinic:Dedicated Angelman programs at children's hospitals consolidate multidisciplinary care including neurology, genetics, and developmental pediatrics. Patient volume clusters at US academic medical centers with foundation-backed registry partnerships, driven by centralized trial access and caregiver travel willingness.
- Hospital:Inpatient admissions manage acute seizure escalation and surgical interventions including gastrostomy placement. Demand concentrates at quaternary pediatric facilities with epilepsy monitoring units, constrained by bed capacity and prior authorization requirements.
- Home Care:Private duty nursing and therapy services extend institutional protocols to residential settings.
- Rehabilitation Center:Intensive motor and communication therapy programs address developmental delay progression.
Most patient encounters flow through Specialized Clinic. Capacity expansion is fastest in Home Care.
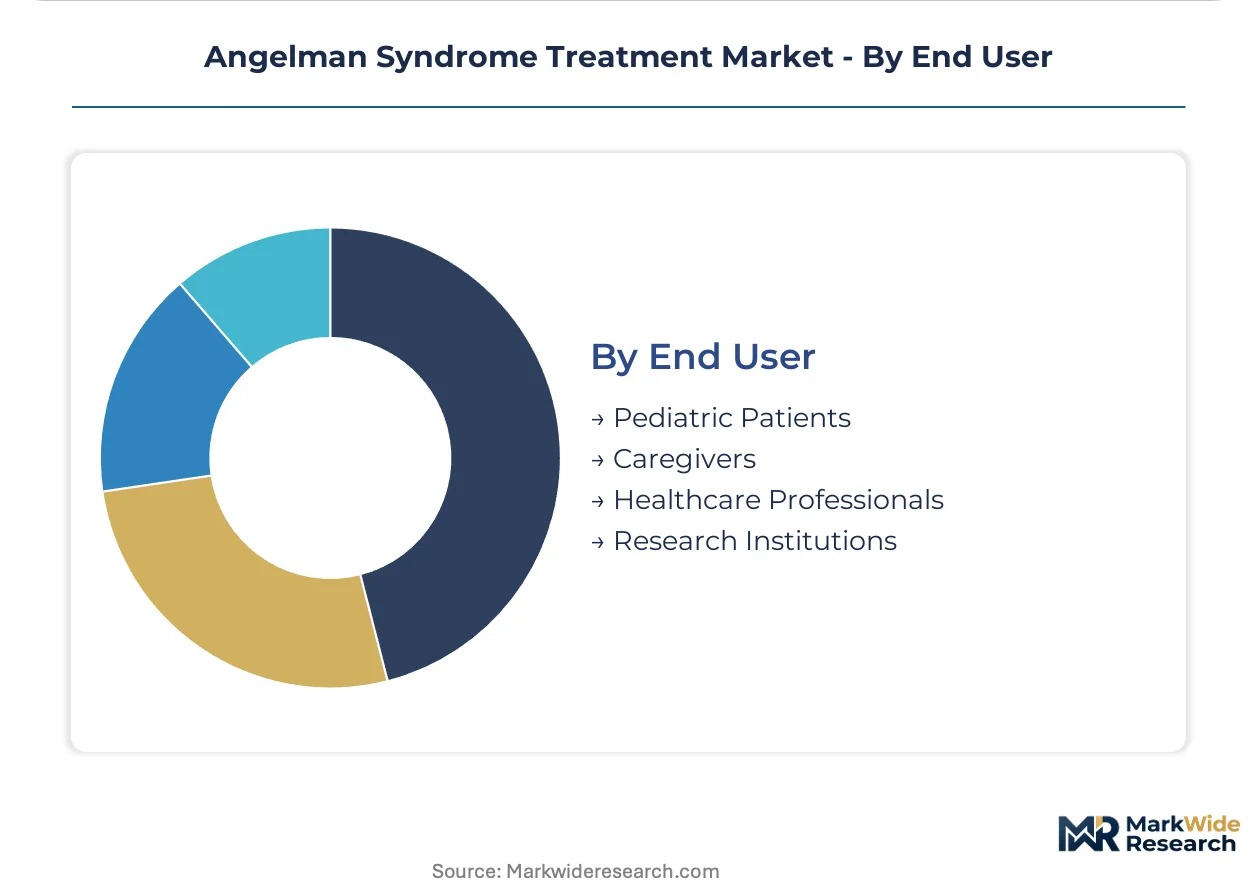
End User:
Decision authority fragments across patients, caregivers, and institutional purchasers with divergent evidence requirements.
- Pediatric Patients:The direct therapeutic beneficiaries with genotype-confirmed UBE3A imprinting defects, typically diagnosed before age three. Care access concentrates in US metropolitan areas with specialized neurogenetic diagnostic capacity, driven by newborn screening expansion and developmental delay referral patterns.
- Caregivers:Parents and guardians exercise substantial purchasing influence through foundation-backed registries and direct-to-family trial enrollment platforms. Engagement clusters among US advocacy organizations with early-access protocol navigation expertise, driven by information asymmetry reduction through peer networks.
- Healthcare Professionals:Pediatric neurologists and geneticists prescribe and manage therapeutic protocols.
- Research Institutions:Academic medical centers conduct investigator-initiated studies and sponsor-sponsored trials.
Most commercial decisions flow through Caregivers. Evidence generation concentrates on Pediatric Patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's concentration of academic medical centers anchors clinical trial capacity for neurogenetic therapeutics. The United States concentrates specialized pediatric neurology infrastructure and early-access protocol frameworks. Germany, the United Kingdom, Japan, and Australia each host distinct regulatory and research ecosystems shaping regional development patterns.
United States
Caregiver advocacy organizations in Massachusetts and California drive direct-to-family enrollment platforms that displace traditional physician-led recruitment. The FDA's Rare Pediatric Disease Priority Review Voucher program compresses development timelines for UBE3A-targeted therapeutics. Boston Children's Hospital and UCSF Benioff Children's Hospitals anchor the nation's densest Angelman program networks.
Germany
Academic medical centers in Munich and Heidelberg concentrate neurogenetic nursing expertise for complex pediatric trial populations. EMA's parallel orphan designation framework complements FDA pathways for sponsors pursuing transatlantic strategies. The country's national pharmaceutical regulator mandates pediatric investigation plans earlier than historical adult-first paradigms permitted.
United Kingdom
London's Great Ormond Street Hospital and Manchester's specialized genetics centers consolidate multidisciplinary care for UBE3A-imprinting defects. The NHS England's specialized commissioning framework creates distinct reimbursement pathways for one-time gene interventions versus chronic management. Cambridge's biotech cluster attracts antisense chemistry investment targeting neuronal delivery platforms.
Japan
PMDA's sakigake designation system accelerates first-in-human studies for neurogenetic candidates at Tokyo and Osaka academic hospitals. The country's national pharmaceutical regulator demands longer follow-up data for gene therapies than current clinical trial designs provide. Keio University and the University of Tokyo anchor investigator-initiated study networks generating real-world evidence.
Australia
TGA's orphan drug program and early access schemes attract Phase 1-2 trial investment to Melbourne and Sydney pediatric research units. The country's national pharmaceutical regulator aligns with FDA and EMA on biomarker qualification standards for UBE3A unsilencing endpoints. Murdoch Children's Research Institute hosts one of the southern hemisphere's largest neurogenetic patient registries.
Angelman Syndrome Treatment Market Competitive Environment
Global majors compete with regional champions across regulatory strategy and manufacturing scale. The vendor base stratifies into three tiers: integrated rare disease platforms, antisense chemistry specialists, and gene therapy vector developers. Dominant competitive moves include strategic partnerships for UBE3A gene reactivation and capacity expansion for viral vector production.
Within the rare disease platform tier, Ultragenyx Pharmaceutical and GeneTx Biotherapeutics exemplify archetypes leveraging focused partnership strategies. Ionis Pharmaceuticals occupies a position representing ligand-conjugated antisense specialists competing for academic medical center investigator attention. These three entities anchor distinct strategic postures around CNS penetration chemistry, gene reactivation partnerships, and vectorized delivery manufacturing.
| Leading Market Players |
|---|
| Ultragenyx Pharmaceutical |
| Ovid Therapeutics |
| GeneTx Biotherapeutics |
| Ionis Pharmaceuticals |
| Neuren Pharmaceuticals |
| Biogen |
| Elesion Therapeutics |
| PTC Therapeutics |
| Taysha Gene Therapies |
| Others |
Value Chain & Pricing Dynamics
Next-generation antisense backbone chemistry is compressing manufacturing cost curves while concentrating viral vector production among United States and European contract manufacturers. This dual shift simultaneously reshapes therapeutic pricing power and supply vulnerability for gene therapy developers.
Pricing Analysis
Input-cost pass-through from viral vector manufacturing dominates gene therapy pricing structures. Three-tier pricing stratifies across premium intrathecal delivery, standard intravenous administration, and economy-tier symptomatic management protocols. Price differentiation hinges on CNS penetration certification and caregiver support bundling. Pricing pressure stems from single-source vector supply constraints. Caregivers enrolled in foundation-backed registries exhibit lowest price sensitivity due to early-access protocol navigation.
Supply Chain Analysis
Reverse-logistics flows for clinical trial materials and compassionate use drug returns concentrate regulatory compliance burdens on United States and German distribution hubs. Viral vector manufacturing draws from plasmid DNA suppliers in the United States, cell line providers in Europe, and fill-finish capacity in Switzerland. Single-source vector supply vulnerability creates structural risk. Distribution runs through specialty pharmacy networks anchored at academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Angelman syndrome treatment market functions as a geographic-arbitrage play between FDA accelerated approval pathways and EMA pediatric investigation mandates, with development cost differentials favoring transatlantic strategies.
For Market Incumbents: Acquire antisense chemistry platforms with validated CNS penetration data to counter emerging ligand-conjugated competitors. Expand viral vector manufacturing capacity in the United States to reduce single-source supply vulnerability. Secure foundation-backed patient registry partnerships to defend trial enrollment access against direct-to-family enrollment platforms. For New Entrants and Emerging Players: Capture white-space in Japanese and Australian early-access schemes where PMDA sakigake and TGA orphan programs compress first-in-human timelines. Target caregiver advocacy organizations with navigation expertise as the most penetrable channel. Deploy outcomes-based contracting models to differentiate from chronic symptomatic management paradigms. For Investors and Strategic Acquirers: Valuations sit cheapest among clinical-stage antisense developers with biomarker-qualified endpoints but incomplete registrational data. Long-term viability over the next decade hinges on manufacturing scale and regulatory exclusivity duration. Monitor FDA Rare Pediatric Disease Priority Review Voucher issuance frequency as the critical inflection signal for development economics.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase 3 readouts for UBE3A unsilencing endpoints anchor registrational submissions to FDA and EMA. |
| Manufacturing Scale-Up | Viral vector capacity expansion at United States contract manufacturers reduces supply lead times for gene therapy candidates. |
| Regulatory Approval Pathway | Orphan drug designation applications compress review timelines and extend commercial exclusivity periods. |
| Licensing Agreement | Partnerships with academic medical centers secure investigator-initiated study networks and real-world evidence generation. |
| Pipeline Diversification | Antisense platform expansion into adjacent neurogenetic indications leverages CNS delivery chemistry investments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged drug development executives at rare disease platforms, regulatory affairs leads navigating FDA and EMA orphan pathways, formulary directors at specialty pharmacy benefit managers, and payer access specialists at United States commercial insurers. Secondary validation drew from FDA orphan drug designations, EMA pediatric investigation plans, ClinicalTrials.gov enrollment data, and foundation-backed patient registry disclosures. Bottom-up patient population estimates and top-down therapeutic revenue projections underwent iterative reconciliation.
Comparable-period anchoring linked projection assumptions to historical regulatory approval timelines and commercial launch trajectories across neurogenetic indications. The analytical framework modeled segmentation across treatment stage, product type, care setting, and regional regulatory cluster. CAGRs derived from patent expiry curves, biosimilar entry assumptions, and gene therapy adoption elasticity. Forecast inputs incorporated biomarker qualification progress and caregiver advocacy organization purchasing influence trajectories.
Underlying measurement precision varies by segment; FDA Approved therapies carry tighter precision than Preclinical assets due to reimbursement data availability. Forecasts reflect assumptions about regulatory exclusivity duration and vector manufacturing cost compression. Practitioners should monitor FDA Priority Review Voucher policy revisions and EMA pediatric investigation plan enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Global Leukapheresis Market
Medical Treatment
Thyroid Gland Disorders Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
North America Breast Reconstruction Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Global Acromegaly Treatment Market
Medical Treatment
Diphtheria Treatment Market
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Precocious Puberty Treatment Market