
 Global Chiropractic Care Market | 2026-2036
Global Chiropractic Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chiropractic Care Market Foresight
Corporate health programs is unwinding traditional reliance on individual out-of-pocket payments as the dominant buyer archetype in chiropractic services. The Joint Corp leverages a membership-based retail model to sustain high patient throughput across suburban shopping centers. HealthSource Chiro anchors its competitive position through integrated wellness protocols that combine spinal adjustment with lifestyle counseling. Chiro One Wellness Centers dominates in metropolitan markets by controlling multi-site clinic networks with centralized administrative infrastructure.
Chiropractic care encompasses manual and instrument-assisted manipulation of the spine and musculoskeletal structures to restore joint mobility, alleviate pain, and support neurological function without pharmaceutical or surgical intervention. Practitioners typically apply controlled thrusts with specified force ranges to vertebral segments, complemented by soft tissue therapy and rehabilitative exercise prescriptions targeting specific motion deficits. Spinal adjustment services command the largest revenue share due to established reimbursement pathways and patient familiarity, while telehealth consultations represent the fastest-expanding delivery mode as remote diagnostic tools and exercise supervision protocols gain clinical acceptance. Rehabilitation exercises capture concentrated margin pools through recurring session structures and durable medical equipment bundling that extends per-patient revenue cycles.
The FDA regulates chiropractic adjusting instruments as Class I or Class II medical devices, imposing quality system requirements that filter equipment suppliers and elevate clinic capital costs. Australia's TGA and private health funds jointly determine rebate eligibility for chiropractic services, directly influencing patient access and provider network participation decisions. Stakeholders must monitor evolving telehealth reimbursement policies and scope-of-practice expansions that could redistribute patient volumes between traditional in-person clinics and technology-enabled care models.
Market Dynamics
Corporate health programs are displacing individual out-of-pocket payment as the dominant buyer archetype, forcing clinic operators to restructure pricing and service bundling for employer-sponsored contracts.
Growth Catalysts
- Employer musculoskeletal cost containment:Large self-insured employers in the United States are expanding chiropractic benefit allocations to reduce surgical intervention rates and opioid prescriptions for back pain.
- TGA regulatory clarity:Australia's Therapeutic Goods Administration provides explicit medical device classification pathways for chiropractic instruments, reducing market entry friction for equipment suppliers.
- Instrument-assisted adjustment technology:Computerized adjusting devices with force-feedback sensors are penetrating high-volume suburban clinics seeking to standardize treatment protocols across multi-site networks.
Market Restraints
- Reimbursement fragmentation:Private health insurance rebate variability across Australian states creates patient access disparities that constrain clinic network standardization.
- FDA Class II device compliance costs:Quality system regulation requirements for chiropractic adjusting instruments elevate capital expenditure thresholds for independent practitioners.
- Physical therapy substitution:Licensed physical therapists in the United States are expanding spinal manipulation scope-of-practice in multiple states, diverting patient volumes from chiropractic-specific providers.
Strategic Opportunities
- Telehealth diagnostic convergence:Remote motion analysis platforms paired with exercise supervision protocols are opening patient segments beyond traditional geographic clinic catchments.
- Rehabilitation equipment bundling:Durable medical device integration with recurring session structures extends per-patient revenue cycles in Australian private practice networks.
- Corporate on-site clinic placement:Employer-sponsored health campuses in suburban United States office parks represent underpenetrated distribution channels for membership-based service models.
Industry Challenges
- Practitioner supply constraints:Accredited chiropractic college graduation rates in the United States lag behind clinic network expansion timelines, compressing wage structures in metropolitan markets.
- Electronic health record interoperability:Legacy practice management systems in independent Australian clinics resist integration with insurer rebate processing platforms, delaying claims cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chiropractic Care Market |
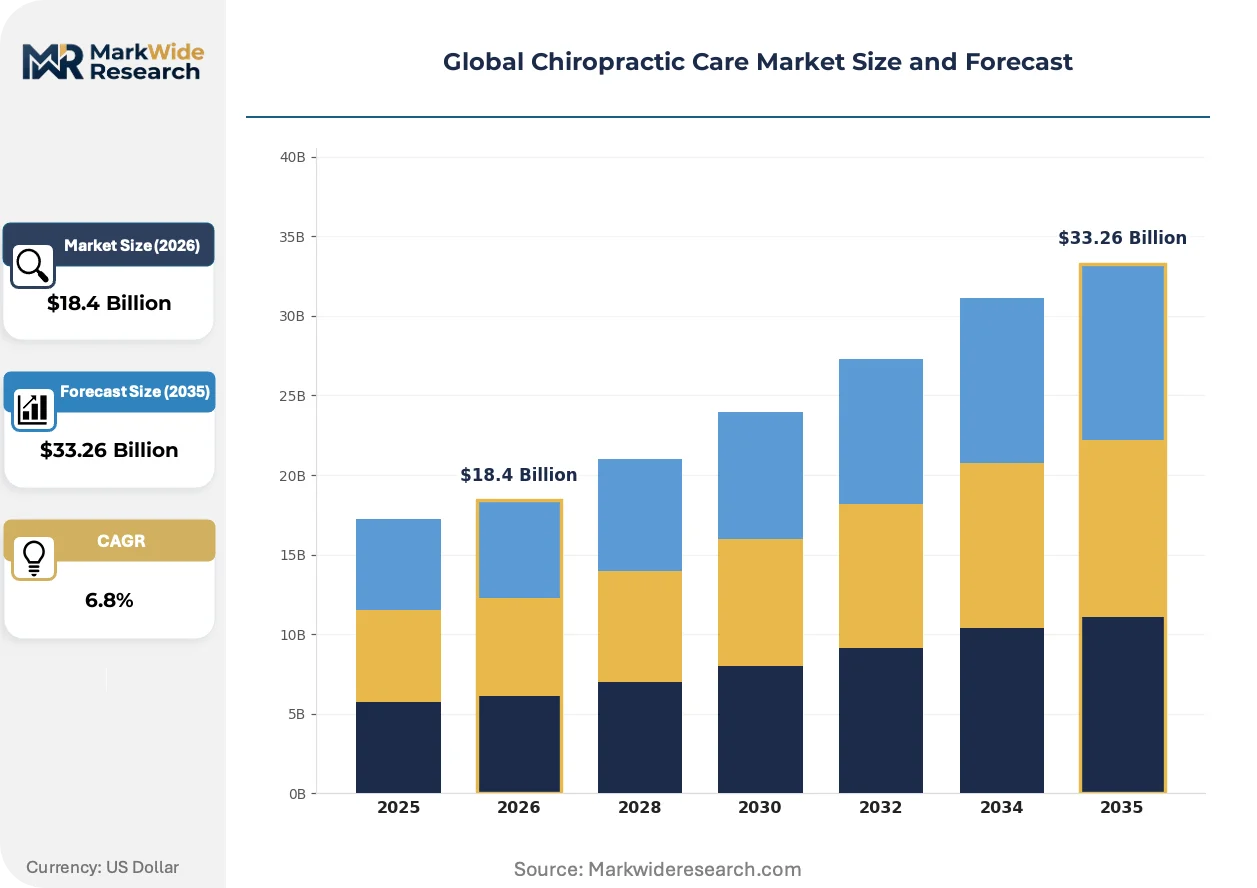
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $33.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Spinal Adjustment, Soft Tissue Therapy, Rehabilitation Exercises, Lifestyle Counseling, Posture Correction Application: Back Pain Relief, Neck Pain Management, Sports Injury Treatment, Headache Alleviation, Joint Dysfunction End User: Private Clinics, Wellness Centers, Sports Teams, Corporate Health Programs, Military Facilities Delivery Mode: In-person Sessions, Telehealth Consultations, Mobile Clinics, Group Workshops, Home Visit Services |
| Companies Covered | HealthSource Chiro, IMS Primary Care, The Joint Chiropractic, Excelsia Injury Care, Emergency Chiropractic PC, Chiro One Wellness Centers, Physicians Group Management, The Joint Corp, 100% Chiropractic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chiropractic Care Market Shifts & Advancements
Technology-enabled care delivery and regulatory clarity around device classification are compressing traditional boundaries between in-person adjustment services and remote patient management.
Computerized adjusting instruments with integrated force-feedback sensors are bifurcating the equipment market into precision-calibrated systems for metropolitan multi-site networks and simplified mechanical devices for independent rural practitioners. Suburban shopping center clinics in the United States are adopting the calibrated tier at three times the rate of solo practices. This divergence is compressing price competition at the mid-market equipment tier while expanding margin pools for integrated hardware-software bundles.
REACH chemical safety standards in Europe are extending substance restriction requirements to chiropractic table upholstery materials and cleaning protocols, elevating compliance costs for equipment manufacturers serving cross-border clinic networks. The European Medical Device Regulation's expanded definition of therapeutic purpose is capturing previously unclassified massage and traction accessories. German clinic suppliers are responding by consolidating procurement through notified body-certified distributors to streamline conformity assessment documentation.
Self-insured employers are consolidating vendor relationships through direct contracting with chiropractic network administrators, bypassing traditional insurance intermediaries. Third-party administrators in the United States are capturing patient volume allocation decisions that previously flowed through primary care physician referrals. This channel compression is most visible in Texas and Florida metropolitan corridors where large employer campus densities support dedicated on-site clinic placement economics.
Global Chiropractic Care Market Segmentation
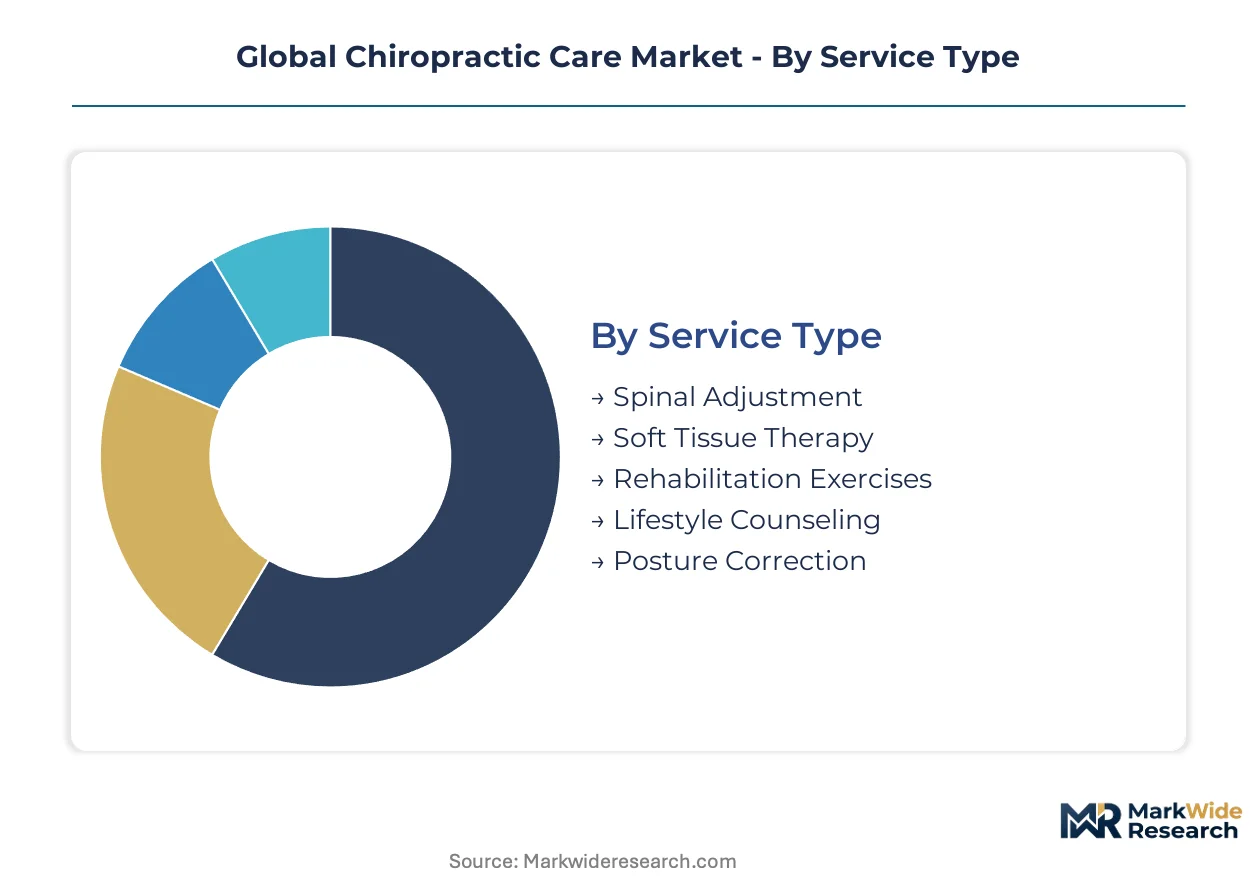
Chiropractic market segmentation reveals distinct regulatory, reimbursement, and operational profiles across service categories. Understanding these divisions enables targeted positioning for equipment suppliers, clinic operators, and employer benefit administrators.
Service Type:
FDA device classification tiers and TGA medical device pathways create divergent compliance burdens across service modalities.
- Spinal Adjustment:Manual and instrument-assisted vertebral manipulation using controlled thrust techniques with specified force ranges. Demand concentrates in United States metropolitan corridors where employer-sponsored benefit allocations expand coverage for musculoskeletal cost containment.
- Rehabilitation Exercises:Prescriptive movement protocols targeting specific motion deficits combined with durable medical equipment integration. Australian private practice networks capture concentrated margin pools through recurring session structures and equipment bundling that extends per-patient revenue cycles.
- Soft Tissue Therapy:Myofascial release and trigger point techniques complementing spinal manipulation protocols.
- Lifestyle Counseling:Integrated wellness coaching addressing ergonomic and behavioral factors.
- Posture Correction:Biomechanical assessment and corrective exercise programming for occupational health segments.
Established volume favors spinal adjustment; emerging adoption favors rehabilitation exercises.
Application:
Reimbursement pathway maturity and clinical evidence depth determine patient access economics by condition treated.
- Back Pain Relief:Lumbar and thoracic spine interventions addressing mechanical dysfunction and radicular symptoms. United States self-insured employers direct vendor consolidation toward this segment to reduce surgical intervention rates and opioid prescriptions.
- Sports Injury Treatment:Acute and overuse injury management for athletic populations requiring rapid return-to-play protocols. Australian sports medicine clinics leverage TGA regulatory clarity and private health fund rebates to sustain network expansion.
- Neck Pain Management:Cervical spine manipulation and mobilization techniques for mechanical neck disorders.
- Headache Alleviation:Cervicogenic headache protocols targeting upper cervical dysfunction.
- Joint Dysfunction:Peripheral joint manipulation for extremity mobility restoration.
Back pain relief commands the deepest reimbursement infrastructure; sports injury treatment is climbing the fastest as employer wellness programs expand athletic coverage.
End User:
Procurement authority and budget source reshape service bundling requirements across institutional buyer types.
- Corporate Health Programs:Employer-sponsored benefit allocations displacing individual out-of-pocket payment as the dominant buyer archetype. Texas and Florida metropolitan corridors support dedicated on-site clinic placement economics through large employer campus densities.
- Private Clinics:Independent practitioner-owned facilities serving fee-for-service and insurance-reimbursed patients. Australian private health insurance rebate variability across states creates patient access disparities that constrain network standardization.
- Wellness Centers:Integrated health facilities combining chiropractic with complementary services.
- Sports Teams:Professional and collegiate athletic organization medical staff contracts.
- Military Facilities:Government healthcare systems serving active duty and veteran populations.
Corporate health programs are gaining share fastest; private clinics retain the broadest geographic footprint.
Delivery Mode:
Technology infrastructure investment and regulatory scope-of-practice boundaries determine channel economics.
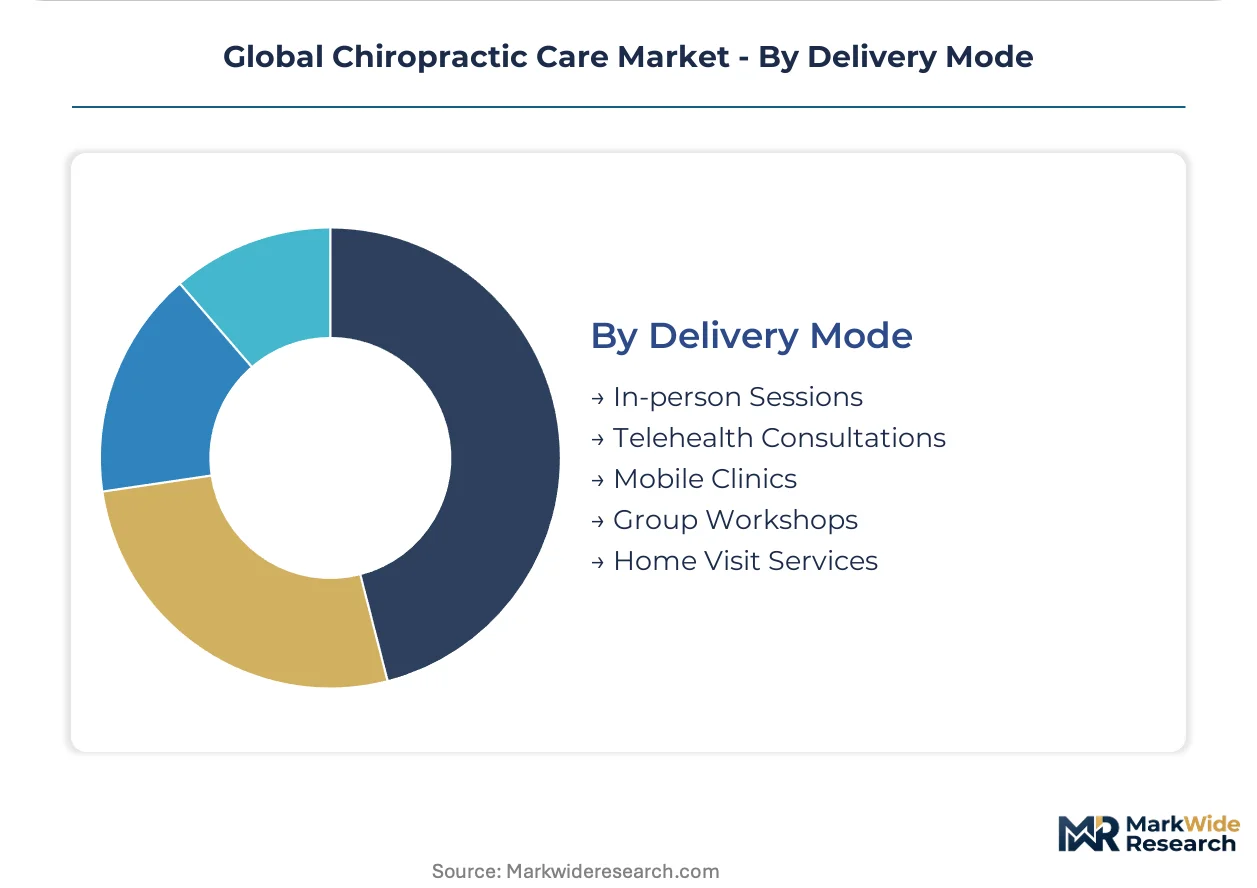
- Telehealth Consultations:Remote diagnostic platforms paired with exercise supervision protocols extending beyond traditional geographic clinic catchments. Remote motion analysis tools gain clinical acceptance fastest where physical therapy substitution pressures intensify.
- In-person Sessions:Traditional clinic-based manual and instrument-assisted adjustment services. Suburban shopping center clinics in the United States adopt computerized adjusting instruments with force-feedback sensors at three times the rate of solo practices.
- Mobile Clinics:Transportable equipment configurations serving remote or event-based populations.
- Group Workshops:Educational and preventive care delivery in corporate or community settings.
- Home Visit Services:Direct-to-patient delivery for mobility-limited or high-priority cases.
In-person sessions anchor current revenue; telehealth consultations show the steepest expansion trajectory as remote diagnostic tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian equipment manufacturers export computerized adjusting instruments to United States metropolitan clinic networks, establishing the primary trade-flow corridor in this medical device segment.
United States
Self-insured employers in Texas and Florida metropolitan corridors drive demand for on-site corporate clinic placement. FDA Class II device quality system requirements filter equipment suppliers and elevate capital costs for independent practitioners. The Joint Corp operates membership-based retail clinics across suburban shopping centers in these states.
Australia
Private health insurance rebates sustain clinic network expansion in New South Wales and Victoria. TGA regulatory clarity on medical device classification reduces market entry friction for chiropractic instrument suppliers. Sydney and Melbourne anchor the highest concentration of multi-site practice networks benefiting from rebate standardization.
Germany
REACH chemical safety standards extend substance restrictions to chiropractic table upholstery and cleaning protocols. The European Medical Device Regulation's expanded therapeutic purpose definition captures previously unclassified massage and traction accessories. German clinic suppliers consolidate procurement through notified body-certified distributors to streamline conformity documentation.
Canada
Provincial health plan variability creates reimbursement fragmentation across Ontario, British Columbia, and Alberta. Health Canada medical device licensing requirements parallel FDA structures but with streamlined Class I pathways for manual instruments. Toronto and Vancouver concentrate the largest private practice networks serving employer-sponsored benefit plans.
United Kingdom
NHS commissioning groups pilot musculoskeletal pathway integration with chiropractic services in selected clinical commissioning groups. MHRA medical device registration requirements align with post-Brexit UKCA marking standards. London and Southeast England concentrate corporate wellness program adoption among financial services employers.
Global Chiropractic Care Market Competitive Landscape
Listed leaders compete with private specialists across capital access and geographic scale dimensions. The vendor base fragments across independent practitioner-owned clinics, franchise-network operators, and integrated wellness platforms. Three strategic archetypes dominate: membership-based retail models, multi-site network administrators, and integrated wellness protocols. M&A activity concentrates in suburban United States markets while technology licensing partnerships proliferate around telehealth diagnostic platforms.
Within the franchise-network tier, The Joint Corp and The Joint Chiropractic exemplify membership-based retail positioning across United States suburban corridors. HealthSource Chiro anchors integrated wellness protocol development combining spinal adjustment with lifestyle counseling. Chiro One Wellness Centers occupies a position representing multi-site network administration with centralized infrastructure in metropolitan markets. These three entities collectively illustrate the strategic divergence between high-throughput retail formats and clinically integrated service bundles.
| Leading Market Players |
|---|
| HealthSource Chiro |
| IMS Primary Care |
| The Joint Chiropractic |
| Excelsia Injury Care |
| Emergency Chiropractic PC |
| Chiro One Wellness Centers |
| Physicians Group Management |
| The Joint Corp |
| 100% Chiropractic |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for FDA Class II certified adjusting instruments from Australian manufacturers compress pricing power for independent practitioners while amplifying margin capture for multi-site networks with forward inventory positions. This inventory concentration dynamic bifurcates procurement economics between high-volume corporate clinic chains and solo practices.
Pricing Analysis
Next-generation computerized adjusting instruments with force-feedback sensors command premium positioning against prior-generation mechanical devices and entry-level manual tables. Three-tier pricing structure across precision-calibrated, standard mechanical, and economy manual levels reflects FDA certification tier and software integration depth. Cost compression in the standard tier intensifies as suburban shopping center clinics consolidate procurement volume. Corporate health program buyers exhibit lowest price sensitivity due to bundled employer contracts, while independent rural practitioners face acute budget constraints.
Supply Chain Analysis
Australia and the United States anchor manufacturing for computerized adjusting instruments and rehabilitation equipment respectively. Supply chains draw from Taiwanese sensor components, German precision motors, and Chinese steel framing. Single-source vulnerability concentrates in force-feedback sensor modules where two suppliers dominate global capacity. Distribution runs through notified body-certified medical device distributors in Europe and direct-to-clinic relationships in North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across reimbursement pathways and delivery modalities creates niche positioning opportunities for specialists targeting underserved corporate and telehealth segments.
For Market Incumbents: Secure multi-site network density in Texas and Florida metropolitan corridors before physical therapy scope-of-practice expansions capture employer contract volumes. Consolidate backward integration into rehabilitation equipment manufacturing to defend margin structures against durable medical device bundling competitors. Channel control through direct corporate contracting relationships represents the critical defensive lever. For New Entrants and Emerging Players: Lead with telehealth diagnostic platforms targeting Australian private health insurance gaps where rebate variability across states creates patient access friction. Corporate on-site clinic placement in underpenetrated suburban United States office parks offers the most penetrable white space. Go-to-market execution should emphasize outcome-based musculoskeletal cost containment metrics for self-insured employer procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because reimbursement standardization and technology-enabled care delivery will compress independent practice economics toward network participation. Acquisition targets should cluster around multi-site clinic administrators with centralized infrastructure and established corporate contract portfolios. Watch telehealth reimbursement policy clarity as the primary inflection signal for capital redeployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | Aligns clinic network participation with evolving TGA and private health fund rebate pathways in Australia. |
| Hospital System Partnership | Integrates chiropractic services into musculoskeletal care pathways within United States integrated delivery networks. |
| Software Companion Development | Enables remote motion analysis and exercise supervision protocols for telehealth consultation expansion. |
| FDA Submission Pathway | Secures Class II medical device clearance for next-generation instrument-assisted adjustment technology. |
| CE Marking Pathway | Facilitates European market entry under MDR expanded therapeutic purpose definitions for traction accessories. |
Research Methodology
Cross-validation between primary clinician interviews and secondary regulatory filings anchors the qualitative findings in this analysis. The research combined structured discussions with chiropractic college administrators, multi-site clinic network operators, biomedical equipment procurement managers, and employer benefits directors alongside validation against FDA 510(k) databases, TGA medical device registers, Australian private health fund rebate schedules, and United States self-insured employer plan documents. Bottom-up clinic capacity modeling and top-down healthcare expenditure allocation triangulate volume estimates.
Sensitivity analysis around reimbursement policy scenarios and technology adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions include service modality, application condition, end-user procurement authority, and delivery mode technology infrastructure. CAGRs derive from patient volume trajectory modeling, per-visit revenue cycle analysis, and equipment replacement cycle patterns. Forecast inputs incorporate employer musculoskeletal benefit allocation trends and instrument-assisted adjustment technology penetration curves.
Forecasts assume regulatory continuity in FDA Class II device quality systems and TGA medical device classification pathways; material policy shifts would require re-modeling. Specific risks include physical therapy scope-of-practice expansions, telehealth reimbursement reversals, and REACH chemical safety standard extensions to equipment materials. Recalibration cycles align with material shifts in employer benefit design and regulatory clarity events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Chronic Lower Back Pain Treatment Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Migraine Management Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Pain Relief Oil Market
Pain Management
Pain Management Software Market
Pain Management
Palliative Care Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Topical Pain Relief Market
Pain Management
Painkillers Market
Pain Management
Ketorolac Market
Pain Management
Medical Morphine Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Muscle Tension Dysphonia Treatment Market