
 Pain Therapeutic Solutions Market | 2026-2036
Pain Therapeutic Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Therapeutic Solutions Market Analytics
Modular pain management kits that combine pharmacologic and non-pharmacologic components is broadening buyer choice across hospital procurement channels. Pfizer Inc. leverages its scale in analgesic manufacturing to anchor contracts with large health systems. Boston Scientific Corporation competes through its interventional pain device portfolio, while Medtronic specializes in neuromodulation systems for refractory chronic conditions.
Pain therapeutic solutions encompass pharmaceutical agents, medical devices, and integrated care protocols engineered to interrupt nociceptive signaling, modulate neural transmission, or alter pain perception through receptor-specific binding or electrical stimulation at defined frequency parameters. These interventions serve clinical and homecare settings where sustained functional improvement and reduced opioid exposure represent core therapeutic objectives. Analgesics still occupy the largest share of the product type landscape, though transdermal delivery modes are gaining share as clinicians prioritize steady-state plasma concentrations and improved patient compliance. Cancer pain within the therapy area dimension commands premium pricing due to complex co-morbidity management requirements.
The FDA maintains stringent REMS requirements for opioid analgesics, while the EMA's pharmacovigilance frameworks shape product labeling and post-market surveillance obligations across European markets. ISO 13485 certification governs quality management for device manufacturers, directly affecting market access timelines and competitive positioning. Stakeholders must monitor evolving reimbursement criteria for non-opioid alternatives and interventional procedures as payors recalibrate coverage policies.
Market Dynamics
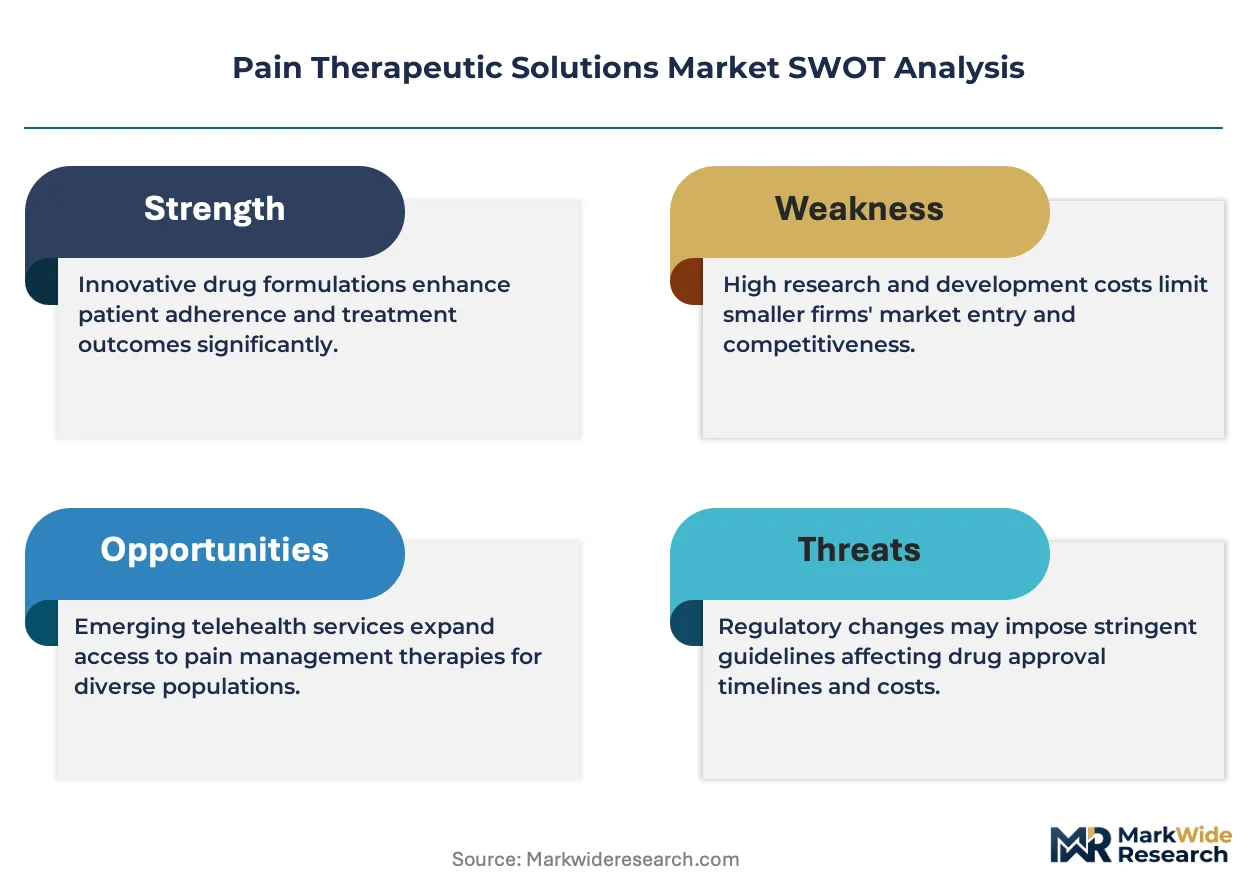
Hospital procurement departments now mandate bundled contracts that combine pharmaceutical and device-based pain therapies, forcing manufacturers to restructure their commercial organizations around integrated delivery networks rather than discrete product lines.
Growth Catalysts
- FDA Risk Evaluation and Mitigation Strategy:Extended-release opioid prescribing restrictions are redirecting clinical demand toward neuromodulation devices and non-opioid analgesics.
- Integrated Delivery Networks:Large health systems in the United States negotiate volume-based contracts that favor suppliers with full-spectrum portfolios spanning pharmacologic and interventional modalities.
- Transdermal Delivery Systems:Steady-state plasma concentration profiles are displacing immediate-release oral formulations in chronic pain management protocols.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of specialized opioid antagonists and extended-release matrices depends on a limited base of contract manufacturers concentrated in India and China.
- Device Quality Certification Timeline:ISO 13485 compliance cycles extend market access timelines by 18-24 months for neuromodulation system entrants.
- Reimbursement Compression:Medicare's parallel review process for breakthrough device designation creates uncertainty in pricing negotiations for spinal cord stimulators.
Strategic Opportunities
- Home-Based Pain Management:Portable transcutaneous electrical nerve stimulation units address the shift toward ambulatory care settings in Germany and the United Kingdom.
- EMA Pharmacovigilance Frameworks:Post-market surveillance obligations for novel analgesics create first-mover advantages for manufacturers with established risk management infrastructure.
- Cancer Pain Protocols:Complex co-morbidity management requirements in oncology centers support premium positioning for multimodal combination therapies.
Industry Challenges
- Interventional Pain Specialist Pipeline:Fellowship training programs produce insufficient proceduralists to support projected demand for implantable neuromodulation devices.
- Legacy EHR Integration:Device manufacturers must engineer proprietary data streams into hospital information systems that lack standardized APIs for therapeutic monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Therapeutic Solutions Market |
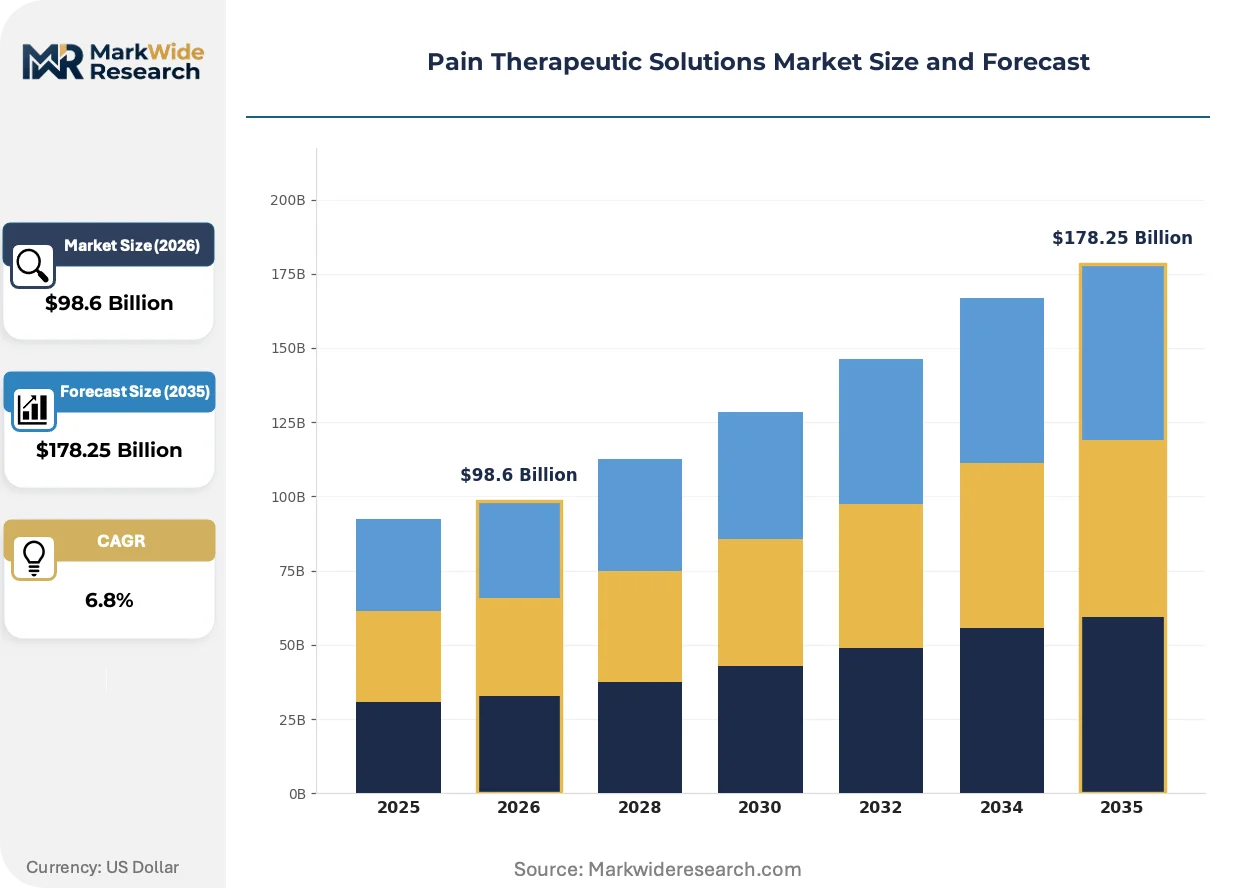
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Topical Agents Therapy Area: Chronic Pain, Neuropathic Pain, Acute Pain, Cancer Pain Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Pfizer Inc., Boston Scientific Corporation, Sanofi S.A., Johnson & Johnson Services, Inc., Abbott Laboratories, Novartis AG, Teva Pharmaceutical Industries Ltd., Medtronic, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Therapeutic Solutions Market Evolving Landscape
Digital therapeutic platforms are embedding closed-loop algorithms into neuromodulation hardware, creating real-time adaptive dosing that responds to patient-reported outcomes and biometric feedback.
Closed-loop spinal cord stimulation systems are consolidating market share among refractory chronic pain populations. Academic medical centers in the United States are adopting these platforms at accelerating rates. The technology is consolidating the competitive landscape by raising technical barriers for device manufacturers without embedded software capabilities.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for pain management hardware. Manufacturers must generate prospective data on long-term safety outcomes to maintain CE marking. High-risk device categories including implantable pulse generators face extended notified body review timelines.
Integrated delivery networks are unbundling pharmaceutical and device procurement functions that previously operated as separate cost centers. Hospital supply chain executives now negotiate enterprise-wide contracts that span analgesic formularies and interventional equipment. This consolidation is most visible in the United States, where systems like Kaiser Permanente and Intermountain Healthcare have centralized therapeutic sourcing decisions.
Pain Therapeutic Solutions Market Segmentation
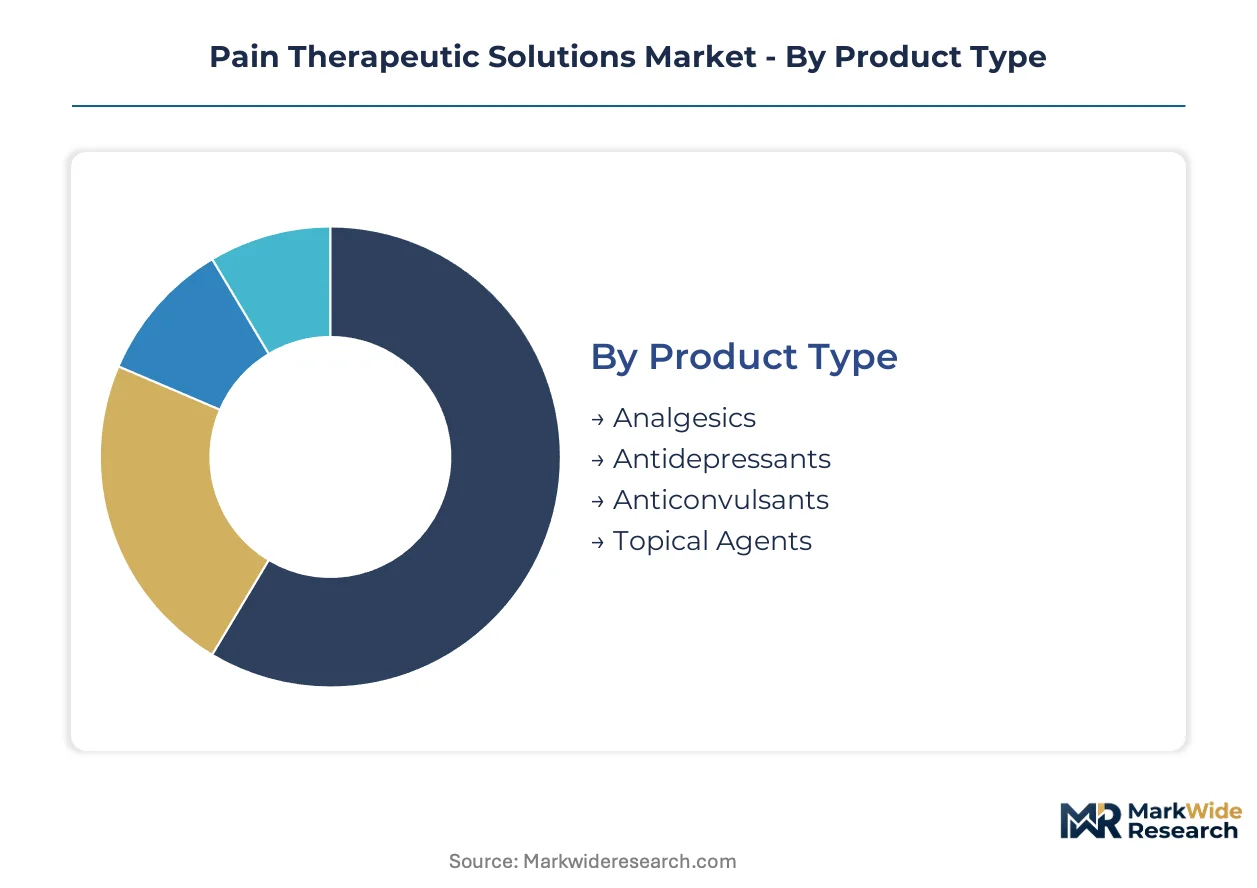
Segmentation in pain therapeutics reveals divergent margin structures across pharmacologic and interventional modalities. Procurement officers at integrated delivery networks use these categories to structure tiered formulary access and bundled contracting strategies.
Product Type:
Analgesics dominate prescription volume while antidepressants and anticonvulsants capture premium positioning in neuropathic indications.
- Analgesics:Opioid and non-opioid formulations targeting nociceptive pathways remain the foundational pharmacologic intervention across emergency departments and surgical wards. Demand concentrates in United States hospital systems where FDA REMS protocols restrict extended-release opioid prescribing, redirecting volume toward immediate-release and combination products.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors and tricyclic compounds modulate descending inhibitory pain pathways in chronic centralized pain states. Germany's statutory health insurance funds now reimburse duloxetine and milnacipran for fibromyalgia without prior authorization, accelerating category uptake.
- Anticonvulsants:Gabapentinoids and sodium channel blockers stabilize hyperexcitable neuronal membranes in peripheral neuropathy.
- Topical Agents:Local anesthetic and capsaicin formulations deliver site-specific analgesia with minimal systemic exposure.
Mature deployment sits with analgesics in acute surgical settings. Newer deployment is concentrated in topical agents for ambulatory chronic pain protocols.
Therapy Area:
Application-driven segmentation aligns reimbursement codes with clinical outcome metrics and episode-based payment models.
- Chronic Pain:Persistent pain states lasting beyond tissue healing timeframes require multimodal management spanning pharmacologic, interventional, and rehabilitative disciplines. Medicare Advantage plans in the United States increasingly impose step-therapy requirements that mandate non-opioid trials before prior authorization for Schedule II analgesics.
- Cancer Pain:Tumor-related nociception and treatment-induced neuropathy demand aggressive titration protocols and breakthrough dose flexibility. Oncology centers in the United Kingdom negotiate directly with manufacturers for patient access schemes that bundle strong opioids with antiemetics and laxatives.
- Neuropathic Pain:Lesion or disease of the somatosensory nervous system produces dysesthetic symptoms poorly responsive to conventional analgesia.
- Acute Pain:Postoperative and trauma-related pain episodes drive hospital formulary decisions and discharge prescribing patterns.
Revenue concentration favors cancer pain due to premium pricing and complex co-morbidity management. Volume expansion is climbing the fastest in chronic pain as ambulatory care protocols extend treatment duration.
Delivery Mode:
Route of administration determines pharmacokinetic profiles, compliance rates, and manufacturing complexity for contract development organizations.
- Oral:Immediate-release and extended-release tablets and capsules constitute the default prescribing pattern across primary care and specialist settings. Kaiser Permanente's centralized pharmacy operations in California have driven generic substitution rates above ninety percent for immediate-release opioid formulations.
- Transdermal:Matrix and reservoir patches maintain steady-state plasma concentrations over seventy-two-hour intervals, improving adherence in elderly populations with swallowing difficulties. The United Kingdom's National Institute for Health and Care Excellence recommends fentanyl patches as second-line therapy for opioid-tolerant chronic pain patients.
- Injectable:Intravenous and intramuscular formulations serve perioperative and emergency department protocols where rapid onset is clinically essential.
- Intranasal:Mucosal absorption bypasses first-pass hepatic metabolism for rapid systemic delivery in breakthrough pain episodes.
Injectable formulations anchor hospital-based acute pain management. Transdermal systems are gaining share fastest in homecare transitions and palliative care settings.
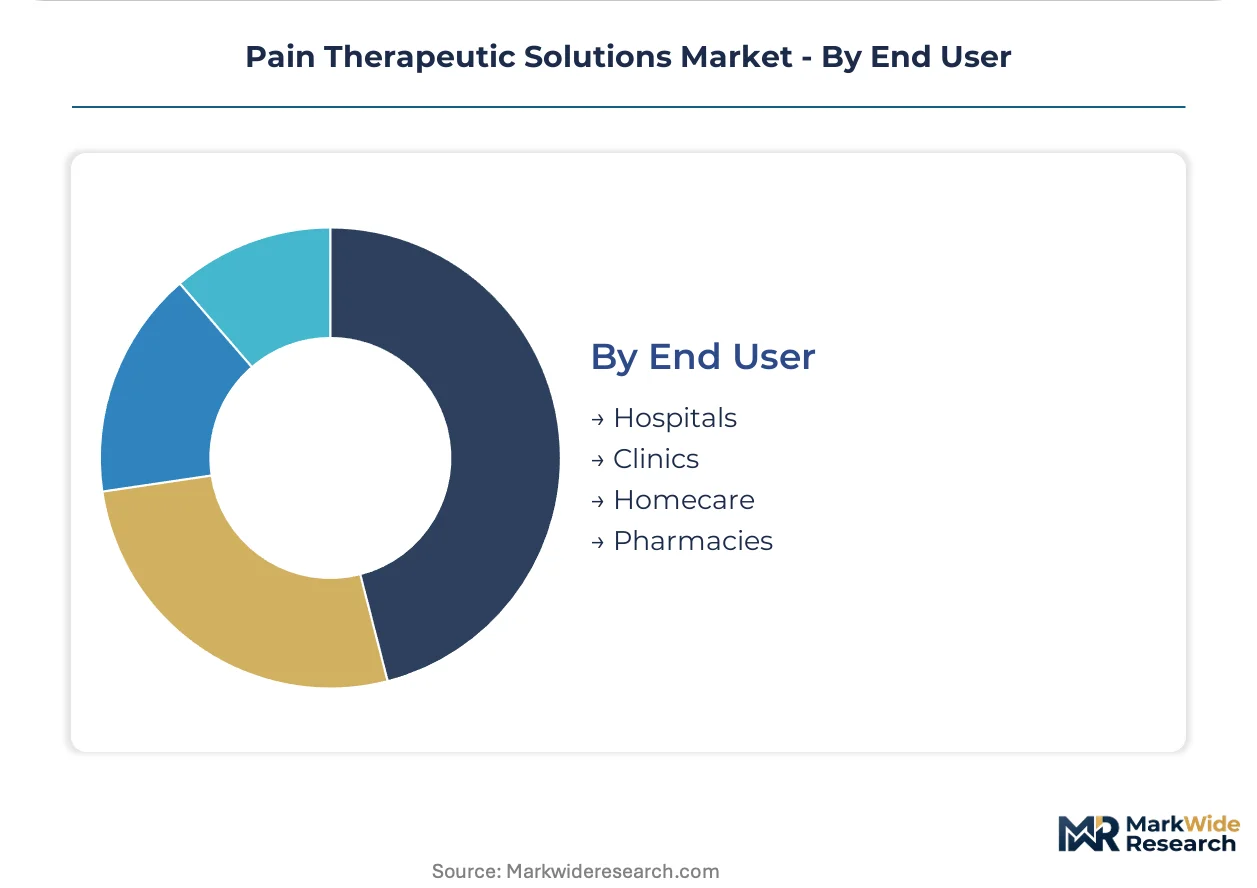
End User:
Channel segmentation determines packaging specifications, cold chain requirements, and direct-to-patient service models.
- Hospitals:Inpatient and surgical facilities negotiate enterprise contracts covering formulary placement, pharmacy dispensing, and interventional procedure suites. Intermountain Healthcare's consolidated supply chain in Utah sources analgesics and neuromodulation devices through a single procurement function.
- Homecare:Skilled nursing and hospice agencies manage complex analgesic titration and infusion pump delivery in residential settings. Germany's regional care associations have expanded reimbursement for home-based patient-controlled analgesia following total joint replacement.
- Clinics:Ambulatory pain management and infusion centers specialize in interventional procedures and parenteral administration.
- Pharmacies:Retail and specialty pharmacy channels handle outpatient prescription fulfillment and adherence monitoring programs.
Contracting sophistication is most advanced in hospitals with centralized procurement functions. Homecare channels are expanding most quickly as payors shift financial risk toward post-acute settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters in Ireland and Switzerland export neuromodulation hardware to hospital systems in the United States and Germany. Consumption concentrates in North American and Western European markets where integrated delivery networks negotiate bundled contracts for pharmaceutical and interventional pain therapies.
United States
Medicare Advantage plans impose step-therapy requirements that mandate non-opioid trials before prior authorization for Schedule II analgesics. The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids continues to reshape prescribing patterns across hospital systems. Kaiser Permanente in California has centralized pharmaceutical and device procurement through a single supply chain function.
Germany
Statutory health insurance funds now reimburse duloxetine and milnacipran for fibromyalgia without prior authorization, accelerating uptake of antidepressant-class analgesics. The country's national pharmaceutical regulator enforces pharmacovigilance frameworks that shape post-market surveillance obligations for novel analgesics. Regional care associations in Bavaria have expanded reimbursement for home-based patient-controlled analgesia following total joint replacement.
United Kingdom
The National Institute for Health and Care Excellence recommends fentanyl patches as second-line therapy for opioid-tolerant chronic pain patients, driving transdermal system adoption. NHS England negotiates directly with manufacturers for patient access schemes that bundle strong opioids with antiemetics and laxatives. Oncology centers in London and Manchester command premium pricing for complex cancer pain protocols.
Switzerland
Swissmedic maintains stringent quality certification timelines that extend market access for neuromodulation system entrants by 18-24 months. The country's medical device regulation aligns with EU MDR requirements for prospective clinical evidence on long-term safety outcomes. Basel and Zurich host manufacturing operations for implantable pulse generators serving European hospital networks.
Japan
PMDA approval pathways for breakthrough pain devices create uncertainty in pricing negotiations for spinal cord stimulators. METI industrial policy supports domestic production of portable transcutaneous electrical nerve stimulation units for homecare transitions. Tokyo and Osaka medical centers adopt closed-loop spinal cord stimulation systems at accelerating rates for refractory chronic pain populations.
Pain Therapeutic Solutions Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with full-spectrum portfolios spanning analgesic manufacturing and device distribution. Tiered positioning separates scale-driven drug manufacturers from interventional device specialists and emerging digital therapeutic platforms. Dominant competitive moves include portfolio diversification into neuromodulation hardware and strategic partnerships with integrated delivery networks for bundled contract access.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson Services, Inc. occupy positions that exemplify scale-driven archetypes with formulary anchoring capabilities. Boston Scientific Corporation and Medtronic represent the device-specialist tier, with the former competing through interventional pain portfolios and the latter specializing in neuromodulation systems for refractory conditions. Sanofi S.A. and Novartis AG sit within the European-origin pharmaceutical tier, while Abbott Laboratories and Eli Lilly and Company exemplify diversified health science conglomerates with pain therapeutic exposure.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Boston Scientific Corporation |
| Sanofi S.A. |
| Johnson & Johnson Services, Inc. |
| Abbott Laboratories |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Medtronic |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Opioid API spot prices in India and China cascade through contract manufacturing tiers into three distinct pricing bands for finished analgesic formulations. Hospital procurement officers exploit this concentration by negotiating volume commitments that compress margins for non-integrated suppliers while rewarding manufacturers with captive active pharmaceutical ingredient production.
Pricing Analysis
Margin tightening in neuromodulation devices reflects extended ISO 13485 certification timelines that defer revenue recognition by eighteen to twenty-four months. Three-tier pricing structure across premium closed-loop systems, standard programmable generators, and economy fixed-output devices separates reimbursement-eligible tiers from cash-pay segments. Cost-down pressure on transdermal patches accelerates because Kaiser Permanente and Intermountain Healthcare have centralized generic substitution rates above ninety percent for immediate-release oral formulations. Oncology centers exhibit the lowest price sensitivity due to bundled patient access schemes, while ambulatory clinics face the highest sensitivity as Medicare Advantage step-therapy requirements mandate non-opioid trials first.
Supply Chain Analysis
Freight cost volatility for temperature-controlled shipments of extended-release matrices has prompted manufacturers to regionalize final formulation steps. Active pharmaceutical ingredient synthesis concentrates in India and China, with implantable pulse generator assembly anchored in Ireland and Switzerland. Raw material dependencies include specialized opioid antagonists, biocompatible polymers for reservoir patches, and lithium-ion cells for rechargeable neurostimulators. Single-source vulnerability persists for fentanyl citrate precursors subject to export licensing restrictions. Distribution runs through integrated delivery network consolidated procurement functions rather than discrete pharmaceutical and device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA REMS compliance bottlenecks for extended-release opioids prop pricing power for manufacturers with established risk evaluation infrastructure. Active pharmaceutical ingredient capacity constraints in India limit supply elasticity, sustaining premium positioning for vertically integrated players.
For Market Incumbents: Cement formulary anchoring through backward integration into active pharmaceutical ingredient production, particularly for extended-release matrices where contract manufacturer concentration creates vulnerability. Expand neuromodulation device portfolios with embedded closed-loop software capabilities to raise technical barriers against emerging digital therapeutic platforms. Prioritize ISO 13485 certification maintenance in Swissmedic and notified body jurisdictions to defend eighteen-to-twenty-four month market access timelines. For New Entrants and Emerging Players: Capture home-based pain management white space in Germany and the United Kingdom where regional care associations have expanded reimbursement for patient-controlled analgesia following total joint replacement. Target portable transcutaneous electrical nerve stimulation units for ambulatory care transitions, the fastest-expanding channel as payors shift financial risk toward post-acute settings. Pursue direct-to-hospital contracting outside integrated delivery network consolidated procurement functions to avoid volume-based discount requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor neuromodulation device specialists with FDA breakthrough device designation progress but stalled Medicare parallel review negotiations in the United States. Long-term viability over the next decade hinges on software-enabled adaptive dosing platforms that consolidate refractory chronic pain market share. Monitor EMA pharmacovigilance framework implementation timelines as the inflection signal for first-mover advantage in post-market surveillance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Intermountain Healthcare's consolidated supply chain in Utah sources analgesics and neuromodulation devices through a single procurement function. |
| FDA Submission | Breakthrough device designation for closed-loop spinal cord stimulators triggers Medicare parallel review uncertainty affecting pricing negotiations. |
| CE Marking Pathway | EU MDR requirements for prospective long-term safety data extend notified body review timelines for implantable pulse generators. |
| Software Companion Development | Closed-loop algorithms embedding patient-reported outcomes and biometric feedback consolidate competitive position among academic medical centers. |
| Reimbursement Strategy | Germany's statutory health insurance funds now reimburse duloxetine and milnacipran for fibromyalgia without prior authorization. |
Research Methodology
FDA REMS documentation, EMA pharmacovigilance filings, and ClinicalTrials.gov registry data formed the secondary backbone for therapeutic protocol and regulatory trajectory assessment. Primary interviews with hospital procurement managers, formulary directors, interventional pain specialists, and payer access specialists validated prescribing pattern shifts and bundled contracting structures. Bottom-up patient volume estimates by therapy area and delivery mode were triangulated against top-down pharmaceutical and device revenue benchmarks.
Historical trendline analysis across analgesic prescription volumes, neuromodulation implant procedures, and transdermal patch shipments established baseline growth trajectories. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user channel, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth rates adjusted for FDA REMS implementation effects and integrated delivery network consolidation timing. Forecast inputs incorporated Medicare Advantage step-therapy penetration rates and EU MDR notified body capacity constraints.
The model holds under stable FDA REMS enforcement and continued integrated delivery network procurement consolidation; deviation in opioid litigation settlements or EMA pharmacovigilance framework acceleration would shift volume projections toward non-opioid alternatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Ketorolac Market
Pain Management
Migraine Management Market
Pain Management
Arthralgia Management Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
OTC Painkiller Market
Pain Management
Cancer Pain Management Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Chronic Pain Market
Pain Management
Global Morphine Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Heat Therapy Market