
 Neurological Biomarkers Market | 2026-2036
Neurological Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Neurological Biomarkers Market Intelligence
Capital-intensity divergence between integrated diagnostic platforms and point-of-care assay developers is reorganizing competitive boundaries in neurological biomarker supply. Thermo Fisher Scientific leverages its genomic sequencing infrastructure to anchor high-throughput biomarker discovery workflows. Quanterix sustains ultra-sensitive detection capabilities that differentiate its position in blood-based neurodegenerative screening.
Neurological biomarkers comprise quantifiable biological indicators—proteins, metabolites, genetic variants, or imaging signatures—detectable in blood, cerebrospinal fluid, or neural tissue that reflect pathophysiological states of the central nervous system. These indicators typically require analytical sensitivity thresholds in the femtomolar-to-picomolar range for blood-based neurodegenerative applications, serving primarily to enable early disease detection, patient stratification, and therapy response monitoring in conditions where clinical symptoms lag biological onset by years. Blood-based biomarkers command expanding clinical adoption due to non-invasive collection logistics, while imaging biomarkers retain premium reimbursement in dementia diagnosis where spatial resolution requirements remain irreducible. CSF biomarkers occupy a narrowing but defended niche in Alzheimer's screening confirmation protocols where analytical specificity thresholds exceed peripheral blood capabilities.
FDA's breakthrough device designation framework and EMA's in-vitro diagnostic regulation shape market access timelines and analytical validation requirements for neurological biomarker assays. The EU AI Act introduces additional conformity obligations for algorithm-driven imaging biomarker interpretation tools entering European clinical deployment. Stakeholders must monitor evolving harmonization between FDA and EMA biomarker qualification pathways to anticipate parallel submission strategies and avoid jurisdiction-specific validation redundancies.
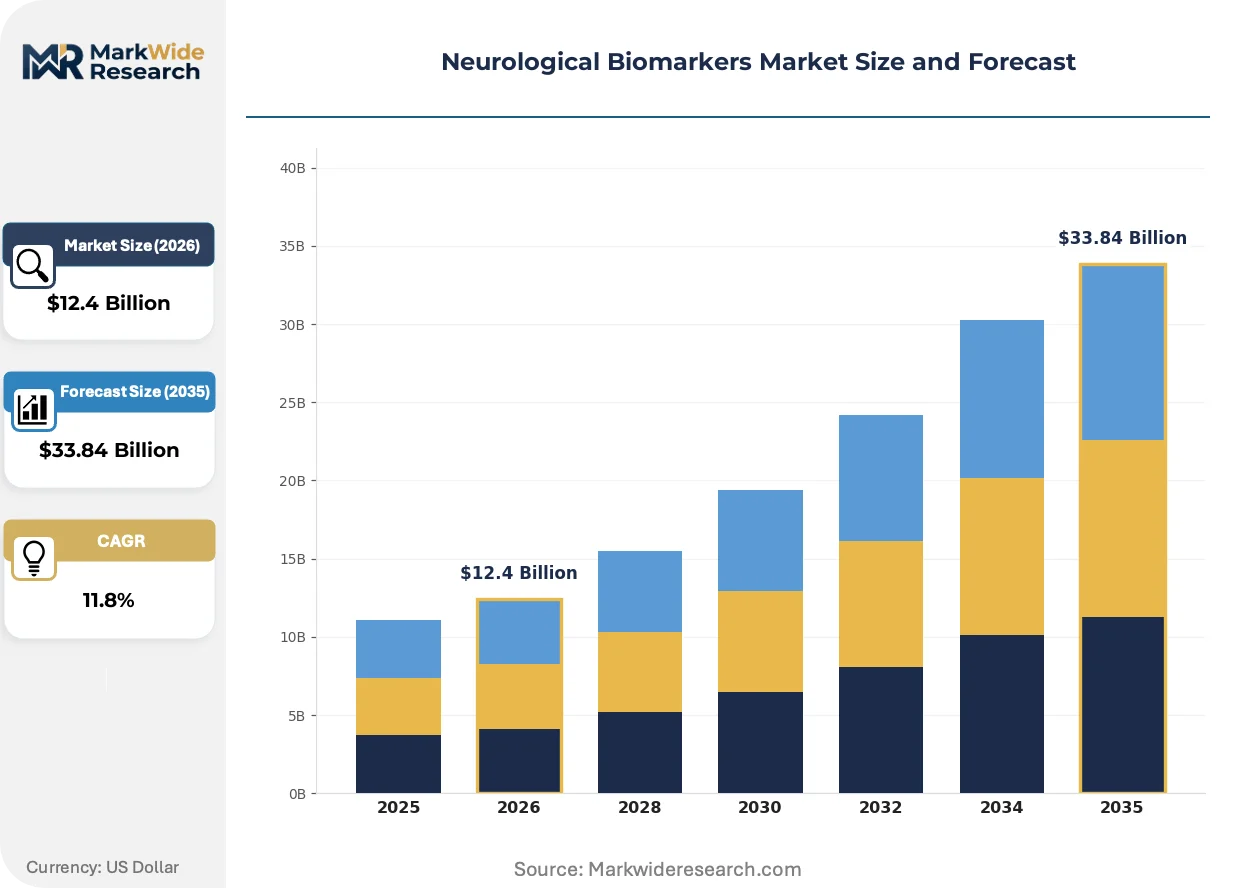
Market Dynamics
FDA breakthrough device designations and EMA parallel biomarker qualification pathways are compressing development timelines and forcing assay developers to build dual-validation capabilities from inception rather than retrofitting for second markets.
Growth Catalysts
- Blood-based assay validation:Analytical sensitivity advances in femtomolar-range protein detection are opening population-scale screening for Alzheimer's and Parkinson's disease progression.
- Companion diagnostic mandates:FDA's accelerated approval framework increasingly requires biomarker-stratified enrollment, embedding assay demand into neurology drug development pipelines.
- Aging demographic concentration:Japan, Germany, and the United States exhibit concentrated demand for early neurodegenerative detection as median population age advances.
Market Restraints
- CSF collection infrastructure:Lumbar puncture requirements and specialized collection logistics limit biomarker confirmation testing to tertiary hospital networks.
- Reimbursement fragmentation:Medicare coverage determinations for blood-based neurodegenerative biomarkers remain jurisdiction-variable across US administrative regions.
- Analytical specificity thresholds:Peripheral blood matrix interference exceeds CSF capabilities for certain tau isoform quantifications, constraining assay migration.
Strategic Opportunities
- Point-of-care deployment:Ultra-sensitive single-molecule array platforms enable decentralized testing in neurology clinics and memory care centers.
- EU AI Act alignment:Algorithm-driven imaging biomarker interpretation tools face new conformity obligations, creating first-mover advantage for validated systems.
- Pharmaceutical integration:Biomarker-integrated trial designs allow patient stratification and response monitoring, embedding assay demand into drug development contracts.
Industry Challenges
- Cross-platform standardization:Inter-laboratory variability in immunoassay calibration complicates multi-site clinical trial data pooling.
- Specialized technical workforce:Femtomolar-range assay development requires rare combinations of neurobiology and analytical chemistry expertise.
- Legacy LIMS integration:Hospital laboratory information systems require substantial modification to accommodate novel biomarker reporting workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurological Biomarkers Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.84 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood-Based Biomarkers, Imaging Biomarkers, CSF Biomarkers, Genetic Biomarkers Application: Dementia Diagnosis, Alzheimer's Screening, Parkinson's Disease Management, Stroke Assessment Technology: Immunoassays, Genomic Sequencing, Magnetic Resonance Imaging, Biomarker Discovery Platforms End User: Research Institutions, Hospitals, Diagnostic Laboratories, Pharmaceutical Companies |
| Companies Covered | Abbott, Thermo Fisher Scientific, Qiagen, Merck KGaA, Bio-Rad Laboratories, Johnson & Johnson, Quanterix, Banyan Biomarkers, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurological Biomarkers Market Strategic Shifts & Innovations
Neurological biomarker platforms are diverging between centralized high-throughput discovery infrastructure and distributed point-of-care detection, with each trajectory demanding distinct technical capabilities and commercial models.
Simoa technology is bifurcating the neurodegenerative screening landscape. Single-molecule array platforms achieve sub-picomolar detection of phosphorylated tau and neurofilament light chain in peripheral blood. Academic medical centers and pharmaceutical sponsors are adopting these systems for early-stage patient identification. The technology is bifurcating market structure between centralized reference laboratories and instrument placements in neurology practices.
EMA's in-vitro diagnostic regulation and the EU AI Act are imposing layered conformity obligations on imaging biomarker software. Algorithm-driven quantification of amyloid PET and MRI volumetrics now requires dual technical documentation for clinical safety and machine learning transparency. European radiology networks are consolidating vendor relationships to manage validation costs, favoring integrated platform providers over specialized software developers.
Hospital procurement committees are unbundling biomarker testing from bundled neurology service contracts. Separate assay pricing and performance benchmarking now govern contract renewals at major US health systems. This shift compresses vendor margins while elevating analytical performance specifications as primary selection criteria.
Neurological Biomarkers Market Segmentation
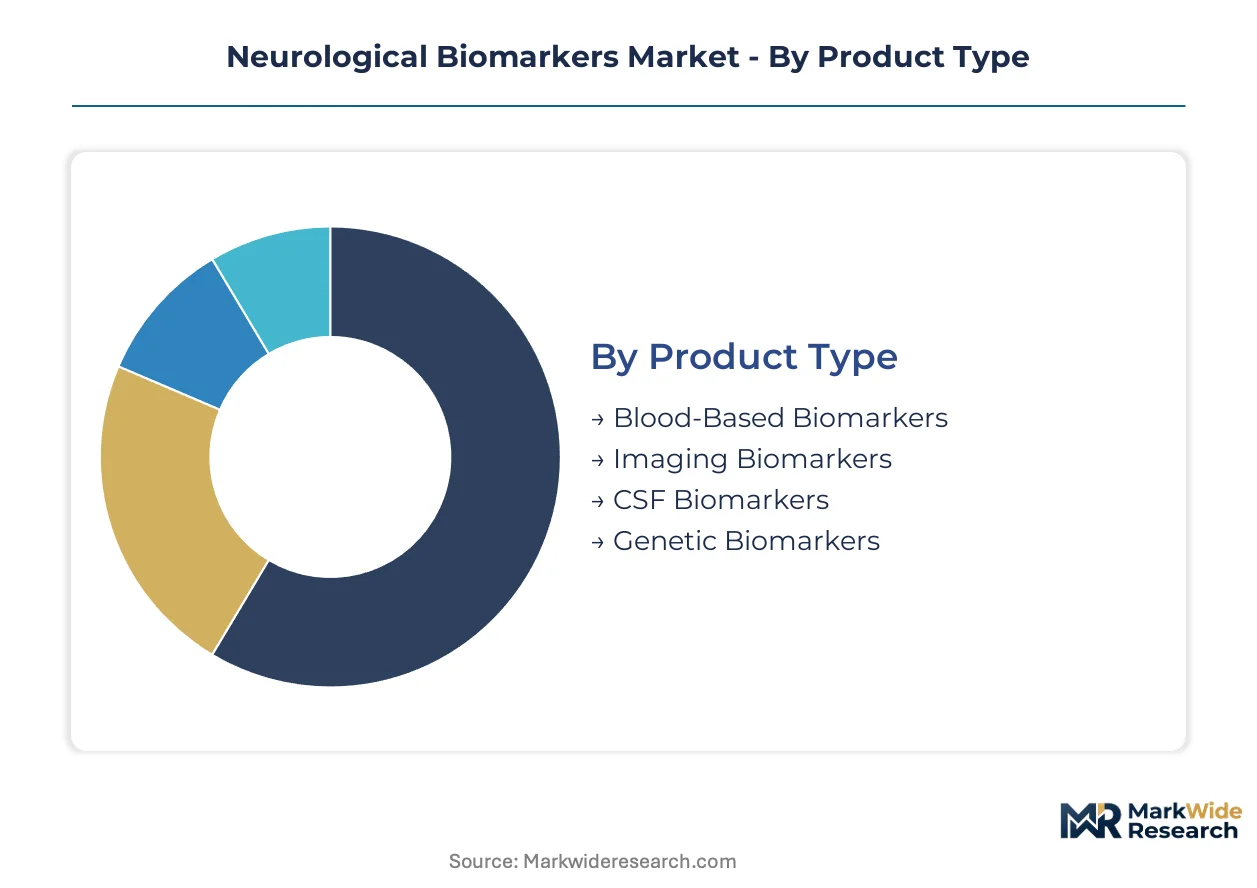
Neurological biomarker segmentation reflects divergent technical capabilities across detection modalities and care settings. Assay developers must align platform investments with specific reimbursement pathways and collection logistics that vary sharply by sample type and clinical application.
Product Type:
Domestic demand concentrates in blood-based and imaging platforms where collection infrastructure already exists; CSF and genetic segments rely more heavily on export markets with specialized tertiary hospital networks.
- Blood-Based Biomarkers:Peripheral protein detection achieves femtomolar sensitivity for phosphorylated tau and neurofilament light chain. US Medicare administrative contractors and German statutory insurers are expanding coverage determinations for Alzheimer's screening in primary care settings.
- Imaging Biomarkers:Amyloid PET and quantitative MRI volumetrics require centralized radiology infrastructure with specialized interpretation protocols. Japan's dementia care networks and US academic medical centers anchor demand where premium reimbursement persists despite higher per-test costs.
- CSF Biomarkers:Cerebrospinal fluid analysis delivers superior analytical specificity for tau isoform quantification. Specialized lumbar puncture logistics restrict deployment to hospital networks in Germany, Japan, and select US tertiary centers.
- Genetic Biomarkers:APOE genotyping and polygenic risk scores support familial screening protocols. Research institutions and direct-to-consumer channels in the United States drive volume before clinical translation.
Blood-based platforms hold the largest share; momentum sits with imaging biomarkers as AI-driven quantification tools secure EMA conformity certification.
Application:
Cost-tier stratification separates premium-priced early detection protocols from standardized monitoring applications, with reimbursement intensity tracking diagnostic certainty requirements.
- Dementia Diagnosis:Multi-modal biomarker integration distinguishes Alzheimer's pathology from frontotemporal and Lewy body dementias. Japanese long-term care insurance and US Medicare Advantage plans are embedding biomarker confirmation into care pathway protocols.
- Alzheimer's Screening:Pre-symptomatic detection demands highest analytical sensitivity as biological changes precede cognitive decline by years. Blood-based assays are displacing CSF collection in US and German primary care screening programs.
- Parkinson's Disease Management:Alpha-synuclein seed amplification assays and DAT-SPECT imaging track dopaminergic degeneration. Movement disorder centers in Germany and Japan concentrate specialized testing volume.
- Stroke Assessment:Acute neurofilament light chain and GFAP elevation predict tissue injury severity. Emergency department protocols in US comprehensive stroke centers are standardizing point-of-care deployment.
Dementia diagnosis holds the largest share; Alzheimer's screening is climbing the fastest as population-scale prevention trials expand enrollment.
Technology:
Volume concentration favors immunoassay platforms with established manufacturing scale; discovery platforms and advanced imaging command margin premiums through technical differentiation.
- Immunoassays:Simoa and Ella platforms achieve single-molecule detection for blood-based neurodegenerative proteins. Quanterix and Bio-Techne instrument placements span US neurology practices and European reference laboratories.
- Genomic Sequencing:Targeted panels and whole-genome analysis identify rare variant burden and polygenic risk architectures. Thermo Fisher and Illumina infrastructure anchors pharmaceutical biomarker discovery contracts.
- Magnetic Resonance Imaging:Volumetric quantification of hippocampal and cortical atrophy requires standardized acquisition protocols. EMA's EU AI Act conformity obligations are consolidating vendor relationships among European radiology networks.
- Biomarker Discovery Platforms:Mass spectrometry and multi-omics integration support novel target identification. Academic medical centers and pharmaceutical sponsors in the United States and Germany fund exploratory workflows.
Immunoassays hold the largest share; genomic sequencing is gaining share fastest as companion diagnostic mandates expand biomarker-stratified trial enrollment.
End User:
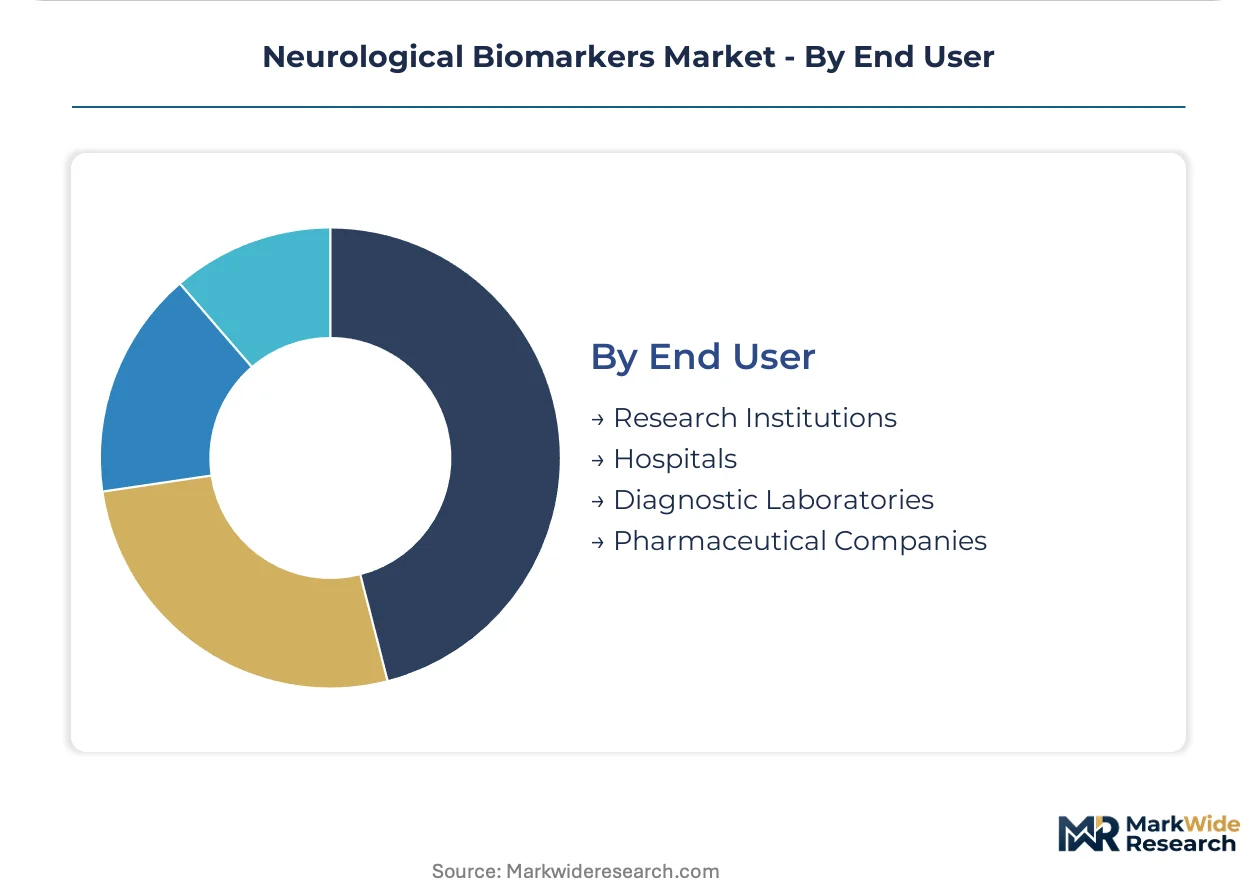
Customer-type segmentation separates research-funded discovery from clinically reimbursed diagnostics, with procurement authority shifting toward hospital laboratory committees.
- Research Institutions:Academic medical centers drive biomarker qualification studies and novel assay validation. NIH and German Research Foundation grants support early-stage platform development.
- Hospitals:Integrated health systems are unbundling neurology service contracts to benchmark assay performance separately. US health system procurement committees now govern renewal decisions on analytical specifications.
- Diagnostic Laboratories:Reference laboratories scale high-throughput processing for regional hospital networks. Quest and LabCorp infrastructure dominates US commercial testing volume.
- Pharmaceutical Companies:Biomarker-integrated trial designs embed assay demand into drug development pipelines. FDA accelerated approval pathways mandate stratified enrollment, contracting discovery platform access.
Hospitals hold the largest share; pharmaceutical companies are expanding most quickly as precision neurology pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for neurological biomarker assays varies sharply across healthcare systems. Japanese and German buyers accept premium pricing for centralized diagnostic infrastructure, while US Medicare administrative contractors and Indian hospital networks drive harder negotiations on per-test reimbursement rates.
United States
Medicare Advantage plans and integrated health systems anchor demand for blood-based Alzheimer's screening assays. FDA breakthrough device designations accelerate market access for Simoa-platform developers in Boston and San Diego biotech clusters. Academic medical centers in the Northeast Corridor unbundle neurology service contracts to benchmark biomarker performance separately.
Germany
Statutory health insurance funds and dementia care networks concentrate demand for CSF confirmation testing in tertiary hospitals. EMA parallel biomarker qualification pathways compress validation timelines for assay developers in Munich and Heidelberg. The country's centralized laboratory infrastructure favors high-throughput reference laboratory models over point-of-care deployment.
Japan
Long-term care insurance and aging demographic density sustain premium reimbursement for amyloid PET imaging in Tokyo and Osaka medical centers. PMDA accelerated approval pathways align with FDA timelines for companion diagnostic submissions. Regional dementia care networks standardize biomarker-integrated care pathways across prefectural health systems.
China
Hospital procurement reform and volume-based purchasing squeeze margins for imported immunoassay platforms in Beijing and Shanghai tertiary centers. NMPA regulatory harmonization efforts with FDA standards reshape validation requirements for multinational assay developers. Domestic manufacturers in Suzhou and Shenzhen biotech parks scale production of localized biomarker detection systems.
United Kingdom
NHS England's national dementia strategy embeds blood-based biomarker screening into primary care pathways in London and Manchester health systems. MHRA post-Brexit regulatory autonomy creates divergence from EMA qualification timelines for UK-specific submissions. Academic medical centers in Oxford and Cambridge anchor discovery platform contracts with pharmaceutical sponsors.
Neurological Biomarkers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in neurological biomarker supply. Thermo Fisher Scientific anchors high-throughput discovery infrastructure, while Quanterix occupies ultra-sensitive detection niches. Three archetypes dominate: diversified life science conglomerates with genomic sequencing backbones, precision diagnostics specialists with single-molecule array platforms, and pharmaceutical-integrated companion diagnostic developers. Competitive moves concentrate on strategic partnerships for trial enrollment access and technology licensing for assay menu expansion.
Within the diversified infrastructure tier, Thermo Fisher Scientific exemplifies scale-driven platform provision. Quanterix occupies a distinct position among blood-based neurodegenerative screening specialists. Among European-headquartered diagnostic conglomerates, F. Hoffmann-La Roche and Merck KGaA represent integrated assay and pharmaceutical development models. Abbott and Johnson & Johnson anchor point-of-care and hospital system distribution channels respectively.
| Leading Market Players |
|---|
| Abbott |
| Thermo Fisher Scientific |
| Qiagen |
| Merck KGaA |
| Bio-Rad Laboratories |
| Johnson & Johnson |
| Quanterix |
| Banyan Biomarkers |
| F. Hoffmann-La Roche |
| Others |
Cost & Logistics Intelligence
Long-term instrument placement contracts with reagent rental clauses lock in supply access for neurology practices while capping price visibility across the assay lifecycle. US health system procurement committees and German statutory insurers leverage these structures to secure preferential per-test rates for blood-based Alzheimer's screening platforms.
Pricing Analysis
After-sales reagent revenue and service contracts drive lifetime value for assay platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated systems from CE-marked alternatives and research-use-only configurations. Cost compression in the standard tier is intensifying because hospital procurement committees unbundle neurology service contracts to benchmark assay performance separately. US Medicare administrative contractors exhibit highest price sensitivity, while Japanese dementia care networks accept premium pricing for amyloid PET imaging infrastructure.
Supply Chain Analysis
Extended lead times for femtomolar-range detection components constrain inventory flexibility for Simoa instrument manufacturers. Supply concentrates in the United States, Germany, and Japan for high-sensitivity immunoassay platforms, with China scaling domestic production of localized detection systems. Raw material dependencies include rare-earth magnets for magnetic bead separation, specialized optical sensors for single-molecule detection, and recombinant antibodies for tau isoform specificity. Single-source vulnerability for photomultiplier tubes creates chokepoint exposure. Distribution runs through integrated health system procurement committees in the United States and centralized reference laboratory networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospital laboratory committees as integrated health systems consolidate procurement authority across regional networks. This concentration fragments vendor pricing leverage and elevates analytical performance specifications as primary selection criteria.
For Market Incumbents: Shield assay menu expansion through exclusive reagent supply agreements with academic medical centers in Boston and San Diego biotech clusters. Deepen backward integration into recombinant antibody production to secure supply continuity against single-source photomultiplier tube vulnerabilities. Lock in long-term instrument placement contracts before procurement committee consolidation accelerates. For New Entrants and Emerging Players: Anchor in point-of-care deployment for memory care centers and neurology clinics where centralized laboratory infrastructure remains underdeveloped. Target US primary care screening programs as the most penetrable segment, where blood-based Alzheimer's assays are displacing CSF collection protocols. Pursue FDA breakthrough device designation as the go-to-market angle to accelerate reimbursement coverage. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors precision diagnostics specialists with single-molecule array capabilities over diversified life science conglomerates. Long-term viability over the next decade hinges on companion diagnostic integration into precision neurology pipelines. Watch FDA accelerated approval mandates for biomarker-stratified trial enrollment as the inflection signal for assay demand embedding.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market access timelines for blood-based neurodegenerative screening assays in Boston clusters. |
| Companion Diagnostic Partnership | Embeds assay demand into pharmaceutical precision neurology pipelines under accelerated approval frameworks. |
| Point-of-Care Instrument Placement | Enables decentralized testing in memory care centers where centralized laboratory infrastructure remains limited. |
| EU AI Act Conformity Certification | Creates first-mover advantage for algorithm-driven imaging biomarker interpretation tools in European radiology networks. |
| Reagent Rental Contract Structure | Locks in long-term supply relationships with US health systems while securing predictable revenue streams. |
Research Approach
A spread of perspectives from assay development scientists, regulatory affairs specialists at FDA and EMA, hospital laboratory directors, and pharmaceutical biomarker strategists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA qualification pathway documentation, ClinicalTrials.gov biomarker-stratified trial records, and CMS Medicare coverage determination databases. Bottom-up instrument placement counts and top-down pharmaceutical R&D spend triangulation anchored volume estimates.
Segmentation dimensions modeled include biomarker modality, clinical application, detection technology platform, and end-user setting across the analysis window. CAGRs were derived from instrument placement trajectories, reagent consumption curves, and reimbursement expansion timelines. Forecast inputs incorporated companion diagnostic mandate intensity, aging demographic concentration in Japan and Germany, and blood-based assay analytical sensitivity advances.
Material uncertainties — regulatory harmonization delays between FDA and EMA, reimbursement coverage variability across US Medicare administrative contractors, and photomultiplier tube supply disruptions — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Spinal Laminoplasty Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Neurology Devices Market
Neurology
Global Vertigo Treatment Market
Neurology
Neurology Software Market
Neurology
Transverse Myelitis Treatment Market
Neurology
3D Neuroscience Market
Neurology
Movement Disorder Market
Neurology
North America Neurology Devices Market
Neurology
Neuroprotection Market
Neurology
Australia Neurology Devices Market
Neurology
Pediatric Neurology Device Market
Neurology
Sweden Neurology Devices Market
Neurology
CNS Lymphoma Market
Neurology
Neuropsychiatric Disorders and Treatment Market