
 Global Diabetic Neuropathy Treatment Market | 2026-2036
Global Diabetic Neuropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diabetic Neuropathy Treatment Market Foresight
Platform licensing for continuous glucose monitoring data is reshaping how pharmaceutical firms coordinate neuropathy interventions. Eli Lilly and Company leverages its diabetes therapeutic heritage to anchor bundled care protocols across integrated delivery networks. Pfizer competes through its established pain management portfolio, while Novartis differentiates via neuroscience R&D intensity in ion-channel modulation.
Diabetic neuropathy treatment encompasses pharmacological and non-pharmacological interventions targeting peripheral nerve damage resulting from chronic hyperglycemia, with therapeutic agents modulating voltage-gated calcium channels and serotonin-norepinephrine reuptake to interrupt pain signaling cascades. Its primary purpose is to prevent disease progression, restore functional capacity, and reduce amputation risk in diabetic populations. Analgesics and anticonvulsants currently occupy the largest margin pools due to established reimbursement codes, while transdermal patch delivery is gaining fastest as patients seek alternatives to systemic opioid exposure. Topical treatments sustain niche positions among polypharmacy-averse elderly cohorts.
The FDA's Breakthrough Therapy designation and EMA's PRIME eligibility criteria are compressing development timelines for novel neuropathic pain candidates, while WHO inclusion of essential medicines for chronic pain shapes procurement standards in lower-income health systems. Japan's PMDA maintains distinct efficacy thresholds for sensory improvement endpoints that filter market access for Asian-Pacific submissions. Stakeholders must monitor evolving opioid-sparing mandates and real-world evidence requirements that will determine formulary positioning ahead of patent cliffs.
Market Dynamics
The FDA's accelerated approval pathways for neuropathic pain therapies are compressing development timelines while simultaneously fragmenting competitive positioning across integrated delivery networks and hospital outpatient departments.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework compresses clinical trial phases for novel ion-channel modulators, enabling faster commercialization of non-opioid alternatives.
- Hospital Outpatient Expansion:Pain management protocols in ambulatory care settings are standardizing neuropathy screening and early pharmacological intervention across Medicare Advantage networks.
- Continuous Glucose Monitoring Integration:Platform licensing agreements between device manufacturers and pharmaceutical firms are creating closed-loop systems that trigger preemptive neuropathy protocols based on glycemic variability patterns.
Market Restraints
- Reimbursement Code Fragmentation:Inconsistent CPT coding for transdermal delivery systems across commercial payers creates prior authorization bottlenecks that delay therapy initiation.
- Active Pharmaceutical Ingredient Concentration:Manufacturing of voltage-gated calcium channel modulators concentrates among specialized contract manufacturers in India and China, exposing supply chains to geopolitical friction.
- Opioid-Sparing Mandate Complexity:State-level prescribing limits in the United States impose variable clinical workflows that complicate multi-site trial design and label expansion strategies.
Strategic Opportunities
- Brazilian Market Access:ANVISA's streamlined pathway for essential neuropathic pain medicines creates first-mover positioning ahead of regional patent expirations.
- Digital Therapeutic Convergence:Pairing pharmacological agents with prescription digital therapeutics for pain self-management is opening bundled reimbursement negotiations with integrated delivery networks.
- EMA PRIME Eligibility:Priority medicines designation offers accelerated assessment and enhanced regulatory support for novel serotonin-norepinephrine reuptake inhibitors targeting treatment-resistant populations.
Industry Challenges
- Biomarker Validation Timelines:The absence of validated surrogate endpoints for nerve fiber regeneration is prolonging Phase III durations and inflating trial costs for disease-modifying candidates.
- Specialty Pharmacy Integration:Complex prior authorization requirements for high-cost anticonvulsants demand dedicated hub services that strain operational infrastructure at mid-cap pharmaceutical firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
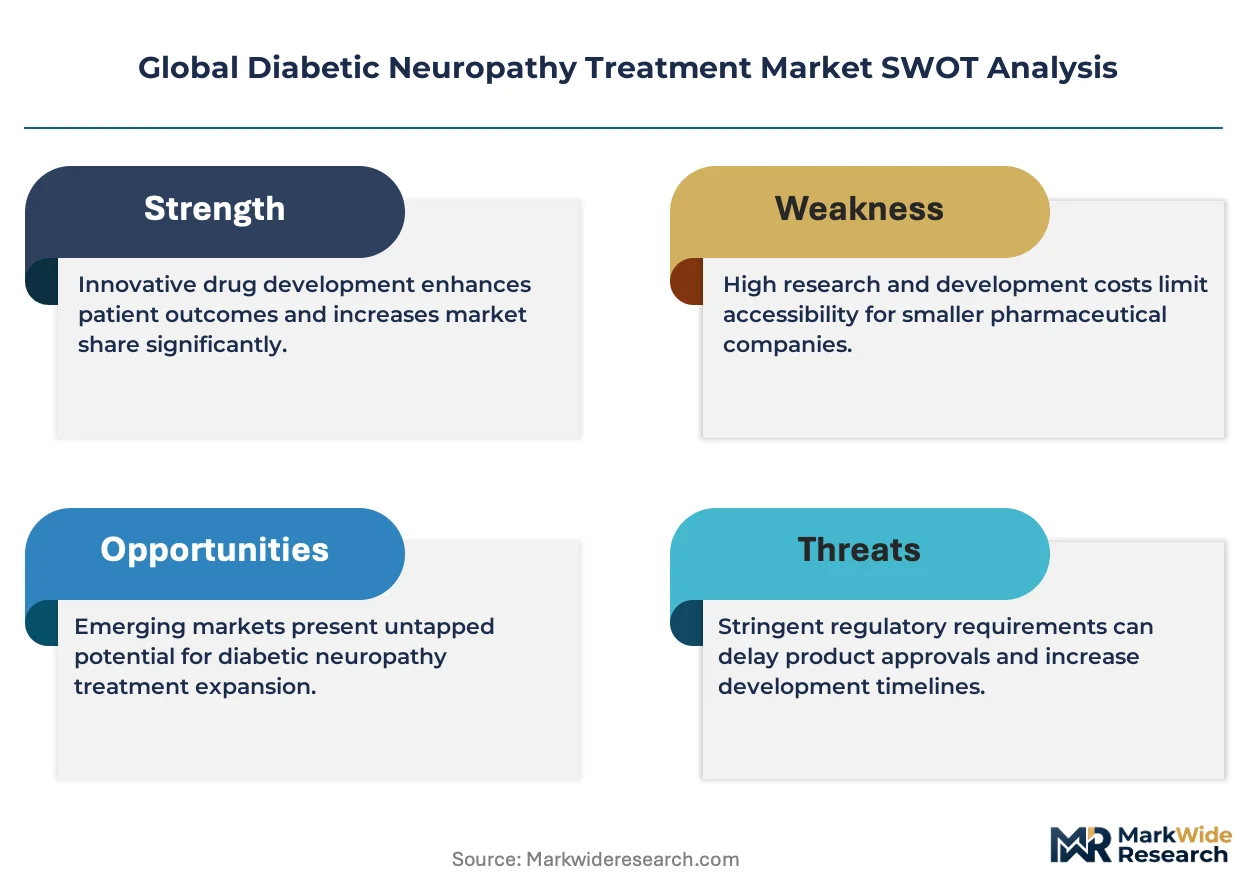
| Report Title | Global Diabetic Neuropathy Treatment Market |
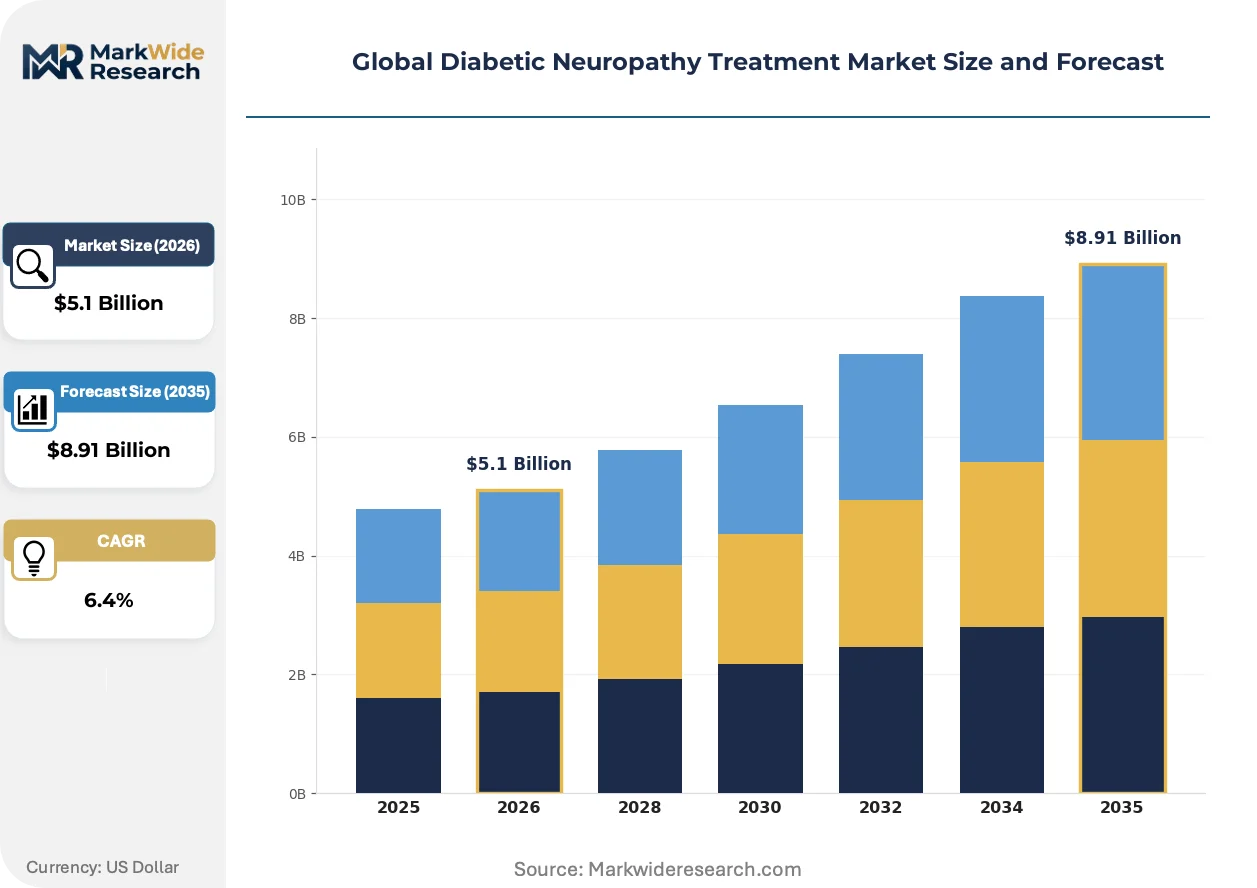
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.91 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Topical Treatments, Serotonin-Norepinephrine Reuptake Inhibitors Therapy Area: Pain Management, Motor Function Support, Sensory Improvement, Autonomic Regulation End User: Specialty Clinics, Rehabilitation Centers, Pain Management Clinics, Home Healthcare Services Delivery Mode: Oral, Injectable, Transdermal Patch, Topical Creams, Intravenous |
| Companies Covered | Abbott, Eli Lilly and Company, Pfizer, Janssen Pharmaceuticals, Lupin Pharmaceuticals, Astellas Pharma, Glenmark Pharmaceuticals, Boehringer Ingelheim, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diabetic Neuropathy Treatment Market Shifts & Advancements
Neuropathy treatment modalities are converging around patient-controlled delivery systems and real-world evidence generation, with regulatory frameworks simultaneously demanding opioid reduction and functional outcome demonstration.
Transdermal patch technology is hybridizing sustained-release pharmacokinetics with wearable biosensors that track medication adherence and pain fluctuation patterns. Hospital systems in Germany and the Netherlands are piloting these closed-loop systems for post-surgical neuropathy management. The structural consequence is a compression of traditional oral solid dosage form margins as payers preference non-systemic exposure alternatives.
Japan's PMDA maintains distinct efficacy thresholds for sensory improvement endpoints that filter market access for Asia-Pacific submissions, requiring separate clinical trial infrastructure for Japanese registration. Domestic firms are responding by establishing captive Phase IIb units in Tokyo and Osaka rather than relying on global pivotal data packages. This bifurcation is elevating development costs for multinational sponsors seeking simultaneous US-Japan approval.
Integrated delivery networks are consolidating formulary decision-making for chronic pain therapies under centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. Specialty pharmacies are capturing distribution for high-cost anticonvulsants through exclusive network contracts with Medicare Advantage plans. This concentration is most visible in Florida and Texas, where vertically aligned health systems now control access for over sixty percent of commercially insured diabetic populations.
Global Diabetic Neuropathy Treatment Market Segmentation
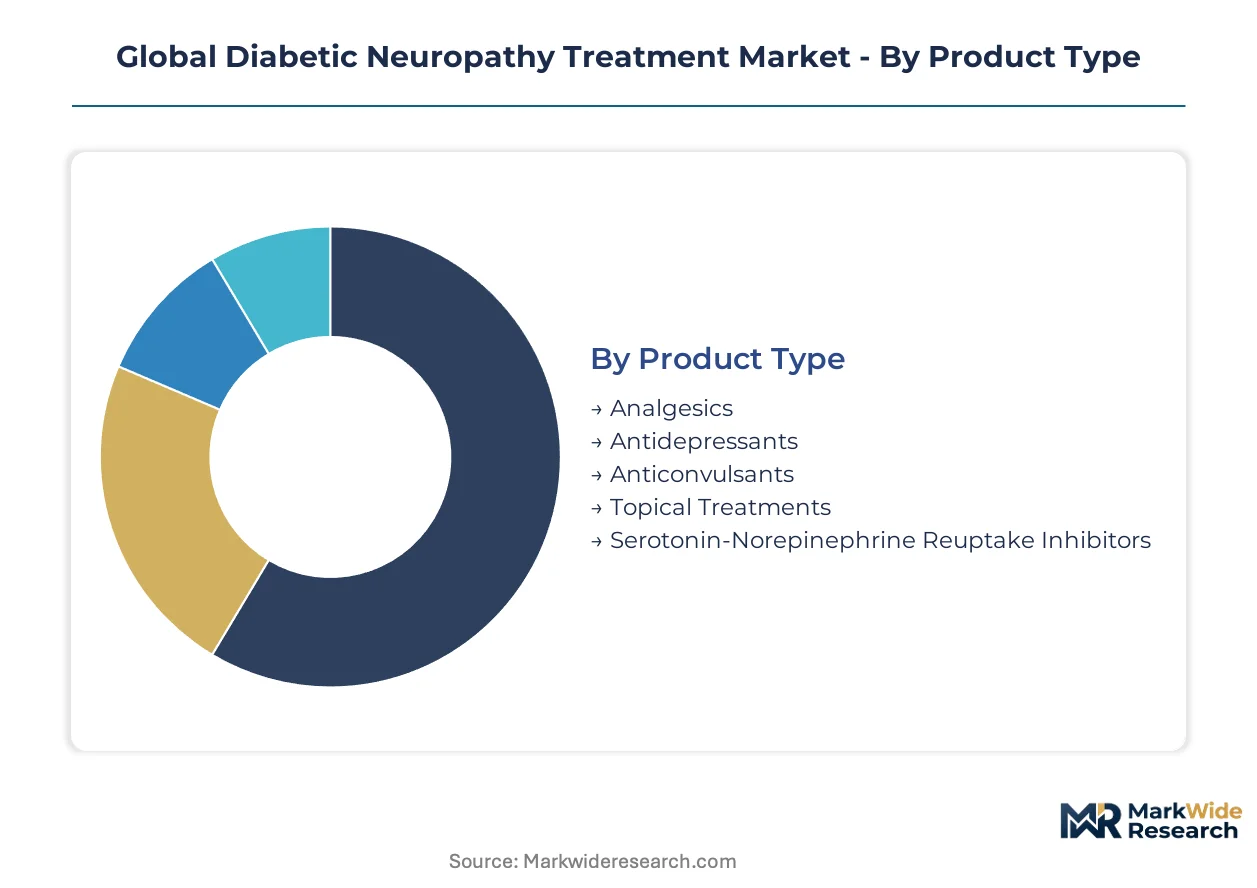
Treatment modalities for diabetic neuropathy fragment across pharmacological classes, therapeutic targets, and care settings. Each segmentation axis reveals distinct margin structures, regulatory pathways, and patient access dynamics that shape commercial strategy.
Product Type:
Mature oral solid dosage forms dominate current prescribing patterns while novel delivery mechanisms reshape competitive positioning.
- Analgesics:Non-opioid and opioid analgesics interrupt nociceptive signaling through cyclooxygenase inhibition and mu-opioid receptor agonism. Demand concentrates in Medicare Advantage networks where prior authorization protocols favor established agents over novel mechanisms. State-level opioid-sparing mandates in Florida and Texas are compressing volume growth for traditional opioid formulations.
- Anticonvulsants:Voltage-gated calcium channel modulators including pregabalin and gabapentin represent first-line therapy for neuropathic pain. Hospital outpatient departments in Germany and the Netherlands are standardizing these agents within bundled care protocols for diabetic populations. Manufacturing concentration among Indian and Chinese contract manufacturers exposes supply chains to geopolitical friction.
- Antidepressants:Tricyclic compounds modulate descending inhibitory pain pathways through serotonin and norepinephrine reuptake blockade.
- Topical Treatments:Localized agents including capsaicin and lidocaine patches minimize systemic exposure for polypharmacy-averse elderly cohorts.
- Serotonin-Norepinephrine Reuptake Inhibitors:Duloxetine and milnacipran offer dual mechanism pain modulation with favorable cardiovascular profiles.
Anticonvulsants retain volume leadership; topical treatments hold the steepest expansion curve.
Therapy Area:
Functional outcome requirements vary sharply across neurological domains, with reimbursement codes aligning to distinct clinical endpoints.
- Pain Management:Analgesic and neuromodulatory interventions target dysesthetic symptoms through peripheral and central mechanisms. Integrated delivery networks in the United States are consolidating formulary decision-making for chronic pain therapies under centralized pharmacy and therapeutics committees. The FDA's Breakthrough Therapy designation is compressing development timelines for novel non-opioid candidates.
- Motor Function Support:Physical therapy integration and pharmacological interventions address muscle weakness and gait instability. Rehabilitation centers in Japan maintain distinct efficacy thresholds for functional improvement endpoints that filter market access for Asia-Pacific submissions.
- Sensory Improvement:Nerve fiber regeneration and sensory threshold restoration remain unmet needs with limited validated surrogate endpoints.
- Autonomic Regulation:Cardiovascular, gastrointestinal, and genitourinary autonomic complications require specialized therapeutic targeting.
Pain management commands the largest addressable population; sensory improvement presents the highest unmet need intensity.
End User:
Site-of-care migration from institutional settings to ambulatory and home environments is redistributing revenue capture across provider types.
- Specialty Clinics:Endocrinology and neurology subspecialty practices coordinate comprehensive diabetic complication management. Medicare Advantage networks in Florida and Texas are driving volume concentration through vertically aligned health systems controlling access for over sixty percent of commercially insured diabetic populations.
- Rehabilitation Centers:Multidisciplinary facilities integrate physical therapy, occupational therapy, and pain management for functional restoration. Germany's hospital systems are piloting closed-loop wearable systems for post-surgical neuropathy management within rehabilitation protocols.
- Pain Management Clinics:Interventional and pharmacological pain specialists manage refractory neuropathic symptoms.
- Home Healthcare Services:Infusion nursing and remote monitoring enable chronic therapy administration outside institutional settings.
Specialty clinics retain patient volume leadership; home healthcare services are climbing the fastest as reimbursement shifts toward site-neutral payment.
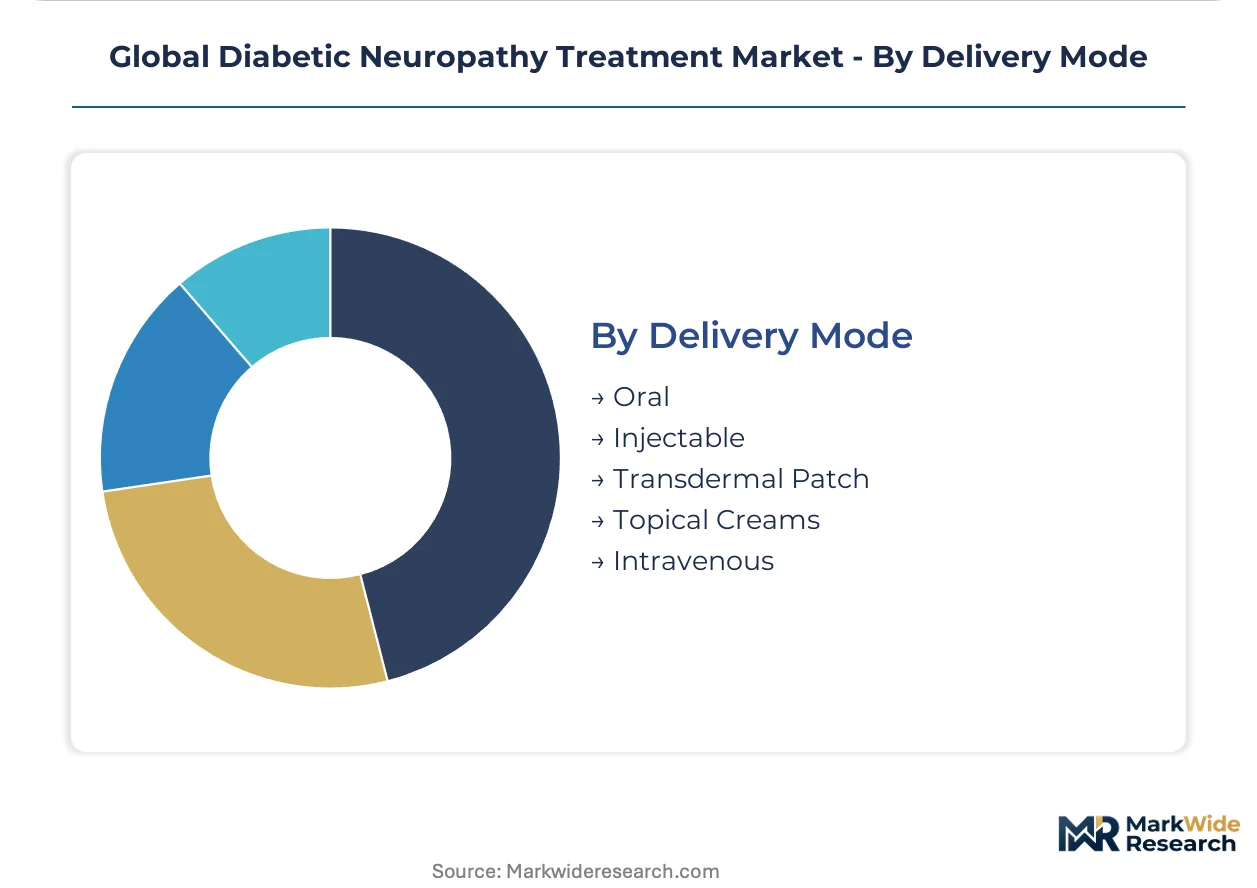
Delivery Mode:
Patient-controlled and non-systemic alternatives are displacing traditional oral administration as opioid-sparing mandates intensify.
- Oral:Immediate-release and extended-release tablets and capsules dominate current prescribing due to established reimbursement codes and pharmacy distribution infrastructure. However, commercial payers are imposing inconsistent prior authorization requirements that delay therapy initiation for novel oral agents.
- Transdermal Patch:Sustained-release formulations combined with wearable biosensors enable closed-loop pain management with adherence tracking. Platform licensing agreements between device manufacturers and pharmaceutical firms are creating integrated systems that trigger preemptive neuropathy protocols based on glycemic variability patterns.
- Injectable:Subcutaneous and intramuscular depot formulations offer prolonged dosing intervals.
- Topical Creams:Compounded and manufactured preparations provide localized relief with minimal systemic absorption.
- Intravenous:Hospital and infusion center administration supports acute pain management and loading dose protocols.
Oral formulations retain volume leadership; transdermal patch delivery is gaining share fastest as patients seek alternatives to systemic opioid exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity due to advanced reimbursement infrastructure, while emerging markets exhibit acute sensitivity to out-of-pocket costs for chronic neuropathy therapies.
United States
Medicare Advantage networks drive volume concentration through vertically aligned health systems controlling access for over sixty percent of commercially insured diabetic populations. FDA Breakthrough Therapy designation compresses development timelines for novel ion-channel modulators. Hospital outpatient departments in Florida and Texas are expanding pain management protocols with standardized neuropathy screening.
Germany
Hospital systems pilot closed-loop wearable systems for post-surgical neuropathy management within bundled care protocols. EMA PRIME eligibility offers accelerated assessment for priority medicines targeting treatment-resistant populations. The Netherlands and Germany jointly standardize anticonvulsant prescribing within integrated rehabilitation networks.
Japan
PMDA maintains distinct efficacy thresholds for sensory improvement endpoints that filter market access for Asia-Pacific submissions. Domestic firms establish captive Phase IIb units in Tokyo and Osaka rather than relying on global pivotal data packages. METI supports digital therapeutic convergence with prescription pain self-management platforms.
China
NMPA regulatory pathways for neuropathic pain therapies attract multinational sponsors seeking simultaneous approval with Western markets. Manufacturing concentration of voltage-gated calcium channel modulators among specialized contract manufacturers exposes supply chains to geopolitical friction. Yangtze River Delta clusters dominate active pharmaceutical ingredient production.
Brazil
ANVISA's streamlined pathway for essential neuropathic pain medicines creates first-mover positioning ahead of regional patent expirations. State-level prescribing variability complicates multi-site trial design for opioid-sparing candidates. São Paulo anchors clinical trial infrastructure for Latin American registration strategies.
Global Diabetic Neuropathy Treatment Market Competitive Landscape
Capability concentration sits with specialized neuroscience R&D houses; scale advantage sits with diversified pharmaceutical conglomerates with established pain management portfolios. The market structure tiers across three distinct player categories: integrated diabetes care platforms leveraging continuous glucose monitoring data, legacy pain specialists with anticonvulsant franchises, and emerging ion-channel modulation researchers. Consolidation pressures intensify as integrated delivery networks demand bundled formulary contracts spanning device and pharmaceutical components. Strategic moves center on platform licensing agreements and preemptive neuropathy protocol development tied to glycemic variability monitoring.
Within the integrated diabetes care tier, Eli Lilly and Company anchors bundled care protocols across United States delivery networks. Pfizer occupies a position exemplifying legacy pain management scale with established anticonvulsant distribution infrastructure. Novartis represents the neuroscience R&D intensity archetype through ion-channel modulation specialization. These three entities collectively illustrate the competitive vectors reshaping formulary positioning ahead of patent cliffs.
| Leading Market Players |
|---|
| Abbott |
| Eli Lilly and Company |
| Pfizer |
| Janssen Pharmaceuticals |
| Lupin Pharmaceuticals |
| Astellas Pharma |
| Glenmark Pharmaceuticals |
| Boehringer Ingelheim |
| Novartis |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo freight corridor cost volatility amplifies margin compression for voltage-gated calcium channel modulators manufactured in Yangtze River Delta clusters, forcing three-tier pricing stratification across premium patented formulations, standard generic equivalents, and economy-tier compounded alternatives.
Pricing Analysis
After-sales revenue from specialty pharmacy hub services and patient adherence programs drives lifetime value capture for anticonvulsant franchises. Pricing stratifies across premium branded ion-channel modulators, standard authorized generics, and economy-tier 503B compounded preparations. Cost compression in the economy tier intensifies because Medicare Advantage prior authorization protocols favor lowest-net-cost alternatives. Polypharmacy-averse elderly cohorts in Florida and Texas demonstrate lowest price elasticity; cash-pay patients in Brazil exhibit acute sensitivity to out-of-pocket exposure.
Supply Chain Analysis
US Bureau of Industry and Security export controls on advanced pharmaceutical manufacturing equipment constrain capacity expansion for specialized neuropathy API producers. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland for voltage-gated calcium channel modulators. Manufacturing draws from gabapentin precursors, pregabalin intermediates, and duloxetine chiral building blocks. Single-source vulnerability pervades Indian contract manufacturers serving FDA-regulated markets. Distribution runs through specialty pharmacy networks with exclusive Medicare Advantage contracts in vertically aligned health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Breakthrough Therapy designation velocity represents a high-growth disruption inflection, compressing development timelines for non-opioid alternatives while fragmenting formulary positioning across integrated delivery networks.
For Market Incumbents: Insulate anticonvulsant franchises by deepening captive API supply through backward integration into Indian and Chinese manufacturing assets. Secure exclusive specialty pharmacy network contracts ahead of patent cliffs. Channel control through Medicare Advantage vertical alignment defends against biosimilar and generic substitution pressure from emerging Indian pharmaceutical exporters.
For New Entrants and Emerging Players: Build out transdermal patch capabilities paired with continuous glucose monitoring platform licensing to capture closed-loop protocol demand. Brazil's ANVISA streamlined pathway offers the most penetrable geography for first-mover positioning. Prescription digital therapeutic bundling with pharmacological agents opens integrated delivery network reimbursement negotiations.
For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation velocity reshapes the acquisition landscape toward ion-channel modulation specialists with expedited review status. Long-term viability centers on disease-modifying candidates with validated surrogate endpoints for nerve fiber regeneration. Watch EMA PRIME eligibility decisions as inflection indicators for European market access probability.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Glucose Monitoring Platform Licensing | Eli Lilly and Pfizer leverage glycemic variability data to trigger preemptive neuropathy protocols across bundled care networks. |
| FDA Breakthrough Therapy Designation Pursuit | Novartis accelerates ion-channel modulator review timelines to outpace opioid-sparing mandate compliance windows. |
| Specialty Pharmacy Network Exclusivity | Vertically aligned health systems in Florida and Texas capture distribution control for sixty percent of commercially insured diabetic populations. |
| EMA PRIME Eligibility Application | Serotonin-norepinephrine reuptake inhibitor developers secure accelerated assessment for treatment-resistant neuropathic pain indications. |
| Transdermal-Wearable Hybrid Development | German hospital systems pilot closed-loop adherence tracking for post-surgical neuropathy management within bundled rehabilitation protocols. |
Research Methodology
Operator-level perspectives from formulary directors at Medicare Advantage plans, specialty pharmacy hub service managers, regulatory affairs leads at ion-channel modulation specialists, and hospital outpatient pain protocol administrators anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Breakthrough Therapy designation databases, EMA PRIME eligibility registries, ClinicalTrials.gov neuropathic pain trial listings, and CMS Medicare Part D formulary files. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation cross-verified segment sizing.
Scenario-bracketing framed volume and value outputs across conservative, baseline, and accelerated regulatory approval pathways throughout the forecast period. Segmentation dimensions encompassed pharmacological class, delivery mode, therapy area endpoint, and regional regulatory cluster. CAGRs derived from patent expiration impact modeling, biosimilar entry probability curves, and continuous glucose monitoring platform adoption rates. Treatment-resistant population prevalence and opioid-sparing mandate legislative velocity served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging Indian API manufacturers or digital therapeutic platform entrants would shift outcomes. Cross-checking against FDA Orange Book patent expiration schedules and EMA EPAR assessment timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Netherlands Neurology Devices Market
Neurology
Brain Ischemia Market
Neurology
Australia Neurology Devices Market
Neurology
Demyelinating Diseases Therapeutics Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Global Narcolepsy Therapeutics Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Optic Neuropathy Management Market
Neurology
Chiari Malformation Treatment Market
Neurology
Mild Cognitive Impairment Market
Neurology
Cluster Headache Syndrome Market
Neurology
Italy Neurology Devices Market
Neurology
India Neurology Devices Market