
 Moyamoya Disease Market | 2026-2036
Moyamoya Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Moyamoya Disease Market Analysis
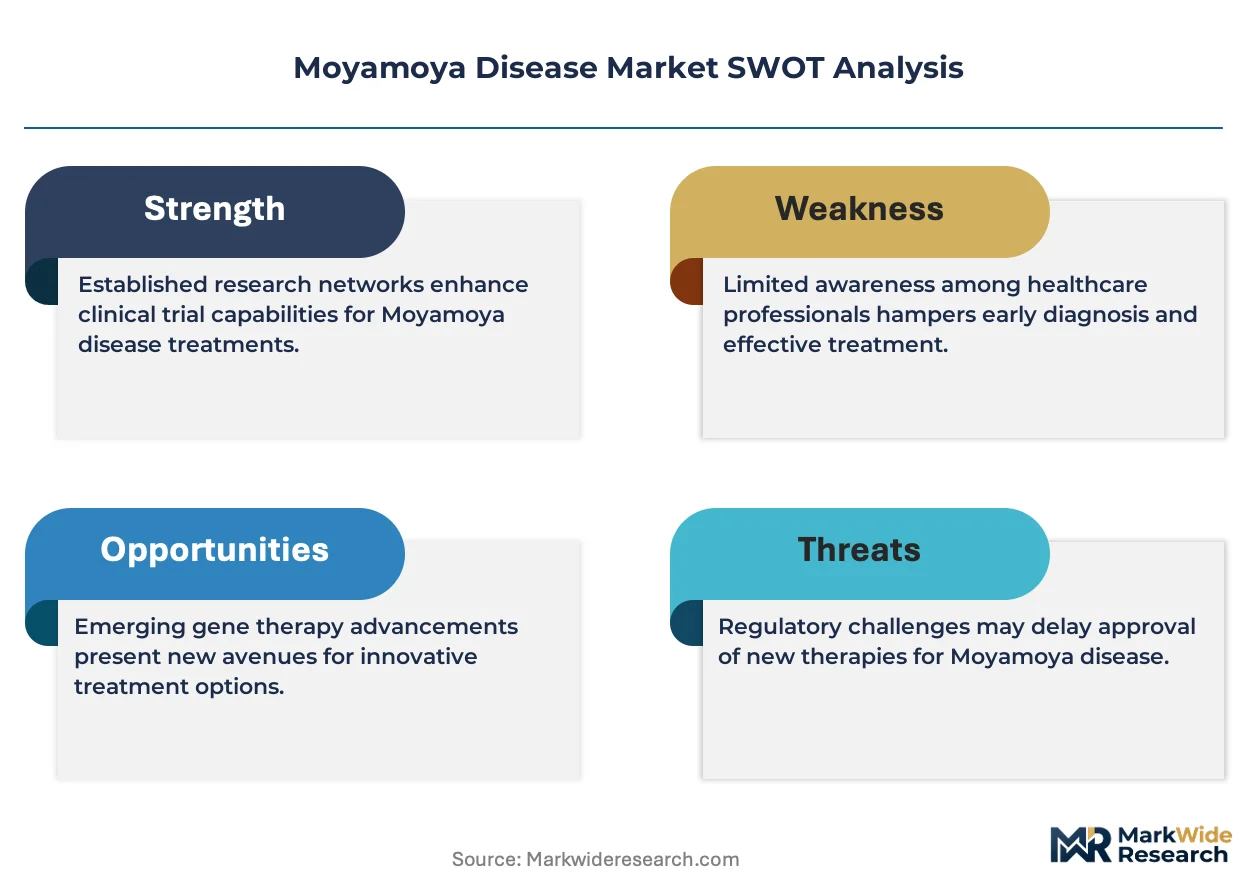
Japan's PMDA orphan-drug framework is rebalancing development economics for cerebrovascular therapeutics, lowering trial-size requirements and extending exclusivity periods for Moyamoya-targeted compounds. Siemens Healthcare GmbH leverages its angiography imaging leadership to anchor premium diagnostic workflows in Japanese and US neurological centers. Stryker competes through specialized microsurgical instrument portfolios designed for extracranial-intracranial bypass procedures. Medtronic controls the neurovascular stenting adjunct market with flow-diversion technologies that surgeons deploy during revascularization cases.
Moyamoya disease is a progressive cerebrovascular disorder characterized by bilateral stenosis of the terminal internal carotid arteries and compensatory formation of fragile collateral vessels at the base of the brain, with diagnosis requiring digital subtraction angiography or high-resolution MRI to visualize the characteristic puff-of-smoke vascular pattern. Its primary clinical purpose centers on preventing ischemic stroke and intracranial hemorrhage through timely revascularization intervention. Diagnostic Tools within the product-type dimension command premium pricing due to MRI and angiography equipment dependencies, while Surgical Revascularization under treatment type captures the deepest margin pools owing to procedure complexity and instrument disposability. Hospitals dominate end-user demand as the sole settings equipped for bypass surgery, though Research Institutions are expanding preclinical pipelines for novel pharmacological approaches.
The FDA maintains stringent premarket approval pathways for neurovascular devices used in Moyamoya bypass procedures, while Japan's PMDA orphan-drug designation accelerates regulatory timelines for condition-specific therapies. ISO 13485 quality management standards govern manufacturing consistency across implantable neurosurgical products, shaping supplier qualification criteria for hospital procurement committees. Stakeholders must monitor how payer coverage policies for indirect revascularization procedures evolve relative to direct bypass outcomes data, as reimbursement decisions will determine addressable patient volumes across tertiary care networks.
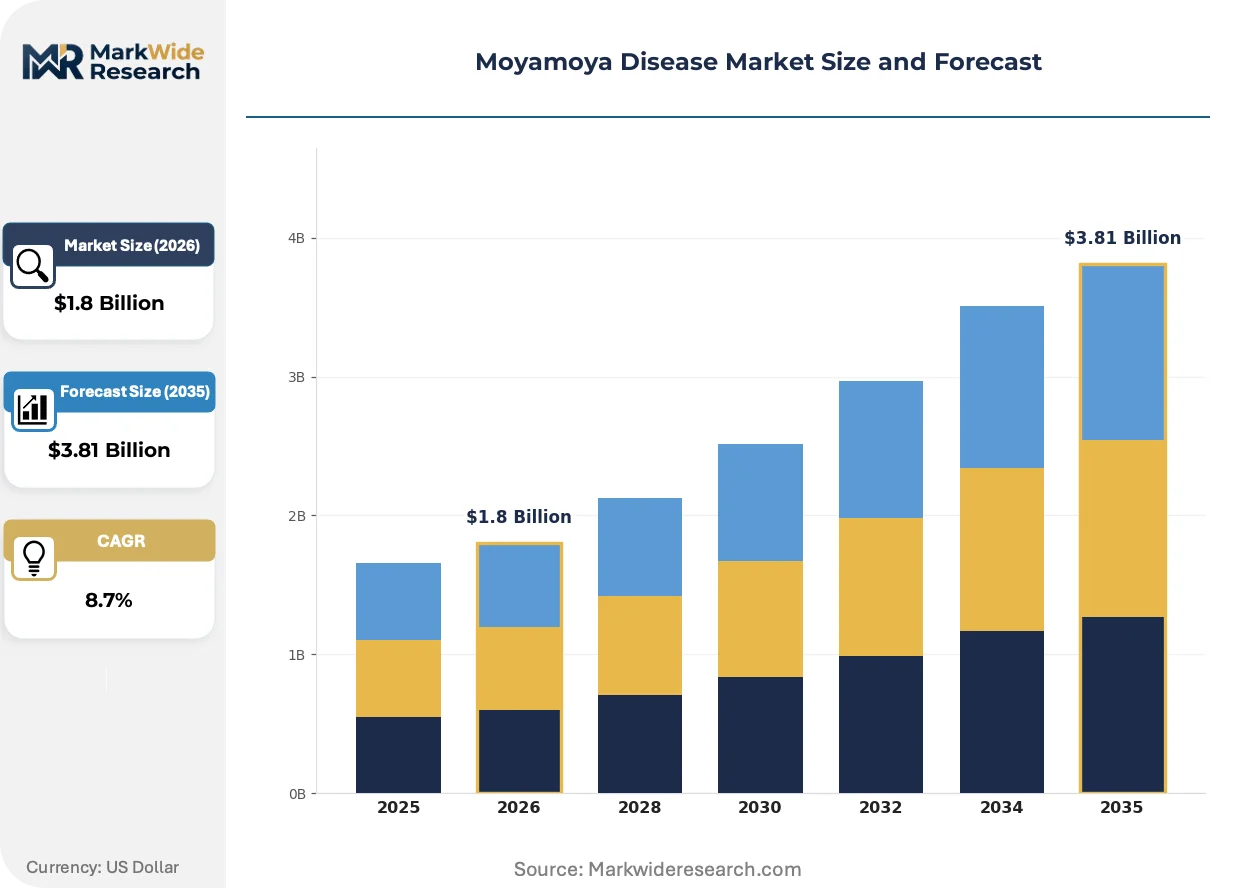
Market Dynamics
Diagnostic sensitivity improvements are compressing time-to-intervention windows, forcing neurological centers to reconfigure surgical throughput and imaging workflows around revascularization volume targets.
Growth Catalysts
- PMDA Orphan-Drug Pathways:Japan's streamlined designation process reduces trial-size requirements and extends market exclusivity for cerebrovascular therapeutics, accelerating compound development timelines.
- High-Resolution MRI Diffusion:Advanced magnetic resonance protocols are electrifying detection rates for the characteristic puff-of-smoke vascular pattern in asymptomatic populations.
- Stanford-Boston Referral Networks:Specialized Moyamoya clinics in the United States are standardizing bypass protocols and concentrating surgical expertise in tertiary care corridors.
Market Restraints
- Digital Subtraction Angiography Cost Structure:Gold-standard diagnostic imaging requires capital-intensive fluoroscopy suites and specialized neuroradiologist staffing, limiting deployment to major medical centers.
- Flow-Diversion Device Supply Concentration:Neurovascular stenting adjunct production clusters with a limited supplier base, creating procurement vulnerability for revascularization programs.
- ISO 13485 Certification Friction:Implantable neurosurgical product manufacturing faces extended quality management audits, delaying supplier qualification for hospital procurement committees.
Strategic Opportunities
- Indirect Revascularization Expansion:Payer coverage policies for encephaloduroarteriosynangiosis procedures are stabilizing, opening addressable patient volumes beyond direct bypass candidates.
- Pharmacological Pipeline White Space:Research institutions are advancing preclinical compounds targeting vascular endothelial growth factor modulation for non-surgical intervention pathways.
- Angiography Workflow Convergence:Siemens Healthcare GmbH and competing imaging vendors are integrating AI-assisted vessel tracking with biplane angiography systems, compressing procedural setup times.
Industry Challenges
- Microsurgical Bypass Skill Scarcity:Extracranial-intracranial anastomosis requires subspecialized cerebrovascular fellowship training, constraining surgeon supply relative to diagnostic case detection.
- Revascularization Outcome Documentation Burden:Long-term stroke prevention efficacy data collection spans decades, complicating health technology assessment submissions for reimbursement authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moyamoya Disease Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgical Treatments, Support Devices, Diagnostic Tools End User: Hospitals, Clinics, Research Institutions, Home Care Treatment Type: Medical Management, Surgical Revascularization, Observation, Combination Therapy Diagnosis Method: Angiography, MRI, CT Scan, Cerebral Angiogram |
| Companies Covered | Johnson & Johnson Services, Inc., Siemens Healthcare GmbH, Abbott Laboratories, Stryker, GE Healthcare, Boston Scientific Corporation, Novartis AG, Eisai Co., Ltd, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moyamoya Disease Market Emerging Trajectories
Neuroimaging resolution thresholds and surgical robotics are converging to redefine intervention eligibility criteria, compressing the gap between detection and revascularization.
High-resolution vessel wall MRI is electrifying characterization of stenosis progression and collateral maturity without invasive catheterization. Japanese neurological centers at Juntendo and Tohoku University are deploying 7-tesla platforms for submillimeter arterial wall assessment. This capability is compressing the diagnostic pathway from multi-modality workup to single-session confirmation.
Japan's PMDA orphan-drug framework is extending exclusivity periods and reducing pivotal trial enrollment thresholds for Moyamoya-targeted therapies. Pharmaceutical developers are repositioning cerebroprotective agents from broader stroke indications toward this designated population. Biotech sponsors with Japanese regulatory strategy capabilities are capturing accelerated review timelines unavailable in standard neurological drug pathways.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment acquisitions for angiography suites. Buyers in the United States are negotiating discrete maintenance agreements and training packages separate from Siemens or GE Healthcare system purchases. This behavior is most visible in California and Massachusetts, where specialized Moyamoya centers operate multiple biplane rooms and possess internal biomedical engineering capacity.
Moyamoya Disease Market Segmentation
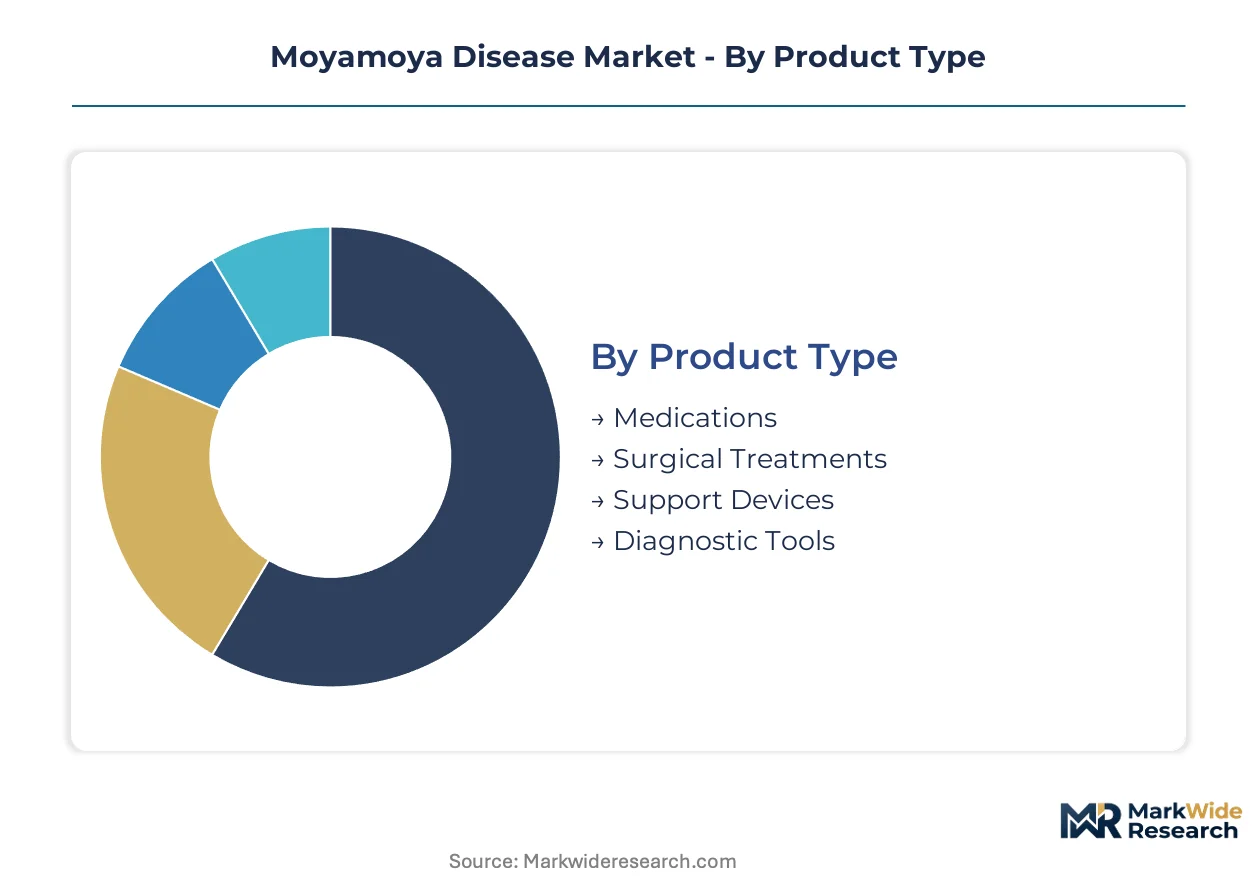
Moyamoya disease management requires precise patient stratification across intervention intensity and care setting. Segmentation reveals where capital concentrates versus where volume expansion is accelerating.
Product Type:
Standardization dominates commodity categories while customization governs premium tiers where procedure-specific configurations command price premiums.
- Diagnostic Tools:High-resolution MRI protocols and digital subtraction angiography systems visualize the characteristic puff-of-smoke vascular pattern. Japanese neurological centers at Juntendo and Tohoku University anchor demand for 7-tesla platforms with submillimeter arterial wall assessment capabilities. Procurement committees unbundle service contracts from capital acquisitions.
- Surgical Treatments:Extracranial-intracranial bypass instruments and flow-diversion devices support revascularization procedures. Stanford and Boston Children's Hospital concentrate surgical expertise and drive protocol standardization across US tertiary corridors. Stryker and Medtronic compete through specialized microsurgical portfolios.
- Medications:Antiplatelet agents and calcium channel blockers manage ischemic symptoms pre- and post-intervention.
- Support Devices:Cerebral oxygenation monitors and postoperative care equipment serve recovery protocols.
Most installed capacity flows through Diagnostic Tools. Expansion is steepest in Surgical Treatments.
End User:
Capital intensity and regulatory licensing create sharp tiering between institutional settings and distributed care.
- Hospitals:Tertiary neurological centers house biplane angiography suites and specialized cerebrovascular fellowship programs. California and Massachusetts corridors concentrate Moyamoya-specific surgical volume. ISO 13485 certification requirements govern implantable product procurement.
- Research Institutions:Preclinical pipelines for vascular endothelial growth factor modulation advance non-surgical intervention pathways. Japan's PMDA orphan-drug framework accelerates compound development timelines for designated cerebrovascular populations.
- Clinics:Referral networks channel suspected cases toward specialized diagnostic hubs.
- Home Care:Post-revascularization monitoring and rehabilitation support extend recovery outside institutional settings.
Revenue concentrates in Hospitals. Patient volume is climbing fastest in Research Institutions.
Treatment Type:
Intervention intensity stratifies across observation, pharmacological management, and surgical spectrum.
- Surgical Revascularization:Direct bypass and indirect procedures prevent ischemic stroke and intracranial hemorrhage. Payer coverage policies for encephaloduroarteriosynangiosis are stabilizing, expanding addressable volumes beyond direct bypass candidates. Long-term outcome documentation spans decades.
- Medical Management:Antiplatelet therapy and blood pressure control serve patients awaiting surgery or with contraindications. Demand concentrates in asymptomatic populations detected through improved MRI sensitivity.
- Observation:Serial imaging monitors stenosis progression in stable presentations.
- Combination Therapy:Staged medical and surgical approaches tailor intervention intensity to disease trajectory.
Procedure volume centers on Surgical Revascularization. Medical Management is gaining share fastest among newly diagnosed asymptomatic cases.
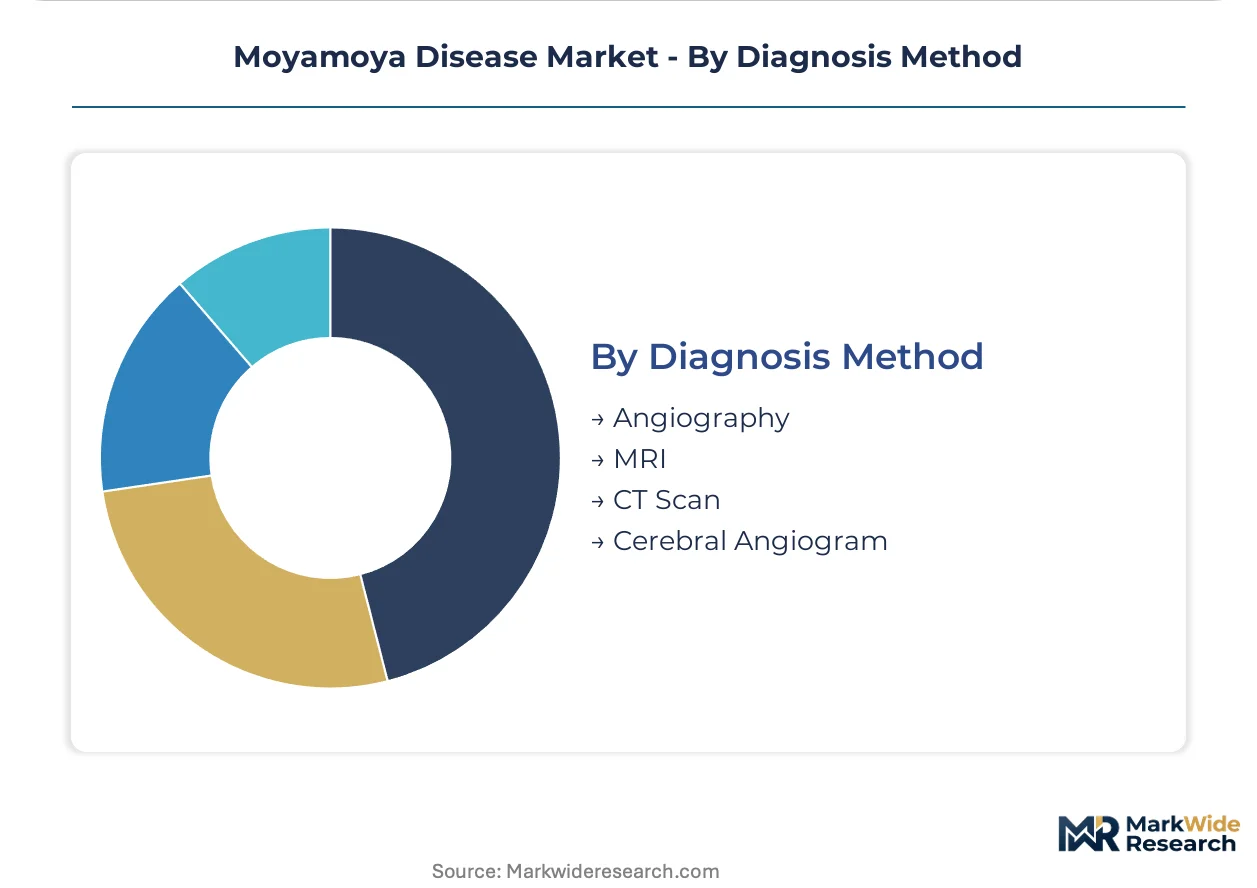
Diagnosis Method:
Resolution capability and invasiveness trade off across the detection pathway.
- MRI:High-resolution vessel wall imaging characterizes stenosis progression without catheterization. 7-tesla platforms at Japanese academic centers compress multi-modality workup to single-session confirmation. Siemens Healthcare GmbH anchors premium diagnostic workflows.
- Angiography:Digital subtraction angiography remains gold standard for collateral vessel visualization. Capital-intensive fluoroscopy suites and specialized neuroradiologist staffing limit deployment to major medical centers.
- Cerebral Angiogram:Invasive catheter-based assessment confirms surgical candidacy.
- CT Scan:Emergency stroke protocol entry point rules out hemorrhage in acute presentations.
Diagnostic throughput flows primarily through MRI. Technical advancement is accelerating most quickly in Angiography with AI-assisted vessel tracking integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moyamoya disease was first characterized and surgically treated in Japan during the 1950s, establishing the country's foundational role in cerebrovascular research. Diagnostic protocols and revascularization techniques developed at Japanese academic centers subsequently diffused to tertiary hospitals across North America and Europe.
United States
Stanford University and Boston Children's Hospital anchor specialized Moyamoya clinics that standardize bypass protocols and concentrate surgical expertise. The FDA maintains stringent premarket approval pathways for neurovascular devices used in revascularization procedures. California and Massachusetts corridors house multiple biplane angiography suites and internal biomedical engineering capacity.
Japan
Juntendo and Tohoku University deploy 7-tesla MRI platforms for submillimeter arterial wall assessment, compressing diagnostic pathways to single-session confirmation. The PMDA orphan-drug framework extends market exclusivity and reduces trial-size requirements for cerebrovascular therapeutics. Tokyo and Sendai neurological centers drive demand for premium diagnostic workflows and accelerated therapeutic development.
Germany
Siemens Healthcare GmbH leverages angiography imaging leadership to anchor premium diagnostic workflows in neurological centers across Bavaria and North Rhine-Westphalia. The EMA regulates neurovascular device approvals under the Medical Device Regulation framework. Munich and Düsseldorf hospital networks concentrate revascularization surgical volume and procurement committee influence.
United Kingdom
London teaching hospitals and the Greater Manchester neurosciences center manage complex cerebrovascular referrals from across England. The MHRA oversees post-Brexit medical device regulations for implantable neurosurgical products. Oxford and Cambridge research institutions advance preclinical vascular endothelial growth factor modulation studies.
South Korea
Seoul National University Hospital and Severance Hospital operate high-volume cerebrovascular surgery programs with specialized Moyamoya units. The MFDS regulates orphan drug designations with reduced clinical trial requirements for rare neurological conditions. The Seoul Capital Area concentrates diagnostic imaging capacity and tertiary referral networks.
Moyamoya Disease Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with dedicated neurovascular divisions. Imaging equipment manufacturers and surgical instrument specialists occupy distinct tier positions based on capital intensity and procedure integration depth. Three archetypes dominate: premium diagnostic system vendors, specialized microsurgical instrument suppliers, and diversified neurovascular device conglomerates. Strategic moves center on unbundling service contracts from capital equipment sales and expanding indirect revascularization device portfolios.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and Abbott Laboratories exemplify scale-driven players with broad neurosurgical footprints. Siemens Healthcare GmbH represents the imaging-centric archetype, anchoring diagnostic workflow relationships in Japanese and US neurological centers. Stryker occupies a position within the specialized surgical instrument tier, with product configurations designed for extracranial-intracranial bypass procedures. Medtronic plc exemplifies the neurovascular device specialist archetype, with flow-diversion technologies deployed during revascularization cases.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Siemens Healthcare GmbH |
| Abbott Laboratories |
| Stryker |
| GE Healthcare |
| Boston Scientific Corporation |
| Novartis AG |
| Eisai Co., Ltd |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
ISO 13485 quality management certification gates qualified supply of implantable neurosurgical instruments and anchors premium-tier pricing access for manufacturers serving Japanese and US neurological centers. This regulatory threshold concentrates procurement authority among hospital committees that unbundle service contracts from capital equipment acquisitions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies diagnostic tools and surgical treatments based on ISO certification grade and after-sales service bundling. Price differentiation stems from 7-tesla MRI platform capabilities versus conventional angiography systems, with Japanese academic centers commanding premium positioning. Cost compression in standard-tier flow-diversion devices is intensifying because of procurement committee unbundling behaviors. Research institutions exhibit highest price sensitivity due to grant-funded capital constraints, while tertiary hospitals with dedicated Moyamoya clinics demonstrate lowest sensitivity given outcome-driven procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese imaging component suppliers for biplane angiography systems deployed in revascularization suites. Manufacturing concentrates in Germany, Japan, and the United States for specialized microsurgical instruments and flow-diversion devices. Raw material dependencies include medical-grade titanium alloys, biocompatible polymers, and rare-earth magnets for MRI superconducting coils. Tariff exposure on Japanese-sourced neuroradiology components creates procurement risk for US hospital networks. Distribution runs through GPO contracts and direct hospital procurement committees with ISO 13485 qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Moyamoya disease market functions as a geographic-arbitrage play between Japan's PMDA orphan-drug acceleration and the FDA's stringent premarket approval timelines, exploiting regulatory cost differentials for therapeutic development.
For Market Incumbents: Cement defensive positioning by deepening backward integration into 7-tesla MRI superconducting coil production and securing exclusive service contracts with Stanford and Boston Children's Hospital referral networks. Threats from AI-assisted vessel tracking vendors compressing procedural setup times demand counterinvestment in integrated diagnostic-surgical workflow platforms. Certification investment in PMDA orphan-drug pathways represents the priority lever for Japanese market access. For New Entrants and Emerging Players: Research institutions with preclinical vascular endothelial growth factor modulation programs offer the most penetrable entry channel for pharmacological intervention development. White-space targets include indirect revascularization device portfolios for encephaloduroarteriosynangiosis procedures and AI-integrated angiography software companions. Go-to-market execution should prioritize partnership structures with Japanese neurological centers leveraging PMDA accelerated review timelines. For Investors and Strategic Acquirers: Roll-up economics work for specialized microsurgical instrument manufacturers because surgeon skill scarcity and fellowship program concentration create durable customer lock-in. Long-term viability hinges on exposure to revascularization volume growth in California and Massachusetts corridors. Acquisition targets should demonstrate ISO 13485 certification and installed base relationships with biplane angiography suite operators. The signal to watch is payer coverage policy stabilization for indirect revascularization procedures as inflection indicator for addressable patient expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Orphan-Drug Pathway Investment | Accelerates therapeutic development timelines through reduced trial-size requirements and extended exclusivity periods. |
| AI-Assisted Angiography Integration | Compresses procedural setup times at Japanese and US neurological centers deploying Siemens biplane systems. |
| Indirect Revascularization Device Expansion | Captures addressable patient volumes beyond direct bypass candidates as payer coverage stabilizes. |
| ISO 13485 Certification Investment | Qualifies manufacturers for procurement committee consideration at tertiary hospital networks. |
| Service Contract Unbundling Strategy | Aligns with California and Massachusetts hospital procurement behaviors separating maintenance from capital acquisitions. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cerebrovascular surgeons, neuroradiologists, hospital procurement managers, biomedical engineers, and PMDA regulatory specialists with secondary validation. Primary sources included structured interviews with fellowship-trained surgeons at Stanford, Boston Children's Hospital, Juntendo, and Tohoku University. Secondary data drew from FDA premarket approval filings, PMDA orphan-drug designations, hospital procurement databases, and CMS Medicare reimbursement policies. Bottom-up procedure volume estimates and top-down market sizing triangulated across diagnostic equipment installations and revascularization surgery throughput.
Segment-weighting approaches modeled product type, end user, treatment type, and diagnosis method dimensions across the analysis window. Analytical frameworks incorporated patient flow from MRI detection through surgical intervention, with CAGRs derived from procedural volume trajectories and equipment replacement cycles. Forecast inputs included PMDA regulatory pathway adoption rates, payer coverage policy evolution for indirect revascularization, and 7-tesla MRI platform diffusion curves at Japanese academic centers.
Revisions become necessary when PMDA orphan-drug framework modifications, FDA neurovascular device reclassification, or major payer coverage determinations for encephaloduroarteriosynangiosis procedures materialize. Forecasts reflect documented assumptions about surgeon training pipeline expansion and diagnostic sensitivity improvement trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Movement Disorder Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Neuroprotection Market
Neurology
Chile Neurology Devices Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Arachnoiditis Treatment Market
Neurology
Cluster Headache Syndrome Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
Argentina Neurology Devices Market
Neurology
Neurology Services Market
Neurology
Interventional Neurology Market
Neurology
Cognitive Neuroscience Market
Neurology
Bell Palsy Treatment Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Grand Mal Seizure Treatment Market