
 Neurology Software Market | 2026-2036
Neurology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Neurology Software Market Analysis
Cloud-native architecture certification is rotating through vendor roadmaps as the decisive quality-tier upgrade in neurology software procurement. Epic Systems Corporation leverages its dominant hospital EHR footprint to embed neurology-specific order sets and imaging workflows. Cerner Corporation anchors its position through deep integration with radiology PACS and neurology device data streams. Siemens Healthineers differentiates by controlling the full imaging-to-diagnosis pathway with native software on its MRI and CT platforms.
Neurology software encompasses clinical applications designed to acquire, process, visualize, and manage neurological data, typically integrating with neuroimaging modalities at sub-millimeter spatial resolution and supporting longitudinal patient tracking across multiple cognitive domains. Its primary commercial purpose is to reduce diagnostic latency for stroke, epilepsy, and neurodegenerative conditions while standardizing care protocols across distributed provider networks. Diagnostic tools command the largest installed base among product types, though AI-driven analytics within the technology dimension captures the fastest expansion as vendors embed FDA-cleared algorithms for hemorrhage detection and seizure forecasting. Telemedicine platforms occupy a narrower but strategically defended margin pool, particularly where rural hospital networks purchase bundled remote neurology consultation services.
The FDA's software as a medical device framework and HIPAA security rule jointly constrain market access, requiring premarket validation for diagnostic algorithms and encrypted patient data architectures that increase compliance costs for new entrants. The European Medicines Agency's medical device regulation extends these requirements across EU member states, mandating clinical evidence for software supporting therapeutic decisions. Stakeholders must monitor how the FDA's evolving predicate device policy for AI-based neuroimaging tools reshapes the competitive boundary between established enterprise vendors and specialized algorithm developers.
Market Dynamics
Cloud-native architecture certification is rotating through vendor roadmaps as the decisive quality-tier upgrade in neurology software procurement, forcing established enterprise platforms to revalidate their deployment models against containerized, API-first alternatives that promise faster algorithm iteration and lower total cost of ownership.
Growth Catalysts
- FDA Software as a Medical Device framework:The FDA's premarket validation pathway for diagnostic algorithms creates a defensible moat for vendors that secure clearance, accelerating hospital purchasing confidence in AI-driven neuroimaging tools.
- Academic medical center neuroinformatics platforms:Leading teaching hospitals in the United States are consolidating fragmented neurology data streams into unified research-clinical hybrids, generating pull-through demand for interoperable software architectures.
- Stroke diagnostic latency reduction:Emergency departments are prioritizing sub-minute hemorrhage detection capabilities, creating procurement urgency for software that integrates directly with CT and MRI acquisition protocols.
Market Restraints
- HIPAA security rule compliance costs:Encrypted patient data architectures and audit infrastructure impose capital burdens on new entrants that lack existing hospital IT relationships.
- European Medicines Agency MDR clinical evidence requirements:The EMA's mandate for therapeutic decision-support software to demonstrate clinical outcomes extends development timelines and raises validation expenses across EU member states.
- Radiology PACS integration complexity:Deep embedding with legacy imaging infrastructure requires specialized engineering resources that concentrate among established vendors with decades of hospital system relationships.
Strategic Opportunities
- Rural hospital telemedicine bundling:Neurology consultation services delivered through remote platforms capture margin pools in underserved geographies where specialist physician scarcity is acute.
- EU AI Act algorithmic transparency mandates:The European Union's risk-based classification system for medical AI creates first-mover advantage for vendors that pre-build explainability documentation and post-market monitoring infrastructure.
- Seizure forecasting algorithm convergence:Integration of continuous EEG monitoring with wearable biometric streams opens new application categories beyond traditional hospital-bound diagnostics.
Industry Challenges
- Neuroinformatics talent scarcity:The intersection of clinical neurology, computational neuroscience, and regulatory science commands premium compensation that strains mid-size vendor hiring pipelines.
- FDA predicate device policy uncertainty:Evolving guidance on substantial equivalence for AI-based neuroimaging tools forces developers to maintain parallel regulatory strategies that consume executive bandwidth.
- Legacy EHR integration friction:Hospital information systems built on decades-old data models resist real-time neuroimaging workflow embedding, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurology Software Market |
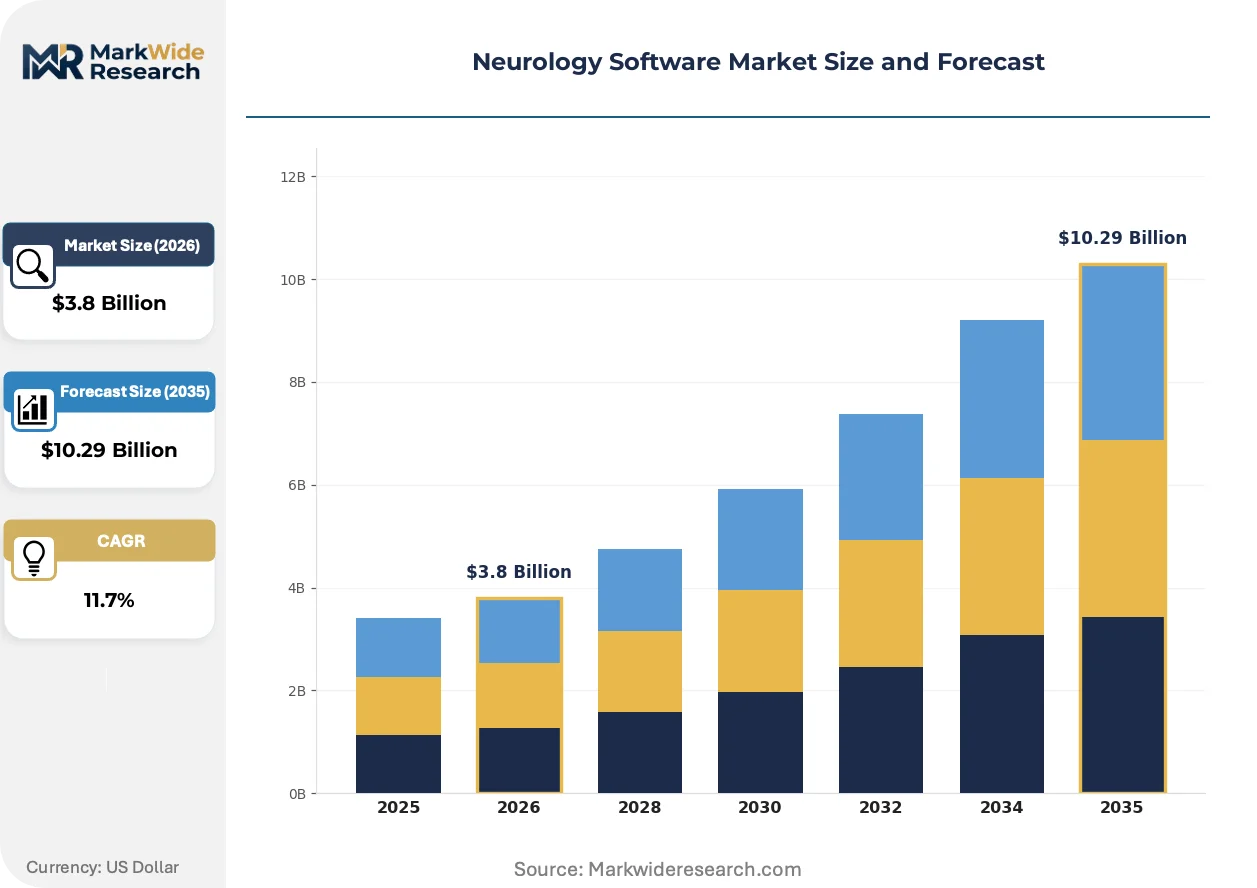
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treatment Planning Software, Diagnostic Tools, Patient Management Systems, Telemedicine Platforms End User: Hospitals, Clinics, Rehabilitation Centers, Research Institutions Technology: Cloud-Based Solutions, On-Premise Software, Mobile Applications, AI-Driven Analytics Application: Stroke Management, Epilepsy Monitoring, Dementia Care, Cognitive Assessment Tools |
| Companies Covered | Epic Systems Corporation, Athenahealth, NextGen Healthcare, Cerner Corporation, McKesson Corporation, Siemens Healthineers, GE Healthcare, Medtronic, Brainlab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurology Software Market Emerging Trajectories
Federated learning architectures and edge-computing deployment models are redistributing computational load away from centralized cloud infrastructure, enabling real-time neurological data processing at the point of care while addressing data sovereignty concerns that constrain cross-border research collaborations.
Containerized microservices for neuroimaging analysis is fragmenting the traditional monolithic software stack. Academic medical centers in the United States are piloting Kubernetes-orchestrated deployments that decouple image reconstruction from diagnostic interpretation. This architecture is fragmenting vendor lock-in by allowing hospitals to swap algorithm providers without replacing entire platform ecosystems.
The FDA's evolving enforcement discretion policy for clinical decision support software is narrowing the scope of unregulated tools while clarifying boundaries for premarket submission. Software that provides specific diagnostic or treatment recommendations now faces heightened scrutiny. AI-driven stroke detection algorithms fall squarely within the regulated boundary, prompting developers to build quality management systems that mirror pharmaceutical manufacturing standards.
Subscription-based pricing for algorithm modules is displacing perpetual licensing in hospital procurement negotiations. Chief information officers are negotiating usage-based contracts that tie payments to validated diagnostic outcomes rather than seat counts. This shift is most visible in United States academic medical centers, where capital budget constraints favor operational expenditure models that preserve balance sheet flexibility for infrastructure modernization.
Neurology Software Market Segmentation
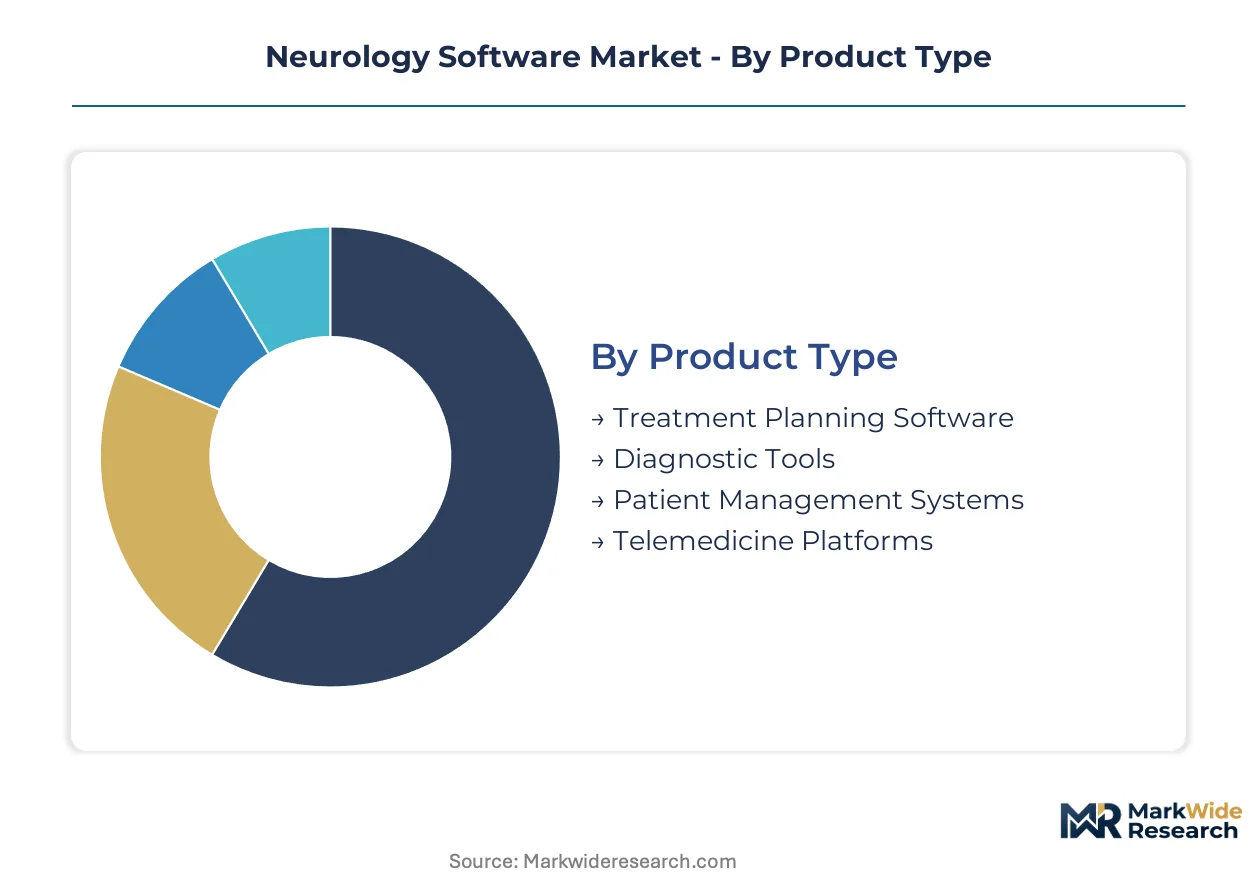
Neurology software procurement channels diverge sharply by segment complexity. Enterprise hospital contracts favor integrated diagnostic suites, while point solutions penetrate through departmental budgets and research grants.
Product Type:
Diagnostic Tools and Treatment Planning Software dominate hospital capital budgets, while Patient Management Systems and Telemedicine Platforms flow through operational expenditure channels and bundled service contracts.
- Diagnostic Tools:Applications integrating neuroimaging modalities at sub-millimeter spatial resolution, including FDA-cleared algorithms for hemorrhage detection and seizure forecasting. Academic medical centers in the United States drive procurement for stroke diagnostic latency reduction.
- Treatment Planning Software:Radiosurgery and neuromodulation planning modules requiring precise anatomical mapping. Demand concentrates in tertiary hospitals with neurosurgical capabilities, constrained by EMA MDR clinical evidence requirements for therapeutic decision support.
- Patient Management Systems:Longitudinal tracking platforms for chronic neurological conditions.
- Telemedicine Platforms:Remote consultation infrastructure for rural hospital networks.
By volume, Diagnostic Tools leads. By growth pace, Telemedicine Platforms is ahead.
End User:
Cost tier stratification separates enterprise hospital deployments from mid-market clinic adoption and grant-funded research installations.
- Hospitals:Large-scale neurology departments requiring full-stack integration with EHR and PACS infrastructure. United States academic medical centers pioneer neuroinformatics platforms that consolidate fragmented data streams.
- Clinics:Outpatient neurology practices prioritizing cloud-native architectures with lower total cost of ownership.
- Rehabilitation Centers:Cognitive and motor recovery tracking systems for post-stroke and traumatic brain injury patients.
- Research Institutions:Federated learning and edge-computing deployments for multi-site neuroimaging studies.
By installed base, Hospitals dominates. By expansion trajectory, Research Institutions is climbing the fastest.
Technology:
Deployment maturity separates proven on-premise architectures from emerging cloud-native and AI-augmented alternatives.
- Cloud-Based Solutions:Containerized microservices enabling Kubernetes-orchestrated neuroimaging analysis. United States academic medical centers pilot API-first deployments that decouple image reconstruction from diagnostic interpretation.
- AI-Driven Analytics:Machine learning modules for pattern recognition in EEG and neuroimaging data. FDA premarket validation creates defensible moats for cleared algorithms.
- On-Premise Software:Legacy architectures retained by hospitals with strict data sovereignty requirements.
- Mobile Applications:Point-of-care tools for bedside neurological assessment and remote patient monitoring.
By revenue concentration, Cloud-Based Solutions leads. By technology investment intensity, AI-Driven Analytics is gaining share fastest.
Application:
Clinical urgency and reimbursement pathways shape segment economics across neurological conditions.
- Stroke Management:Emergency department prioritization of sub-minute hemorrhage detection capabilities. Software integrates directly with CT and MRI acquisition protocols in United States hospital networks.
- Epilepsy Monitoring:Continuous EEG analysis with wearable biometric convergence for seizure forecasting. FDA-cleared algorithms command premium pricing in academic medical center contracts.
- Dementia Care:Longitudinal cognitive tracking platforms for Alzheimer's and related neurodegenerative conditions.
- Cognitive Assessment Tools:Standardized testing modules for concussion and mild cognitive impairment evaluation.
By procurement urgency, Stroke Management leads. By algorithmic innovation pace, Epilepsy Monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources cluster in the United States and Germany, where hospital IT infrastructure density supports specialized neurology software development. Academic medical centers in Boston and Heidelberg generate demand pull-through for neuroinformatics platforms. Regulatory complexity varies sharply across jurisdictions, fragmenting deployment strategies.
United States
FDA premarket validation pathways for AI-driven neuroimaging tools concentrate vendor regulatory investment in this market. Academic medical centers in Massachusetts and California pioneer integrated neuroinformatics platforms that consolidate fragmented data streams. HIPAA security rule compliance costs favor established vendors with existing hospital IT relationships over new market entrants.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia drive demand for treatment planning software requiring precise anatomical mapping. The European Medicines Agency's medical device regulation mandates clinical evidence for therapeutic decision-support software, extending development timelines. Siemens Healthineers anchors engineering talent in Erlangen, controlling full imaging-to-diagnosis pathways with native MRI and CT platform software.
United Kingdom
NHS digital transformation programs accelerate cloud-native architecture procurement in London and Oxford medical clusters. MHRA alignment with FDA software as a medical device frameworks streamlines validation for vendors with existing US clearance. Research institutions in Cambridge pilot federated learning deployments for multi-site neuroimaging studies.
Japan
PMDA regulatory pathways for clinical decision support software narrow the scope of unregulated tools while clarifying premarket submission boundaries. METI funding for healthcare AI creates procurement pull-through in Tokyo and Osaka hospital networks. Aging demographics concentrate demand for dementia care longitudinal tracking platforms in Kansai region medical centers.
India
CDSCO medical device regulations for software supporting therapeutic decisions raise validation barriers for imported platforms. Telemedicine platforms capture margin pools in Maharashtra and Karnataka where rural hospital networks face specialist physician scarcity. Hyderabad and Bengaluru engineering clusters support cost-competitive development of cloud-native neurology software architectures.
Neurology Software Market Vendor Landscape
Concentration sits with enterprise health IT vendors that control hospital EHR infrastructure and imaging device manufacturers with captive software ecosystems. Three archetypes dominate: integrated platform vendors embedding neurology-specific modules within existing hospital systems, specialized neuroimaging software developers targeting stroke and epilepsy workflows, and medical device manufacturers bundling diagnostic algorithms with hardware procurement. M&A activity concentrates on algorithm developers seeking FDA clearance, while strategic partnerships between EHR vendors and AI startups accelerate cloud-native deployment.
Within the integrated platform tier, Epic Systems Corporation and Cerner Corporation exemplify vendors leveraging dominant hospital EHR footprints to embed neurology-specific order sets and imaging workflows. Siemens Healthineers occupies a position bridging device manufacturing and software development, controlling native diagnostic algorithms on MRI and CT platforms. These three companies represent the competitive boundary between enterprise IT consolidation and specialized clinical algorithm development.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Athenahealth |
| NextGen Healthcare |
| Cerner Corporation |
| McKesson Corporation |
| Siemens Healthineers |
| GE Healthcare |
| Medtronic |
| Brainlab |
| Others |
Supply Flow & Price Mechanics
Containerized microservices replacing legacy monolithic stacks simultaneously redistributes engineering talent toward United States and German cloud-native clusters while compressing deployment cost structures for mid-tier hospital buyers. This substitution dynamic fragments vendor pricing power by decoupling algorithm procurement from platform lock-in.
Pricing Analysis
FDA Software as a Medical Device framework dictates the pricing tier structure across neurology software procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic algorithms from CE-marked equivalents and uncertified research tools. Price differentiation hinges on validation depth and EHR integration complexity. Cost compression in the standard tier is intensifying because cloud-native entrants are disaggregating imaging reconstruction from diagnostic interpretation. Academic medical centers exhibit lowest price sensitivity due to grant-funded research budgets, while rural hospital networks face acute procurement constraints.
Supply Chain Analysis
Just-in-time algorithm deployment through API-first architectures dominates vendor inventory strategy, minimizing capital-intensive on-premise infrastructure commitments. Engineering talent concentrates in the United States, Germany, and India, with Hyderabad and Bengaluru clusters feeding cost-competitive development pipelines. Raw material dependencies include cloud compute credits, neuroimaging training datasets, and regulatory consulting expertise. Single-source vulnerability sits with hyperscaler cloud infrastructure that anchors containerized deployments. Distribution runs through hospital GPO contracts and direct enterprise sales to academic medical center procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurology software sits in early-cycle expansion as FDA-cleared AI diagnostic algorithms penetrate emergency department workflows faster than legacy imaging protocols anticipated. Cloud-native architecture adoption accelerates this penetration curve.
For Market Incumbents: Secure FDA predicate device pathways for AI-based neuroimaging tools before evolving guidance narrows substantial equivalence claims. Consolidate cloud-native certification investments to defend against API-first challengers decoupling algorithm modules from platform ecosystems. Deepen EHR integration moats through embedded order sets that raise switching costs for hospital neurology departments.
For New Entrants and Emerging Players: Differentiate on seizure forecasting algorithm convergence that integrates continuous EEG with wearable biometric streams, a white-space category beyond traditional hospital-bound diagnostics. Target rural hospital telemedicine bundling where specialist physician scarcity creates procurement urgency without incumbent saturation. Pursue EU AI Act pre-compliance documentation as a first-mover positioning lever in European academic medical centers.
For Investors and Strategic Acquirers: The market sits at a validation-infrastructure buildout phase that favors algorithm developers with FDA-cleared hemorrhage detection or seizure forecasting modules. Long-term viability centers on regulatory science capabilities that compound across therapeutic decision-support categories. Watch for FDA enforcement discretion policy clarifications on clinical decision support boundaries as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Submission | FDA clearance for stroke hemorrhage detection algorithms creates hospital procurement pull-through in emergency departments. |
| Cloud-Native Architecture Certification | Kubernetes-orchestrated deployments decouple image reconstruction from diagnostic interpretation, fragmenting vendor lock-in. |
| Hospital System Partnership | Epic and Cerner EHR integration embeds neurology-specific workflows that raise switching costs for competing platforms. |
| Acquisition of Algorithm Specialist | Seizure forecasting and continuous EEG analysis capabilities accelerate wearable biometric convergence roadmaps. |
| EU AI Act Pre-Compliance | Explainability documentation and post-market monitoring infrastructure capture first-mover positioning in European tenders. |
Methodological Framework
A standing panel of hospital CIOs, neurology department chairs, FDA regulatory consultants, and GPO contracts managers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA 510(k) filings, EMA medical device regulation submissions, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up triangulation across vendor revenue disclosures and top-down validation against healthcare IT expenditure benchmarks anchored the analytical framework.
Consistency checks against external benchmarks confirmed segmentation outputs across the projection horizon. The modeling framework disaggregated neurology software by deployment model, end-user scale tier, integration complexity, and regional regulatory cluster. CAGRs were derived from algorithmic adoption curves and hospital capital expenditure patterns. Forecast inputs included FDA clearance timelines, cloud infrastructure cost trajectories, and academic medical center neuroinformatics platform deployment rates.
Material uncertainties — FDA predicate device policy reversals, hyperscaler cloud pricing volatility, and EU MDR clinical evidence requirement extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway stability and hospital IT modernization budgets. Revision becomes warranted when FDA enforcement discretion boundaries for clinical decision support software cross clarity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
US Optic Neuritis Market
Neurology
AIDS Related Primary CNS Lymphoma Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
Global Sciatica Treatment Market
Neurology
India Neurology Devices Market
Neurology
Pediatric Neurology Device Market
Neurology
Neurological Biomarkers Market
Neurology
Spasticity Treatment Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
CNS Lymphoma Market
Neurology
Aneurysmal Subarachnoid Hemorrhage Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Global Vertigo Treatment Market
Neurology
Spinal Laminoplasty Market