
 Aneurysmal Subarachnoid Hemorrhage Market | 2026-2036
Aneurysmal Subarachnoid Hemorrhage Market Size, Share, and Industry Trends Forecast 2026-2036
Aneurysmal Subarachnoid Hemorrhage Market Analysis
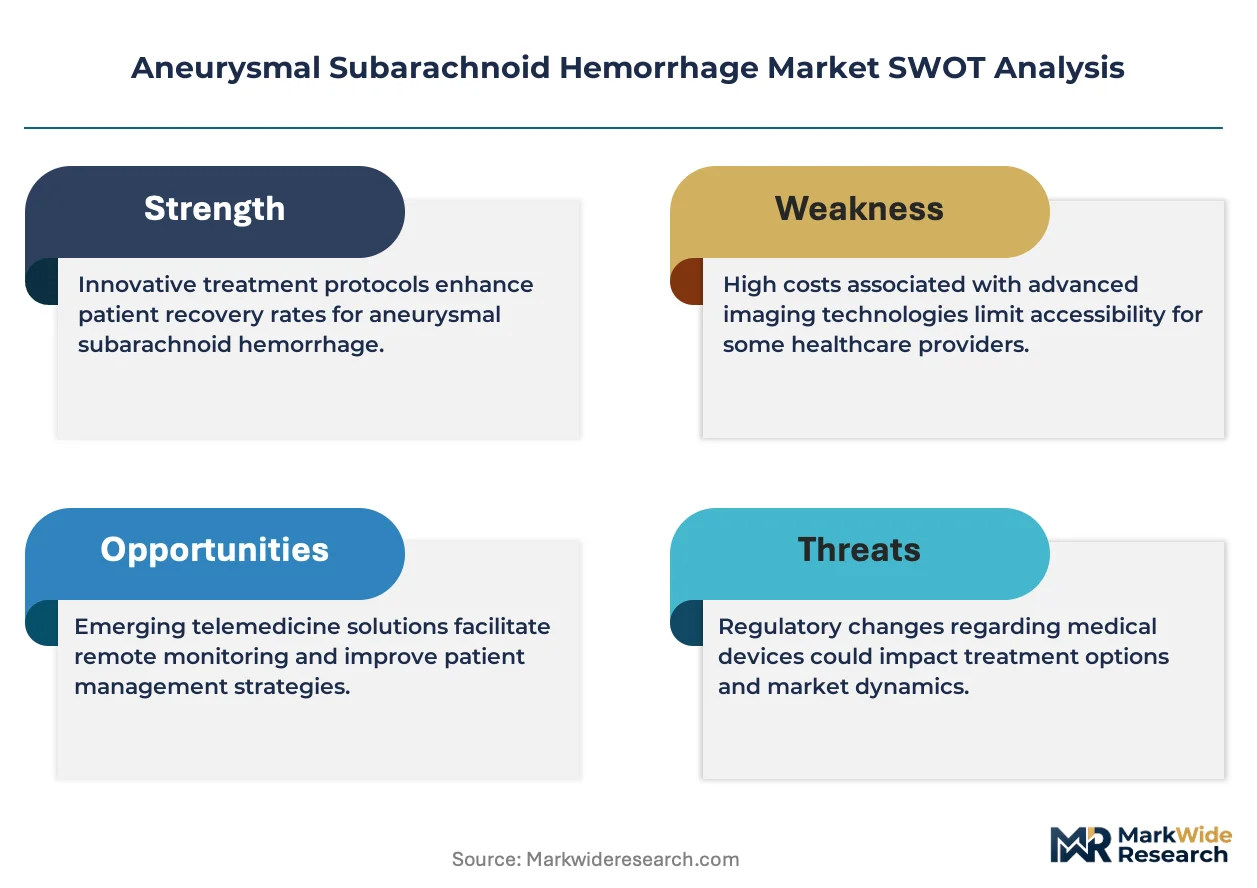
The EU Medical Device Regulation is expanding compliance requirements for neurovascular implantables, compelling manufacturers to intensify clinical evidence generation. Medtronic leverages its integrated neuroscience portfolio to sustain leadership across clipping and coiling modalities. Stryker Neurovascular anchors its position through specialized flow diversion platforms that dominate the high-acuity segment. Johnson & Johnson competes by extending its reach from pharmaceutical adjuncts into procedural device ecosystems.
Aneurysmal subarachnoid hemorrhage denotes bleeding into the subarachnoid space resulting from ruptured intracranial aneurysms, typically requiring endovascular coiling with platinum-alloy embolic coils or surgical clipping with titanium aneurysm clips to prevent rebleeding and manage vasospasm. Coiling systems currently occupy the largest product category as minimally invasive approaches displace open craniotomy in eligible cases, while flow diversion devices represent the fastest-expanding segment driven by expanding indications for complex wide-neck aneurysms that resist conventional reconstruction. Hospitals capture the dominant end-user share due to the requisite neurocritical care infrastructure, though academic clinics concentrate the most complex case volumes and trial enrollment.
FDA enforces rigorous premarket approval pathways for neurovascular devices under 21 CFR 882, while EMA's MDR framework demands enhanced post-market surveillance and unique device identification across European member states. Japan's PMDA maintains distinct consultation routes for innovative neurointerventional products that streamline review for breakthrough mechanisms. Stakeholders must monitor evolving reimbursement thresholds for flow diversion procedures across national health technology assessment bodies.
Market Dynamics
Flow diversion technologies are compressing treatment paradigms for wide-neck and fusiform aneurysms that resist conventional coiling, while MDR compliance costs in Europe are forcing mid-tier manufacturers to consolidate clinical evidence programs ahead of notified body capacity constraints.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for neurovascular innovations are accelerating commercialization of next-generation flow diverters and intrasaccular devices.
- Academic Medical Center Expansion:Neurointerventional fellowship programs in the United States, Germany, and Japan are expanding the specialist workforce capable of deploying advanced endovascular techniques.
- Platinum-Alloy Coil Refinement:Enhanced embolic density and controlled detachment mechanisms are improving aneurysm occlusion rates and reducing retreatment incidence.
Market Restraints
- Palladium Price Volatility:Platinum-ruthenium and platinum-tungsten alloy feedstocks face supply concentration from South African and Russian mining operations, compressing coil manufacturing margins.
- Notified Body Bottlenecks:EU MDR recertification queues for Class III implantables are extending market access timelines by 18-24 months for emerging manufacturers.
- Surgical Clipping Persistence:Younger patient cohorts with accessible anterior circulation aneurysms continue to select microsurgical clipping for durable occlusion without antiplatelet burden.
Strategic Opportunities
- Brazilian Neurovascular Infrastructure:ANVISA regulatory harmonization with FDA precedents is opening procedural adoption in São Paulo and Rio de Janeiro academic centers previously dependent on surgical clipping.
- Artificial Intelligence-Enabled Aneurysm Detection:Machine learning algorithms integrated into CT angiography workflows are identifying unruptured aneurysms earlier, expanding the addressable patient pool.
- Bioresorbable Flow Modulators:Magnesium-based scaffolding technologies that dissolve after endothelialization represent a convergence of metallurgy and vascular biology.
Industry Challenges
- Neurointerventionalist Training Pipeline:The extended learning curve for flow diversion deployment—typically 50-100 supervised cases—limits adoption velocity in community hospital settings.
- Post-Market Surveillance Infrastructure:MDR-mandated implant registries and unique device identification tracking require manufacturers to rebuild quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aneurysmal Subarachnoid Hemorrhage Market |
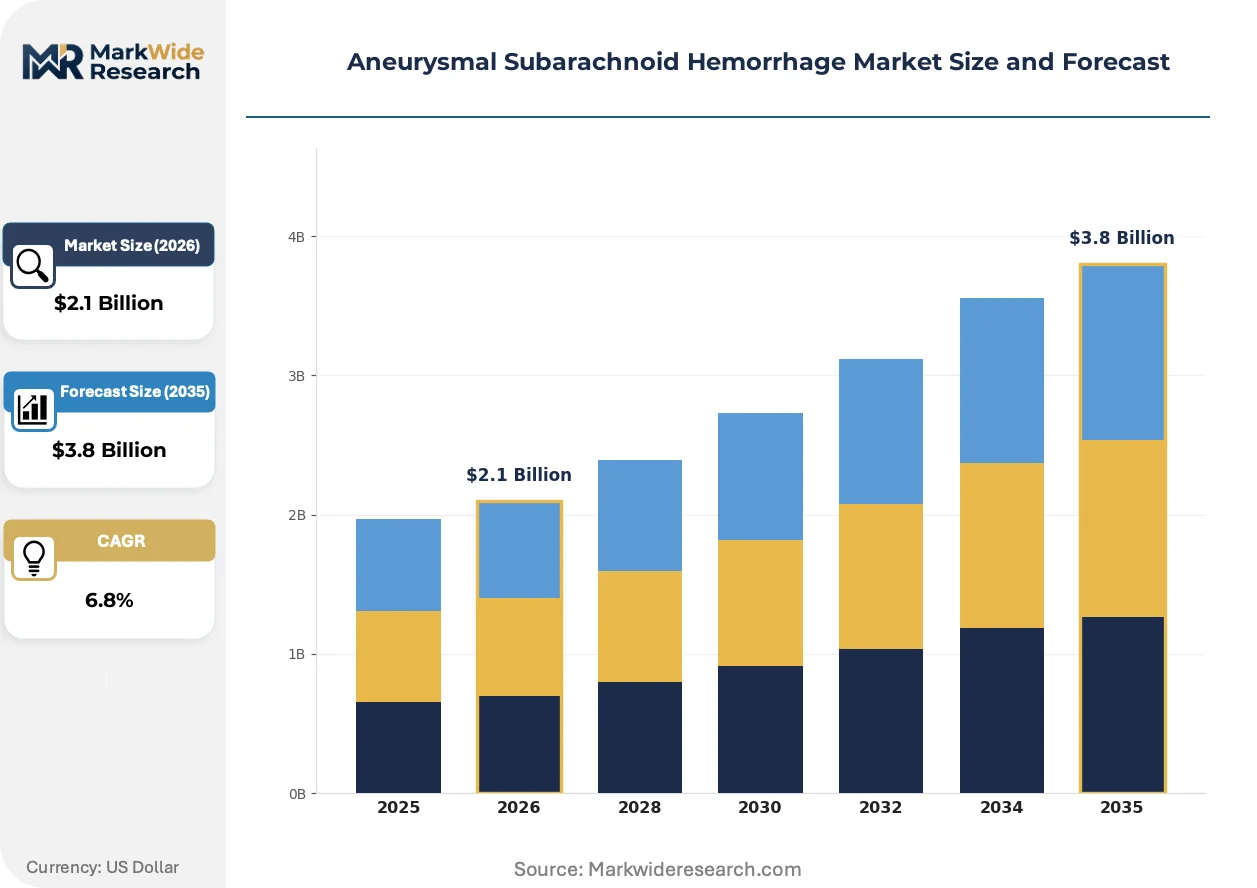
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clipping Devices, Coiling Systems, Flow Diversion Devices, Other Endovascular Tools End User: Hospitals, Surgical Centers, Academic Clinics, Outpatient Facilities Delivery Mode: Intravenous, Intra-arterial, Oral, Other Delivery Methods Indication: Aneurysm Repair, Monitoring, Post-Operative Care, Clinical Trials |
| Companies Covered | Medtronic, Stryker Neurovascular, Johnson & Johnson, Pfizer, Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Idorsia Pharmaceuticals Ltd., Arbor Pharmaceuticals, Edge Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aneurysmal Subarachnoid Hemorrhage Market Emerging Trajectories
Endovascular platforms are fragmenting into specialized modalities for aneurysm morphology, while regulatory frameworks on both sides of the Atlantic are tightening evidentiary standards for permanent implants.
Intrasaccular flow disruption using braided nitinol mesh constructs is electrifying treatment protocols for bifurcation aneurysms at the middle cerebral artery and basilar tip. Academic centers in the United States and Germany are adopting these devices for cases where stent-assisted coiling would require dual antiplatelet therapy. The technology is electrifying the shift toward aneurysm reconstruction rather than parent vessel sacrifice in complex geometries.
EMA's Medical Device Regulation is demanding prospective clinical data for neurovascular implantables previously cleared under the Medical Device Directive's equivalence pathway. Manufacturers must now sponsor post-market clinical follow-up studies with minimum two-year imaging endpoints. High-acuity flow diversion platforms face the steepest compliance burden, with several products withdrawn from European markets pending evidence generation.
Hospital purchasing committees are consolidating neurovascular device contracts into single-source agreements with procedure-volume guarantees. Integrated delivery networks in the United States are replacing physician-preferred item flexibility with standardized coil and stent inventories. This concentration is most visible in Texas and Florida health systems where neurointerventional case volumes justify dedicated supply chain negotiations.
Aneurysmal Subarachnoid Hemorrhage Market Segmentation
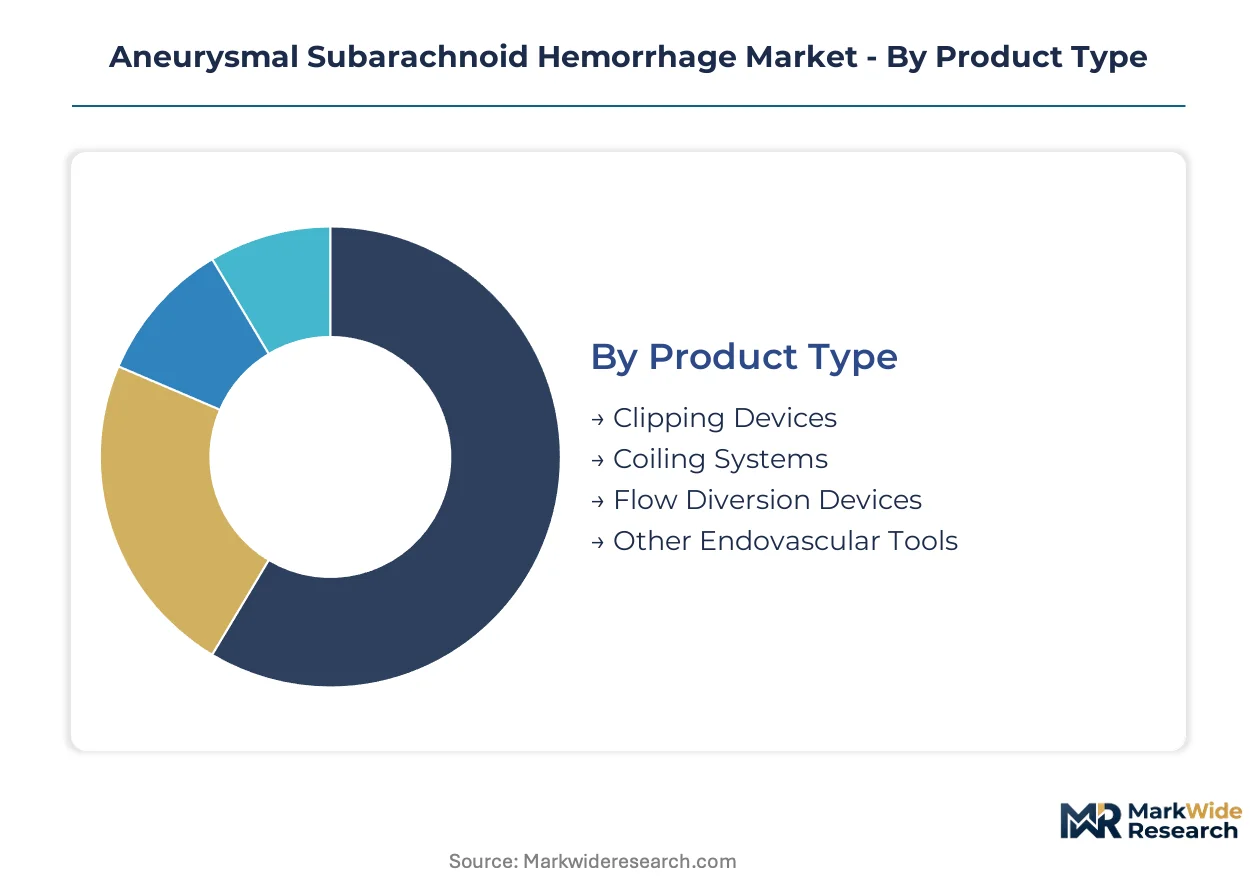
Neurovascular device segmentation tracks the migration from open surgical intervention toward endovascular reconstruction, with each category reflecting distinct technical competencies and capital intensity requirements. Product type stratification captures the rivalry between durable mechanical occlusion and biologically-mediated flow modulation, while end-user categories map the concentration of complex case volumes against ambulatory expansion.
Product Type:
Volume concentration remains with established platinum-alloy technologies, while premium expansion concentrates in braided mesh platforms that command higher reimbursement per procedure.
- Clipping Devices:Titanium and cobalt-chromium aneurysm clips deliver immediate mechanical occlusion through microsurgical craniotomy. Demand persists in Germany and Japan where academic neurosurgical departments maintain clipping proficiency for younger patients with accessible anterior circulation anatomy.
- Coiling Systems:Platinum-tungsten and platinum-ruthenium embolic coils achieve aneurysm thrombosis through minimally invasive transfemoral access. Hospitals in the United States deploy these systems for the majority of ruptured aneurysm presentations, driven by interventionalist workforce expansion and reduced ICU length of stay versus open surgery.
- Flow Diversion Devices:Braided nitinol or cobalt-chromium pipeline constructs reconstruct parent vessel hemodynamics across wide-neck aneurysm necks. Academic centers in the United States and Germany are the primary adoption sites for these high-acuity platforms.
- Other Endovascular Tools:Balloon remodeling catheters, micro-guidewires, and distal access delivery sheaths complete procedural ecosystems.
Mature deployment sits with Coiling Systems. Newer deployment is concentrated in Flow Diversion Devices.
End User:
Case complexity and reimbursement adequacy split demand between high-volume comprehensive centers and emerging ambulatory sites.
- Hospitals:Integrated neurocritical care units, biplane angiography suites, and 24-hour neurosurgical coverage define the infrastructure for emergency subarachnoid hemorrhage management. Academic medical centers in the United States, Germany, and Japan capture the most complex fusiform and giant aneurysm volumes.
- Surgical Centers:Standalone facilities with neurointerventional capabilities are expanding in Texas and Florida health systems where elective unruptured aneurysm screening drives procedural volume.
- Academic Clinics:University-affiliated outpatient sites concentrate clinical trial enrollment and complex case referral networks.
- Outpatient Facilities:Limited to stable post-operative surveillance and antiplatelet monitoring rather than acute intervention.
Revenue concentration aligns with Hospitals. Capacity expansion is accelerating fastest in Surgical Centers.
Delivery Mode:
Route selection follows anatomic targeting precision, with arterial access dominating device deployment and intravenous routes reserved for adjunctive pharmaceutical therapy.
- Intravenous:Nimodipine infusion for vasospasm prophylaxis and antiplatelet loading doses precede or follow endovascular procedures.
- Intra-arterial:Direct catheter-based delivery of embolic coils, flow diverters, and intra-saccular devices into the cerebral vasculature represents the dominant therapeutic modality.
- Oral:Dual antiplatelet regimens following stent-assisted coiling or flow diversion require structured outpatient pharmacy protocols.
- Other Delivery Methods:Intrathecal routes for refractory vasospasm and intra-cisternal thrombolysis occupy niche rescue indications.
Standard practice centers on Intra-arterial delivery. Adjunctive expansion is occurring in Oral antiplatelet protocols.
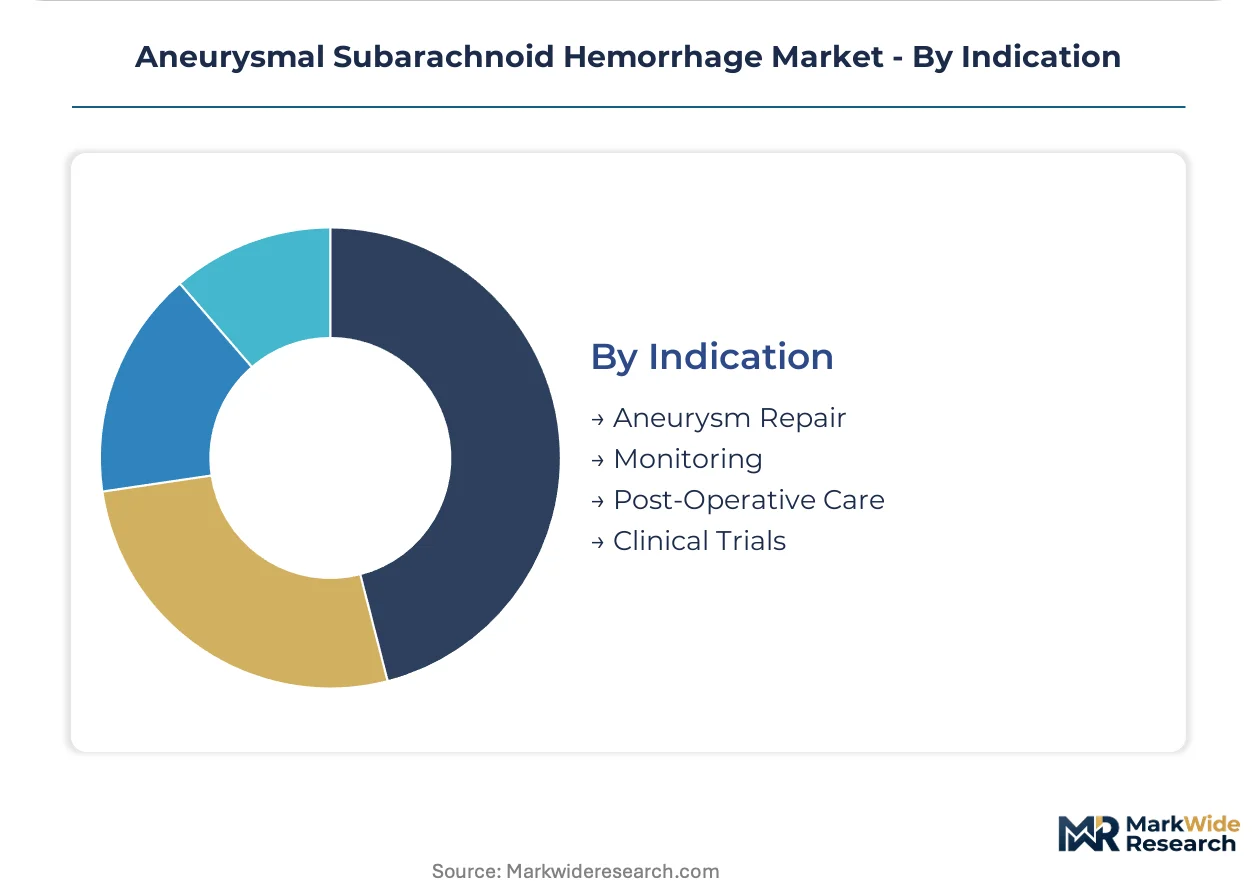
Indication:
Therapeutic intent separates emergent hemorrhage control from elective reconstruction and longitudinal surveillance.
- Aneurysm Repair:Endovascular coiling, surgical clipping, or flow diversion to secure ruptured or unruptured aneurysms and prevent rebleeding. United States hospitals generate the highest procedural volumes for both emergent subarachnoid hemorrhage and incidental unruptured detection.
- Monitoring:Serial CT angiography, MR angiography, and digital subtraction angiography surveillance detect recurrence or de novo formation. Academic Clinics in Germany and Japan maintain structured imaging protocols with standardized volumetric measurement techniques.
- Post-Operative Care:Neurocritical care management of vasospasm, hydrocephalus, and delayed cerebral ischemia following aneurysm securing.
- Clinical Trials:Prospective enrollment in device investigational studies and post-market surveillance registries mandated by FDA and EMA frameworks.
Established volume resides in Aneurysm Repair. Protocol investment is deepening fastest in Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors neurovascular innovation density, with Massachusetts General Hospital and Brigham and Women's Hospital driving flow diversion adoption rates that exceed national benchmarks by considerable margins.
United States
Academic medical centers in Boston, Baltimore, and Phoenix generate the highest procedural volumes for complex wide-neck aneurysms. FDA breakthrough device designations under 21 CFR 882 compress review timelines for braided nitinol platforms. Texas and Florida health systems are consolidating neurovascular device contracts into single-source agreements with volume guarantees.
Germany
University hospitals in Munich, Heidelberg, and Berlin maintain microsurgical clipping proficiency alongside endovascular expansion. EMA's MDR framework demands enhanced post-market surveillance with two-year imaging endpoints for Class III implantables. The Bavarian medical technology cluster around Nuremberg supplies precision nitinol braiding equipment to device manufacturers.
Japan
PMDA consultation routes for innovative neurointerventional products streamline regulatory review for Tokyo and Osaka academic centers. The country's aging demographic concentrates unruptured aneurysm detection through widespread CT angiography screening protocols. Kyushu University Hospital leads prospective registries tracking long-term flow diversion outcomes.
Brazil
ANVISA regulatory harmonization with FDA precedents accelerates procedural adoption in São Paulo and Rio de Janeiro academic centers. Private hospital networks in these metros are investing in biplane angiography suites previously limited to public university hospitals. The southeastern corridor captures the majority of South American neurointerventional training fellowships.
United Kingdom
NICE health technology assessments determine reimbursement thresholds for flow diversion procedures across NHS England trusts. London's National Hospital for Neurology and Neurosurgery anchors the country's complex case referral network. Manchester and Birmingham are expanding interventional neurology departments to reduce transfer burdens on the capital.
Aneurysmal Subarachnoid Hemorrhage Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and clinical evidence generation capabilities. The vendor base stratifies into integrated neuroscience conglomerates, specialized neurovascular pure-plays, and pharmaceutical adjunct providers. Three archetypes dominate: diversified medtech platforms with interventional portfolios, focused flow diversion specialists with academic center penetration, and pharma-device hybrid strategists extending from drug delivery into procedural ecosystems. Competitive moves concentrate on M&A for regulatory dossier accumulation and strategic partnerships for notified body capacity access.
Within the integrated platform tier, Medtronic and Stryker Neurovascular exemplify divergent specialization strategies. Medtronic leverages cross-modal presence across clipping and coiling modalities to sustain leadership in comprehensive aneurysm treatment ecosystems. Stryker Neurovascular anchors premium positioning through dedicated flow diversion platforms that dominate high-acuity academic center procurement. Johnson & Johnson occupies a hybrid position, extending pharmaceutical adjunct expertise into procedural device integration.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Neurovascular |
| Johnson & Johnson |
| Pfizer |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Idorsia Pharmaceuticals Ltd. |
| Arbor Pharmaceuticals |
| Edge Therapeutics |
| Others |
Supply Flow & Price Mechanics
Flow diversion manufacturing migration from hand-braided nitinol to automated laser-cut stents compresses unit economics while redistributing supplier power toward precision metallurgy houses in Germany and Japan. This transition simultaneously elevates FDA premarket approval costs and consolidates purchasing leverage among integrated delivery networks demanding volume-based contract structures.
Pricing Analysis
Procedure reimbursement thresholds set by CMS and NICE anchor value-based pricing for flow diversion platforms, with academic medical centers capturing premium rates for complex wide-neck cases while community hospitals face compressed margins on standard coiling. Price differentiation hinges on clinical evidence depth and dual antiplatelet therapy requirements. Cost compression in platinum-alloy feedstocks is intensifying because palladium price volatility from South African supply disruptions. Community hospital purchasing committees exhibit highest price sensitivity; academic centers with trial enrollment privileges show lowest.
Supply Chain Analysis
Dual-sourcing mandates from GPOs and hospital purchasing committees require qualified secondary suppliers for nitinol wire and platinum-tungsten alloys, extending qualification timelines. Manufacturing concentrates in the United States, Germany, and Ireland for final device assembly, with raw material dependencies on South African platinum group metals, Chinese nitinol wire, and Japanese precision braiding equipment. Single-source vulnerability sits with South African palladium-ruthenium ore concentration. Distribution runs through specialized neurovascular distributors with cath lab direct delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EMA MDR compliance costs and FDA premarket approval barriers force mid-tier manufacturers without notified body relationships toward exit or acquisition.
For Market Incumbents: Cement leadership by acquiring European regulatory dossiers from cash-constrained competitors facing MDR recertification queues. Deepen backward integration into precision nitinol braiding through captive supply agreements with Nuremberg-area equipment manufacturers. The threat of Brazilian and Indian emerging manufacturers with ANVISA harmonization advantages demands proactive capacity positioning.
For New Entrants and Emerging Players: The price-point gap between premium flow diversion and economy coiling systems offers white-space targeting for intrasaccular disruption devices with reduced antiplatelet burdens. Brazil's southeastern corridor presents the most penetrable geography where ANVISA-FDA harmonization accelerates procedural adoption previously limited to surgical clipping. A focused go-to-market angle centers on neurointerventional fellowship training partnerships to compress the 50-100 case learning curve.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated neuroscience conglomerates seeking regulatory dossier accumulation. Long-term viability favors targets with established MDR technical documentation and FDA 510(k) predicate libraries rather than pre-revenue platforms. The signal to watch is notified body capacity expansion announcements from TÜV SÜD and BSI, which would decompress European market access timelines and revalue acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses commercialization timelines for braided nitinol platforms by 12-18 months. |
| Hospital System Partnership | Single-source agreements with Texas and Florida IDNs lock in procedure-volume guarantees and coil standardization. |
| CE Marking Pathway | MDR technical documentation investment separates viable European players from withdrawn product portfolios. |
| Software Companion Development | AI-enabled aneurysm detection algorithms expand addressable patient pools through CT angiography integration. |
| Reimbursement Strategy | NICE health technology assessments determine NHS England flow diversion adoption thresholds. |
Methodological Framework
FDA 510(k) and PMA filings, EMA MDR technical documentation databases, and hospital procurement contract records formed the secondary backbone. Primary interviews with neurointerventionalists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers validated volume assumptions. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against procedure registry counts.
Bottom-up modeling anchored volume projections across the analysis window, with top-down macro validation from national health expenditure trajectories. Segmentation dimensions included product type, end-user category, delivery mode, and indication severity. CAGRs derived from procedure volume elasticity to interventionalist workforce expansion and platinum price regression models.
Inputs from FDA premarket databases and EMA notified body registers were available through the study window; gaps in real-time hospital purchasing contract terms introduce uncertainty bands around pricing assumptions. Deviation in palladium group metal supply disruptions or MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Brazil Neurology Devices Market
Neurology
CNS Treatment and Therapy Market
Neurology
Neuropsychiatric Disorders and Treatment Market
Neurology
Sweden Neurology Devices Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
Mexico Neurology Devices Market
Neurology
India Neurology Devices Market
Neurology
Vocal Cord Paralysis Market
Neurology
Pediatric Neurology Device Market
Neurology
Europe Neurology Monitoring Market
Neurology
Chile Neurology Devices Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Transverse Myelitis Treatment Market
Neurology
UAE Neurology Devices Market
Neurology
South America Neurology Monitoring Market