
 High Energy Shockwave Therapy Units Market | 2026-2036
High Energy Shockwave Therapy Units Market Size, Share, and Industry Trends Forecast 2026-2036
High Energy Shockwave Therapy Units Market Foresight
Equipment leasing and pay-per-procedure financing is rewriting competitive access for mid-size physiotherapy clinics. STORZ MEDICAL AG leverages its Swiss manufacturing base to sustain premium positioning in electromagnetic systems. Dornier MedTech anchors its presence in urological and orthopedic applications through specialized clinical training networks. EMS Electro Medical Systems competes by extending distribution partnerships across European rehabilitation centers.
High energy shockwave therapy units generate acoustic pulses above 0.1 mJ/mm² through electromagnetic or piezoceramic transducers to induce localized mechanical stress and microtrauma in musculoskeletal tissue, triggering angiogenesis and collagen remodeling for non-invasive pain management and tissue regeneration. Focused shockwave systems command the highest margin pools due to precise depth targeting for calcific tendinitis and bone stress injuries, while portable units represent the fastest-expanding segment as ambulatory sports clinics seek point-of-care deployment flexibility. Combination devices that integrate radial and focused modalities occupy a growing niche among multi-disciplinary rehabilitation hospitals seeking capital efficiency.
The FDA classifies these units as Class II medical devices requiring 510(k) premarket notification, while the EU MDR demands enhanced post-market surveillance and clinical performance data for CE marking renewal. Germany's national reimbursement framework through the Institut für das Entgeltsystem im Krankenhaus shapes hospital procurement timelines and technology adoption cycles. Stakeholders must monitor evolving evidence requirements from both regulators and determine whether to prioritize electromagnetic platform refinement or pneumatic cost reduction for emerging clinic segments.
Market Dynamics
Equipment leasing and pay-per-procedure financing models are compressing capital barriers for mid-size physiotherapy clinics, forcing manufacturers to restructure pricing architectures around utilization-based revenue streams rather than upfront unit sales.
Growth Catalysts
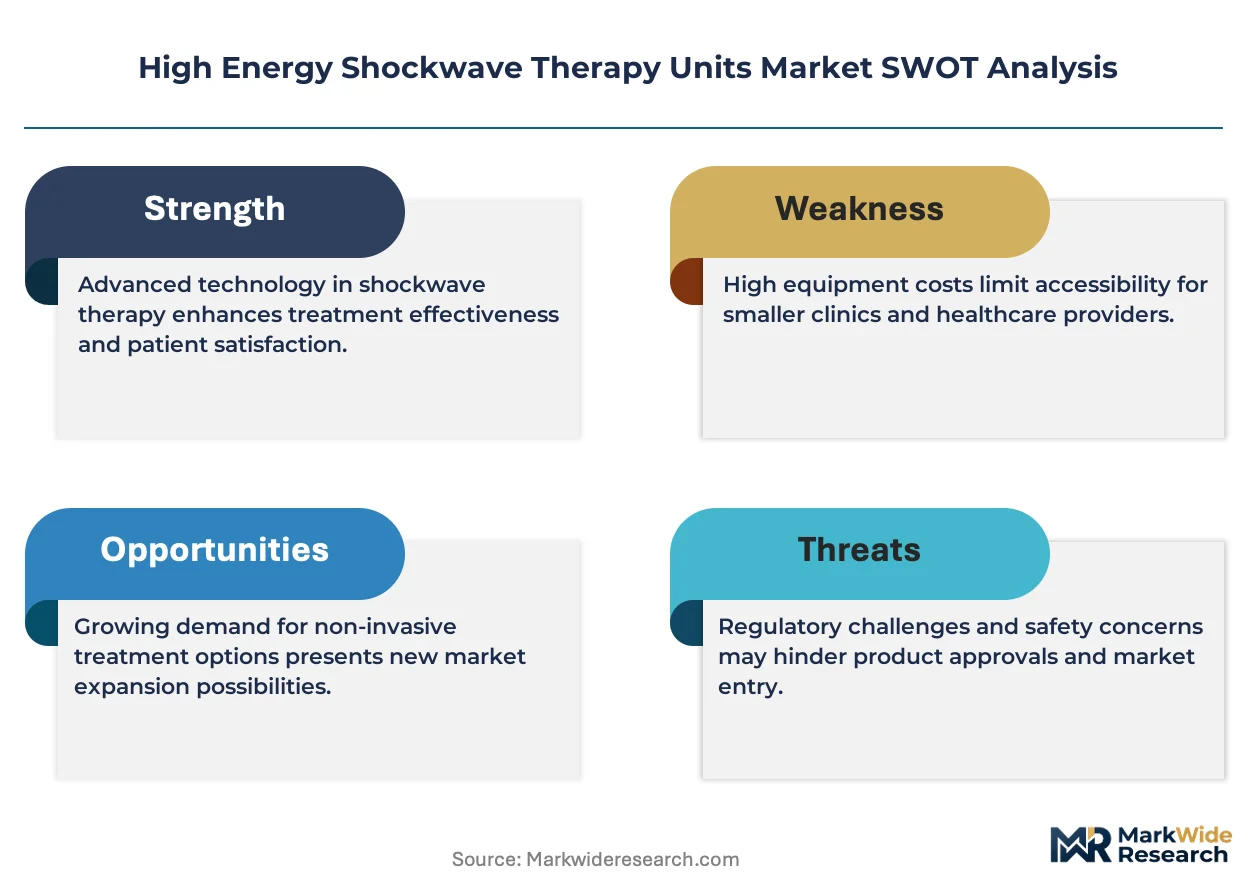
- EU MDR clinical evidence mandates:The Medical Device Regulation's tightened post-market surveillance requirements are filtering out marginal competitors, concentrating procurement among validated suppliers in German orthopedic rehabilitation centers.
- Calcific tendinitis protocols:Sports medicine departments in Swiss university hospitals are standardizing focused shockwave interventions for rotator cuff conditions, driving repeat system deployments.
- Piezoceramic transducer miniaturization:Advances in ceramic array manufacturing are enabling portable unit development for ambulatory deployment in South Korean clinic chains.
Market Restraints
- Electromagnetic coil supply concentration:Precision copper winding fabrication for high-energy generators clusters in Southern German industrial zones, creating single-source vulnerability for electromagnetic platform manufacturers.
- FDA 510(k) notification timelines:Class II device premarket review durations for acoustic pulse parameter modifications extend commercialization cycles for next-generation focal depth systems.
- Radial pressure wave substitution:Lower-cost pneumatic ballistic devices capture price-sensitive tendonitis cases in cash-pay physiotherapy segments, pressuring premium electromagnetic unit volumes.
Strategic Opportunities
- Veterinary orthopedic expansion:Equine sports medicine practices in Kentucky and Baden-Württemberg represent unserved demand for portable focused systems in tendon and ligament regeneration protocols.
- Combination modality integration:Radial-focused hybrid platforms enable capital-efficient single-unit procurement for multi-disciplinary rehabilitation hospitals consolidating device footprints.
- Institut für das Entgeltsystem im Krankenhaus reimbursement alignment:Germany's hospital payment framework revisions for outpatient musculoskeletal procedures incentivize shockwave adoption in integrated care networks.
Industry Challenges
- Clinical training bandwidth constraints:Specialized operator certification for focal zone targeting in calcific deposits requires extended proctoring periods, slowing deployment velocity in expanding clinic chains.
- CE marking renewal documentation:EU MDR Article 86 post-market clinical follow-up data compilation demands dedicated regulatory affairs staffing that mid-tier manufacturers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Energy Shockwave Therapy Units Market |
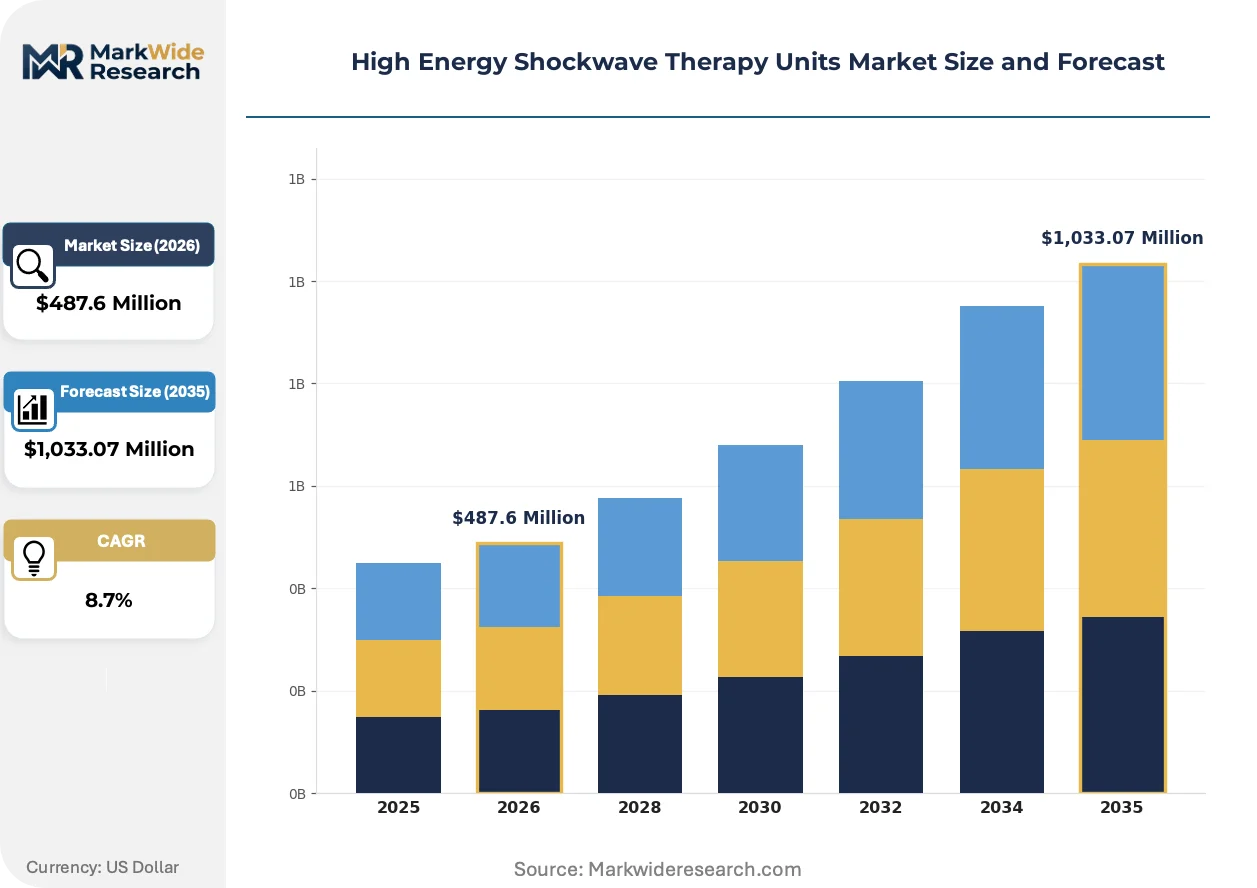
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Shockwave, Focused Shockwave, Combination Devices, Portable Units Technology: Piezoceramic, Electromagnetic, Pneumatic, Others Application: Musculoskeletal Disorders, Rehabilitation, Sports Injuries, Aesthetic Medicine End User: Hospitals, Rehabilitation Centers, Physiotherapy Clinics, Sports Clinics |
| Companies Covered | Siemens Healthineers AG, Dornier MedTech, STORZ MEDICAL AG, Zimmer MedizinSysteme, BTL Industries, EMS Electro Medical Systems, Inceler Medikal Co Ltd, Lumenis Ltd, EDAP TMS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Energy Shockwave Therapy Units Market Shifts & Advancements
Acoustic pulse generation architectures are fragmenting across electromagnetic, piezoceramic, and electrohydraulic principles, with each technology path optimizing for distinct clinical depth and energy density requirements rather than converging on a single dominant standard.
Electromagnetic shockwave generation is migrating from fixed-site hospital installations toward portable configurations. Ambulatory sports medicine clinics in Germany and South Korea are adopting battery-coupled electromagnetic platforms for pitch-side and trackside deployment. This migration is compressing the addressable market for traditional cart-based systems while expanding total procedure volumes through point-of-care accessibility.
REACH substance restrictions on piezoelectric ceramics containing lead zirconate titanate are forcing reformulation of transducer materials for European market access. Manufacturers are accelerating barium titanate and potassium sodium niobate alternative development to maintain CE marking compliance. Swiss and German component suppliers are absorbing the highest compliance costs, passing through material premiums to system integrators.
Hospital procurement committees are unbundling device acquisition from mandatory service contracts, forcing manufacturers to price maintenance and calibration separately. German rehabilitation center chains are piloting third-party technical service agreements for electromagnetic coil replacement and acoustic lens refurbishment. This unbundling is most advanced in North Rhine-Westphalia and Bavaria, where purchasing cooperatives negotiate multi-vendor maintenance frameworks.
High Energy Shockwave Therapy Units Market Segmentation
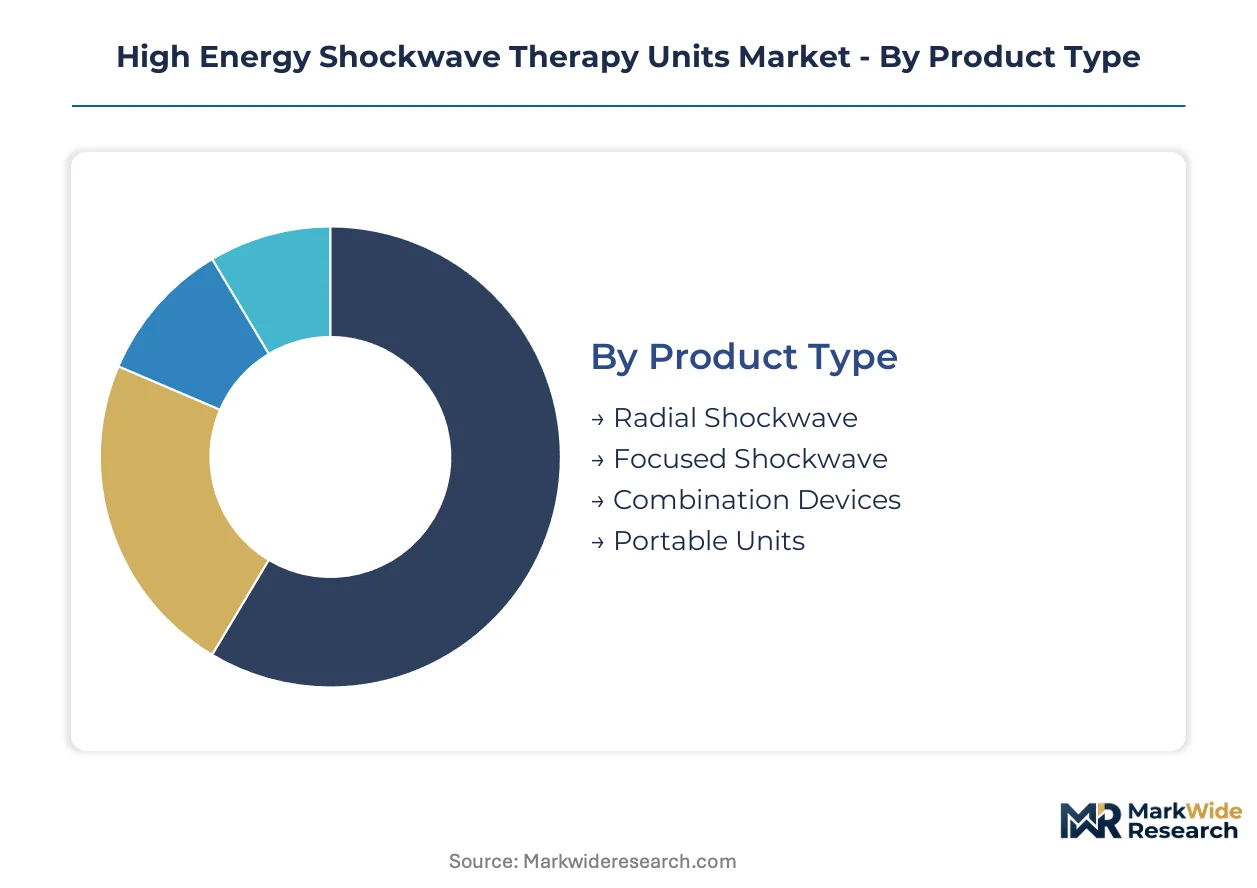
Segmentation in high energy shockwave therapy units reveals how acoustic pulse generation methods, clinical deployment settings, and reimbursement pathways fragment procurement patterns across healthcare systems. Manufacturers must align platform architectures with specific depth-energy requirements and capital constraints of distinct user categories.
Product Type:
Clinical use cases span superficial tendon treatments to deep bone stress injuries, demanding divergent focal precision and energy density specifications.
- Focused Shockwave:Electromagnetic or piezoceramic transducers generate convergent acoustic pulses exceeding 0.1 mJ/mm² for precise depth targeting. German orthopedic rehabilitation centers and Swiss university hospitals prioritize these systems for calcific tendinitis protocols, where focal zone accuracy determines clinical outcomes and repeat procedure rates.
- Portable Units:Battery-coupled electromagnetic platforms enable ambulatory deployment outside traditional clinical settings. South Korean physiotherapy clinic chains and German sports medicine practices are expanding procurement for pitch-side accessibility, compressing the addressable market for cart-based installations while expanding total procedure volumes.
- Radial Shockwave:Pneumatic ballistic mechanisms deliver divergent pressure waves for superficial musculoskeletal conditions.
- Combination Devices:Integrated radial-focused hybrid platforms serve multi-disciplinary rehabilitation hospitals seeking capital efficiency through single-unit procurement.
Established volume favors focused shockwave systems in hospital settings; emerging adoption favors portable units in ambulatory and sports clinic deployments.
Technology:
Cost tiers separate precision electromagnetic platforms from accessible pneumatic alternatives, with material compliance costs reshaping European supplier economics.
- Electromagnetic:High-energy copper coil generators deliver consistent acoustic pulse parameters for clinical reliability. Southern German industrial zones concentrate precision winding fabrication, creating supply vulnerability that STORZ MEDICAL AG and Dornier MedTech navigate through captive supplier relationships and inventory buffers.
- Piezoceramic:Ceramic array transducers enable miniaturization for portable configurations. REACH substance restrictions on lead zirconate titanate are forcing Swiss and German component suppliers toward barium titanate reformulations, passing material premiums to system integrators.
- Pneumatic:Ballistic pressure wave generation offers lower capital entry points for price-sensitive clinic segments.
- Others:Electrohydraulic principles persist in specialized urological applications requiring specific pulse characteristics.
Margin concentration sits with electromagnetic platforms; volume expansion is climbing the fastest in piezoceramic miniaturization for portable deployment.
Application:
Reimbursement alignment and clinical evidence depth determine adoption velocity across therapeutic domains.
- Musculoskeletal Disorders:Non-invasive pain management for tendonopathies and bone stress injuries represents the foundational clinical indication. Germany's Institut für das Entgeltsystem im Krankenhaus reimbursement framework for outpatient musculoskeletal procedures directly shapes hospital procurement timelines for shockwave adoption in integrated care networks.
- Sports Injuries:Acute and overuse conditions in athletic populations drive point-of-care deployment requirements. Swiss university hospitals are standardizing focused shockwave interventions for rotator cuff conditions, establishing protocol templates that diffuse through European sports medicine departments.
- Rehabilitation:Post-surgical and chronic condition management protocols in specialized centers.
- Aesthetic Medicine:Cellulite and tissue remodeling applications with variable regulatory classification across jurisdictions.
Reimbursement stability favors musculoskeletal applications; protocol innovation favors sports injury segments.
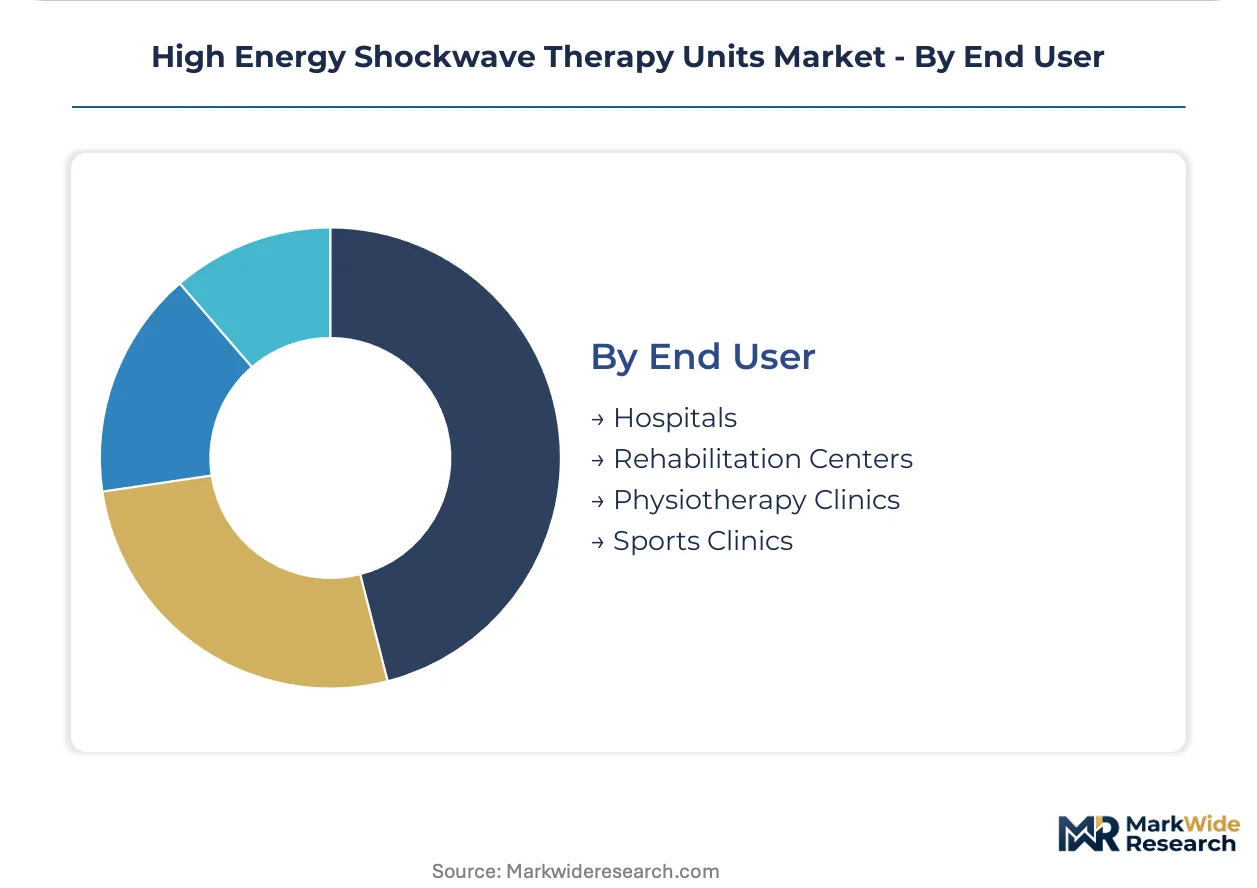
End User:
Customer type differentiation separates capital-intensive hospital procurement from utilization-sensitive clinic financing models.
- Physiotherapy Clinics:Mid-size clinic chains in Germany, Switzerland, and South Korea are driving equipment leasing and pay-per-procedure financing adoption. This restructuring of pricing architectures around utilization-based revenue streams is compressing capital barriers and expanding addressable clinic segments beyond traditional hospital purchasers.
- Rehabilitation Centers:Specialized orthopedic and neurological facilities require combination modality platforms for diverse patient populations. North Rhine-Westphalia and Bavaria purchasing cooperatives are piloting third-party technical service agreements, unbundling device acquisition from mandatory manufacturer service contracts.
- Hospitals:Academic medical centers with research mandates and integrated care networks.
- Sports Clinics:Ambulatory facilities serving athletic populations with point-of-care deployment requirements.
Procurement volume concentrates in physiotherapy clinic chains; margin protection concentrates in rehabilitation center service contract structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in high energy shockwave therapy units tilt toward net manufacturing surplus in German-speaking Europe and net import dependence in East Asian clinic chains. Switzerland and Germany supply precision electromagnetic platforms to South Korean physiotherapy networks while importing specialized piezoceramic arrays from Japanese component fabricators.
Germany
Orthopedic rehabilitation centers in North Rhine-Westphalia and Bavaria are expanding focused shockwave procurement through purchasing cooperatives. The Institut für das Entgeltsystem im Krankenhaus reimbursement framework for outpatient musculoskeletal procedures directly shapes hospital adoption timelines. Southern German industrial zones around Stuttgart concentrate precision copper winding fabrication for electromagnetic generators, creating captive supply relationships with STORZ MEDICAL AG.
Switzerland
Swiss university hospitals in Zurich and Geneva are standardizing calcific tendinitis protocols using focused shockwave interventions for rotator cuff conditions. Swissmedic maintains stringent clinical evidence requirements for CE marking renewal under EU MDR alignment. The Lake Geneva corridor hosts electromagnetic system manufacturing operations serving premium-tier European rehabilitation centers.
South Korea
Physiotherapy clinic chains in Seoul and Busan are driving portable unit adoption through equipment leasing models. The Ministry of Food and Drug Safety (MFDS) regulates high energy shockwave devices as Class III medical products requiring premarket approval. Daegu-Gyeongbuk region hosts assembly operations for battery-coupled electromagnetic platforms targeting ambulatory sports medicine deployment.
United States
Sports medicine practices in Kentucky and Florida represent emerging demand for veterinary orthopedic applications in equine tendon regeneration. The FDA 510(k) premarket notification pathway for Class II acoustic pulse devices extends commercialization timelines for focal depth system modifications. The Ohio River Valley corridor concentrates distribution partnerships serving mid-size physiotherapy clinic networks.
Japan
Piezoceramic transducer manufacturers in Nagoya and Osaka supply ceramic arrays for portable unit miniaturization across Asia-Pacific markets. The Pharmaceuticals and Medical Devices Agency (PMDA) requires clinical performance data for regenerative medicine device approvals. The Chubu region maintains specialized fabrication capabilities for lead-free barium titanate formulations responding to REACH substance restrictions.
High Energy Shockwave Therapy Units Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in electromagnetic coil and piezoceramic transducer fabrication. The vendor structure concentrates around three to five validated suppliers in European hospital procurement while fragmenting across regional distributors in Asian clinic markets. Electromagnetic platform manufacturers and pneumatic ballistic device fabricators represent distinct strategic archetypes with divergent margin profiles. Competitive dynamics center on technology licensing arrangements for focal depth precision and geographic expansion through third-party technical service partnerships.
Within the electromagnetic platform tier, STORZ MEDICAL AG and Dornier MedTech exemplify premium positioning through Swiss and German manufacturing heritage. EMS Electro Medical Systems occupies a position emphasizing European distribution breadth across rehabilitation center networks. These three anchors illustrate how validated clinical training networks and captive supplier relationships differentiate procurement outcomes in German orthopedic rehabilitation centers.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Dornier MedTech |
| STORZ MEDICAL AG |
| Zimmer MedizinSysteme |
| BTL Industries |
| EMS Electro Medical Systems |
| Inceler Medikal Co Ltd |
| Lumenis Ltd |
| EDAP TMS |
| Others |
Supply & Pricing Matrix
Stuttgart's precision copper winding cluster anchors electromagnetic generator fabrication, concentrating supplier power for high-energy coil assemblies and compressing margin negotiation space for downstream system integrators serving German rehabilitation networks.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium electromagnetic platforms, standard pneumatic alternatives, and economy-tier refurbished units. Price differentiation hinges on CE marking tier under EU MDR and bundled technical service contract duration. Cost compression in the pneumatic segment intensifies as South Korean clinic chains drive volume procurement of radial pressure wave devices. Cash-pay physiotherapy practices exhibit highest price sensitivity; Swiss university hospitals demonstrate lowest sensitivity due to reimbursement stability through national health frameworks.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements for piezoceramic array manufacturers in Japan and Switzerland. Component sourcing concentrates in Southern Germany for electromagnetic coils, Nagoya for ceramic transducers, and Daegu-Gyeongbuk for battery-coupled portable assemblies. Raw material dependencies include precision copper winding wire, lead-free barium titanate ceramics, and lithium-ion power cells. Single-source vulnerability in Southern German coil fabrication creates supply chain risk. Distribution runs through specialized medical device distributors serving hospital procurement committees and direct sales teams for clinic chain accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in cyclical recovery driven by EU MDR regulatory consolidation filtering marginal competitors and concentrating procurement among validated suppliers with compliant clinical evidence portfolios.
For Market Incumbents: Harden electromagnetic platform differentiation through captive supplier relationships with Stuttgart coil fabricators, insulating against raw material allocation constraints. Deepen clinical training network density in German orthopedic rehabilitation centers to slow competitive displacement from portable piezoceramic alternatives. Prioritize CE marking renewal documentation capacity to outlast mid-tier manufacturers struggling with EU MDR Article 86 post-market surveillance staffing requirements.
For New Entrants and Emerging Players: Pursue veterinary orthopedic applications in Kentucky equine sports medicine and Baden-Württemberg tendon regeneration protocols, where regulatory barriers are lower and incumbent presence is sparse. Target portable focused system deployment for ambulatory sports clinics in South Korea through equipment leasing partnerships with Seoul and Busan physiotherapy chains. Emphasize pay-per-procedure financing models to bypass capital-intensive hospital procurement committees.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with piezoceramic miniaturization capabilities and REACH-compliant material formulations over pure-play system integrators. Long-term viability rests on regulatory compliance infrastructure rather than device innovation velocity. Acquisition targets should demonstrate established EU MDR technical documentation and post-market clinical follow-up protocols. The signal to watch is CE marking renewal failure rates among mid-tier electromagnetic platform manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking renewal capacity separates viable suppliers from filtered competitors in German hospital procurement. |
| Piezoceramic Transducer Miniaturization | Barium titanate reformulation enables portable unit compliance with REACH substance restrictions in European markets. |
| Clinical Training Network Expansion | Specialized operator certification programs lock in repeat system deployments at Swiss university hospitals. |
| Third-Party Technical Service Partnerships | Unbundled maintenance agreements respond to North Rhine-Westphalia purchasing cooperative procurement preferences. |
| Veterinary Orthopedic Market Entry | Equine tendon regeneration protocols in Kentucky represent unserved demand with lower regulatory barriers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries. Interviews with biomedical engineers, rehabilitation center purchasing managers, GPO contracts specialists, and electromagnetic component suppliers inform demand-side and supply-side validation. Secondary sources include Swissmedic device registries, MFDS premarket approval records, and Institut für das Entgeltsystem im Krankenhaus reimbursement framework documentation. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction.
Forecast inputs span acoustic pulse generation technology migration, reimbursement pathway evolution, and regulatory compliance cost trajectories across the analysis window. Segmentation dimensions include product type, technology architecture, clinical application, and end-user category with geographic procurement cluster overlay. CAGRs derive from procedure volume elasticity to reimbursement rate changes and capital equipment replacement cycles. Industry-specific inputs incorporate EU MDR implementation timelines and REACH substance restriction phase-out schedules.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles, copper commodity pricing, or lithium-ion cell supply would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and reimbursement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Personalized Orthopaedic Implant Market
Orthopedic Devices
Podiatry Laser Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Needles Market
Orthopedic Devices
Cementless Total Knee Arthroplasty (TKA) Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Orthopedic Bone Cement and Casting Materials Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Orthopedic Consumables Market
Orthopedic Devices
Global Orthopedic Digit Implants Market
Orthopedic Devices
Pediatrics Orthotics Market
Orthopedic Devices
Orthopedic Pedicle Screw Market
Orthopedic Devices
Cartilage Repair Market
Orthopedic Devices
Femoral Head Prostheses Market
Orthopedic Devices
Spine Surgery Devices Market