
 Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market | 2026-2036
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market Outlook
Combination therapy bundling is broadening buyer choice across the Asia-Pacific kidney cancer landscape. Novartis AG leverages its cross-portfolio oncology presence to anchor bundled regimens spanning targeted and immunotherapy agents. Pfizer Inc competes through manufacturing scale that sustains cost-efficient supply of tyrosine kinase inhibitors across high-volume hospital channels. Eisai Co Ltd specializes in regional regulatory navigation, positioning its renal cell carcinoma portfolio for differentiated access in Japan and Southeast Asia.
Asia-Pacific kidney cancer therapeutics and diagnostics encompass pharmaceutical interventions and detection technologies addressing malignant neoplasms of the renal parenchyma, with functional parameters including tumor mutational burden assessment and vascular endothelial growth factor pathway inhibition. The primary purpose is to extend progression-free survival through molecularly guided treatment selection and early-stage detection via cross-sectional imaging and circulating biomarker analysis. Targeted therapy leads current revenue pools given established reimbursement for sunitinib-class agents, while immunotherapy represents the fastest-expanding segment as PD-1/PD-L1 inhibitors gain formulary inclusion across Australian and South Korean hospital systems. Liquid biopsy technology is capturing growing diagnostic share as non-invasive serial monitoring displaces repeat tissue biopsies in treatment-resistant patient cohorts.
Japan's PMDA, Australia's TGA, and China's NMPA collectively shape product standards through divergent clinical evidence requirements and manufacturing inspection protocols that determine market access timelines. The Therapeutic Goods Administration mandates local stability data that extends registration lead times for temperature-sensitive biologics. Stakeholders must monitor evolving harmonization discussions between ASEAN regulatory coalitions and national agencies to anticipate streamlined approval pathways that could reshape competitive positioning in Southeast Asian expansion strategies.
Market Dynamics
Combination therapy protocols are restructuring treatment hierarchies across Asia-Pacific oncology departments, with hospital procurement committees now bundling diagnostic imaging and molecular profiling services alongside pharmaceutical regimens.
Growth Catalysts
- PMDA Accelerated Approval Pathways:Japan's streamlined immuno-oncology review timelines compress product launch cycles, enabling earlier patient access to checkpoint inhibitors.
- Multidisciplinary Tumor Board Expansion:China's tier-one hospital networks integrate cross-sectional imaging with circulating biomarker analysis for treatment selection.
- Liquid Biopsy Serial Monitoring:Non-invasive ctDNA testing displaces repeat tissue biopsies in treatment-resistant patient cohorts across Australian and South Korean hospital systems.
Market Restraints
- Cold Chain Biologic Distribution Costs:Temperature-sensitive checkpoint inhibitors require specialized logistics infrastructure that elevates per-dose delivery expenses across Southeast Asian archipelago markets.
- Divergent Evidence Requirements:China's NMPA, Japan's PMDA, and Australia's TGA impose non-overlapping clinical trial standards that fragment development investment across national boundaries.
- Tyrosine Kinase Inhibitor Substitution Pressure:Biosimilar sunitinib-class agents entering South Korean and Indian hospital formularies compress branded therapy pricing power.
Strategic Opportunities
- ASEAN Regulatory Harmonization:Coalition discussions between Southeast Asian national agencies signal potential unified approval pathways that would streamline multi-country market entry.
- Rural China Diagnostic Penetration:Tier-two and tier-three city hospital networks remain underpenetrated for molecular profiling services that guide targeted therapy selection.
- Artificial Intelligence Imaging Convergence:Machine learning algorithms paired with contrast-enhanced CT protocols enable automated renal mass characterization in high-volume Japanese screening programs.
Industry Challenges
- Immuno-oncology Biomarker Interpretation Expertise:Shortage of pathologists trained in PD-L1 expression scoring and tumor mutational burden assessment creates diagnostic bottlenecks in Australian regional hospitals.
- Cross-border Data Localization Requirements:China's cybersecurity law and Australia's privacy framework impose conflicting patient data residency rules that complicate multi-site clinical trial execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market |
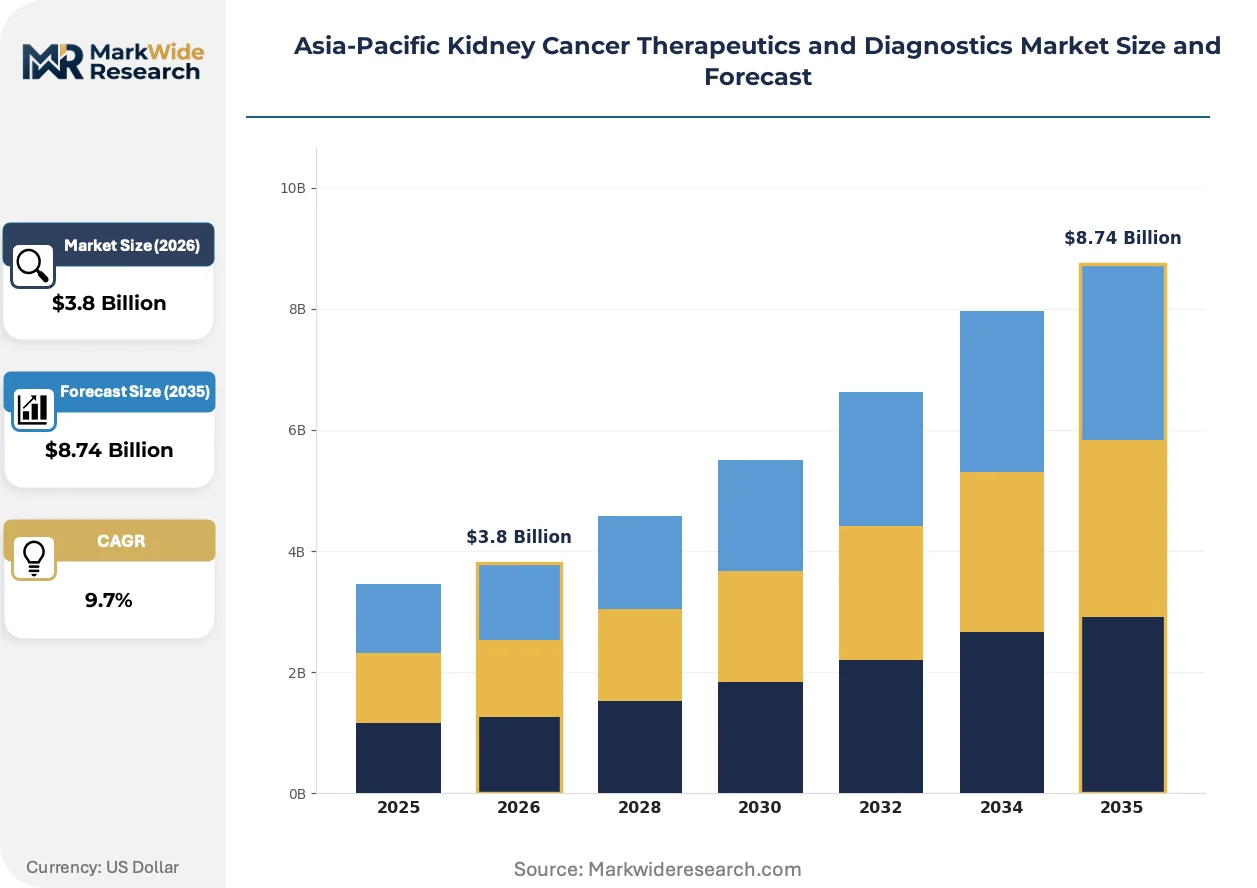
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiotherapy Delivery Mode: Injectable, Oral, Infusion, Localized End User: Hospitals, Clinics, Homecare, Research Institutes Technology: Biomarkers, Imaging Techniques, Genetic Testing, Liquid Biopsy |
| Companies Covered | Novartis AG, Abbott Laboratories, F. Hoffmann-La Roche Ltd, GlaxoSmithKline, Amgen Inc, Bayer AG, Eisai Co Ltd, Sanofi SA, Pfizer Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market Strategic Shifts
Diagnostic-therapeutic integration is compressing decision timelines across Asia-Pacific kidney cancer care pathways, with liquid biopsy platforms and artificial intelligence imaging tools converging to reshape how treatment resistance is monitored and addressed.
Next-generation sequencing-based liquid biopsy technology is absorbing market share from tissue-based companion diagnostics in serial monitoring applications. Major tertiary oncology centers in Tokyo, Shanghai, and Sydney deploy ctDNA panels to track clonal evolution without invasive re-biopsy procedures. This shift is absorbing revenue from traditional pathology services while creating new recurring diagnostic revenue streams.
Japan's PMDA has implemented conditional early approval frameworks for breakthrough oncology therapies that accept single-arm trial data. This regulatory innovation compresses time-to-market for novel immuno-oncology combinations by twelve to eighteen months. Australian and South Korean regulators are studying this model for potential adoption, creating competitive pressure on China's NMPA to accelerate its own review timelines.
Hospital procurement committees in China and India are unbundling diagnostic and therapeutic contracts that were previously awarded to single vendors. This fragmentation enables specialized liquid biopsy laboratories to compete directly with pharmaceutical suppliers for molecular profiling budgets. The pattern is most visible in Beijing and Mumbai, where independent diagnostic platforms now bid separately from drug formularies.
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market Segmentation
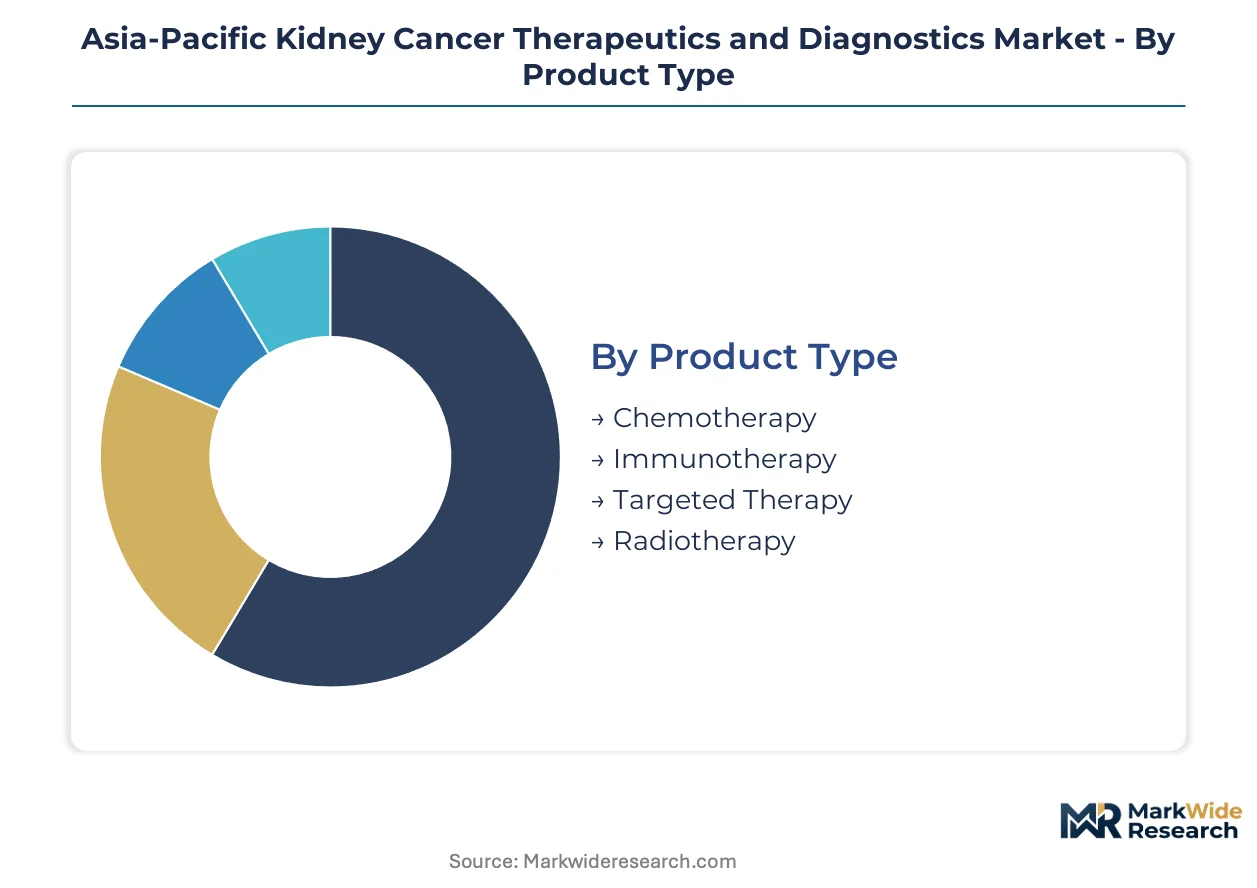
Segmentation in the Asia-Pacific kidney cancer market reflects divergent reimbursement pathways, treatment resistance patterns, and diagnostic infrastructure maturity across national health systems. Understanding these divides enables suppliers to align portfolio investments with where clinical decision-making and procurement authority actually concentrate.
Product Type:
Buyers differentiate primarily by progression-free survival benchmarks and reimbursement tier placement within hospital formularies.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR inhibitors dominate current prescribing patterns across China's tier-one oncology centers and Japan's designated cancer care hospitals. Sunitinib-class agents retain formulary priority where biosimilar substitution pressure remains nascent.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors command premium procurement budgets in Australian and South Korean hospital systems with established immuno-oncology infrastructure. PMDA accelerated approval pathways compress launch-to-access timelines for novel combinations.
- Chemotherapy:Cytotoxic regimens persist in Indian and Southeast Asian markets where cost-containment protocols prioritize established reimbursement codes.
- Radiotherapy:Stereotactic ablative radiotherapy integrates with systemic therapy in Japanese multidisciplinary tumor boards for oligometastatic disease management.
Volume sits with targeted therapy; growth tilts toward immunotherapy.
Delivery Mode:
Route selection tracks cold chain infrastructure maturity and patient mobility constraints across archipelago and continental markets.
- Injectable:Intravenous checkpoint inhibitors require specialized infusion centers with adverse event monitoring capabilities concentrated in Tokyo, Shanghai, and Sydney tertiary hospitals.
- Oral:Tyrosine kinase inhibitors enable outpatient treatment continuity in China's tier-two cities and Indian regional cancer centers where infusion capacity is constrained.
- Infusion:Continuous delivery protocols for cytokine therapy retain niche application in select Australian academic medical centers.
- Localized:Intra-arterial chemoembolization and radioembolization target unresectable disease in Japanese and South Korean interventional radiology departments.
Oral formulations capture volume expansion in infrastructure-limited settings; injectable biologics claim margin concentration where cold chain logistics are assured.
End User:
Procurement authority fragments across centralized hospital pharmacy committees and emerging distributed care models.
- Hospitals:Tertiary oncology departments in Beijing, Mumbai, and Singapore anchor pharmaceutical volume through multidisciplinary tumor board protocols that bundle diagnostics with therapeutic selection.
- Clinics:Specialized urology and medical oncology practices in Australian metropolitan areas drive liquid biopsy adoption for treatment monitoring outside inpatient settings.
- Homecare:Oral targeted therapy administration shifts to domestic settings in Japan's aging patient population with established home nursing infrastructure.
- Research Institutes:Academic medical centers in Seoul and Tokyo coordinate investigator-initiated trials for novel immuno-oncology combinations.
Hospital procurement committees retain pharmaceutical volume control; clinics represent the steepest expansion trajectory for diagnostic services.
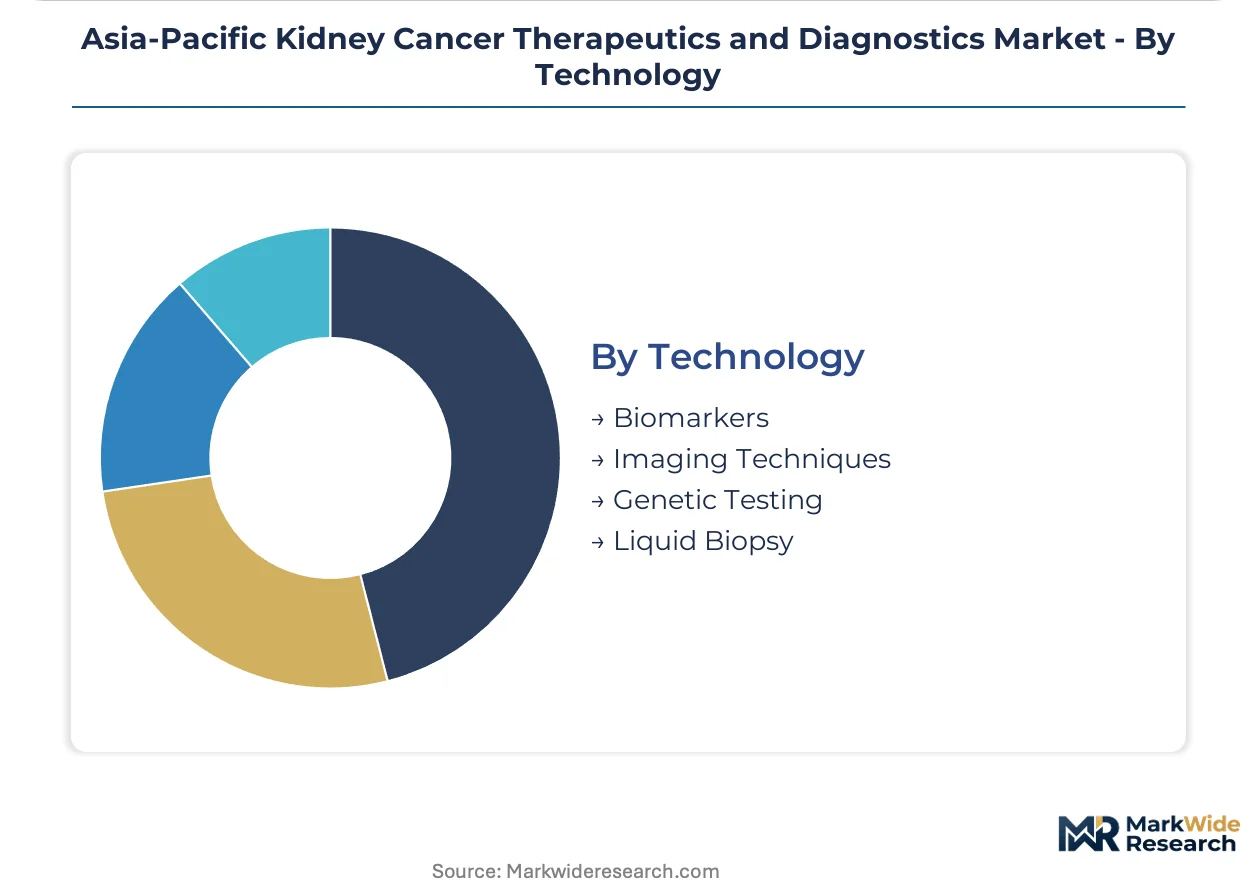
Technology:
Diagnostic platform selection follows biomarker validation status and pathologist workforce density across national laboratory networks.
- Imaging Techniques:Contrast-enhanced CT and MRI protocols standardize renal mass characterization in Chinese and Japanese screening programs with machine learning augmentation gaining validation.
- Liquid Biopsy:Circulating tumor DNA panels enable serial resistance monitoring without invasive re-biopsy in Australian and South Korean tertiary centers displacing repeat tissue sampling.
- Biomarkers:PD-L1 immunohistochemistry and tumor mutational burden assessment guide checkpoint inhibitor eligibility in PMDA-regulated pathways.
- Genetic Testing:Next-generation sequencing for hereditary renal cell carcinoma syndromes concentrates in Japanese and Australian reference laboratories with genetic counseling integration.
Imaging techniques anchor current diagnostic volume; liquid biopsy platforms are climbing the fastest as resistance monitoring protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates biologics manufacturing capacity while China absorbs the bulk of diagnostic imaging system deployment. India's pharmaceutical production feeds cost-sensitive Southeast Asian markets. Australia's tertiary hospitals anchor immuno-oncology adoption rates across the southern hemisphere.
Japan
PMDA accelerated approval pathways compress checkpoint inhibitor launch timelines by twelve to eighteen months. METI coordinates domestic biologics manufacturing subsidies that reduce cold chain dependency for regional distribution. Tokyo's designated cancer care hospitals anchor multidisciplinary tumor board protocols bundling imaging with molecular profiling.
China
Tier-one city hospital networks drive demand for next-generation sequencing-based treatment selection. NMPA imposes local clinical trial requirements that extend registration timelines for novel immuno-oncology agents. Beijing and Shanghai oncology centers integrate artificial intelligence-augmented CT protocols into renal mass characterization workflows.
India
CDSCO streamlined biosimilar approval pathways accelerate tyrosine kinase inhibitor substitution in government hospital formularies. Mumbai and Delhi tertiary centers expand multidisciplinary tumor board adoption for treatment-resistant patient cohorts. Domestic pharmaceutical manufacturing scales cost-efficient supply across South Asian export markets.
Australia
TGA mandates local stability data for temperature-sensitive biologics that extends registration lead times. Sydney and Melbourne academic medical centers drive liquid biopsy adoption for serial resistance monitoring outside inpatient settings. Medicare reimbursement frameworks prioritize progression-free survival endpoints in formulary placement decisions.
South Korea
MFDS aligns immuno-oncology review timelines with PMDA accelerated models to compress market access windows. Seoul's tertiary hospital networks integrate PD-L1 expression scoring into checkpoint inhibitor eligibility protocols. Domestic biotechnology clusters scale contract manufacturing for regional biologics export.
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market Competitive Environment
The competitive structure tilts toward cross-portfolio oncology bundling rather than single-agent dominance. Large-cap pharmaceutical conglomerates anchor combination therapy protocols through manufacturing scale and regulatory navigation capabilities. Mid-tier specialists concentrate on regional access pathways and diagnostic-therapeutic integration. M&A activity targets liquid biopsy platforms and artificial intelligence imaging tools. Strategic partnerships between pharmaceutical suppliers and independent diagnostic laboratories fragment procurement authority previously held by single vendors.
Within the large-cap tier, Novartis AG and Pfizer Inc exemplify cross-portfolio bundling archetypes that anchor hospital formulary placement. Eisai Co Ltd occupies a specialized position in regional regulatory navigation. These three companies represent distinct competitive vectors: manufacturing scale, portfolio breadth, and geographic access specialization respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline |
| Amgen Inc |
| Bayer AG |
| Eisai Co Ltd |
| Sanofi SA |
| Pfizer Inc |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committee consolidation across China's tier-one cities and Japan's designated cancer care hospitals is compressing supplier margins and forcing pharmaceutical manufacturers to absorb cold chain logistics costs previously passed through to buyers. This buyer-side concentration is reshaping how checkpoint inhibitors and tyrosine kinase inhibitors reach oncology departments across the Asia-Pacific region.
Pricing Analysis
Margin tightening in branded tyrosine kinase inhibitors reflects biosimilar sunitinib-class substitution accelerating through South Korean and Indian government hospital formularies. Three-tier pricing structure across premium immuno-oncology combinations, standard targeted therapy regimens, and economy chemotherapy protocols stratifies procurement budgets by progression-free survival benchmarks. Cost-down pressure on diagnostic imaging bundles intensifies as Chinese hospital networks unbundle previously consolidated vendor contracts. Government tenders in India and Southeast Asia exhibit highest price sensitivity; Australian and Japanese private hospital channels retain lowest sensitivity due to reimbursement tier placement.
Supply Chain Analysis
Dual-sourcing qualification requirements imposed by Japan's PMDA and Australia's TGA mandate that biologics manufacturers maintain validated production facilities across at least two regulatory jurisdictions. Active pharmaceutical ingredient production concentrates in India and China, while fill-finish capacity clusters in South Korea and Singapore. Cold chain distribution for temperature-sensitive checkpoint inhibitors draws from specialized logistics providers with validated container platforms. Single-source vulnerability persists for monoclonal antibody cell lines held in limited master cell banks. Distribution runs through hospital pharmacy committees in tier-one cities, with regional hub-and-spoke models extending to tier-two and tier-three markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific kidney cancer therapeutics and diagnostics market is consolidating around manufacturers with cross-portfolio bundling capabilities and regulatory navigation expertise, as biosimilar substitution and diagnostic unbundling force single-product specialists toward exit or acquisition.
For Market Incumbents: Deploy cross-portfolio oncology bundling to anchor hospital formulary placement against unbundling pressures. Integrate liquid biopsy partnerships into existing targeted therapy contracts to retain molecular profiling revenue streams. Expand manufacturing scale in South Korean and Singaporean facilities to satisfy dual-sourcing requirements from Japan's PMDA and Australia's TGA. Defensive consolidation through acquisition of regional diagnostic platforms will preempt independent laboratories from fragmenting procurement authority. For New Entrants and Emerging Players: Begin with artificial intelligence imaging tools for renal mass characterization in China's tier-two and tier-three hospital networks, where radiologist workforce density lags behind tier-one centers. Target rural China diagnostic penetration for molecular profiling services that guide treatment selection in underpenetrated markets. Pursue regulatory approval through Japan's PMDA accelerated pathways to compress time-to-market for novel immuno-oncology combinations. Partner with established cold chain logistics providers rather than building proprietary distribution infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with liquid biopsy platform specialists given ASEAN regulatory harmonization discussions that would streamline multi-country market entry. Long-term viability in this market hinges on diagnostic-therapeutic integration capabilities rather than single-modality dominance. Acquisition targets should demonstrate established reimbursement pathways in at least two Asia-Pacific jurisdictions. Watch for PMDA conditional approval announcements as inflection indicators for checkpoint inhibitor portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Japan's PMDA accelerated frameworks compress launch timelines by twelve to eighteen months for novel combinations. |
| Diagnostic-Therapeutic Integration | Bundling imaging and molecular profiling with pharmaceutical regimens anchors procurement committee decisions in Chinese hospitals. |
| Manufacturing Scale-Up | South Korean biologics capacity expansion satisfies dual-sourcing mandates from Australian TGA stability requirements. |
| Licensing Agreement | Partnerships with independent liquid biopsy laboratories fragment vendor consolidation in Beijing and Mumbai procurement. |
| Pipeline Diversification | Next-generation sequencing companion diagnostics displace tissue-based testing in Australian serial monitoring protocols. |
Study Parameters
Multi-period observation of PMDA approval timelines, NMPA clinical trial requirements, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and Asia-Pacific formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Segment-weighting across treatment line, administration route, patient population, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from fitted growth curves applied to diagnosed incident cases and therapy penetration rates. Forecast inputs incorporated biomarker-guided treatment selection adoption curves and immuno-oncology infrastructure maturity indices across national health systems. Volume and value outputs reflect convergence of epidemiological, clinical, and economic drivers throughout the projection horizon.
Regulatory timeline delays, biosimilar substitution acceleration, and diagnostic reimbursement policy reversals are the dominant revision risks to the forecast assumptions. A model refresh is warranted upon material change in ASEAN harmonization implementation timelines or PMDA conditional approval criteria expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Global Autoimmune Disease Therapeutics Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Primary Hyperoxaluria Treatment Market
Specialty Medicine
Pseudobulbar Treatment Market