
 Cholangiocarcinoma Market | 2026-2036
Cholangiocarcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Cholangiocarcinoma Market Intelligence
Companion diagnostic revenue is reconfiguring how value accumulates across the cholangiocarcinoma treatment chain. Incyte Corporation leverages its FGFR inhibitor franchise to anchor commercial positioning in biomarker-selected populations. AstraZeneca plc competes through broad oncology infrastructure and pipeline depth across solid tumors. Eli Lilly and Company specializes in antibody-drug conjugate platforms that target surface proteins enriched in biliary tract malignancies.
Cholangiocarcinoma denotes a heterogeneous group of malignancies arising from epithelial cells of the intrahepatic, perihilar, or distal biliary tree, characterized by dense desmoplastic stroma, frequent actionable mutations in FGFR2 fusion, IDH1, and BRAF genes, and poor prognosis due to late-stage diagnosis and limited therapeutic options. Targeted therapy segments now command the most favorable margin pools as payers accept premium pricing for biomarker-restricted indications with demonstrated progression-free survival benefits. Chemotherapy retains volume dominance in first-line settings across most geographies, though its commoditization pressures reimbursement rates. Delivery mode preferences increasingly favor intravenous administration for precision agents requiring therapeutic drug monitoring.
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathway shape how developers design registrational studies and price novel agents in cholangiocarcinoma. ISO 14155 standards for clinical investigation of medical devices for human subjects govern diagnostic companion test validation, while the EU AI Act introduces compliance obligations for algorithmic biomarker interpretation tools. Stakeholders must monitor how evolving evidentiary requirements for confirmatory trials reshape investment timelines and portfolio prioritization across FGFR, IDH1, and emerging target classes.
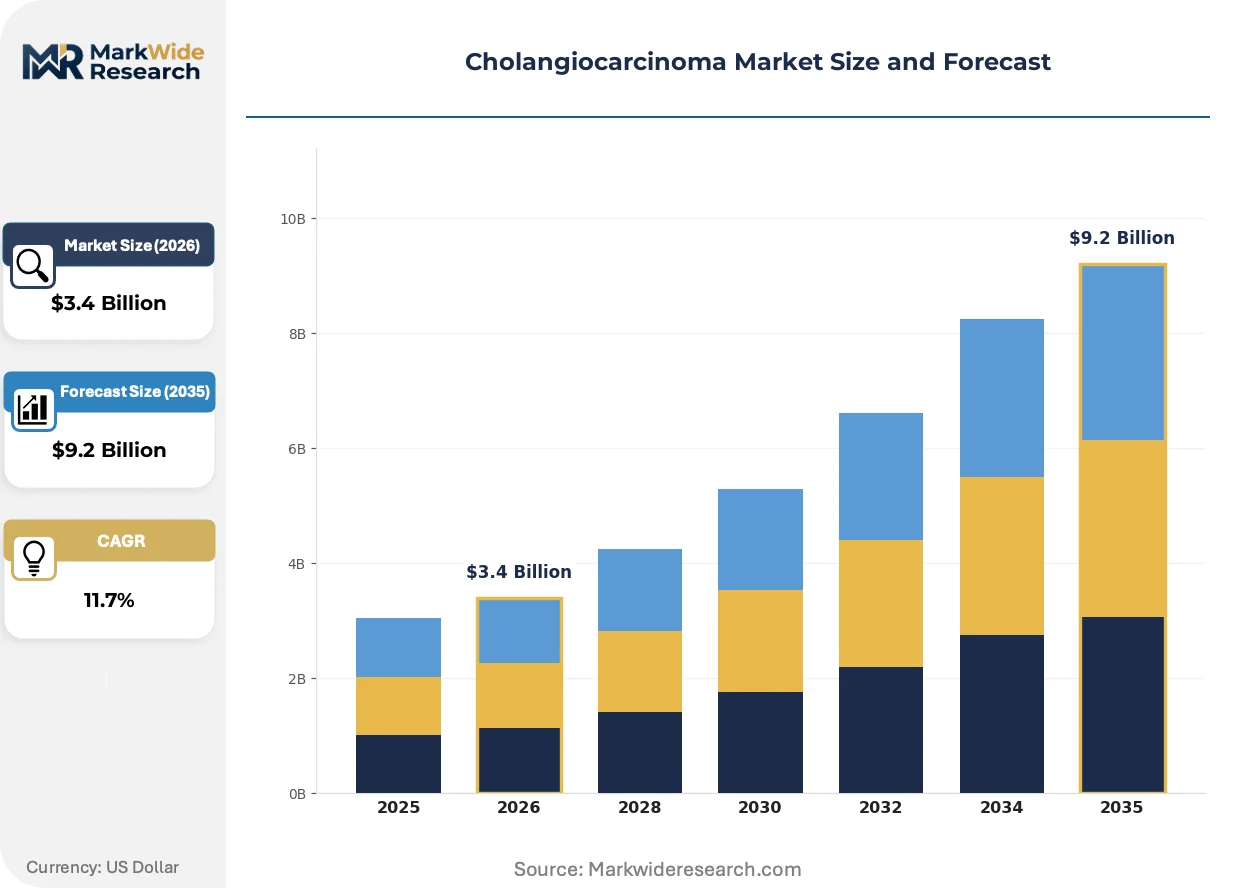
Market Dynamics
The FDA's accelerated approval pathway has compressed development timelines for FGFR and IDH1 inhibitors, forcing developers to front-load biomarker validation and companion diagnostic partnerships before pivotal trials commence.
Growth Catalysts
- EMA Conditional Marketing Authorization:European regulators now permit earlier patient access based on single-arm studies, incentivizing sponsors to prioritize EU enrollment alongside US sites.
- Liquid Biopsy Adoption:Circulating tumor DNA profiling is expanding addressable patient pools by enabling molecular screening in patients with insufficient tissue for conventional sequencing.
- Academic Medical Center Clustering:United States-based NCI-designated cancer centers concentrate trial infrastructure and early commercial uptake for novel agents.
Market Restraints
- Confirmatory Trial Failure Risk:Post-marketing studies for accelerated approvals face elevated discontinuation rates, threatening label withdrawals and payer clawbacks.
- Companion Diagnostic Fragmentation:Multiple FDA-cleared tests for identical biomarkers create prescriber confusion and formulary complexity across health systems.
- Desmoplastic Stroma Barrier:Dense fibrotic tumor microenvironments limit drug penetration and confound radiographic response assessment in biliary tract malignancies.
Strategic Opportunities
- Japan's Sakigake Designation:PMDA's priority review system offers reduced regulatory timelines for first-in-class agents, creating a secondary launch market with premium pricing potential.
- Antibody-Drug Conjugate Expansion:HER2-directed and TROP2-targeting ADCs represent untapped mechanistic classes beyond kinase inhibition in biomarker-unselected populations.
- Community Oncology Infusion:Outpatient administration networks outside academic centers remain underpenetrated for precision therapies requiring therapeutic drug monitoring.
Industry Challenges
- Biomarker Test Turnaround:Two-to-three-week sequencing delays in community settings compromise enrollment windows for time-sensitive clinical trials.
- Cross-Border Data Harmonization:Divergent evidentiary standards between FDA and EMA for surrogate endpoint acceptance complicates global registrational strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholangiocarcinoma Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.2 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Interventions, Chemotherapy, Targeted Therapy, Radiotherapy Application: Localized Tumors, Advanced Tumors, Recurrence, Palliative Care End User: Hospitals, Cancer Treatment Centers, Research Institutes, Specialty Clinics Delivery Mode: Intravenous, Oral, Localized Injection, Regional Perfusion |
| Companies Covered | Incyte Corporation, AstraZeneca plc, Eli Lilly and Company, Merck & Co., Inc., Servier, Taiho Pharmaceutical, Eisai Co., Ltd., Agios Pharmaceuticals, BridgeBio Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholangiocarcinoma Market Strategic Shifts & Innovations
Next-generation sequencing platforms are compressing diagnostic timelines while artificial intelligence tools reshape biomarker interpretation workflows across pathology laboratories.
Comprehensive genomic profiling panels are rendering obsolete single-gene hotspot testing in cholangiocarcinoma diagnostic pathways. Community oncology networks and pathology reference laboratories are adopting these platforms at accelerating velocity. The technology is rendering obsolete legacy fluorescence in situ hybridization workflows for FGFR2 fusion detection, consolidating testing volume toward centralized NCI-designated molecular tumor boards.
The EU AI Act imposes conformity assessment obligations on algorithmic diagnostic tools used for biomarker scoring and treatment recommendation generation. Developers must now document training data provenance and performance drift monitoring for CE-marked software. European pathology networks are responding by segregating AI-assisted workflows into quality-controlled modules with mandatory human-in-the-loop verification steps.
Specialty pharmacy distribution is displacing traditional wholesale channels for oral targeted agents in cholangiocarcinoma. Payers are mandating limited distribution networks with embedded adherence monitoring and adverse event reporting. This channel restructuring is most visible in United States commercial insurance segments, where prior authorization requirements now route prescriptions through designated specialty pharmacies with oncology clinical pharmacist support.
Cholangiocarcinoma Market Segmentation
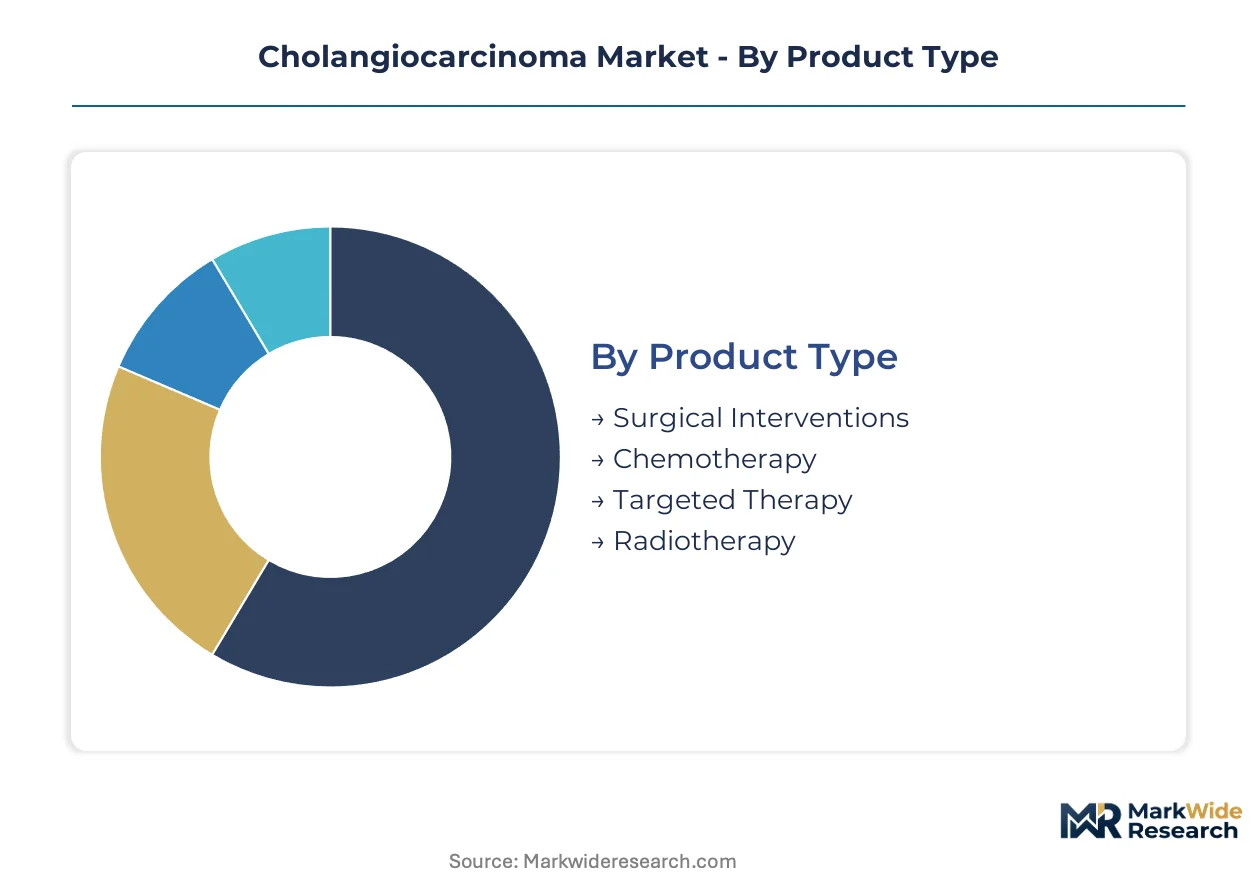
Cholangiocarcinoma treatment selection hinges on tumor location, molecular profile, and patient performance status. Segmentation reveals how biomarker-driven precision therapies are carving out premium positions alongside established modalities.
Product Type:
Cost tier differentiation separates commodity interventions from precision agents commanding reimbursement premiums.
- Surgical Interventions:Hepatic resection and liver transplantation remain curative standards for localized intrahepatic disease. Academic medical centers in the United States perform the majority of complex biliary reconstructions, though referral patterns concentrate at NCI-designated centers with transplant authorization.
- Targeted Therapy:FGFR inhibitors and IDH1 antagonists deliver progression-free survival advantages in biomarker-selected populations. Payers accept premium pricing for these agents when companion diagnostic testing restricts eligibility, creating favorable margin pools distinct from chemotherapy commoditization.
- Chemotherapy:Gemcitabine-cisplatin combinations retain first-line volume dominance across most geographies.
- Radiotherapy:External beam and stereotactic body radiation address locally advanced disease and symptom palliation.
Surgical interventions hold installed capacity. Targeted therapy is rotating up the share rankings.
Application:
Patient staging at diagnosis determines whether curative intent or palliation guides therapeutic sequencing.
- Advanced Tumors:Unresectable disease constitutes the majority of presentations, driving systemic therapy demand and clinical trial enrollment. The FDA's accelerated approval pathway has compressed development timelines for agents targeting this population, with confirmatory trials now mandated post-market.
- Localized Tumors:Resectable disease offers curative potential through surgery with adjuvant chemotherapy. Japanese surgical series report superior outcomes for perihilar tumors managed with aggressive resection and vascular reconstruction at high-volume centers.
- Recurrence:Second-line systemic options expand as resistance mechanisms clarify.
- Palliative Care:Biliary drainage and symptom management address quality-of-life endpoints.
Advanced tumors capture the largest addressable population. Localized tumors demonstrate the steepest expansion trajectory as screening improves.
End User:
Customer type fragmentation reflects concentration of expertise and capital equipment requirements.
- Cancer Treatment Centers:NCI-designated comprehensive cancer centers anchor clinical trial infrastructure and early adoption of novel agents. These institutions concentrate molecular tumor boards, liquid biopsy platforms, and interventional radiology capabilities essential for cholangiocarcinoma management.
- Hospitals:General acute care facilities manage de novo presentations and emergency biliary obstruction. Community hospital networks in the United States increasingly refer complex cases to academic centers, fragmenting longitudinal care.
- Specialty Clinics:Outpatient infusion centers and hepatology-focused practices deliver precision therapies.
- Research Institutes:Translational laboratories drive biomarker discovery and preclinical target validation.
Cancer treatment centers hold installed capacity. Specialty clinics are rotating up the share rankings.
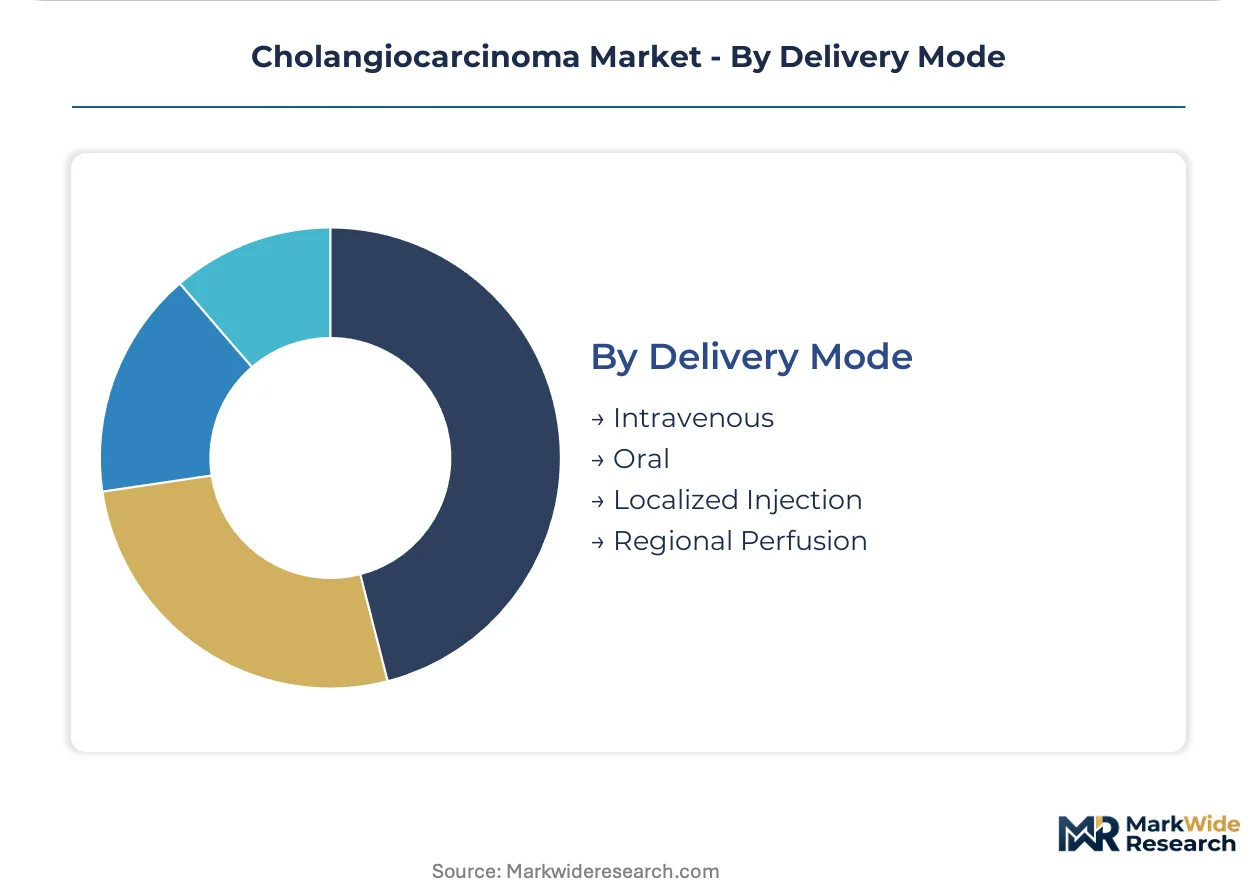
Delivery Mode:
Route of administration shapes site-of-care requirements and therapeutic drug monitoring protocols.
- Intravenous:Infusion-based delivery dominates cytotoxic chemotherapy and antibody-drug conjugates. United States commercial payers increasingly mandate specialty pharmacy networks with embedded clinical pharmacist support for these agents.
- Oral:Small-molecule kinase inhibitors enable outpatient administration but require adherence monitoring. The EU AI Act imposes conformity obligations on algorithmic tools used for treatment recommendation generation in oral therapy selection.
- Localized Injection:Direct tumor or biliary tree instillation addresses regional disease control.
- Regional Perfusion:Hepatic artery infusion and isolated limb perfusion techniques target organ-confined malignancy.
Intravenous delivery holds installed capacity. Oral administration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cholangiocarcinoma treatment access varies sharply by geography. The United States concentrates biomarker-guided therapy adoption and clinical trial density, while Japan and Germany emphasize surgical volume and regulatory innovation pathways.
United States
NCI-designated cancer centers anchor molecular tumor board infrastructure and FGFR inhibitor prescribing. FDA's accelerated approval pathway compresses development timelines for biomarker-selected populations. The MD Anderson Cancer Center and Memorial Sloan Kettering cluster early commercial uptake for novel agents.
Germany
Academic hospital networks manage complex perihilar resections with vascular reconstruction capabilities. EMA conditional marketing authorization enables earlier patient access based on single-arm efficacy data. The Heidelberg University Hospital and Charité Berlin concentrate translational research and surgical volume for biliary malignancies.
Japan
High-volume hepatobiliary surgical centers report superior outcomes for locally advanced disease. PMDA's Sakigake designation offers reduced regulatory timelines for first-in-class agents targeting IDH1 and FGFR alterations. Tokyo and Osaka metropolitan areas concentrate both clinical trial enrollment and precision therapy adoption.
United Kingdom
NHS England's specialized commissioning framework routes complex cases to designated hepatopancreaticobiliary centers. NICE technology appraisals determine reimbursement for targeted therapies with companion diagnostic requirements. The Royal Marsden and Liverpool University Hospitals anchor molecular profiling infrastructure and early access programs.
South Korea
MFDS regulatory reforms align with FDA breakthrough therapy criteria for oncology indications. Seoul National University Hospital and Samsung Medical Center concentrate liquid biopsy adoption and clinical trial infrastructure for FGFR2 fusion detection in intrahepatic disease.
Cholangiocarcinoma Market Key Industry Players
Capability concentration sits with precision oncology specialists commanding biomarker platforms; scale advantage sits with diversified pharmaceutical conglomerates with broad solid tumor infrastructure. The competitive structure tiers into three archetypes: kinase inhibitor specialists with companion diagnostic franchises, antibody-drug conjugate developers targeting surface antigens, and immuno-oncology players leveraging checkpoint modulation. Dominant competitive moves include biomarker validation partnerships with diagnostic firms and accelerated approval pathway exploitation for registrational trial design.
Within the kinase inhibitor tier, Incyte Corporation and Agios Pharmaceuticals exemplify precision-focused developers anchoring commercial positioning through FGFR and IDH1 franchises. Among diversified oncology players, AstraZeneca plc occupies a position representing broad infrastructure deployment across solid tumors with pipeline depth in biliary tract indications. Eli Lilly and Company sits within the antibody-drug conjugate specialization vector, targeting surface proteins enriched in desmoplastic tumor microenvironments.
| Leading Market Players |
|---|
| Incyte Corporation |
| AstraZeneca plc |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Servier |
| Taiho Pharmaceutical |
| Eisai Co., Ltd. |
| Agios Pharmaceuticals |
| BridgeBio Inc. |
| Others |
Cost & Logistics Intelligence
Boston's concentration of NCI-designated cancer centers and specialty pharmacy hubs shapes pricing power for oral FGFR inhibitors, compressing reimbursement negotiations through consolidated formulary control while amplifying margin capture for intravenous precision agents requiring therapeutic drug monitoring infrastructure.
Pricing Analysis
Long-term offtake agreements between biopharmaceutical manufacturers and specialty pharmacy networks dominate cholangiocarcinoma drug distribution, with FDA breakthrough-designated agents commanding premium positioning through restricted distribution channels. Price differentiation rests on companion diagnostic bundling and biomarker eligibility restrictions, with chemotherapy commoditization intensifying cost compression in first-line settings. Payer price sensitivity concentrates in Medicare Advantage segments, while commercial insurers accept elevated premiums for progression-free survival advantages in biomarker-selected populations.
Supply Chain Analysis
Extended payment terms from specialty pharmacy distributors to oral oncology manufacturers now stretch 90-120 days, with supply-chain finance facilities emerging to bridge working capital gaps. Active pharmaceutical ingredient production draws from India, Switzerland, and the United States, with FGFR inhibitor synthesis requiring specialized continuous manufacturing capabilities. Single-source vulnerability concentrates in companion diagnostic reagent supply, with distribution running through limited networks mandated by FDA Risk Evaluation and Mitigation Strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
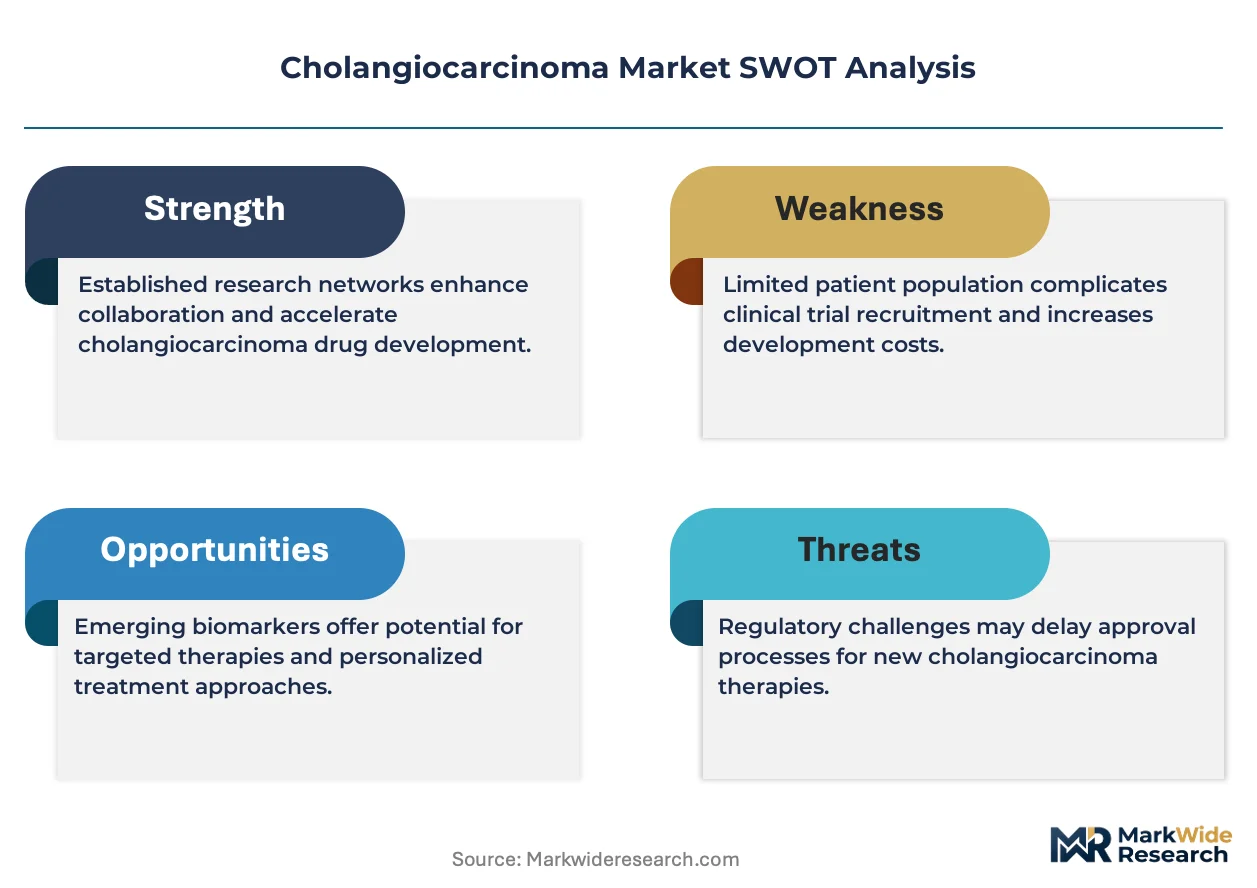
Cholangiocarcinoma therapeutic development is recovering from a cyclical trough as FDA accelerated approvals for IDH1 and FGFR inhibitors validate biomarker-driven trial designs, with pipeline replenishment now tracking toward mechanistic diversification beyond kinase inhibition.
For Market Incumbents: Harden companion diagnostic exclusivity through locked test-and-treat protocols that forestall biosimilar erosion, while deepening backward integration into liquid biopsy platform development to capture screening-stage patient identification. Incyte Corporation's FGFR franchise demonstrates how biomarker gatekeeping preserves pricing power against emerging TROP2-directed antibody-drug conjugate competition.
For New Entrants and Emerging Players: Community oncology networks in the United States Southeast and Mountain West regions present underpenetrated infusion capacity for precision therapies requiring therapeutic drug monitoring, with outpatient administration infrastructure lagging academic medical center clustering. Target these geographies through hub-and-spoke partnerships with regional reference laboratories, leveraging abbreviated FDA pathways for biomarker-selected indications to compress time-to-revenue.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with orphaned biliary tract assets lacking companion diagnostic infrastructure. Position acquisitions for a 5-10 year window where antibody-drug conjugate mechanistic classes displace kinase inhibitor dominance. The signal to watch is confirmatory trial readout success rates for accelerated approvals, which would validate premium multiples for biomarker-selected development platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | FDA-cleared test co-development locks prescribing protocols and defends against therapeutic substitution. |
| Accelerated Approval Pathway Exploitation | Single-arm registrational trials compress development timelines for biomarker-restricted indications. |
| Specialty Pharmacy Network Integration | Limited distribution with embedded adherence monitoring satisfies FDA REMS and payer prior authorization requirements. |
| Liquid Biopsy Platform Investment | Circulating tumor DNA profiling expands addressable screening populations beyond tissue-limited settings. |
| Mechanistic Class Diversification | Antibody-drug conjugate pipelines targeting HER2 and TROP2 reduce reliance on kinase inhibition saturation. |
Research Approach
Cross-validation between primary interviews with oncology clinical pharmacists, regulatory affairs directors at precision therapy developers, formulary managers at national payers, and interventional radiologists anchors the qualitative findings. Secondary validation draws from FDA oncology drug approvals, EMA conditional marketing authorizations, ClinicalTrials.gov enrollment data, and CMS Medicare Part B claims. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation calibrate market size estimates across the analysis window.
Calibration against historical adoption curves for prior accelerated approvals in solid tumors shapes the projection framework. Segmentation dimensions span treatment line, molecular alteration category, administration route, and regional regulatory cluster. CAGRs derive from logistic diffusion modeling of biomarker testing penetration and therapy uptake rates, with inputs including companion diagnostic approval timelines and payer coverage determination velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified immuno-oncology players entering biliary tract indications would shift outcomes. Macroeconomic pressure on Medicare reimbursement, EMA evidentiary standard tightening, or next-generation sequencing platform disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Idiopathic Pulmonary Fibrosis (IPF) Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Herpangina Treatment Market