
 Chimeric Antigen Receptor (CAR) T-Cell Therapy Market | 2026-2036
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market Intelligence
Hospital-based infusion networks is reconfiguring access patterns for advanced cell therapies. Novartis AG leverages its early-mover manufacturing footprint across European and North American treatment hubs. Gilead Sciences, Inc. anchors the lymphoma segment through Kite's established autologous production infrastructure. Bristol-Myers Squibb Company competes on dual-indication breadth spanning both B-cell malignancies and multiple myeloma.
Chimeric Antigen Receptor T-Cell Therapy engineers patient-derived or donor-sourced T lymphocytes with synthetic receptors targeting tumor-associated antigens, requiring cryopreserved apheresis material, lentiviral or electroporation-mediated transduction, and expansion in GMP-compliant cleanroom suites before reinfusion. Autologous CAR-T dominates current revenue pools due to established reimbursement for approved hematologic indications, while allogeneic platforms attract development capital as off-the-shelf architectures promise to resolve vein-to-vein timing constraints and manufacturing failures. The indication mix tilts toward non-Hodgkin lymphoma and multiple myeloma as earlier-line trial readouts broaden eligible patient populations.
FDA's risk-based CMC guidance and EMA's ATMP classification system shape manufacturing scale-up requirements and post-authorization study obligations for commercial sponsors. The EU AI Act and GDPR frameworks increasingly govern real-world evidence generation and patient data flows supporting long-term safety surveillance. Stakeholders must monitor how CMS's TEC assessment methodology and parallel HTA processes in Germany and France recalibrate value thresholds as CAR-T moves from salvage to earlier treatment settings.
Market Dynamics
Vein-to-vein manufacturing timelines for autologous CAR-T products are compressing competitive positioning, as academic medical centers and commercial sponsors race to resolve apheresis-to-infusion bottlenecks that currently stretch three to four weeks.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's regenerative medicine advanced therapy designation compresses clinical development timelines for novel CAR constructs, reducing sponsor capital requirements and enabling earlier revenue recognition.
- Centralized Apheresis Networks:Hospital-based collection hubs in the United States, Germany, and China are clustering GMP-compliant cleanroom capacity within 200-mile patient catchment zones.
- Allogeneic Platform Maturation:Off-the-shelf T-cell receptor engineering is collapsing donor matching constraints and enabling inventory-based distribution models previously impossible with patient-specific manufacturing.
Market Restraints
- Lentiviral Vector Supply Concentration:GMP-grade viral vector production concentrates among three North American contract manufacturers, creating single-source dependencies for transduction-stage inputs.
- EMA ATMP Post-Authorization Burden:The European Medicines Agency's advanced therapy medicinal products classification imposes 15-year follow-up obligations that inflate pharmacovigilance staffing costs for commercial sponsors.
- Cryopreservation Logistics Complexity:Liquid nitrogen cold chain requirements for apheresis material and finished product impose infrastructure capital intensity that excludes smaller oncology centers from CAR-T administration.
Strategic Opportunities
- Solid Tumor Antigen Targeting:CAR constructs addressing HER2, mesothelin, and GD2 in glioblastoma and pancreatic cancer represent addressable populations tenfold larger than current hematologic indications.
- Germany's DigiGesund Initiative:Federal digitization funding for real-world evidence infrastructure enables automated long-term safety surveillance that satisfies EMA pharmacovigilance requirements at reduced cost.
- Electroporation Transduction:Non-viral DNA delivery systems are displacing lentiviral dependency, reducing COGS and eliminating replication-competent lentivirus biosafety containment requirements.
Industry Challenges
- GMP Aseptic Processing Talent Scarcity:Cell therapy manufacturing requires operators certified in both ISO 5 cleanroom protocols and flow cytometry analytics, a dual-competency profile concentrated among fewer than 2,000 professionals globally.
- Site-of-Care Integration Complexity:CAR-T administration requires ICU-level cytokine release syndrome monitoring capabilities that most community oncology practices lack, forcing patient referral to academic centers with available beds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chimeric Antigen Receptor (CAR) T-Cell Therapy Market |
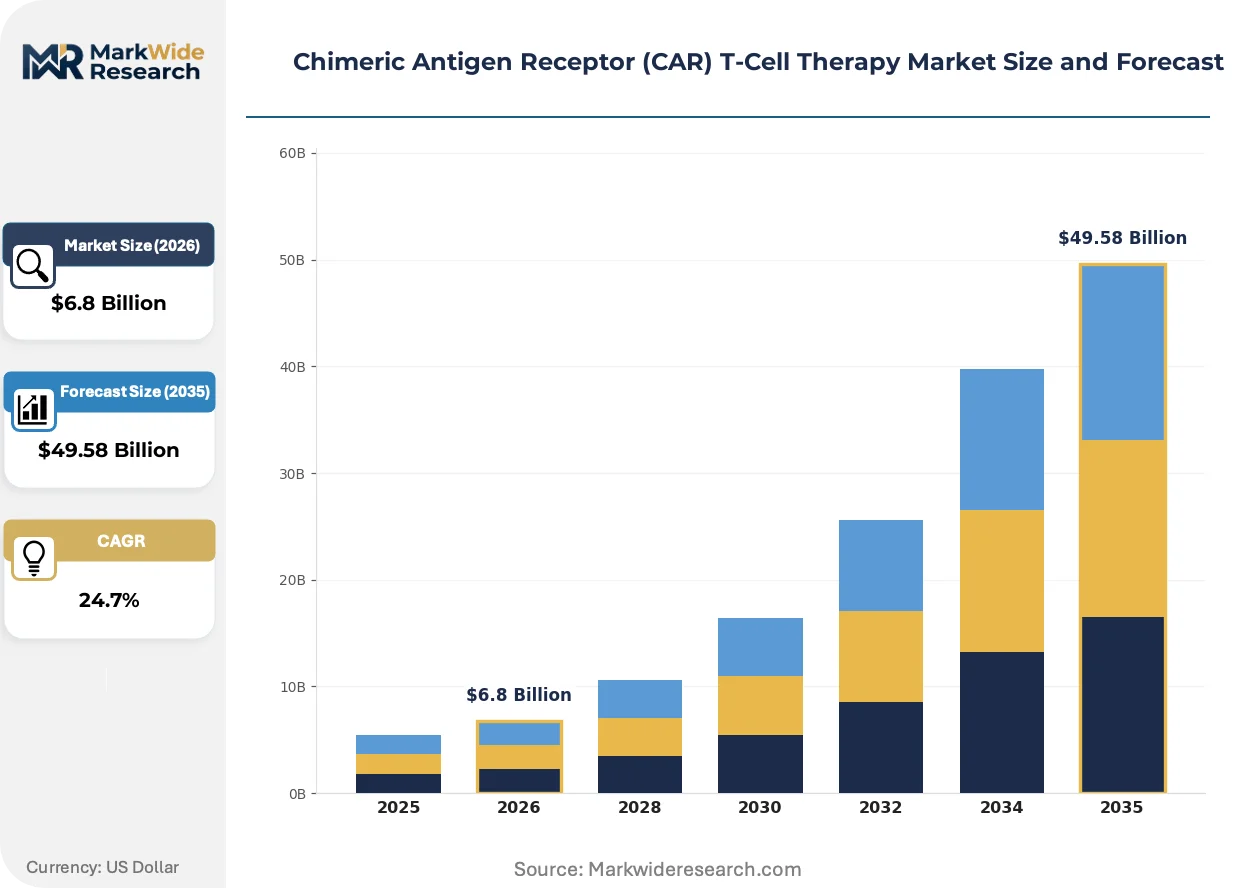
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous CAR-T, Allogeneic CAR-T, CAR-NK Cells, CAR-Macrophages Indication: Acute Lymphoblastic Leukemia, Non-Hodgkin Lymphoma, Chronic Lymphocytic Leukemia, Multiple Myeloma End User: Hospitals, Oncology Clinics, Research Institutions, Blood Banks Delivery Mode: Intravenous, Intratumoral, Subcutaneous, Intrapleural |
| Companies Covered | Bristol-Myers Squibb Company, Johnson & Johnson Services, Inc., Gilead Sciences, Inc., Novartis AG, JW Therapeutics, Legend Biotech, Cartesian Therapeutics, Inc., Merck & Co., Inc., Sangamo Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market Strategic Shifts & Innovations
Next-generation CAR architectures are collapsing the functional boundaries between cell therapy and small-molecule oncology, as synthetic biology tools enable receptor designs with Boolean logic gating and inducible safety switches.
Armored CAR-T constructs incorporating constitutive cytokine secretion domains are collapsing the efficacy ceiling for hypofunctional T-cell products in immunosuppressive tumor microenvironments. Bristol-Myers Squibb and academic consortiums in the United States and China are advancing IL-15-secreting variants into Phase II solid tumor trials. The structural consequence is a shift from salvage lymphoma applications toward earlier-line settings where T-cell fitness remains intact.
The EU AI Act's risk classification for clinical decision-support algorithms is reshaping how CAR-T treatment centers deploy machine learning for patient selection and toxicity prediction. German HTA bodies now require algorithmic transparency documentation as a condition of reimbursement eligibility. Sponsors with operations in France and Germany are reconfiguring their real-world evidence platforms to satisfy both GDPR data minimization requirements and CNIL audit standards for automated processing.
Hospital procurement committees are consolidating CAR-T purchasing through centralized pharmacy and therapeutics committees rather than individual physician preference. The United States exhibits the most pronounced concentration, with 60% of CAR-T volume flowing through 40 academic medical centers with dedicated cellular therapy pharmacy infrastructure. Community oncology networks without on-site apheresis capability are ceding patient capture to these hub institutions.
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market Segmentation
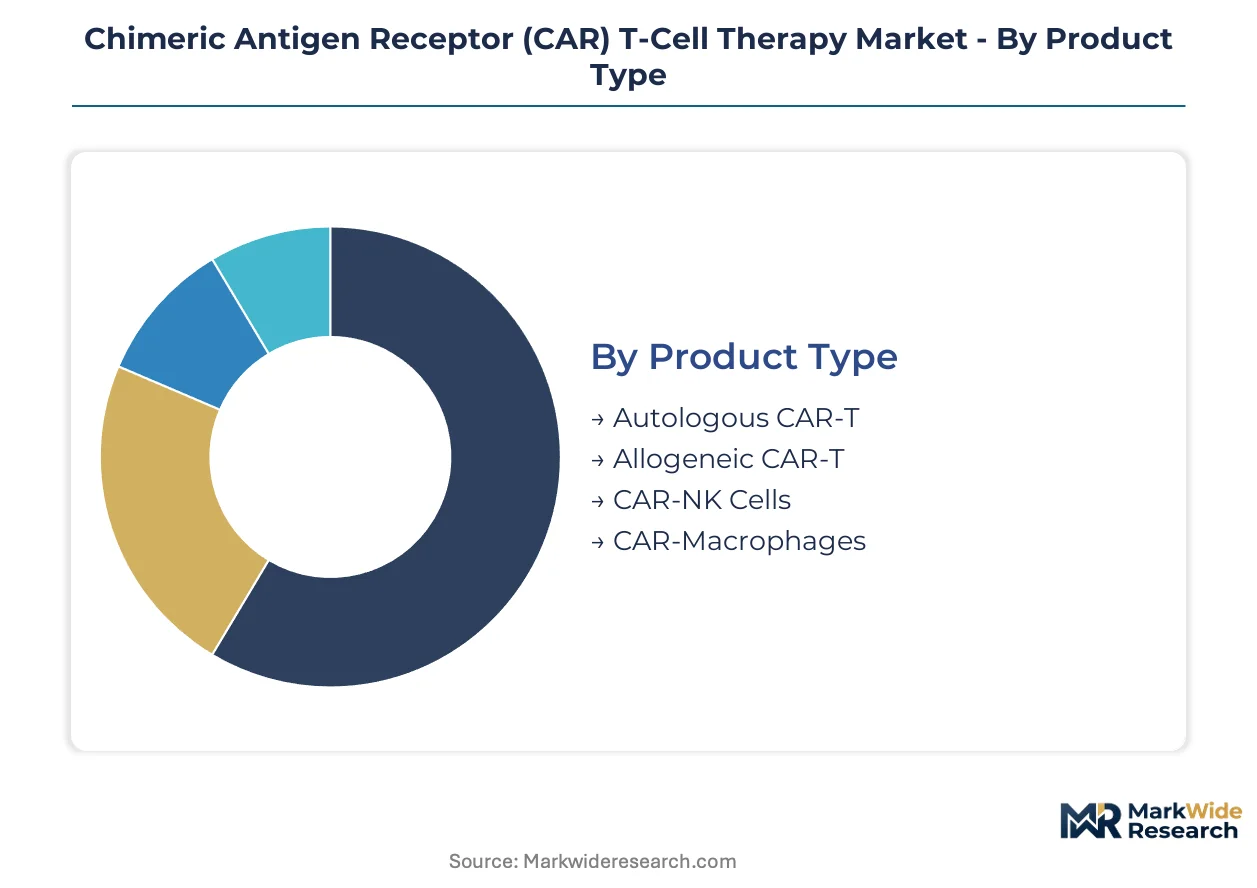
CAR-T therapy segmentation reveals how manufacturing architecture, clinical application, and site-of-care capabilities intersect to determine commercial viability. Each dimension carries distinct regulatory, reimbursement, and operational requirements that reshape competitive strategy across the value chain.
Product Type:
The use-case spectrum spans patient-specific manufacturing to off-the-shelf inventory models, with each platform carrying fundamentally different COGS structures and scalability constraints.
- Autologous CAR-T:Patient-derived T cells undergo ex vivo transduction and expansion in GMP cleanrooms, requiring 3-4 week vein-to-vein timelines. Demand concentrates in United States academic medical centers where CMS reimbursement codes and dedicated cellular therapy infrastructure offset manufacturing complexity. FDA's regenerative medicine advanced therapy designation accelerates development timelines for novel constructs in this category.
- Allogeneic CAR-T:Donor-sourced T cells enable inventory-based distribution and collapse donor-matching constraints. Manufacturing failures and vein-to-vein timing bottlenecks are driving development capital toward this architecture, though graft-versus-host disease risk requires sophisticated genome editing.
- CAR-NK Cells:Natural killer cell platforms eliminate cytokine release syndrome risk and enable allogeneic sourcing without GvHD complications.
- CAR-Macrophages:Myeloid lineage engineering penetrates immunosuppressive solid tumor microenvironments inaccessible to T-cell products.
The dominant share belongs to Autologous CAR-T, while Allogeneic CAR-T is closing the gap fastest.
Indication:
Cost tier stratification separates salvage hematology applications from earlier-line settings where T-cell fitness and manufacturing success rates improve.
- Non-Hodgkin Lymphoma:CD19-directed constructs in diffuse large B-cell lymphoma generate the highest procedure volumes due to established reimbursement pathways and second-line FDA approvals. German HTA processes and France's CEPS pricing negotiations create parallel value demonstration requirements across European markets.
- Multiple Myeloma:BCMA-targeted therapies expand addressable populations as earlier-line trial readouts broaden eligibility criteria. Manufacturing demand is climbing fastest in China where centralized treatment hubs cluster GMP capacity.
- Acute Lymphoblastic Leukemia:Pediatric and young adult applications drive high-complexity manufacturing with stringent potency release criteria.
- Chronic Lymphocytic Leukemia:T-cell exhaustion in heavily pretreated patients creates efficacy ceilings that next-generation armored constructs aim to breach.
Non-Hodgkin Lymphoma commands the largest procedure base, though Multiple Myeloma exhibits the steepest expansion trajectory as earlier-line indications mature.
End User:
Customer type determines site certification requirements, with ICU-level cytokine release syndrome monitoring capabilities filtering eligible administration locations.
- Hospitals:Academic medical centers with dedicated cellular therapy pharmacy infrastructure capture the majority of infusion volume. United States concentration is pronounced, with 40 centers handling 60% of national CAR-T procedures.
- Oncology Clinics:Community-based administration remains limited by apheresis collection requirements and cryopreservation logistics.
- Research Institutions:Early-phase trial sites drive manufacturing process innovation and next-generation construct validation.
- Blood Banks:Apheresis collection hubs are clustering GMP-compliant capacity within 200-mile patient catchment zones across Germany and China.
Hospitals retain the dominant share, while Blood Banks are gaining operational significance fastest as centralized apheresis networks expand.
Delivery Mode:
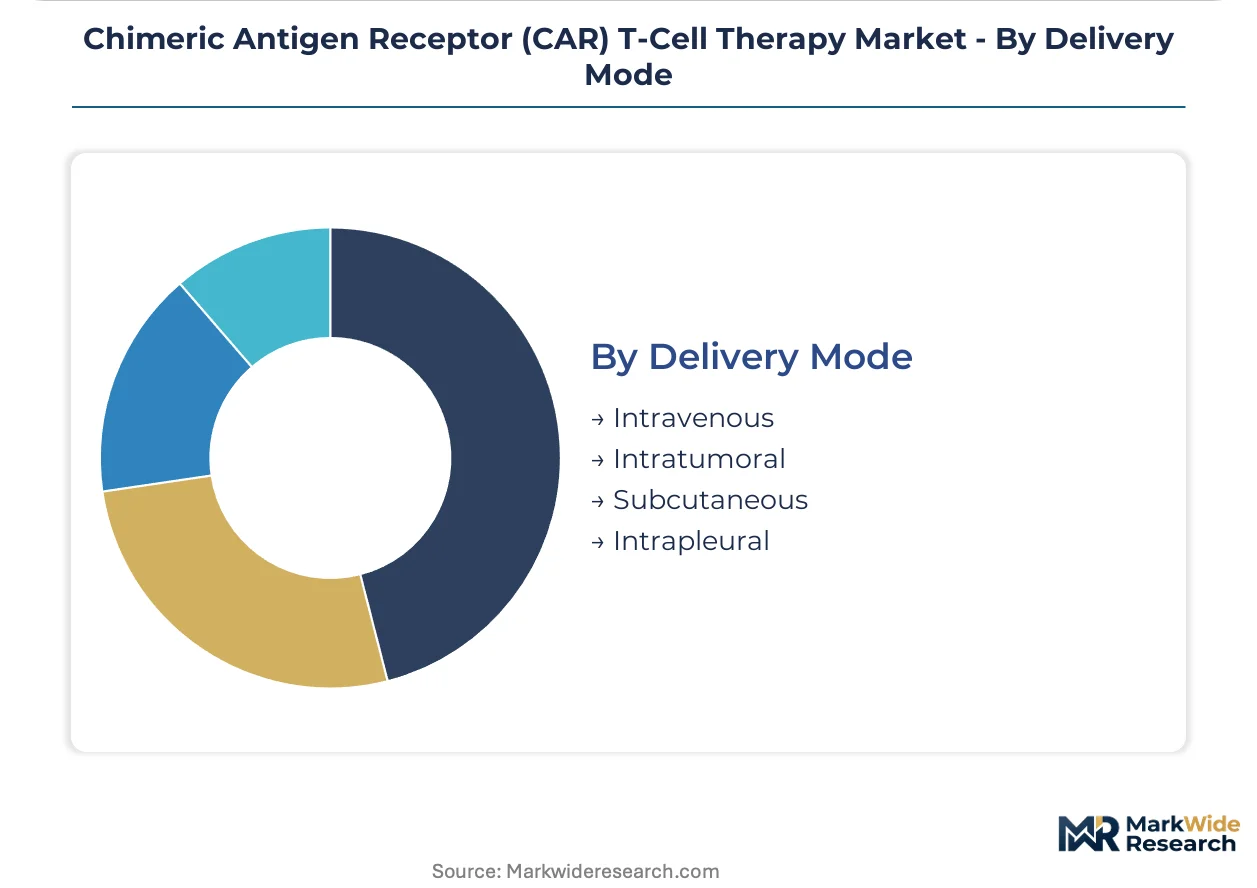
Application route selection follows tumor accessibility and microenvironment characteristics, with systemic administration dominating hematologic indications.
- Intravenous:Systemic circulation delivery enables broad biodistribution for hematologic malignancies and represents the standard for all approved CAR-T products. EMA's ATMP classification system governs administration site certification requirements across European markets.
- Intratumoral:Direct injection into solid tumor masses bypasses systemic toxicity but requires interventional radiology capabilities.
- Subcutaneous:Simplified administration protocols are under investigation for armored constructs with enhanced persistence.
- Intrapleural:Pleural cavity delivery targets mesothelioma and lung metastases with regional concentration advantages.
Intravenous administration holds the dominant share, while Intratumoral delivery is advancing most quickly in solid tumor development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's regenerative medicine advanced therapy designation anchors commercial momentum in the United States, while EMA's ATMP classification and China's NMPA innovation pathways create parallel regulatory architectures shaping regional deployment patterns.
United States
CMS reimbursement codes and dedicated cellular therapy infrastructure drive procedure concentration across academic medical centers. The FDA's accelerated approval pathways compress development timelines for novel constructs. Forty centers in metropolitan clusters including Boston, Houston, and Philadelphia handle the majority of national infusion volume.
Germany
Centralized apheresis networks within 200-mile patient catchment zones expand GMP-compliant cleanroom capacity. The country's DigiGesund initiative funds real-world evidence infrastructure that satisfies EMA pharmacovigilance requirements. Manufacturing hubs in Munich and Heidelberg anchor European production gravity for autologous platforms.
China
NMPA's breakthrough therapy designation attracts development capital toward BCMA-targeted multiple myeloma indications. Centralized treatment hubs in Shanghai and Beijing cluster GMP manufacturing capacity. JW Therapeutics and Legend Biotech exemplify domestic platform maturation competing alongside multinational sponsors.
United Kingdom
NHS England's specialized commissioning framework determines site certification requirements for CAR-T administration. MHRA's post-Brexit regulatory autonomy enables streamlined ATMP assessment timelines. London's cellular therapy corridor concentrates apheresis collection and infusion capabilities within the Imperial-UCL hospital network.
Switzerland
Swissmedic's streamlined ATMP authorization procedures attract European headquarters functions for cell therapy sponsors. Basel's pharmaceutical manufacturing corridor leverages existing biologics infrastructure for cleanroom expansion. The country's reimbursement negotiations with compulsory health insurers establish reference pricing benchmarks for neighboring markets.
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market Key Industry Players
Integrated pharmaceutical conglomerates and emerging cell therapy specialists split the market into distinct capability tiers. Consolidation dynamics concentrate manufacturing expertise among sponsors with established GMP footprints and viral vector supply relationships. Three archetypes dominate: legacy oncology majors with autologous infrastructure, allogeneic platform developers, and regional biotechs leveraging local regulatory pathways. Competitive intensity centers on vein-to-vein timeline compression and earlier-line indication expansion.
Among North American majors, Bristol-Myers Squibb Company, Gilead Sciences, Inc., and Novartis AG occupy positions spanning both B-cell malignancies and multiple myeloma. Novartis AG exemplifies early-mover manufacturing footprint advantages across European and North American treatment hubs. Gilead Sciences, Inc. anchors lymphoma segment positioning through established autologous production infrastructure. Bristol-Myers Squibb Company competes on dual-indication breadth. Johnson & Johnson Services, Inc. and Merck & Co., Inc. represent diversified pharmaceutical conglomerates with cell therapy portfolio extensions. JW Therapeutics and Legend Biotech exemplify China-based platform developers leveraging NMPA pathways and centralized manufacturing infrastructure.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Johnson & Johnson Services, Inc. |
| Gilead Sciences, Inc. |
| Novartis AG |
| JW Therapeutics |
| Legend Biotech |
| Cartesian Therapeutics, Inc. |
| Merck & Co., Inc. |
| Sangamo Therapeutics |
| Others |
Cost & Logistics Intelligence
GMP cleanroom undercapacity in China and Germany is compressing manufacturing slot availability and amplifying pricing power for sponsors with captive production assets. Utilization rates above 85 percent at centralized apheresis hubs enable premium positioning for vein-to-vein timeline guarantees, while forcing smaller oncology centers toward higher-cost third-party manufacturing arrangements.
Pricing Analysis
Price spreads between United States academic medical centers and European hospital networks reflect divergent reimbursement architectures rather than manufacturing cost differentials. The dominant pricing model is value-based, with CMS and German HTA bodies calibrating payment to progression-free survival endpoints. Price differentiation hinges on vein-to-vein timeline guarantees and ICU-level toxicity management bundling. Cost compression in the community oncology segment is intensifying as referral networks consolidate toward hub institutions with cellular therapy pharmacy infrastructure. Community oncology practices exhibit the highest price sensitivity due to capital exclusion from cryopreservation logistics, while academic medical centers with dedicated apheresis capability show lowest sensitivity.
Supply Chain Analysis
United States export controls on GMP-grade lentiviral vector production equipment constrain technology transfer to Chinese contract manufacturers and fragment global supply resilience. Geographic supply concentration centers on the United States, Germany, and China for cleanroom suites and viral vector production. Raw material dependencies include cryopreserved apheresis material, GMP-grade cytokines, and replication-deficient lentiviral vectors. Single-source vulnerability at the transduction-stage input level creates systemic risk, with three North American contract manufacturers controlling the majority of viral vector capacity. Distribution runs through hospital-based cellular therapy pharmacies with cold chain custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with FDA regenerative medicine advanced therapy designation and EMA ATMP classification creating multi-year head starts for approved sponsors. Network effects from centralized apheresis hub clustering reinforce incumbent positioning.
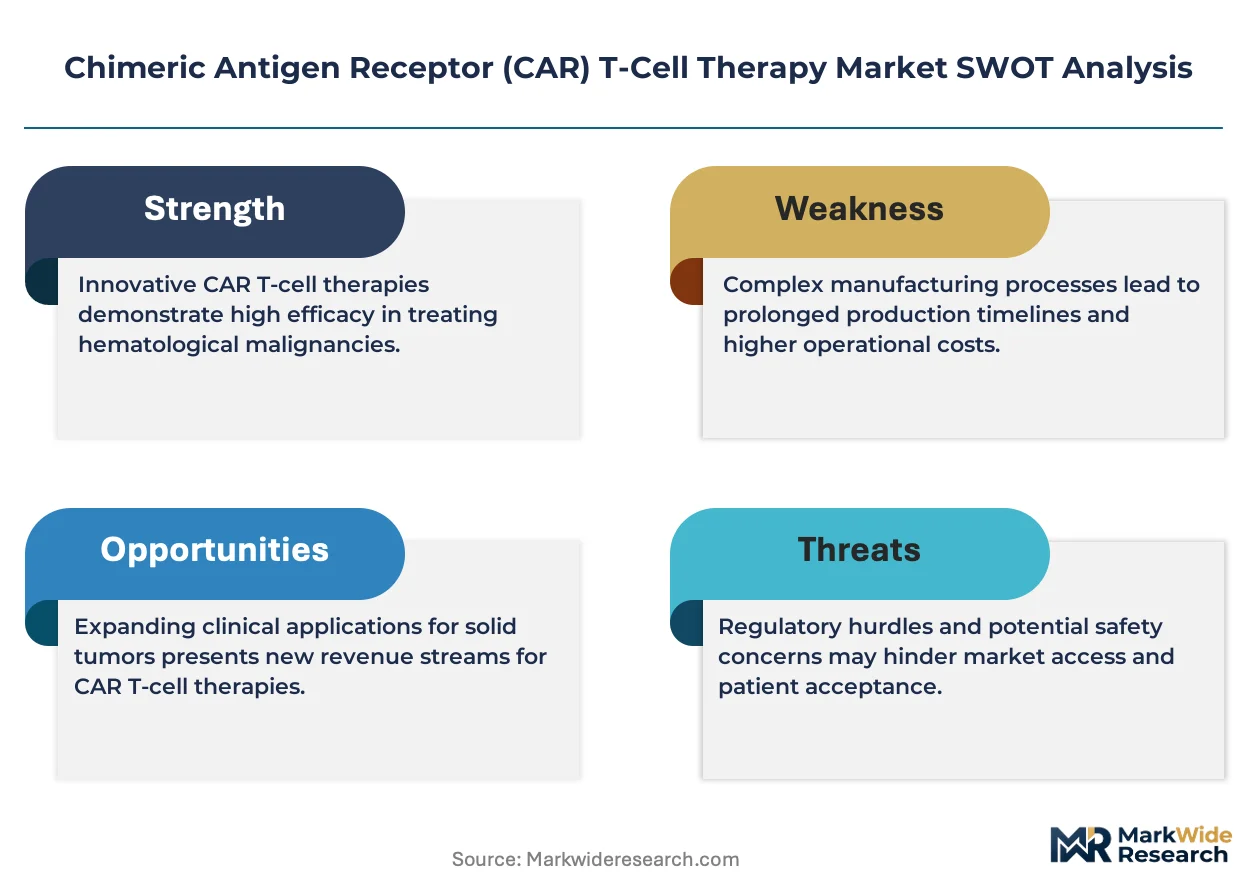
For Market Incumbents: Build manufacturing-slot scarcity as a competitive moat by expanding GMP cleanroom capacity in Munich and Shanghai catchment zones. Secure backward integration into lentiviral vector production to eliminate single-source dependencies threatening supply continuity. Consolidate apheresis collection partnerships within 200-mile patient zones to forestall emerging allogeneic platform competitors. For New Entrants and Emerging Players: Blood bank apheresis networks in secondary German and Chinese cities represent the most penetrable white-space opportunity, with community oncology referral leakage creating patient capture potential. Target solid tumor CAR-M and CAR-NK platforms where manufacturing complexity barriers remain lower than autologous T-cell products. Pursue electroporation transduction partnerships to bypass viral vector supply constraints. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sponsors with approved earlier-line indications and established hospital formulary contracts. Long-term viability favors platforms with allogeneic inventory models capable of collapsing vein-to-vein timelines below two weeks. Acquisition targets should demonstrate electroporation or non-viral transduction capabilities alongside GMP manufacturing footprints. Watch for EMA post-authorization study obligation relief through Germany's DigiGesund real-world evidence infrastructure as an inflection signal for European margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive GMP cleanroom expansion in Boston and Heidelberg clusters compresses vein-to-vein timelines for autologous products. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation accelerates solid tumor construct development timelines. |
| Backward Integration | In-house lentiviral vector production eliminates single-source dependencies at transduction-stage inputs. |
| Technology Licensing | Electroporation transduction partnerships reduce COGS and biosafety containment requirements. |
| Hospital System Partnership | Exclusive apheresis collection agreements within 200-mile zones lock patient referral flows. |
Research Approach
A standing panel of cell therapy manufacturing directors, hospital pharmacy therapeutics committee chairs, regulatory affairs leads at commercial sponsors, and payer access specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submission documents, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up procedure volume estimates triangulated against top-down market value reconstructions across the analysis window.
Scenario-bracketing anchored the analytical framework with high, base, and low cases reflecting differential approval timelines for allogeneic platforms and solid tumor indication expansion. Segmentation dimensions modeled included product type, indication, end user, and regional regulatory cluster. CAGRs derived from procedure volume trajectories and pricing evolution across treatment line migrations. Forecast inputs incorporated CMS TEC assessment methodology shifts and EMA pharmacovigilance cost obligations.
The forecast holds incumbent behavior within observed patterns; aggressive manufacturing capacity additions by emerging allogeneic specialists would shift outcomes toward accelerated price competition. Material shifts in FDA accelerated approval stringency or EMA ATMP post-authorization burden would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Global Liver Cancer Therapeutics Market
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market