
 Irritable Bowel Syndrome (IBS) Treatment Market | 2026-2036
Irritable Bowel Syndrome (IBS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Irritable Bowel Syndrome (IBS) Treatment Market Foresight
Pharmaceutical distribution through specialty pharmacy networks is tilting toward integrated care models that manage chronic gastrointestinal conditions. AbbVie leverages its immunology infrastructure to sustain formulary access for complex IBS therapies across major payers. Takeda Pharmaceutical Company Limited anchors its position in Asia-Pacific markets through deep relationships with academic medical centers. Ironwood Pharmaceuticals Inc. differentiates via gastrointestinal-focused commercial operations that bypass primary care gatekeeping.
Irritable Bowel Syndrome treatment encompasses pharmacological and non-pharmacological interventions targeting visceral hypersensitivity, gut-brain axis dysregulation, and altered motility patterns, with formulations ranging from 5-HT3 antagonists to guanylate cyclase-C agonists dosed at microgram-to-milligram scales for symptom-specific modulation. Antispasmodics retain the largest volume share among product types due to decades of generic availability and first-line prescribing habits, while probiotics command expanding shelf space in retail pharmacy as patients self-direct toward microbiome-targeted approaches. The constipation predominant indication generates premium pricing power compared to mixed type presentations, where treatment response variability complicates reimbursement negotiations.
The FDA maintains stringent efficacy benchmarks for IBS drug approvals through its Center for Drug Evaluation and Research, requiring composite responder endpoints that combine abdominal pain and stool consistency improvements. EMA's Committee for Medicinal Products for Human Use applies similar stringency across European markets, creating parallel development hurdles that filter early-stage pipelines. Stakeholders must monitor how gut-brain axis biomarker validation reshapes trial design and payer willingness to cover novel mechanism therapies outside traditional symptom-management frameworks.
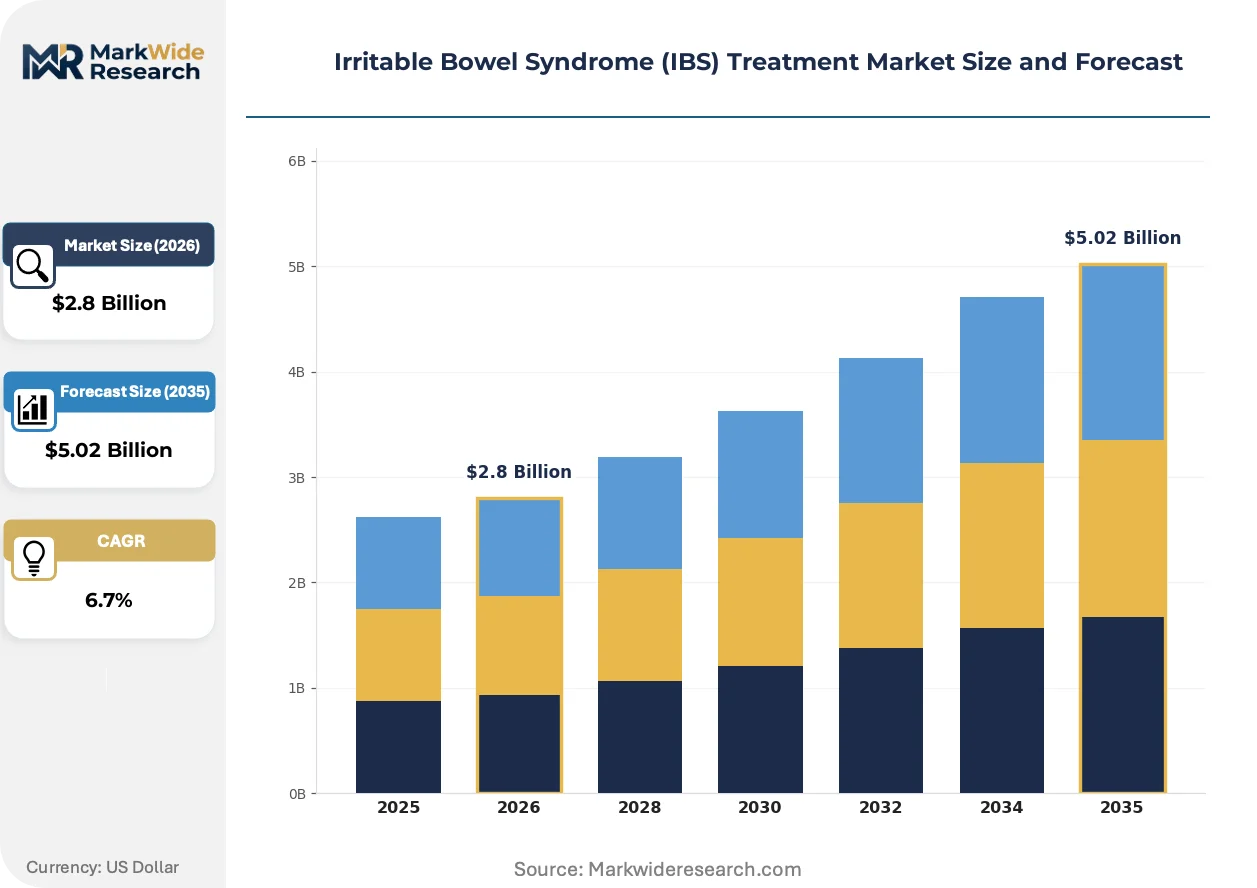
Market Dynamics
The FDA's accelerated approval pathways for functional gastrointestinal disorder drugs are compressing development timelines while simultaneously raising the bar for composite responder endpoints that combine abdominal pain and stool consistency metrics.
Growth Catalysts
- Diagnostic Testing Expansion:Direct-to-consumer gut microbiome profiling and hydrogen breath testing are expanding the addressable patient pool by identifying undiagnosed IBS cases before specialist referral.
- EMA Parallel Scientific Advice:The Committee for Medicinal Products for Human Use offers synchronized guidance that reduces redundant clinical trial phases across European markets, accelerating multi-regional submissions for novel gut-brain axis therapies.
- Specialty Pharmacy Networks:Integrated care models managing chronic gastrointestinal conditions are consolidating prescription fulfillment, improving medication adherence monitoring and prior authorization efficiency for complex IBS therapies.
Market Restraints
- Responder Endpoint Stringency:FDA's Center for Drug Evaluation and Research mandates composite benchmarks that exclude single-symptom improvers, filtering early-stage pipelines and elevating Phase III failure rates for mechanism-first candidates.
- Generic Antispasmodic Dominance:Decades of dicyclomine and hyoscyamine availability at pennies per dose create a floor price that novel mechanism therapies must justify through outcomes data payers rarely fund.
- Microbiome Target Uncertainty:Probiotic strain-specific efficacy remains inconsistent across patient subtypes, limiting prescriber confidence and formulary placement for microbiome-directed interventions.
Strategic Opportunities
- Constipation-Predominant Premium:The IBS-C subtype generates superior pricing power versus mixed presentations, creating incentive for developers to enrich trial populations toward this responsive segment.
- Gut-Brain Axis Biomarker Validation:CRF receptor and neurokinin antagonist development is reshaping trial design toward mechanistic stratification, potentially unlocking payer coverage for therapies outside traditional symptom-management frameworks.
- Asia-Pacific Academic Partnerships:Deep relationships with medical centers in Japan and South Korea offer access to treatment-naïve populations and differentiated regulatory pathways through PMDA and MFDS.
Industry Challenges
- Reimbursement Negotiation Complexity:Mixed-type IBS presentations exhibit treatment response variability that complicates health technology assessment submissions and formulary access discussions with pharmacy benefit managers.
- Primary Care Gatekeeping:Gastroenterology-focused commercial operations must bypass general practitioner skepticism toward functional disorder diagnoses, requiring educational investment that delays revenue ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irritable Bowel Syndrome (IBS) Treatment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antispasmodics, Antidepressants, Probiotics, Dietary Fiber Indication: Diarrhea Predominant, Constipation Predominant, Mixed Type, Post-Infectious Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Home Care, Pharmacists |
| Companies Covered | Allergan plc, AstraZeneca plc, Ironwood Pharmaceuticals Inc., Sebela Pharmaceuticals Inc., Bausch Health Companies Inc., AbbVie Inc., Astellas Pharma Inc., Ardelyx Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irritable Bowel Syndrome (IBS) Treatment Market Shifts & Advancements
Digital biomarker capture and decentralized trial execution are converging to reshape how visceral hypersensitivity endpoints are measured, shifting evidence generation away from clinic-centric models.
Electronic patient-reported outcome platforms is virtualizing the collection of real-time abdominal pain and stool diary data, replacing paper-based symptom tracking that suffered from recall bias and incomplete capture. Specialty IBS centers in the United States are adopting these tools at scale for both clinical care and observational research. The technology is compressing the gap between patient experience and regulatory submission datasets, enabling more granular responder analyses.
EMA's qualification opinion process for novel digital endpoints is creating a pathway for gut-brain axis drug developers to submit smartphone-captured metrics as primary or secondary measures. This regulatory flexibility is reducing the burden of in-clinic assessment visits that previously deterred patient retention. European sponsors are responding by embedding bring-your-own-device protocols into Phase IIb and Phase III protocols earlier than US counterparts.
Subscription-based diagnostic access is altering how patients initiate treatment-seeking behavior, with monthly microbiome monitoring services replacing one-time specialist consultations as the entry point to IBS care. Retail pharmacy chains are capturing this demand through partnerships with direct-to-consumer testing laboratories, displacing traditional gastroenterology referral patterns. This channel shift is most visible in metropolitan United States markets where insurance coverage for functional disorder workups remains inconsistent.
Irritable Bowel Syndrome (IBS) Treatment Market Segmentation
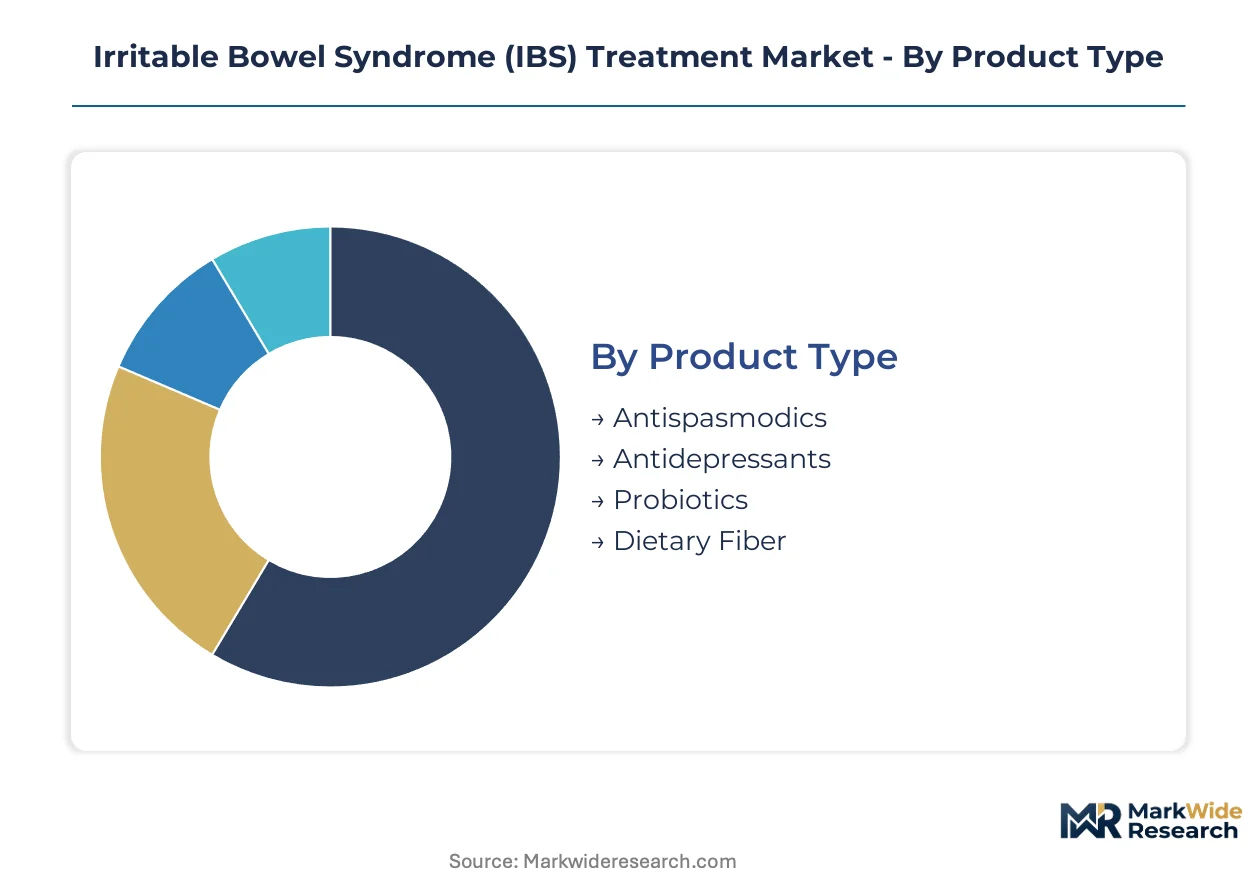
IBS treatment segmentation reveals how symptom heterogeneity and care setting fragmentation create distinct commercial battlegrounds. Product type and indication splits determine pricing power, while delivery mode and end user channels shape go-to-market economics.
Product Type:
Cost tier stratification separates commodity generics from premium mechanism-driven therapies with differentiated formulary access.
- Antispasmodics:Dicyclomine and hyoscyamine formulations dominate first-line prescribing through decades of generic availability at minimal per-dose cost. Primary care gatekeeping in the United States and European reimbursement floors sustain volume leadership despite modest efficacy signals.
- Antidepressants:Low-dose tricyclics and SSRIs target central sensitization pathways with dual pain-mood benefits. Academic medical centers in Japan and Germany drive off-label utilization where gut-brain axis research has penetrated specialist training.
- Probiotics:Strain-specific formulations compete for retail pharmacy shelf space as patients self-direct toward microbiome modulation.
- Dietary Fiber:Soluble and insoluble supplements anchor non-prescription management with lowest out-of-pocket burden.
Antispasmodics command the established base. The steepest expansion runs through probiotics as direct-to-consumer channels reshape patient initiation patterns.
Indication:
Application focus determines trial design complexity and payer willingness to cover novel mechanisms outside traditional frameworks.
- Constipation Predominant:Guanylate cyclase-C agonists and secretagogues generate superior pricing power through measurable endpoint achievement. FDA composite responder benchmarks favor this subtype with clearer stool consistency metrics.
- Diarrhea Predominant:5-HT3 antagonists and bile acid sequestrants address visceral hypersensitivity with established efficacy profiles. Specialist IBS centers in the United States concentrate prescribing for refractory cases.
- Mixed Type:Treatment response variability complicates health technology assessment submissions across European markets.
- Post-Infectious:Emerging mechanistic category linking acute gastroenteritis to persistent symptoms.
Constipation predominant applications concentrate premium pricing. Mixed type presentations face the steepest reimbursement negotiation complexity.
Delivery Mode:
Volume concentration in oral formats reflects chronic disease management economics and patient preference for self-administration.
- Oral:Tablets, capsules, and powders dominate prescription fulfillment through retail and specialty pharmacy networks. Home care adherence monitoring integrates with digital biomarker platforms for real-time symptom tracking.
- Injectable:Biologic and peptide formulations target severe refractory populations in hospital outpatient settings.
- Topical:Limited application for localized symptom management with minimal systemic exposure.
- Intravenous:Reserved for acute decompensation or clinical trial protocols requiring controlled dosing.
Oral delivery commands the established base. The steepest expansion trajectory runs through injectable formats as gut-brain axis biologics advance through development pipelines.
End User:
Customer type fragmentation reflects the tension between primary care gatekeeping and specialist-led complex therapy management.
- Hospitals:Academic medical centers anchor clinical trial recruitment and refractory case referral patterns. PMDA-designated core hospitals in Japan concentrate treatment-naïve populations for novel mechanism studies.
- Clinics:Gastroenterology-focused operations bypass general practitioner skepticism through direct patient acquisition. Ironwood Pharmaceuticals and similar GI-specialized commercial organizations target this channel exclusively.
- Home Care:Digital health integration enables remote monitoring for stable patients on maintenance therapy.
- Pharmacists:Retail and specialty pharmacy counseling drives probiotic and fiber supplement selection.
Hospitals command the established base for complex therapy initiation. The steepest expansion runs through clinics as integrated care models consolidate chronic gastrointestinal management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution dominance for temperature-sensitive biologics targeting functional gastrointestinal disorders.
United States
Specialized IBS centers in Boston and the Research Triangle Park drive treatment-seeking behavior through direct-to-consumer diagnostic testing integration. FDA accelerated approval pathways compress development timelines for gut-brain axis therapies. The Mayo Clinic's Rochester campus anchors clinical trial recruitment for novel mechanism candidates.
Germany
Academic medical centers in Heidelberg and Berlin concentrate prescriber training in central sensitization pathways for off-label antidepressant utilization. EMA's Committee for Medicinal Products for Human Use applies stringent composite responder benchmarks that filter early-stage pipelines. The BioRN cluster in the Rhine-Neckar region hosts microbiome-targeted intervention development.
Japan
PMDA-designated core hospitals in Tokyo and Osaka provide access to treatment-naïve populations for novel gut-brain axis studies. METI funding for functional disorder research accelerates domestic biopharma investment. The Kansai region's pharmaceutical manufacturing base supplies Asia-Pacific markets with 5-HT3 antagonist formulations.
United Kingdom
NHS England's specialized commissioning frameworks for functional gastrointestinal disorders concentrate prescribing authority in tertiary referral centers. MHRA alignment with EMA qualification opinions for digital endpoints enables smartphone-captured symptom metrics in trials. The Cambridge-London corridor anchors microbiome diagnostic startup formation.
South Korea
MFDS fast-track designations for rare and intractable diseases extend to severe refractory IBS populations in Seoul and Busan. National Health Insurance Service reimbursement negotiations favor constipation-predominant subtypes with objective endpoints. The Songdo cluster integrates digital health platforms with pharmaceutical development.
Irritable Bowel Syndrome (IBS) Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around gastrointestinal-focused commercial operations and immunology infrastructure that sustain formulary access across major payers. Three archetypes dominate: diversified pharmaceutical conglomerates leveraging existing specialty pharmacy networks, pure-play GI specialists bypassing primary care gatekeeping, and biotech developers targeting mechanistic stratification through biomarker validation. Competitive moves concentrate on strategic partnerships with academic medical centers and geographic expansion through Asia-Pacific regulatory pathways.
Among North American developers, Ironwood Pharmaceuticals Inc. and Ardelyx Inc. occupy positions within the gastrointestinal-specialist tier, while AbbVie Inc. anchors the diversified pharmaceutical archetype through immunology infrastructure repurposing. Takeda Pharmaceutical Company Limited represents the Asia-Pacific integrated model through deep relationships with Japanese academic medical centers. These three exemplify how scale, specialization, and regional anchoring create distinct competitive positioning within FDA and EMA approval frameworks.
| Leading Market Players |
|---|
| Allergan plc |
| AstraZeneca plc |
| Ironwood Pharmaceuticals Inc. |
| Sebela Pharmaceuticals Inc. |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Ardelyx Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution capacity for temperature-sensitive biologics, with downstream pricing power flowing to manufacturers that secure dedicated freezer capacity during peak demand windows. This geographic concentration creates tiered access where specialty pharmacy networks command premium formulary placement for complex IBS therapies.
Pricing Analysis
Volume-discount tiering structures separate three distinct pricing bands across the IBS treatment landscape. Premium mechanism-driven therapies—guanylate cyclase-C agonists and gut-brain axis biologics—command formulary access through outcomes-based contracts with major pharmacy benefit managers. Price differentiation hinges on FDA approval tier and prescriber specialization level, with gastroenterology-focused products capturing margin premiums over primary care-accessible generics. Cost compression in the antispasmodic tier intensifies as decades of dicyclomine and hyoscyamine availability at minimal per-dose cost forces novel entrants to justify value through composite responder data. Primary care gatekeepers exhibit highest price sensitivity, while academic medical centers demonstrate willingness to absorb premium pricing for mechanistic stratification capabilities.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese and South Korean pharmaceutical manufacturers are reshaping procurement dynamics for Asia-Pacific academic medical centers. Active pharmaceutical ingredient production draws from India, China, and the United States, with fermentation-derived biologics sourcing from specialized facilities in Ireland and Singapore. Supply chain risk centers on single-source vulnerability for 5-HT3 antagonist precursors and guanylate cyclase-C agonist peptide intermediates. Distribution runs through integrated specialty pharmacy networks that consolidate prescription fulfillment and adherence monitoring for chronic gastrointestinal conditions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specialty pharmacy network consolidation and integrated care model expansion, fragmenting traditional primary care gatekeeping channels. This shift rewards manufacturers that bypass general practitioner skepticism through direct gastroenterology clinic relationships.
For Market Incumbents: Build regulatory data moats through EMA qualification opinion submissions for digital biomarker endpoints. AbbVie and Takeda demonstrate how immunology infrastructure repurposing and academic medical center anchoring defend against generic antispasmodic erosion. Capacity addition in Japan and South Korea secures treatment-naïve patient access for novel mechanism studies. Channel control through specialty pharmacy exclusivity agreements limits emerging entrant formulary access. For New Entrants and Emerging Players: Asia-Pacific underpenetration in microbiome-directed interventions offers white-space expansion beyond saturated North American markets. Constipation-predominant IBS-C subtypes present the most penetrable indication segment due to clearer FDA composite responder benchmarks and superior pricing power. Direct-to-consumer diagnostic testing partnerships enable patient acquisition outside traditional gastroenterology referral patterns, displacing primary care gatekeeping through subscription-based microbiome monitoring services. For Investors and Strategic Acquirers: Long-term, this sits as a mechanistic stratification play because gut-brain axis biomarker validation is reshaping trial design and payer coverage frameworks outside traditional symptom-management approaches. Acquisition targets should concentrate on biotech developers with CRF receptor or neurokinin antagonist pipelines and validated digital endpoint capture capabilities. The signal to watch is FDA accelerated approval pathway utilization rates for functional gastrointestinal disorder candidates, indicating regulatory appetite for novel mechanism therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Biomarker Qualification | EMA qualification opinion submissions enable smartphone-captured metrics as primary endpoints in gut-brain axis trials. |
| Asia-Pacific Academic Partnership | PMDA and MFDS relationships unlock treatment-naïve populations and differentiated regulatory pathways for novel mechanisms. |
| Specialty Pharmacy Integration | Consolidated prescription fulfillment improves adherence monitoring and prior authorization efficiency for complex therapies. |
| Constipation-Predominant Trial Enrichment | IBS-C subtype concentration generates superior pricing power through clearer stool consistency endpoint achievement. |
| Direct-to-Consumer Diagnostic Channel | Microbiome testing partnerships displace traditional referral patterns and capture patient initiation upstream of specialist care. |
Research Methodology
The analysis maps antispasmodic, antidepressant, probiotic, and biologic therapeutic segments, each validated through gastroenterology specialists, formulary directors at pharmacy benefit managers, regulatory affairs leads, and specialty pharmacy operations executives. Primary interview data triangulates against FDA Center for Drug Evaluation and Research filings, EMA Committee for Medicinal Products for Human Use submissions, ClinicalTrials.gov protocol registries, and formulary database audits. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure reconciliation anchor value estimates across the projection horizon.
Assumptions held FDA accelerated approval pathway utilization rates and EMA parallel scientific advice uptake patterns within observed historical ranges, while varying gut-brain axis biomarker validation timelines and digital endpoint qualification speeds. Segmentation dimensions include product mechanism class, IBS subtype indication, delivery mode format, prescriber specialty tier, and regional regulatory cluster. CAGRs derive from patient diagnosis expansion rates, prescription volume per diagnosed case trends, and price evolution by mechanism novelty tier. Forecast inputs incorporate direct-to-consumer diagnostic testing penetration curves and specialty pharmacy network consolidation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified pharmaceutical conglomerates or pure-play GI specialists through vertical integration or exclusive biologic licensing would shift outcomes. Payer coverage restriction for mixed-type IBS presentations, microbiome target efficacy failures, or macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Global Spinal Muscular Atrophy Treatment Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market