
 Spina Bifida Market | 2026-2036
Spina Bifida Market Size, Share, and Industry Trends Forecast 2026-2036
Spina Bifida Market Outlook
Silicone-based catheter materials are repositioning product economics across the spina bifida care continuum by reducing infection rates and extending indwelling intervals. Hollister Incorporated leverages integrated manufacturing to sustain cost advantages in intermittent catheter systems. B. Braun SE anchors European supply chains through specialized urology distribution networks. Cardinal Health competes on logistics scale, controlling hospital procurement channels across North American pediatric networks.
Spina bifida encompasses a spectrum of neural tube defects characterized by incomplete vertebral arch closure, typically presenting with myelomeningocele or lipomyelomeningocele pathology requiring cerebrospinal fluid diversion and functional urological management. Surgery dominates value generation within product type segmentation, reflecting the complexity of fetal repair procedures and postnatal shunt revisions. Rehabilitation equipment represents the fastest-expanding therapy support category as ambulation protocols advance. Neurosurgery commands the largest margin pool within therapy area segmentation due to specialized instrumentation and prolonged operative workflows.
The FDA regulates prenatal surgical interventions through its Humanitarian Device Exemption pathway, while the EMA's pediatric investigation plans shape European neurosurgical device development timelines. ISO 13485 quality management standards govern manufacturing consistency for implantable shunt systems across all major supply jurisdictions. Stakeholders must monitor evolving reimbursement frameworks for fetal repair procedures as cost-effectiveness evidence accumulates from longitudinal patient registries.
Market Dynamics
Pediatric surgical volumes are concentrating in high-volume fetal therapy centers, creating tiered referral networks that privilege institutions with established maternal-fetal medicine infrastructure and experienced neurosurgical teams capable of performing in-utero repair procedures.
Growth Catalysts
- Fetal Repair Protocol Expansion:The FDA's Humanitarian Device Exemption pathway for prenatal surgical interventions accelerates device approvals for specialized instrumentation used in myelomeningocele closure procedures.
- EMA Pediatric Investigation Plans:European neurosurgical device developers gain structured development timelines through mandated pediatric study frameworks, reducing regulatory uncertainty for shunt system innovations.
- Silicone Catheter Materials:Advanced polymer formulations reduce urinary tract infection rates and extend indwelling intervals, improving quality-of-life metrics for patients requiring lifelong urological management.
Market Restraints
- Specialized Surgical Workforce Scarcity:Fellowship-trained fetal surgeons and pediatric neurosurgeons concentrate in fewer than forty academic medical centers across the United States, limiting procedure accessibility.
- Implantable Shunt Supply Concentration:Manufacturing of programmable valve systems depends on precision machining capabilities clustered in southern Germany and northern Switzerland.
- Longitudinal Outcome Data Gaps:Twenty-year patient registry follow-up requirements for fetal repair procedures create reimbursement uncertainty for payors evaluating cost-effectiveness.
Strategic Opportunities
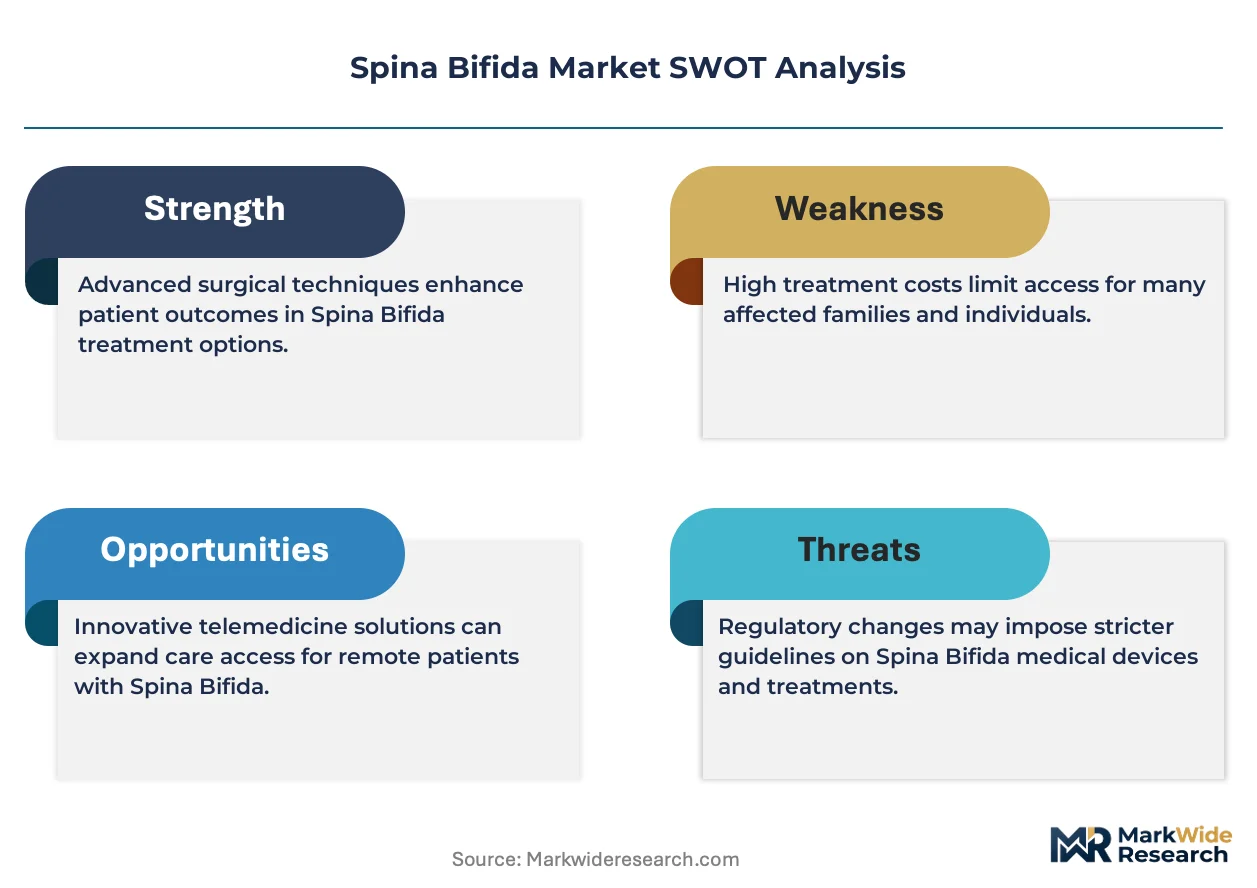
- Telemedicine-Enabled Rural Access:Remote prenatal consultation networks connect expectant mothers in underserved counties to fetal therapy centers, expanding screening and referral capture.
- Bioresorbable Shunt Materials:Convergence of tissue engineering and polymer chemistry enables temporary cerebrospinal fluid diversion without permanent foreign body implantation.
- Rehabilitation Robotics Integration:Powered exoskeleton systems for pediatric ambulation training represent underpenetrated equipment categories within specialized spina bifida clinics.
Industry Challenges
- Pediatric Device Trial Design Complexity:Small patient populations and ethical constraints on placebo-controlled studies complicate statistical powering for regulatory submissions to the FDA.
- Cross-Functional Care Coordination:Integration of neurosurgery, urology, orthopedics, and rehabilitation services requires health system investments in dedicated multidisciplinary clinic infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spina Bifida Market |
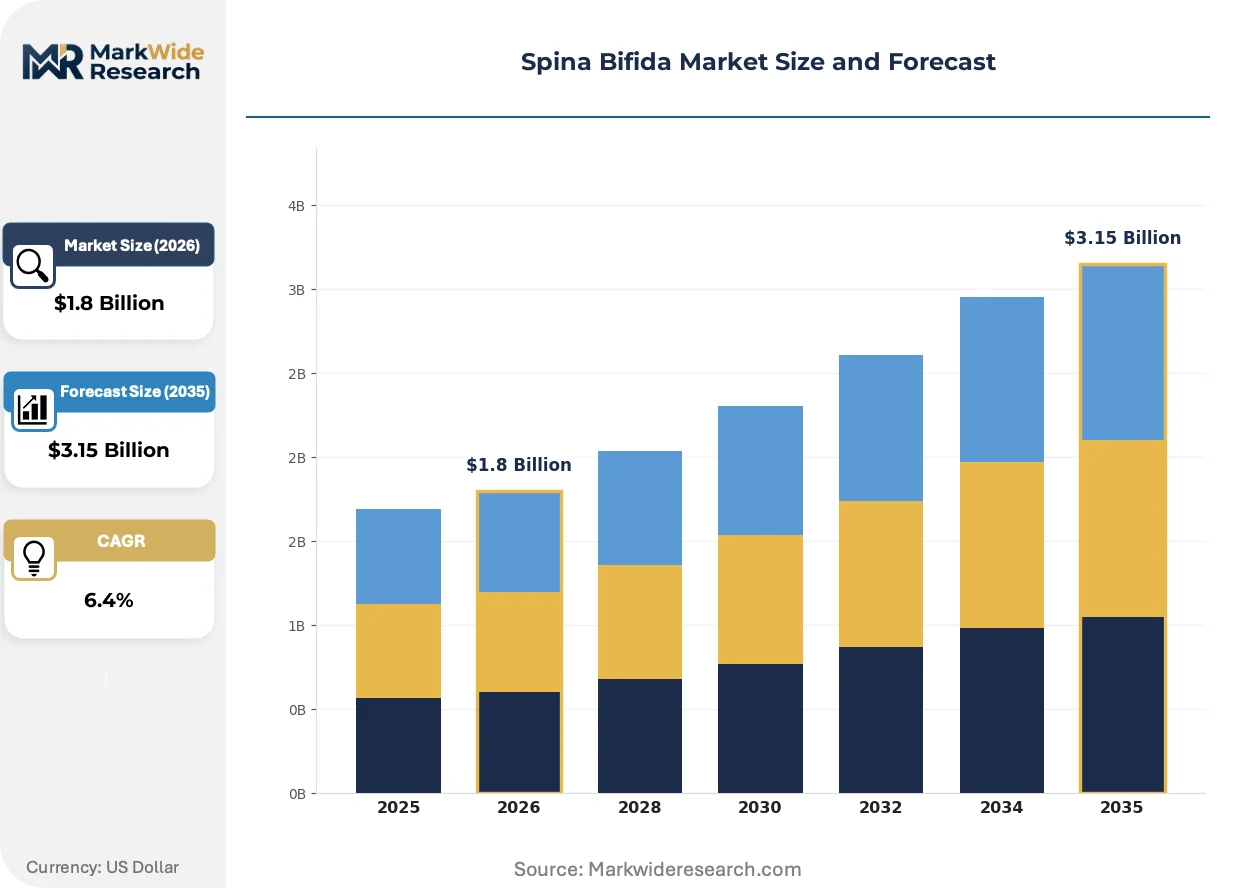
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Medication, Rehabilitation Equipment, Assistive Devices Therapy Area: Neurosurgery, Orthopedics, Urology, Physical Therapy End User: Pediatric Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Care Care Setting: Inpatient, Outpatient, Emergency, Long-term Care |
| Companies Covered | Cardinal Health, Hollister Incorporated, Pfizer Inc., ConvaTec Group plc, Cook Medical, Boston Scientific Corporation, BD, Wellspect Healthcare, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spina Bifida Market Strategic Shifts
Fetal intervention capabilities are advancing through improved imaging resolution and miniature surgical instrumentation, while postnatal care models shift toward patient-centered coordination platforms that consolidate historically fragmented specialty services.
Magnetic resonance imaging-guided thermal ablation is absorbing increasing capital allocation from fetal therapy programs seeking alternatives to open hysterotomy repair. Maternal-fetal medicine departments at tertiary centers are adopting these platforms to reduce preterm delivery risks associated with traditional fetal surgery. The technology is absorbing procedure volume from conventional open repair, compressing the addressable market for specialized hysterotomy instrumentation while expanding demand for MRI-compatible surgical devices.
The European Union's Medical Device Regulation imposes stricter clinical evidence requirements for implantable shunt systems, extending conformity assessment timelines for manufacturers seeking CE marking. Pediatric device companies are responding by front-loading clinical data collection through existing patient registries and collaborative research networks. German and Swiss manufacturers face the most significant compliance burden given their concentration in programmable valve production.
Consolidated purchasing arrangements through pediatric hospital networks are displacing traditional distributor relationships for intermittent catheter supplies. Large children's hospital systems in the United States are negotiating direct manufacturer contracts, bypassing regional medical-surgical distributors. This concentration is most visible in the southeastern states, where three major pediatric networks control procurement for spina bifida clinics across multiple institutions.
Spina Bifida Market Segmentation
Spina bifida care pathways fragment across distinct product, therapeutic, and delivery dimensions, each carrying divergent regulatory burdens and margin profiles. Understanding these segment boundaries clarifies where capital deployment encounters FDA Humanitarian Device Exemption requirements versus standard 510(k) pathways.
Product Type:
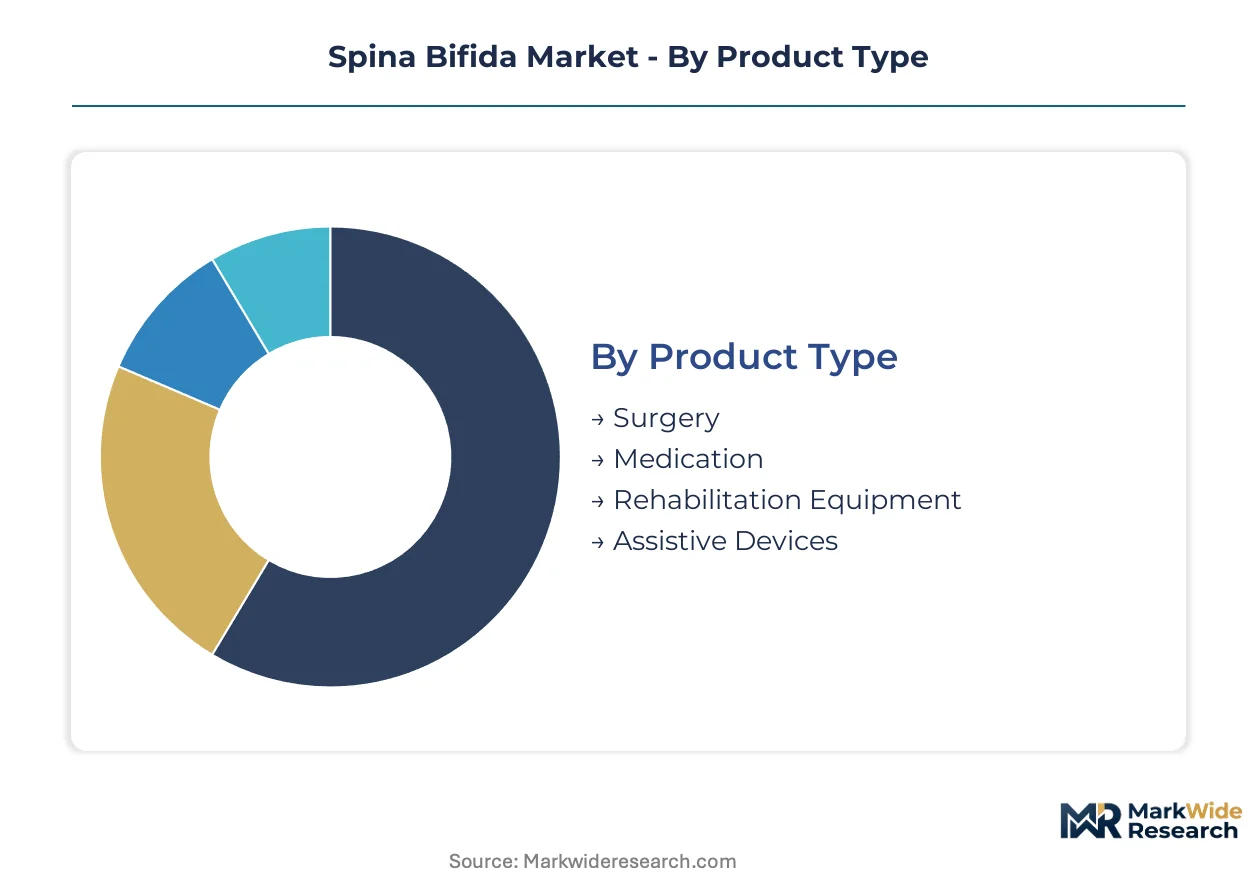
Surgery commands the most intensive premarket approval burden through FDA's Humanitarian Device Exemption, while rehabilitation equipment navigates simpler Class II pathways; medication falls under standard pharmaceutical review timelines.
- Surgery:Fetal repair procedures and postnatal shunt revisions utilize specialized hysterotomy instrumentation and programmable valve systems. Demand concentrates at maternal-fetal medicine centers in the United States with established in-utero repair capabilities, driven by expanding referral networks from rural prenatal screening programs.
- Rehabilitation Equipment:Powered exoskeleton systems and ambulation training platforms support functional independence protocols. Pediatric hospitals in Germany are absorbing the highest procurement volumes for these systems, constrained by reimbursement uncertainty for long-term therapeutic device leasing.
- Medication:Anticholinergic agents and antibiotic prophylaxis for urological management comprise standard pharmaceutical formulations. The segment relies on established generic supply chains with minimal device-specific regulatory overhead.
- Assistive Devices:Wheelchairs, orthotics, and adaptive mobility equipment address lifelong functional support needs. Procurement runs through durable medical equipment channels with Medicare and Medicaid prior authorization requirements.
Surgery sits at the top of the volume ranking, with Rehabilitation Equipment climbing the fastest.
Therapy Area:
Cost tiers separate these segments, with neurosurgical interventions commanding premium reimbursement rates against standardized physical therapy protocols.
- Neurosurgery:Cerebrospinal fluid diversion through ventriculoperitoneal shunts and fetal myelomeningocele repair procedures generate the highest per-procedure revenue. Academic medical centers in Switzerland and southern Germany anchor specialized instrumentation supply, with cross-border patient flows from France and Austria reinforcing volume concentration.
- Urology:Intermittent catheterization programs and antimuscarinic therapy management address neurogenic bladder dysfunction. Silicone-based catheter materials are reducing infection rates and extending replacement intervals across pediatric hospital networks.
- Orthopedics:Spinal fusion and lower extremity corrective procedures address progressive deformities. The segment depends on orthopedic surgery workforce availability at specialized children's hospitals.
- Physical Therapy:Standardized ambulation and functional training protocols represent the most cost-accessible intervention tier. Community-based delivery models are expanding access beyond tertiary center catchment areas.
Neurosurgery captures the highest absolute expenditure, with Urology gaining share fastest as lifelong management protocols extend device utilization horizons.
End User:
Customer type determines procurement sophistication, with integrated pediatric hospital networks leveraging scale against fragmented home care reimbursement.
- Pediatric Hospitals:Tertiary children's hospitals coordinate multidisciplinary spina bifida clinics spanning neurosurgery, urology, and orthopedics. Consolidated purchasing arrangements in the southeastern United States are displacing traditional distributor relationships for catheter supplies.
- Rehabilitation Centers:Specialized inpatient and day rehabilitation programs focus on ambulation training and adaptive equipment fitting. The segment depends on referral relationships with acute care discharge planners.
- Outpatient Clinics:Community-based follow-up and routine urological management extend care beyond hospital walls. Reimbursement compression is constraining specialist staffing ratios.
- Home Care:Family-administered intermittent catheterization and medication management shift cost burden to private insurance and Medicaid programs. Supply logistics complexity limits product standardization.
Pediatric Hospitals dominate procedure volume, with Home Care expanding most quickly as early discharge protocols accelerate.
Care Setting:
Application urgency separates these segments, with emergency interventions requiring immediate resource mobilization against scheduled long-term care planning.
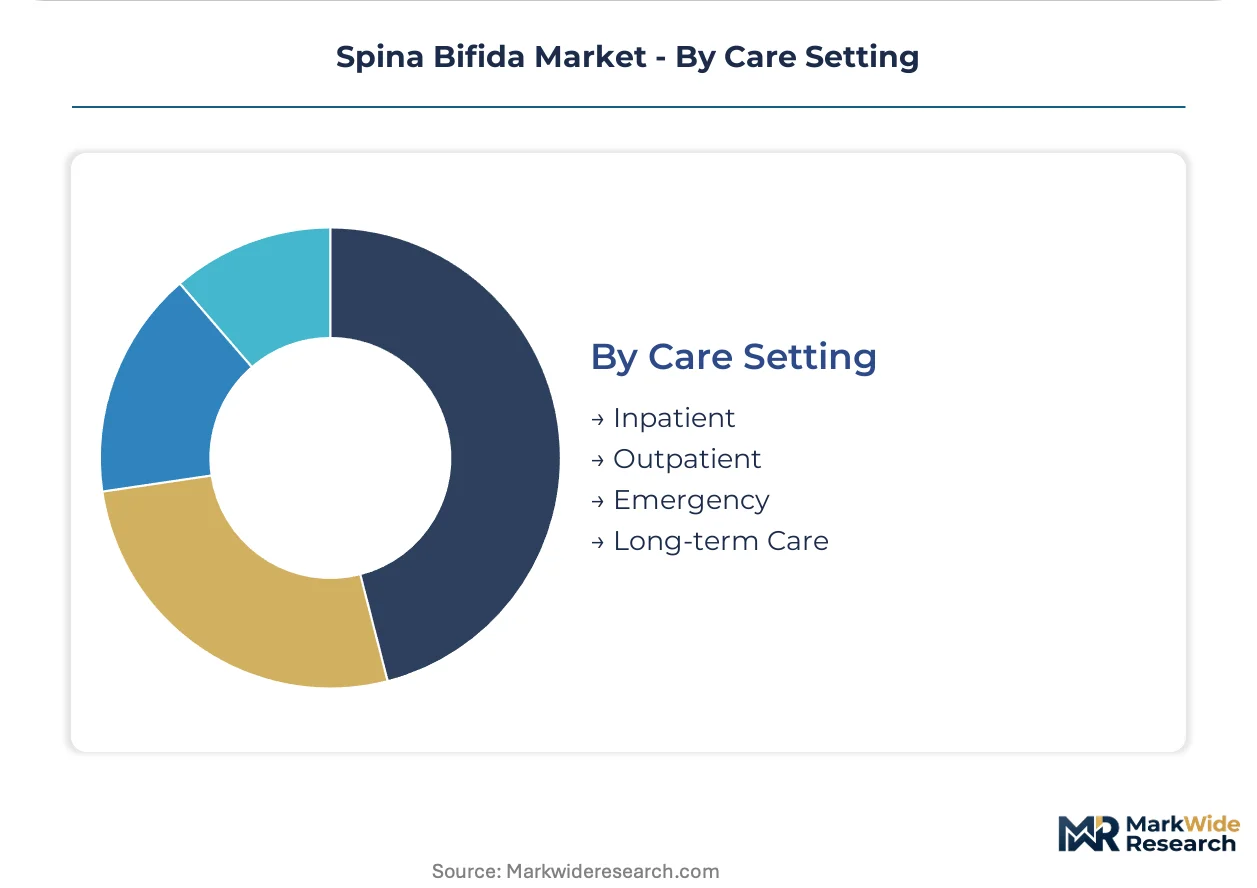
- Inpatient:Fetal repair, shunt placement, and postoperative monitoring require specialized pediatric neurosurgical beds and maternal-fetal intensive care capabilities. Capacity constraints at high-volume centers create waitlist dynamics for non-urgent procedures.
- Long-term Care:Residential facilities for adults with spina bifida address medical complexity and social support needs beyond family caregiving capacity. Medicaid waiver programs determine geographic accessibility.
- Outpatient:Scheduled clinic visits for urodynamic testing, orthopedic follow-up, and equipment adjustment represent the routine care backbone. Telemedicine integration is reducing travel burden for rural patients.
- Emergency:Shunt malfunction and symptomatic urinary tract infections require rapid neurosurgical and urological intervention. Emergency department pediatric readiness varies across hospital systems.
Inpatient commands the highest per-episode cost, with Long-term Care showing the steepest expansion trajectory as pediatric survival extends into adult service systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southern Germany-northern Switzerland precision machining corridor anchors global supply for programmable shunt valve systems. Pediatric hospital networks in the United States concentrate fetal repair volumes at fewer than forty academic medical centers. Cross-border patient flows from France and Austria reinforce neurosurgical demand clustering in German-speaking central Europe.
United States
Pediatric hospitals in the southeastern states are consolidating catheter procurement through direct manufacturer contracts, bypassing regional distributors. The FDA's Humanitarian Device Exemption pathway accelerates prenatal surgical intervention approvals. Maternal-fetal medicine centers in Philadelphia and Houston attract rural referral networks through telemedicine-enabled prenatal consultation platforms.
Germany
Specialized neurosurgical centers in Heidelberg and Munich attract cross-border patient referrals from neighboring European markets. The EMA's pediatric investigation plans shape structured development timelines for shunt system innovations. Precision machining capabilities concentrated in Baden-Württemberg and Bavaria supply programmable valve components to global device manufacturers.
Switzerland
Academic medical centers in Zurich and Geneva anchor specialized instrumentation supply for cerebrospinal fluid diversion procedures. Swissmedic maintains stringent oversight of implantable device manufacturing quality systems. The Basel-Zurich corridor hosts concentrated neurosurgical device engineering talent and cleanroom production infrastructure.
United Kingdom
Pediatric networks in London and Manchester are expanding dedicated spina bifida multidisciplinary clinic infrastructure. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device approval pathways with retained EU MDR standards. NHS England's specialized commissioning frameworks concentrate fetal repair procedures at designated tertiary fetal therapy units.
France
ANSM regulates implantable shunt systems through enhanced vigilance requirements for pediatric populations. Fetal surgery programs in Paris and Lyon coordinate with Belgian and Luxembourg referral networks for complex myelomeningocele cases. The Île-de-France region maintains the highest density of pediatric neurosurgical beds per capita in continental Europe.
Spina Bifida Market Competitive Environment
Global majors compete with regional champions across catheter supply and shunt system manufacturing, producing a tiered structure where integrated manufacturers hold cost advantages in high-volume consumables while precision engineering specialists dominate implantable valve segments. Three archetypes define competitive positioning: diversified health systems suppliers with logistics scale, specialized urology and continence device manufacturers with polymer formulation expertise, and precision neurosurgical instrument makers with cleanroom machining capabilities. Strategic moves concentrate on procurement channel consolidation through pediatric hospital network direct contracts and regulatory pathway optimization for pediatric device submissions.
Among diversified supply chain operators, Cardinal Health exemplifies logistics-scale competitive positioning through hospital procurement channel control. Hollister Incorporated and B. Braun SE represent specialized manufacturing archetypes, with the former leveraging integrated production for intermittent catheter cost structures and the latter anchoring European urology distribution networks. These three companies collectively illustrate how geographic manufacturing concentration and procurement channel strategy determine market access in pediatric specialty care.
| Leading Market Players |
|---|
| Cardinal Health |
| Hollister Incorporated |
| Pfizer Inc. |
| ConvaTec Group plc |
| Cook Medical |
| Boston Scientific Corporation |
| BD |
| Wellspect Healthcare |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Silicone catheter grade certification separates premium reimbursement tiers from commodity procurement channels, with FDA Humanitarian Device Exemption pathways commanding 3-5x per-unit premiums over standard Class II 510(k) equivalents while concentrating supply relationships around German precision machining clusters and southeastern United States pediatric network direct contracts.
Pricing Analysis
Input-cost pass-through from medical-grade silicone and precision-machined valve components shapes pricing stratification across programmable shunt systems. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification depth and indwelling interval performance guarantees. Pricing pressure stems from consolidated purchasing arrangements at large pediatric hospital networks seeking volume discounts on intermittent catheter supplies. Home care segments exhibit highest price sensitivity due to Medicaid reimbursement caps, while fetal therapy centers absorb premium tiers with limited substitution elasticity.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume catheter demand from consolidated pediatric networks, bypassing traditional distributor markups. Manufacturing concentrates in southern Germany, northern Switzerland, and select southeastern United States medical device corridors. Raw material dependencies include medical-grade silicone polymers, titanium valve housings, and MRI-compatible polymer formulations. Single-source vulnerability persists for programmable shunt valve machining capabilities clustered in Baden-Württemberg. Distribution runs through specialized urology supply networks and GPO-contracted hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spina bifida market functions as a regulatory compounder where FDA Humanitarian Device Exemption approvals for fetal repair instrumentation create protected pricing windows and accelerate competitive moat formation around prenatal surgical device portfolios.
For Market Incumbents: Anchor manufacturing scale in Baden-Württemberg precision machining corridors to defend programmable valve margins against emerging polymer-based diversion technologies. Deepen backward integration into medical-grade silicone supply to offset raw material cost volatility. Fortify hospital system partnerships through dedicated spina bifida clinic infrastructure investments that lock in catheter procurement volumes. For New Entrants and Emerging Players: Enter via rehabilitation robotics for pediatric ambulation training, the most underpenetrated equipment category within specialized spina bifida clinics. Target home care supply logistics where product standardization gaps create service-based differentiation opportunities. Pursue telemedicine-enabled rural prenatal consultation platforms as the lowest-capital entry vector into fetal therapy referral capture. For Investors and Strategic Acquirers: Consolidation pressure builds where pediatric device trial design complexity and small patient populations create insurmountable regulatory barriers for standalone developers. Five-to-ten year viability favors precision neurosurgical instrument makers with cleanroom machining capabilities and established FDA pediatric submission track records. Monitor EMA pediatric investigation plan completion rates as the critical inflection signal for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Humanitarian Device Exemption Submission | Accelerates prenatal surgical intervention approvals for specialized hysterotomy instrumentation. |
| Pediatric Hospital Network Direct Contract | Consolidates catheter procurement volumes and displaces regional distributor relationships. |
| CE Marking Pathway Under EU MDR | Extends conformity assessment timelines for implantable shunt systems seeking European access. |
| Bioresorbable Shunt Material R&D Partnership | Converges tissue engineering and polymer chemistry for temporary cerebrospinal fluid diversion. |
| Telemedicine-Enabled Rural Access Platform | Connects underserved counties to fetal therapy centers and expands screening capture. |
Study Parameters
Direct dialogue with pediatric neurosurgeons, maternal-fetal medicine specialists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from FDA Humanitarian Device Exemption filings, EMA pediatric investigation plans, hospital procurement databases, CMS Medicare reimbursement schedules, and ISO 13485 certification registries. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Bottom-up modeling anchored forecasts in procedure volume trajectories at high-volume fetal therapy centers, while top-down validation cross-checked against national healthcare expenditure patterns across the projection horizon. Segmentation dimensions included product type, therapy area, end user archetype, and care setting urgency. CAGRs derived from longitudinal patient registry growth rates and surgical volume concentration trends at academic medical centers. Shunt revision frequency curves and catheter replacement interval extensions informed device utilization intensity assumptions.
The model holds under stable FDA pediatric device review timelines and sustained EMA investigation plan adherence; deviation in regulatory backlog accumulation or reimbursement framework shifts would revise volume assumptions. Forecasts reflect documented base conditions around maternal-fetal medicine center capacity expansion and silicone material cost trajectories. Periodic stress-testing of base assumptions is recommended against emerging bioresorbable diversion technologies and telemedicine reimbursement policy evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Asia-Pacific Down Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Aicardi Syndrome Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
North America Down Syndrome Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Rosai-Dorfman Disease (RDD) Therapeutics Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Europe Down Syndrome Market