
 Operating Room Smoke Aspirators Market | 2026-2036
Operating Room Smoke Aspirators Market Size, Share, and Industry Trends Forecast 2026-2036
Operating Room Smoke Aspirators Market Insights
Hospital procurement consortiums is reshaping how operating room smoke aspirators reach end users, with group purchasing organizations now dictating filtration performance tiers and service bundling. Medtronic leverages its surgical technologies division to bundle aspirators with electrosurgical platforms, creating integrated account relationships. CONMED Corporation anchors its position through specialized smoke evacuation accessories that lock into its broader visualization ecosystem. Stryker Corporation competes on capital equipment placement, using operating room integration contracts to secure long-term aspirator attach rates.
Operating room smoke aspirators are electromechanical devices that capture and filter surgical plume—combining vacuum generation, multi-stage filtration (HEPA and activated carbon), and activated charcoal absorption to remove particulates, volatile organic compounds, and biological aerosols generated during cauterization and laser procedures. Portable aspirators dominate current installed base economics due to lower capital barriers and retrofit flexibility in older surgical suites, while high-efficiency aspirators with ultra-low particulate filtration represent the fastest-growing product tier as hospitals face stricter occupational exposure enforcement. Wall-mounted aspirators occupy a mature niche in new construction, where HVAC integration and fixed infrastructure planning favor centralized evacuation architecture.
FDA 510(k) clearance pathways shape product entry timelines for smoke aspirator manufacturers, while OSHA's permissible exposure limits for airborne contaminants directly drive hospital capital allocation toward compliant evacuation systems. AORN recommended practices on surgical smoke safety create institutional purchasing pressure that converts regulatory awareness into equipment budgets. Stakeholders must monitor evolving state-level surgical smoke legislation—already active in Colorado, Illinois, and Kentucky—as these mandates cascade from policy announcement to procurement execution with limited vendor preparation windows.
Market Dynamics
State-level surgical smoke legislation in the United States is compressing replacement cycles for legacy evacuation equipment, forcing hospitals to accelerate capital allocation toward compliant filtration systems before enforcement windows close.
Growth Catalysts
- OSHA Permissible Exposure Limits:Workplace safety mandates for airborne contaminants are converting regulatory awareness into hospital equipment budgets.
- Ambulatory surgical center construction:United States outpatient facility expansion is generating procurement demand for portable smoke aspirators with retrofit flexibility.
- Electrosurgical platform integration:Bundled equipment contracts are locking in aspirator attach rates through surgical technology suites.
Market Restraints
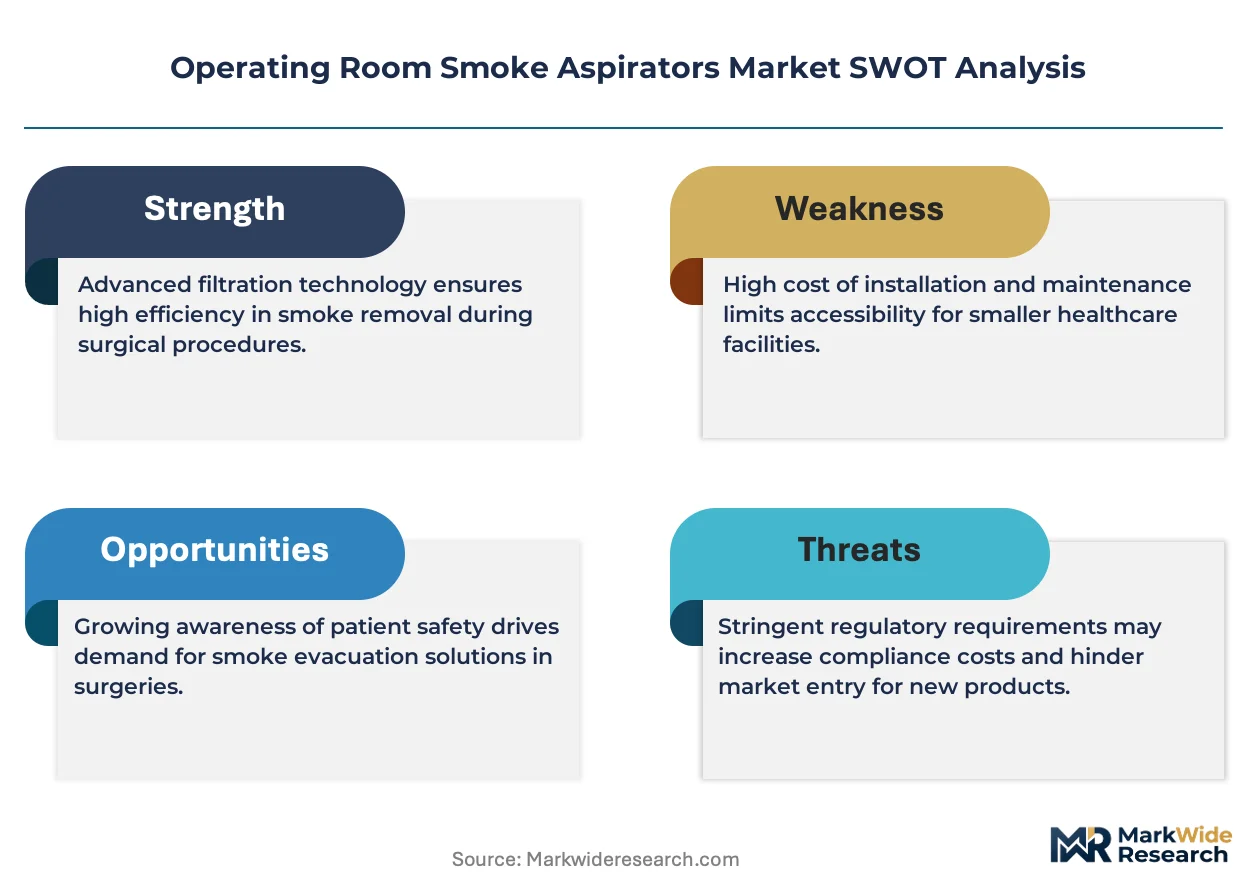
- HEPA filtration input concentration:Specialized filter media supply concentrates among a limited supplier base, creating cost volatility.
- Capital intensity of wall-mounted systems:HVAC integration requirements and fixed infrastructure planning extend payback periods for centralized evacuation architecture.
- Legacy equipment substitution:Existing portable aspirator installed bases create inertia against premium filtration upgrades.
Strategic Opportunities
- State mandate cascade:Colorado, Illinois, and Kentucky legislative frameworks are creating procurement execution windows with limited vendor preparation time.
- Ultra-low particulate filtration convergence:Activated carbon absorption combined with advanced HEPA stages is opening premium product tiers.
- Group purchasing organization channel expansion:Hospital procurement consortiums are dictating performance tiers and service bundling for new market entrants.
Industry Challenges
- FDA 510(k) clearance timelines:Regulatory submission pathways are compressing product entry windows for filtration system manufacturers.
- Legacy surgical suite integration:Older operating room infrastructure requires retrofit compatibility engineering for smoke evacuation hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Operating Room Smoke Aspirators Market |
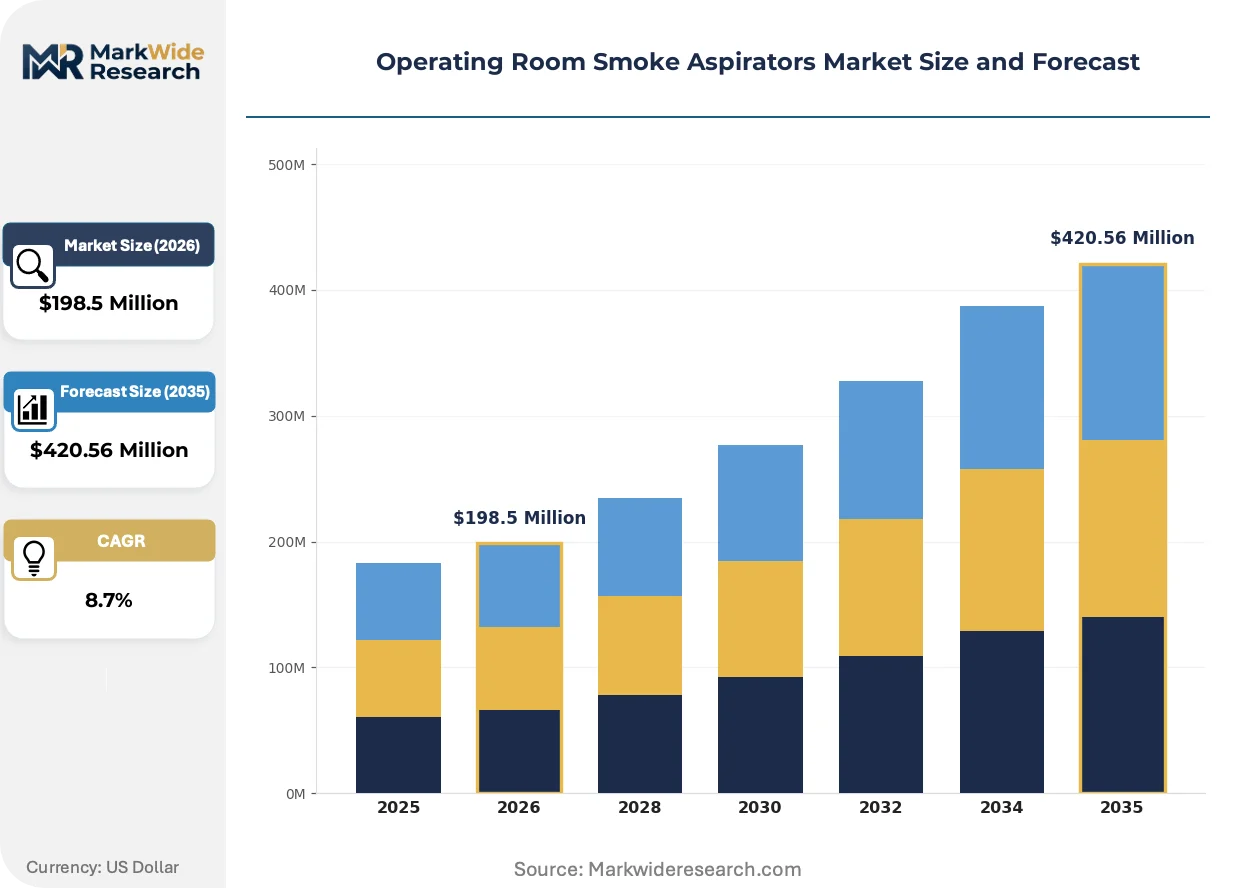
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Aspirators, Wall-Mounted Aspirators, High-Efficiency Aspirators, Integrated Surgical Units End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Educational Institutions Technology: Filtration Technology, Electrostatic Precipitators, HVAC Systems, Carburetor Technologies Application: General Surgery, Gynecological Surgery, Cosmetic Surgery, Laser Surgery |
| Companies Covered | Medtronic, CONMED Corporation, Stryker Corporation, Ecolab, Johnson & Johnson, Olympus Corporation, Zimmer Biomet Holdings, Utah Medical Products, CooperSurgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Operating Room Smoke Aspirators Market Trends and Innovations
Surgical smoke management is pivoting from passive compliance to active occupational health infrastructure, with filtration performance becoming a measurable procurement criterion rather than an afterthought.
Multi-stage filtration architectures combining HEPA and activated carbon stages are collapsing the performance gap between portable and fixed-installation systems. Community hospitals and ambulatory centers are adopting these configurations to meet AORN guidelines without wall-mounted infrastructure investments. Equipment differentiation is compressing toward particulate capture efficiency ratings as the primary purchasing determinant.
OSHA workplace exposure enforcement is hardening capital allocation criteria for hospital safety officers. Updated permissible exposure limits are triggering equipment replacement audits in surgical departments. United States facilities are responding by specifying ultra-low particulate air filtration in procurement contracts ahead of state mandate effective dates.
Service bundling is displacing standalone equipment sales in hospital procurement patterns. Group purchasing organizations are consolidating aspirator selection into broader surgical platform contracts. This concentration is most visible in United States health systems where integrated delivery networks command volume leverage over filtration performance specifications.
Operating Room Smoke Aspirators Market Segmentation
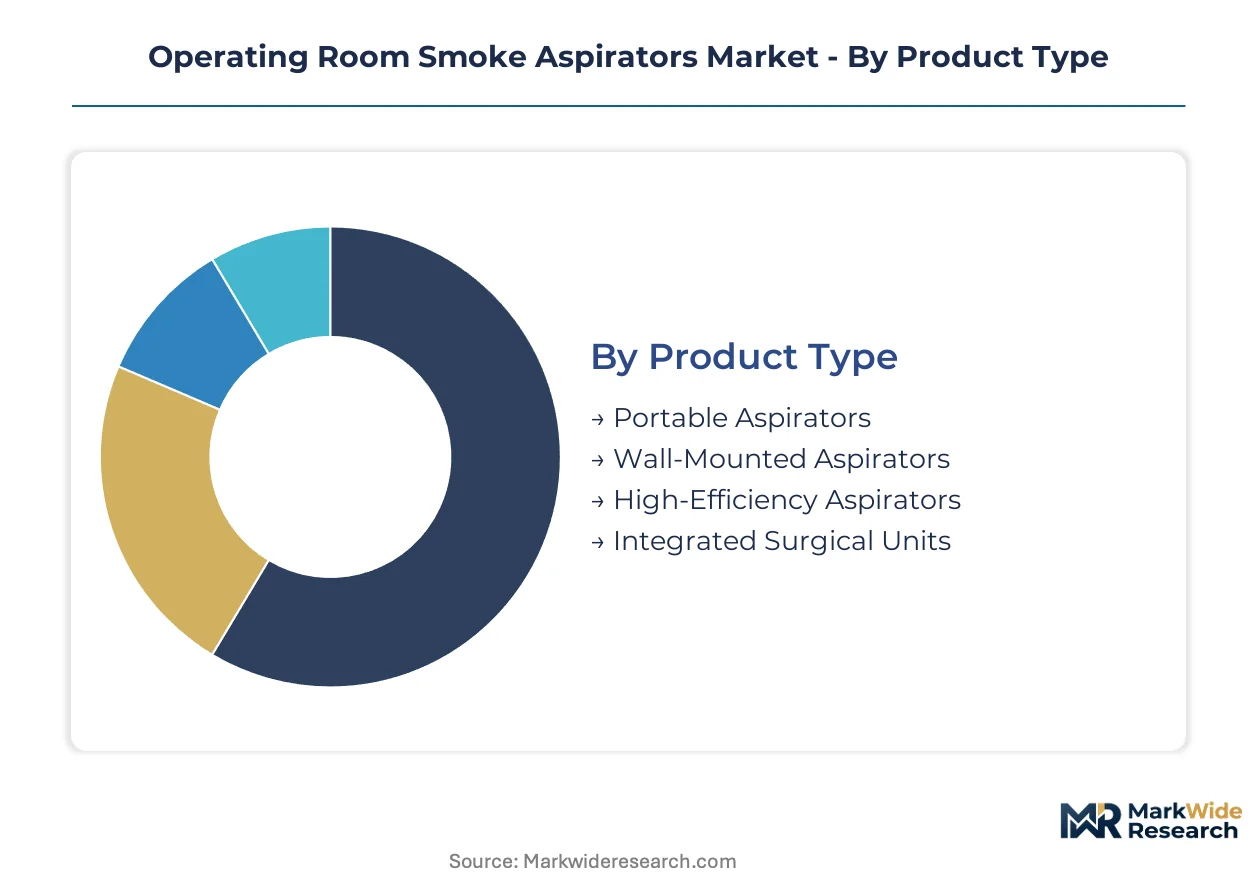
Operating room smoke aspirators segment across four functional dimensions that determine procurement workflows and capital allocation patterns. Product architecture dictates infrastructure requirements, while end-user settings shape performance specifications and service bundling needs.
Product Type:
Mature configurations dominate current installed bases, while emerging high-efficiency platforms capture replacement demand driven by regulatory enforcement.
- Portable Aspirators:Self-contained vacuum and filtration units designed for retrofit deployment in legacy surgical suites. United States ambulatory surgical centers specify these for electrosurgical platform compatibility without HVAC infrastructure investment.
- High-Efficiency Aspirators:Ultra-low particulate air systems combining advanced HEPA stages with activated carbon absorption. Colorado hospitals facing state mandate deadlines are accelerating procurement of these units ahead of enforcement windows.
- Wall-Mounted Aspirators:Fixed-installation systems integrated into operating room HVAC architecture. New construction projects in Illinois specify these for centralized evacuation planning.
- Integrated Surgical Units:Electrosurgical platform bundles incorporating smoke evacuation as standard configuration. Group purchasing organizations favor these for service consolidation across health system networks.
Portable aspirators handle the majority of throughput; high-efficiency aspirators are climbing the fastest on share.
End User:
Customer scale determines procurement channel access, with large health systems leveraging volume leverage unavailable to smaller facilities.
- Hospitals:Acute care facilities with dedicated surgical departments and capital equipment replacement cycles. OSHA workplace exposure audits in Kentucky are triggering equipment budget releases in these settings.
- Ambulatory Surgical Centers:Outpatient facilities requiring compact, mobile evacuation systems for multi-procedure suites. Construction expansion across the United States is generating concentrated demand for portable configurations.
- Specialty Clinics:Dermatology and ophthalmology practices performing laser procedures with lower case volumes. These facilities prioritize retrofit flexibility over integrated infrastructure.
- Educational Institutions:Medical training programs and simulation centers requiring aspirators for competency development. Procurement concentrates through academic medical center supply chains.
Hospitals command the largest equipment budgets; ambulatory surgical centers are expanding most quickly as a customer class.
Technology:
Filtration performance tiers separate premium positioning from standard offerings, with regulatory compliance thresholds driving technology selection.
- Filtration Technology:Multi-stage HEPA and activated carbon architectures capturing particulates, volatile organic compounds, and biological aerosols. AORN recommended practices are elevating these systems to baseline procurement requirements.
- Electrostatic Precipitators:Charged particle separation systems for high-volume plume generation during cauterization procedures. Kentucky state mandates are accelerating evaluation of these technologies for compliance verification.
- HVAC Systems:Centralized building ventilation with dedicated surgical smoke extraction zones. New hospital construction in Illinois integrates these for fixed infrastructure planning.
- Carburetor Technologies:Fuel-air mixture optimization systems adapted for precise vacuum control in specialized surgical applications. Niche deployment in cosmetic surgery suites with specific plume characteristics.
Filtration technology anchors the installed base; electrostatic precipitators are gaining share fastest on regulatory compliance verification.
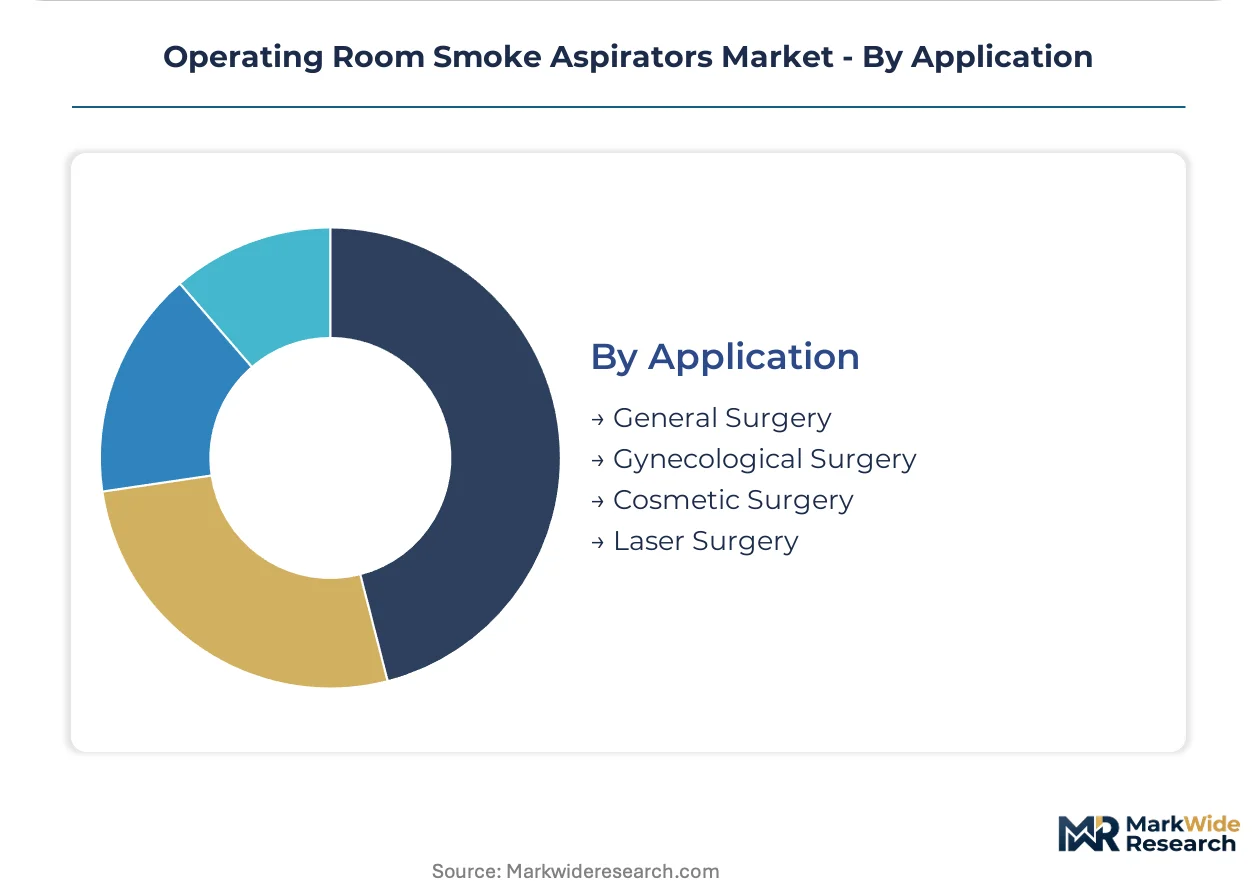
Application:
Procedure-specific plume characteristics determine filtration specification requirements and equipment replacement timing.
- General Surgery:Broad procedural category encompassing laparoscopic and open procedures with variable plume generation. United States hospitals specify portable aspirators for suite flexibility across procedure types.
- Laser Surgery:High-tissue-impact procedures generating dense particulate plumes requiring ultra-low particulate filtration. Colorado enforcement timelines are compressing replacement cycles for legacy equipment in these applications.
- Gynecological Surgery:Minimally invasive procedures with concentrated cauterization use in confined anatomical spaces. Ambulatory centers favor compact evacuation systems for these settings.
- Cosmetic Surgery:Elective procedures in private practice settings with patient-visible equipment aesthetics driving design preferences. Specialty clinics prioritize low-noise portable configurations.
General surgery generates the largest equipment volume; laser surgery is expanding fastest on regulatory exposure limit enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device distribution corridors channel European smoke aspirator procurement, while the Trans-Pacific shipping lanes connecting Shanghai to Long Beach anchor Asia-Pacific supply flows into North American hospital systems.
United States
State-level surgical smoke mandates in Colorado, Illinois, and Kentucky are compressing replacement cycles for legacy evacuation equipment. OSHA workplace exposure limits for airborne contaminants are converting regulatory awareness into hospital capital allocations. The Chicago metropolitan corridor concentrates procurement volume as health systems accelerate compliance ahead of enforcement windows.
Germany
CE marking requirements under the EU Medical Device Regulation are elevating filtration performance standards for aspirator manufacturers serving Central European hospitals. The country's national workplace safety regulator enforces occupational exposure thresholds that mirror OSHA frameworks. The Rhine-Ruhr industrial cluster houses distribution hubs supplying smoke evacuation systems to Benelux and Nordic markets.
Japan
Ministry of Health, Labour and Welfare guidelines on surgical staff protection are institutionalizing smoke evacuation protocols in metropolitan hospital networks. PMDA device registration pathways shape product entry timelines for filtration system manufacturers. The Kanto region surrounding Tokyo generates concentrated demand as academic medical centers upgrade laparoscopic suites.
United Kingdom
NHS procurement frameworks are consolidating aspirator selection into centralized equipment contracts with specified HEPA filtration tiers. The Health and Safety Executive monitors surgical plume exposure in private and public operating theaters. The Greater Manchester health system exemplifies regional consolidation patterns affecting vendor access.
Canada
Health Canada device licensing requirements align with FDA 510(k) pathways, facilitating cross-border supplier participation. Provincial occupational health regulations in Ontario and British Columbia are adopting surgical smoke management standards comparable to US state mandates. The Toronto-Waterloo medical technology corridor channels North American distribution for filtration equipment manufacturers.
Operating Room Smoke Aspirators Market Competitive Landscape
On the supply side, the industry is consolidating around surgical technology platforms rather than standalone filtration equipment. Tiered competitive positioning separates integrated platform vendors from specialized smoke evacuation manufacturers. Three archetypes dominate: diversified surgical technology conglomerates bundling aspirators with electrosurgical systems; dedicated filtration specialists competing on particulate capture efficiency ratings; and regional equipment fabricators serving retrofit demand in legacy surgical suites. Dominant competitive moves include strategic bundling of evacuation hardware with visualization platforms and geographic expansion through group purchasing organization channel partnerships.
Within the integrated platform tier, Medtronic and Stryker Corporation exemplify archetypes leveraging surgical technology divisions to lock in aspirator attach rates through comprehensive account relationships. CONMED Corporation occupies a specialist position, anchoring competitive presence through smoke evacuation accessories that integrate with broader visualization ecosystems.
| Leading Market Players |
|---|
| Medtronic |
| CONMED Corporation |
| Stryker Corporation |
| Ecolab |
| Johnson & Johnson |
| Olympus Corporation |
| Zimmer Biomet Holdings |
| Utah Medical Products |
| CooperSurgical |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in HEPA filtration media manufacturing across Germany and Japan is compressing supplier margins while amplifying pricing power for integrated surgical technology conglomerates with captive filter production. This utilization squeeze forces standalone aspirator manufacturers to absorb input cost volatility or surrender share to bundled platform vendors with deeper backward integration into filtration components.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement consortiums from ambulatory surgical centers in negotiated aspirator contracts. Three-tier pricing stratifies across premium high-efficiency units with ultra-low particulate certification, standard portable configurations, and economy retrofit systems for legacy suites. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling through group purchasing organization channels. Cost compression in the economy tier is intensifying because specialty clinics prioritize retrofit flexibility over integrated infrastructure. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with GPO leverage show lowest.
Supply Chain Analysis
Upstream feedstock concentration in activated carbon media centers on China, Germany, and the United States, with HEPA membrane fabrication anchored in Japan and South Korea. Raw material dependencies span borosilicate glass microfibers, activated charcoal substrates, and precision vacuum pump components. Single-source vulnerability in medical-grade filter media creates exposure to export licensing restrictions from the Japanese Ministry of Economy, Trade and Industry. Distribution runs through hospital procurement consortiums and surgical equipment distributors serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as state-level surgical smoke mandates splinter procurement timelines across Colorado, Illinois, and Kentucky, creating vendor preparation windows that favor nimble specialists over integrated conglomerates.
For Market Incumbents: Insulate attach rates through electrosurgical platform bundling that locks hospital systems into comprehensive service contracts spanning visualization, evacuation, and maintenance. Deepen backward integration into HEPA filtration media production to neutralize input cost volatility from German and Japanese suppliers. Prioritize FDA 510(k) clearance pipeline acceleration as emerging portable specialists threaten premium filtration tiers with faster regulatory submission cycles.
For New Entrants and Emerging Players: Build out retrofit-compatible portable aspirator configurations targeting ambulatory surgical center construction across the United States, where infrastructure flexibility requirements exceed integrated platform capabilities. Target Colorado's compressed compliance timeline as the most penetrable geography, where state mandate enforcement creates urgent procurement demand ahead of legacy vendor response capacity. Pursue group purchasing organization channel partnerships as the primary go-to-market angle, bypassing direct hospital sales cycles through consortium-approved vendor lists.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable aspirator manufacturing as modular designs reduce fixed tooling requirements compared to wall-mounted HVAC-integrated systems. Long-term viability favors acquisition targets with established GPO relationships and FDA clearance portfolios rather than pure technology plays. Watch electrostatic precipitator technology maturation as the signal indicating inflection toward next-generation compliance verification standards.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines in Colorado and Illinois enforcement windows favor first-mover regulatory positioning. |
| Group Purchasing Organization Partnership | Hospital procurement consortiums in the United States now dictate filtration performance tiers for vendor access. |
| Backward Integration into Filter Media | Captive HEPA and activated carbon production neutralizes supply concentration risk from German and Japanese suppliers. |
| CE Marking Pathway Expansion | EU Medical Device Regulation elevates filtration standards for Central European hospital procurement eligibility. |
| Software Companion Development | Digital compliance tracking interfaces with hospital safety officer workflows for OSHA exposure limit documentation. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and operating room safety officers and secondary sources anchors the qualitative findings. FDA 510(k) clearance databases, hospital procurement records, OSHA enforcement documentation, and AORN guideline publications provide triangulation points. Bottom-up demand modeling across ambulatory surgical center construction permits and top-down surgical procedure volume estimates converge on segment-level forecasts.
Calibration against historical replacement cycle patterns in Colorado, Illinois, and Kentucky legislative frameworks shapes the projection framework across the analysis window. Segmentation dimensions span product architecture, end-user facility type, filtration technology tier, and application-specific plume characteristics. CAGRs derive from equipment attach rate modeling against electrosurgical platform deployment and regulatory compliance deadline clustering. Procedure volume growth in laser surgery and laparoscopic suites informs demand elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified surgical technology conglomerates would shift outcomes beyond modeled ranges. Regulatory acceleration in additional United States states or EMA filtration standard tightening represents primary revision risks. Cross-checking against hospital capital equipment budget disclosures and GPO contract award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Global Electromagnetic Surgical Navigation System Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Hydrosurgery Systems Market