
 Abetalipoproteinemia Management Market | 2026-2036
Abetalipoproteinemia Management Market Size, Share, and Industry Trends Forecast 2026-2036
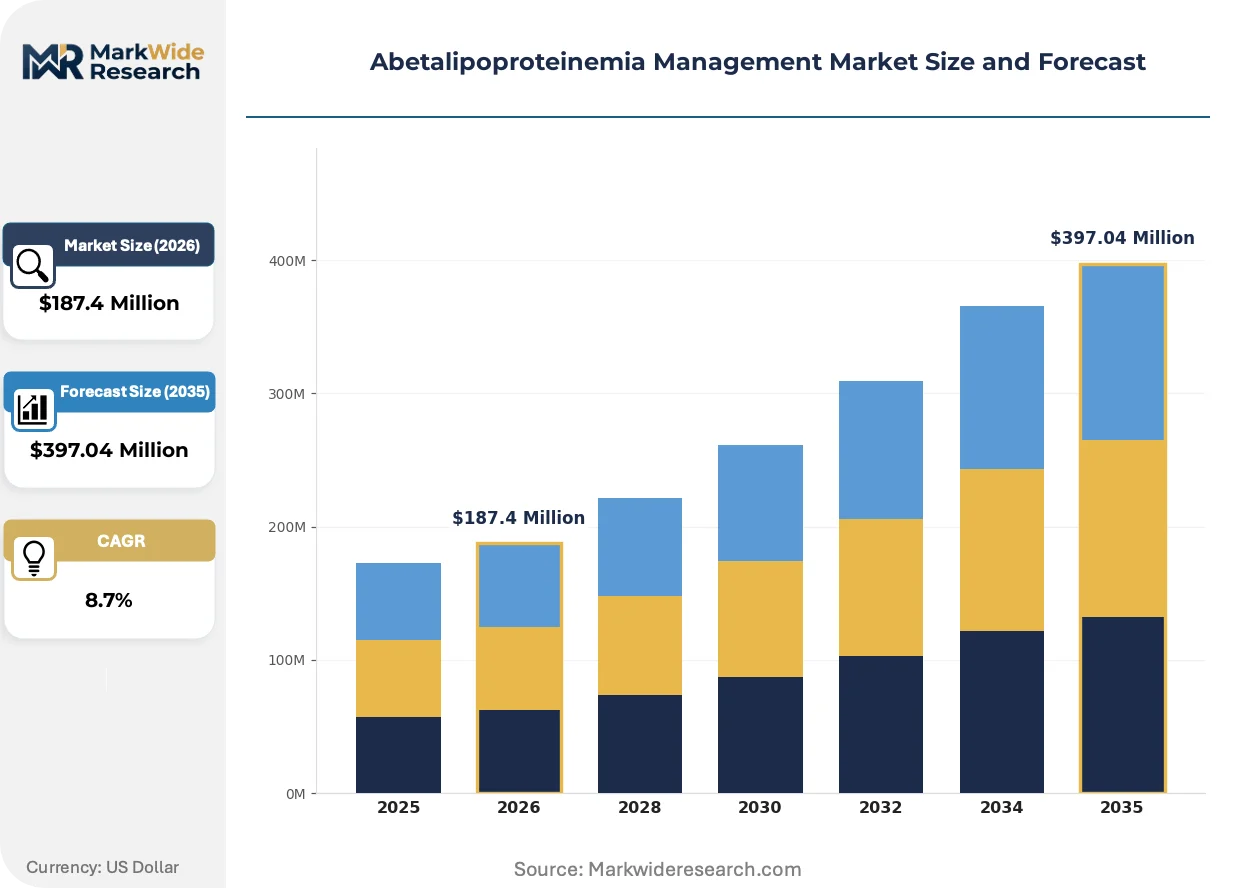
Abetalipoproteinemia Management Market Outlook
North America is narrowing its capacity gap for rare disease therapeutic manufacturing through expanded contract development facilities. Recordati Rare Diseases leverages its established rare disease commercial infrastructure across European and North American markets. Ultragenyx Pharmaceutical Inc. anchors its position through deep specialization in metabolic and genetic disorder portfolios. Lonza Group sustains manufacturing scale advantages across biologics and cell therapy production networks.
Abetalipoproteinemia management encompasses therapeutic interventions, nutritional protocols, and monitoring regimens targeting the rare autosomal recessive disorder characterized by defective microsomal triglyceride transfer protein and absent plasma apolipoprotein B-containing lipoproteins. The primary purpose centers on preventing progressive neurological degeneration, retinitis pigmentosa, and malabsorption complications through lipid-soluble vitamin replacement and essential fatty acid supplementation. Nutritional Supplements occupy the largest therapeutic position due to lifelong dependency on vitamins A, D, E, and K administration. Prescription Medications represent the fastest-expanding category as novel MTP inhibitors and gene therapy candidates advance through clinical pipelines. Hospitals capture dominant patient volumes for initial diagnosis and acute stabilization, while Home Care segments gain traction as stable patients transition to self-administered regimens.
FDA orphan drug designation and EMA rare disease incentives shape development economics by granting market exclusivity and protocol assistance for abetalipoproteinemia therapeutics. ISO 13485 quality management standards and national pharmaceutical regulators in key markets enforce manufacturing rigor for biologic and nutritional products. Stakeholders must monitor gene therapy trial readouts and regulatory precedent for ultra-rare indications to anticipate reimbursement and access dynamics.
Market Dynamics
FDA orphan drug designation and EMA rare disease frameworks are compressing clinical trial timelines for ultra-rare metabolic disorders, pulling gene therapy candidates into accelerated review pathways that reshape competitive positioning across nutritional and biologic therapeutic segments.
Growth Catalysts
- Orphan Drug Incentives:FDA protocol assistance and tax credits reduce development risk for MTP inhibitor programs. Biotech sponsors file breakthrough therapy requests earlier in phase transitions.
- Metabolic Clinic Expansion:Academic medical centers in the United States anchor specialized lipid disorder units. Hospital networks recruit genetic counselors and dietitians into integrated care teams.
- Gene Therapy Platforms:AAV vector manufacturing scale-up at contract development organizations shortens plasmid-to-patient timelines. Viral payload engineering advances target hepatocyte specificity.
Market Restraints
- Patient Pool Concentration:Prevalence below one per million creates enrollment bottlenecks for pivotal trials. Trial sites in the United States and Western Europe absorb disproportionate screening burden.
- Vitamin Raw Material Volatility:Fat-soluble vitamin supply chains face API sourcing constraints from Chinese and Indian manufacturers. Vitamin E acetate and K1 phylloquinone spot prices fluctuate with agricultural feedstock yields.
- Reimbursement Uncertainty:Payers apply step-therapy protocols to nutritional supplements before approving biologic alternatives. Gene therapy pricing faces scrutiny under IRA Medicare negotiation provisions.
Strategic Opportunities
- Home Infusion Services:Specialty pharmacies build lipid-soluble vitamin compounding and delivery networks. Patients transition from hospital-based parenteral administration to home nursing support.
- Real-World Evidence Pathways:FDA's rare disease endpoint advancement guidance enables natural history study substitution for control arms. Sponsors leverage patient registry data from European reference networks.
- Companion Diagnostic Integration:MTP gene sequencing panels enter clinical workflows at tertiary care centers. Genetic testing firms partner with therapeutic developers on co-development strategies.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production requires GMP-trained cell culture specialists. Contract manufacturers compete for limited pools of AAV process engineers.
- Multisite Trial Coordination:Ultra-rare disease studies span pediatric and adult populations across continents. Principal investigators navigate divergent national ethics review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abetalipoproteinemia Management Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 Fatty Acids, Nutritional Supplements, Enzyme Supplements, Prescription Medications Therapy Area: Metabolic Disorders, Dyslipidemia, Genetic Abnormalities, Preventive Care End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injectable, IV Infusion, Sublingual |
| Companies Covered | Recordati Rare Diseases, Lonza Group, Ultragenyx Pharmaceutical Inc., Aeglea BioTherapeutics, Piramal Pharma Solutions, Abbott Laboratories, Nestlé Health Science, Thermo Fisher Scientific, Orphalan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abetalipoproteinemia Management Market Strategic Shifts
Gene therapy manufacturing is hybridizing with nutritional management protocols, creating convergent care models that compress the boundary between biologic intervention and lifelong metabolic support. Regulatory science and patient advocacy are accelerating in parallel.
AAV-mediated MTP gene transfer is hybridizing preclinical and clinical development timelines. Sponsors at academic medical centers in the United States and Switzerland are advancing IND-enabling studies for liver-directed vectors. This convergence is compressing traditional phase boundaries and forcing contract manufacturers to reserve viral production slots before proof-of-concept readouts.
EMA's rare disease framework and FDA's rare disease endpoint advancement guidance are synchronizing transatlantic approval pathways. Developers file parallel scientific advice requests to align pivotal trial designs. Pediatric investigational plans now incorporate extrapolation strategies that reduce juvenile study burden.
Patient advocacy organizations are consolidating procurement influence through managed access programs. Foundation-led registries in the United States and Germany negotiate pre-approval access protocols directly with sponsors. This channel disintermediation is shifting commercialization planning earlier into development timelines.
Abetalipoproteinemia Management Market Segmentation
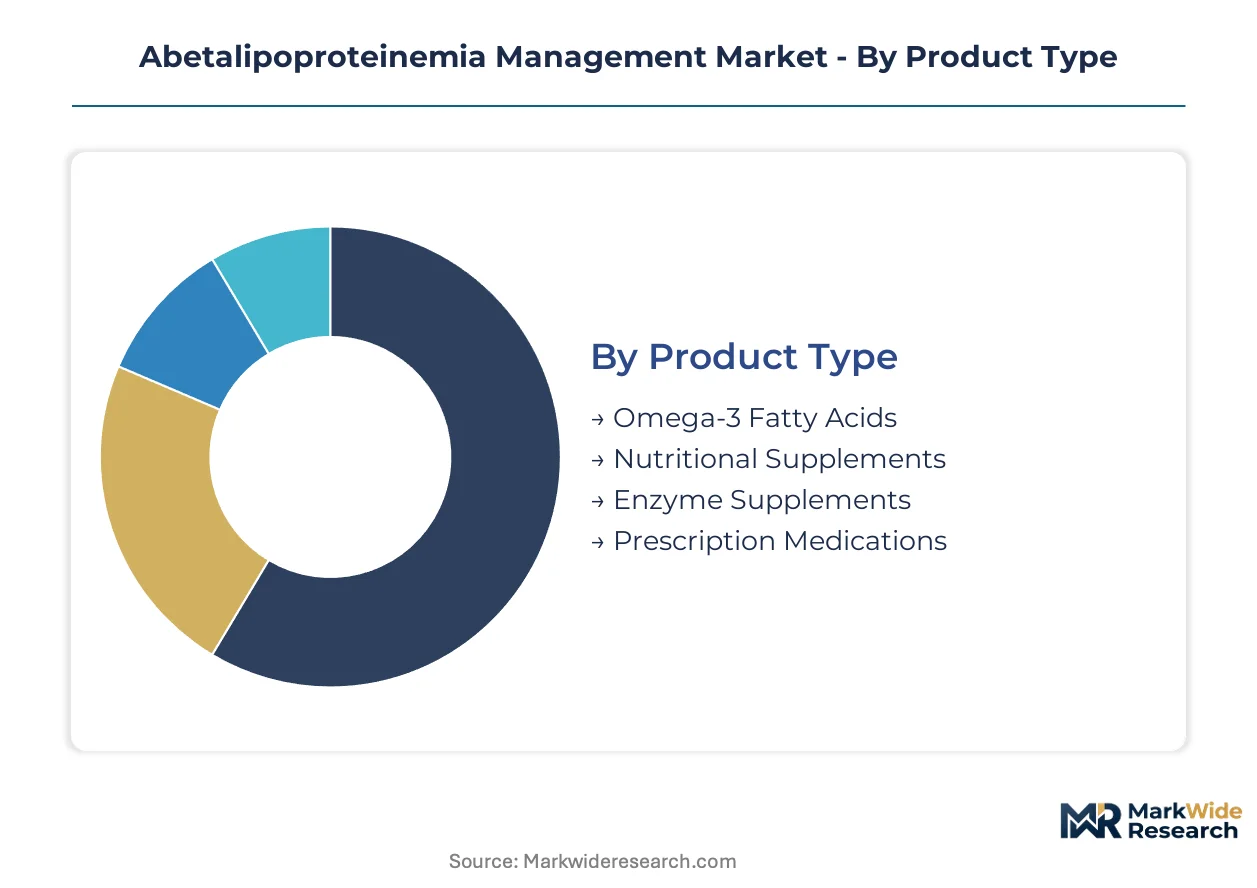
Segmentation in abetalipoproteinemia management reveals how patient acuity, care setting transitions, and therapeutic modality preferences reshape procurement patterns across institutional and home-based channels. Understanding these divides enables suppliers to align formulation development with site-of-care economics and reimbursement pathways.
Product Type:
After-sales service intensity varies sharply across product categories, with parenteral formulations demanding clinical training, compounding support, and adverse event monitoring that oral alternatives rarely require.
- Nutritional Supplements:These comprise fat-soluble vitamins A, D, E, and K in specialized formulations designed for malabsorptive patients. Demand concentrates in United States academic medical centers where integrated metabolic clinics manage lifelong replacement protocols. Supply contracts bundle dietitian counseling with product procurement to reduce hospital readmission rates.
- Prescription Medications:MTP inhibitors and emerging gene therapy candidates occupy this category, requiring cold-chain logistics and specialty pharmacy networks. United States-based biotech sponsors anchor clinical development, with FDA orphan drug designation accelerating regulatory timelines. Payer prior authorization complexity drives manufacturer investment in patient hub services.
- Omega-3 Fatty Acids:Essential fatty acid formulations prevent neurological complications through membrane phospholipid restoration.
- Enzyme Supplements:Pancreatic enzyme replacement therapies address exocrine insufficiency common in abetalipoproteinemia patients.
By volume, Nutritional Supplements leads. By growth pace, Prescription Medications is expanding most quickly.
Therapy Area:
Cost tier differentiation separates acute intervention budgets from chronic maintenance allocations, with metabolic specialists controlling the former and primary care networks the latter.
- Metabolic Disorders:This encompasses the core disease pathology and its systemic complications, requiring coordinated endocrinology, gastroenterology, and neurology input. United States tertiary centers cluster multidisciplinary teams under single institutional protocols. Reimbursement coding complexity favors bundled payment models over fee-for-service fragmentation.
- Genetic Abnormalities:MTP gene sequencing and carrier screening drive precision diagnostic workflows, with prenatal testing expanding addressable patient identification. European reference networks aggregate natural history data to support regulatory submissions. Diagnostic firms partner with therapeutic developers on co-commercialization arrangements.
- Dyslipidemia:Management focuses on lipid profile monitoring and cardiovascular risk modification.
- Preventive Care:Early intervention protocols target asymptomatic siblings and identified carriers.
By patient volume, Metabolic Disorders dominates. By investment intensity, Genetic Abnormalities shows the steepest expansion trajectory.
End User:
Customer type fragmentation creates distinct purchasing behaviors, with hospitals prioritizing formulary control and home care emphasizing patient self-administration compliance.
- Hospitals:These facilities handle acute decompensation, initial diagnosis, and complex surgical interventions requiring intravenous vitamin replacement. United States children's hospitals anchor pediatric metabolic disorder referral networks. Group purchasing organizations negotiate multi-year supply agreements covering both pharmaceutical and nutritional products.
- Home Care:Stable patients transition to self-administered regimens with nursing oversight for injection training and monitoring. Specialty pharmacies build regional compounding capabilities to serve dispersed rural populations. Remote patient monitoring integration reduces emergency department utilization.
- Clinics:Outpatient metabolic centers manage routine follow-up and dose adjustments.
- Rehabilitation Centers:Neurological sequelae recovery programs address ataxia and peripheral neuropathy progression.
By current patient volume, Hospitals leads. By transition momentum, Home Care is gaining share fastest.
Delivery Mode:
Supply concentration in sterile manufacturing capacity favors parenteral formats, while oral formulations compete on excipient innovation and bioavailability enhancement.
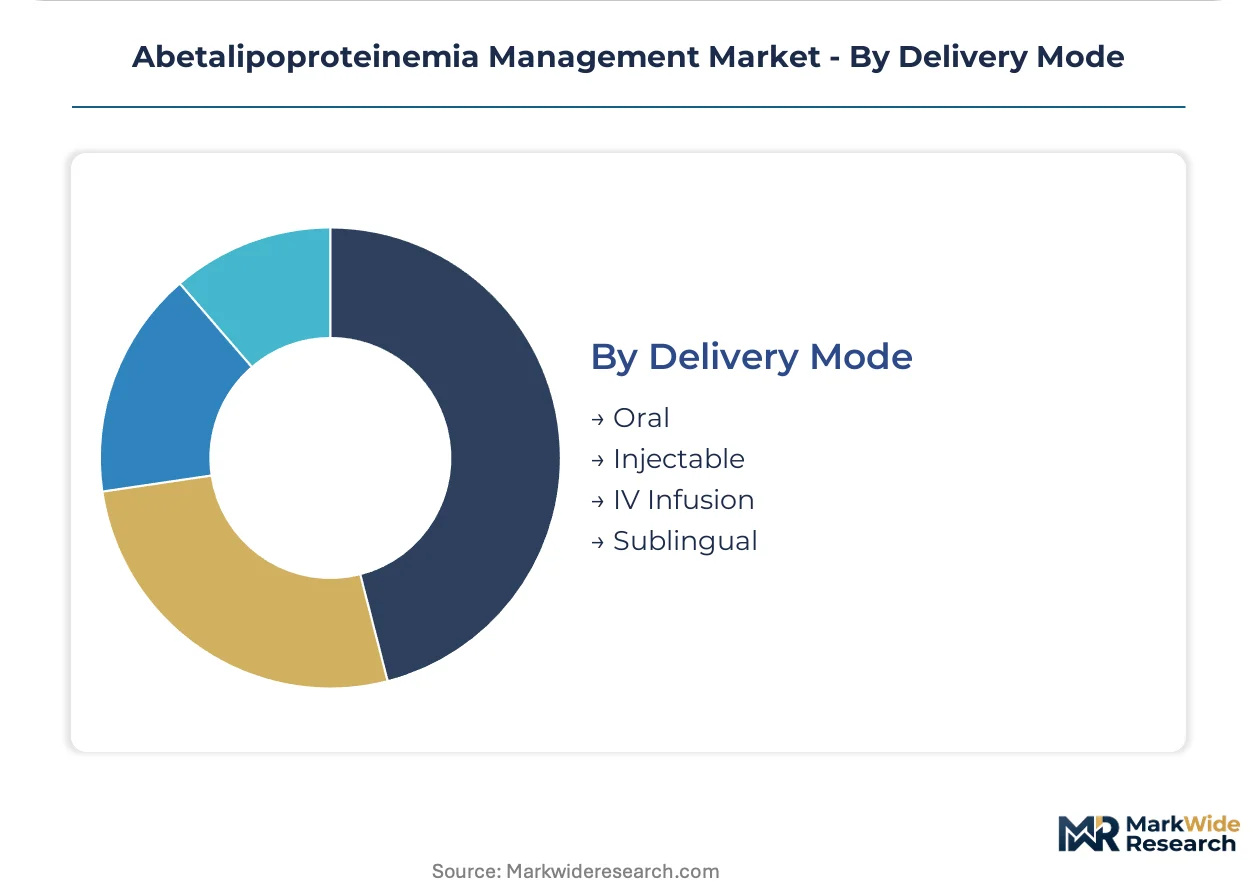
- Oral:Micronized vitamin formulations and lipid-based drug delivery systems improve absorption in fat-malabsorptive patients. United States compounding pharmacies customize doses for pediatric weight bands. Taste-masking technologies address adherence challenges in young children.
- IV Infusion:Hospital-based administration ensures bioavailability for patients with severe malabsorption or acute neurological crisis. United States infusion center networks expand capacity to reduce inpatient bed days. Reimbursement site-of-service differentials drive site selection.
- Injectable:Subcutaneous depot formulations extend dosing intervals for maintenance therapy.
- Sublingual:Buccal absorption bypasses gastrointestinal tract pathology in select vitamin formulations.
By utilization volume, Oral leads. By infrastructure investment, IV Infusion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract development organizations cluster manufacturing capacity for rare disease biologics in Switzerland and the United States, while patient access programs concentrate in Germany and the United Kingdom where reference networks aggregate natural history data.
United States
FDA orphan drug designation accelerates MTP inhibitor development through protocol assistance and tax credits. Academic medical centers in Boston and New York anchor specialized metabolic disorder clinics with integrated genetic counseling. The National Institutes of Health funds natural history studies that substitute for control arms in pivotal trials.
Germany
EMA rare disease frameworks synchronize with national reference networks for ultra-rare metabolic disorders. University hospitals in Munich and Heidelberg coordinate pediatric and adult trial enrollment across the European Union. The Federal Institute for Drugs and Medical Devices streamlines scientific advice for gene therapy candidates.
Switzerland
Swissmedic aligns with FDA breakthrough therapy pathways for liver-directed AAV vectors. Basel and Zurich host contract manufacturers scaling viral payload production for hepatocyte-specific delivery. Federal incentives for rare disease innovation attract biotech sponsors from neighboring jurisdictions.
United Kingdom
NHS England funds specialized lipid disorder units through metabolic medicine networks. London and Cambridge academic centers pioneer real-world evidence pathways using patient registry data. The Medicines and Healthcare products Regulatory Agency expedites access schemes for ultra-rare indications.
France
ANSM coordinates with EMA on pediatric investigation plans that reduce juvenile study burden. Paris and Lyon tertiary centers manage prenatal MTP gene sequencing for carrier identification. National rare disease plans bundle reimbursement for nutritional supplements with dietitian counseling services.
Abetalipoproteinemia Management Market Competitive Environment
Rare disease specialists and contract manufacturers split the market between therapeutic development and production infrastructure. The structure concentrates around players with established orphan drug commercialization pathways and GMP-certified biologics capacity. Three archetypes dominate: metabolic disorder portfolio builders, viral vector production platforms, and nutritional protocol suppliers. Competitive moves center on manufacturing slot reservations and reference network partnerships.
Within the rare disease portfolio tier, Recordati Rare Diseases and Ultragenyx Pharmaceutical Inc. exemplify metabolic specialization strategies, while Lonza Group occupies a position across contract viral vector manufacturing. These three entities anchor distinct value chain segments from clinical development through commercial-scale biologics production.
| Leading Market Players |
|---|
| Recordati Rare Diseases |
| Lonza Group |
| Ultragenyx Pharmaceutical Inc. |
| Aeglea BioTherapeutics |
| Piramal Pharma Solutions |
| Abbott Laboratories |
| Nestlé Health Science |
| Thermo Fisher Scientific |
| Orphalan SA |
| Others |
Value Chain & Pricing Dynamics
Transatlantic air freight corridors linking Swiss viral vector manufacturers to United States academic medical centers impose cold-chain cost premiums that concentrate pricing power among GMP-certified biologics suppliers while fragmenting nutritional supplement procurement across compounding pharmacy networks.
Pricing Analysis
FDA orphan drug designation dictates the pricing tier structure across abetalipoproteinemia therapeutics, stratifying access between premium gene therapy candidates and standard-of-care vitamin replacement protocols. Three-tier pricing structure across premium, standard, and economy levels separates investigational MTP inhibitors from branded fat-soluble vitamin formulations and generic essential fatty acid supplements. Cost compression in the nutritional supplement tier is intensifying because Indian and Chinese API manufacturers face agricultural feedstock volatility. Hospital procurement committees exhibit the highest price sensitivity due to bundled payment constraints, while specialty pharmacies serving home infusion patients demonstrate greater willingness to absorb service premiums.
Supply Chain Analysis
United States export-control restrictions on AAV vector manufacturing equipment limit technology transfer to contract development organizations in Switzerland and Germany, constraining global production capacity for gene therapy candidates. Active pharmaceutical ingredient sourcing draws from India, China, and Italy for vitamin E acetate and K1 phylloquinone, while viral plasmid production rests on United States and Swiss bioreactor capacity. Single-source vulnerability permeates the AAV payload engineering segment where GMP-trained cell culture specialists are scarce. Distribution runs through hospital-based infusion centers for acute parenteral administration, transitioning to regional specialty pharmacy networks for maintenance oral regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Abetalipoproteinemia management is approaching a platform-economics inflection as gene therapy developers and nutritional protocol suppliers converge on interoperable patient registry systems that aggregate natural history data across European reference networks and United States academic centers.
For Market Incumbents: Insulate manufacturing slot reservations at Lonza Group and Thermo Fisher Scientific facilities by securing multi-year viral vector production contracts before IND-enabling studies complete. Backward integration into vitamin E acetate API sourcing from Indian manufacturers reduces exposure to agricultural yield volatility threatening margin stability in the nutritional supplement segment.
For New Entrants and Emerging Players: Establish a beachhead in home infusion services for stable patients transitioning from hospital-based parenteral administration, where specialty pharmacy networks remain underdeveloped in rural United States markets. Partner with European reference networks to leverage real-world evidence pathways that substitute patient registry data for traditional control arms, accelerating regulatory timelines without enrolling scarce trial participants.
For Investors and Strategic Acquirers: Contract manufacturers with captive AAV vector production capabilities represent the most defensible acquisition archetype as gene therapy pipelines expand across ultra-rare metabolic disorders. Watch for FDA breakthrough therapy designations for liver-directed MTP gene transfer candidates as the inflection signal indicating manufacturing capacity constraints will tighten pricing power across the viral vector supply base.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV vector production at Swiss and United States facilities compresses plasmid-to-patient timelines for hepatocyte-specific delivery. |
| Real-World Evidence Pathway Development | FDA rare disease endpoint guidance enables natural history study substitution, reducing enrollment burden in ultra-rare populations. |
| Companion Diagnostic Integration | MTP gene sequencing panels at tertiary United States centers streamline patient identification for therapeutic developers. |
| Home Infusion Network Expansion | Specialty pharmacy compounding capabilities in dispersed rural United States markets reduce emergency department utilization. |
| Orphan Drug Designation Pursuit | FDA protocol assistance and tax credits lower development risk for MTP inhibitor programs entering clinical phases. |
Study Parameters
Operator-level perspectives from metabolic disorder clinic directors, specialty pharmacy procurement managers, GMP manufacturing engineers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA orphan drug filings, EMA rare disease framework documents, ClinicalTrials.gov protocol records, and United States hospital formulary databases. Bottom-up patient volume estimates triangulated against top-down market sizing from nutritional supplement manufacturer disclosures.
Scenario-bracketing around regulatory approval timelines, gene therapy manufacturing success rates, and vitamin API supply disruptions framed the analytical approach across the projection horizon. Segmentation dimensions modeled included therapeutic modality, care setting transition stage, delivery mode, and regional regulatory cluster. CAGRs were derived from patient prevalence projections, treatment penetration assumptions, and pricing trajectory analysis for biologic versus nutritional categories. Forecast inputs incorporated orphan drug incentive policy stability and reference network data aggregation velocity.
Stress conditions across AAV vector production bottlenecks, fat-soluble vitamin supply interruptions, and Medicare reimbursement negotiation outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory pathway continuity and manufacturing scale-up feasibility. Material shifts in FDA gene therapy guidance or EMA rare disease framework revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Bipolar Disorder (BPD) Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market