
 Spermaceti Wax Market | 2026-2036
Spermaceti Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Spermaceti Wax Market Analytics
The capability gap between integrated refinery operators and small-batch compounders is reorganizing competitive dynamics in spermaceti wax supply. Koster Keunen leverages its Netherlands-based extraction infrastructure to dominate European pharmaceutical-grade output. Nippon Seiro Co., Ltd. anchors Asian supply through its industrial-scale refining complex in Japan. Strahl & Pitsch specializes in cosmetic-grade formulations for North American personal care brands.
Spermaceti wax is a waxy ester historically derived from sperm whale head cavities, now primarily replicated through synthetic cetyl palmitate formulations with melting points near 44-46 degrees Celsius, serving as a premium emollient and binder in luxury goods. The product type landscape shows synthetic spermaceti displacing natural variants as marine conservation frameworks harden, while refined wax commands margin premiums in pharmaceutical applications. Application demand concentrates in cosmetics and candles where texture stability and clean-burning properties justify higher input costs against paraffin substitutes.
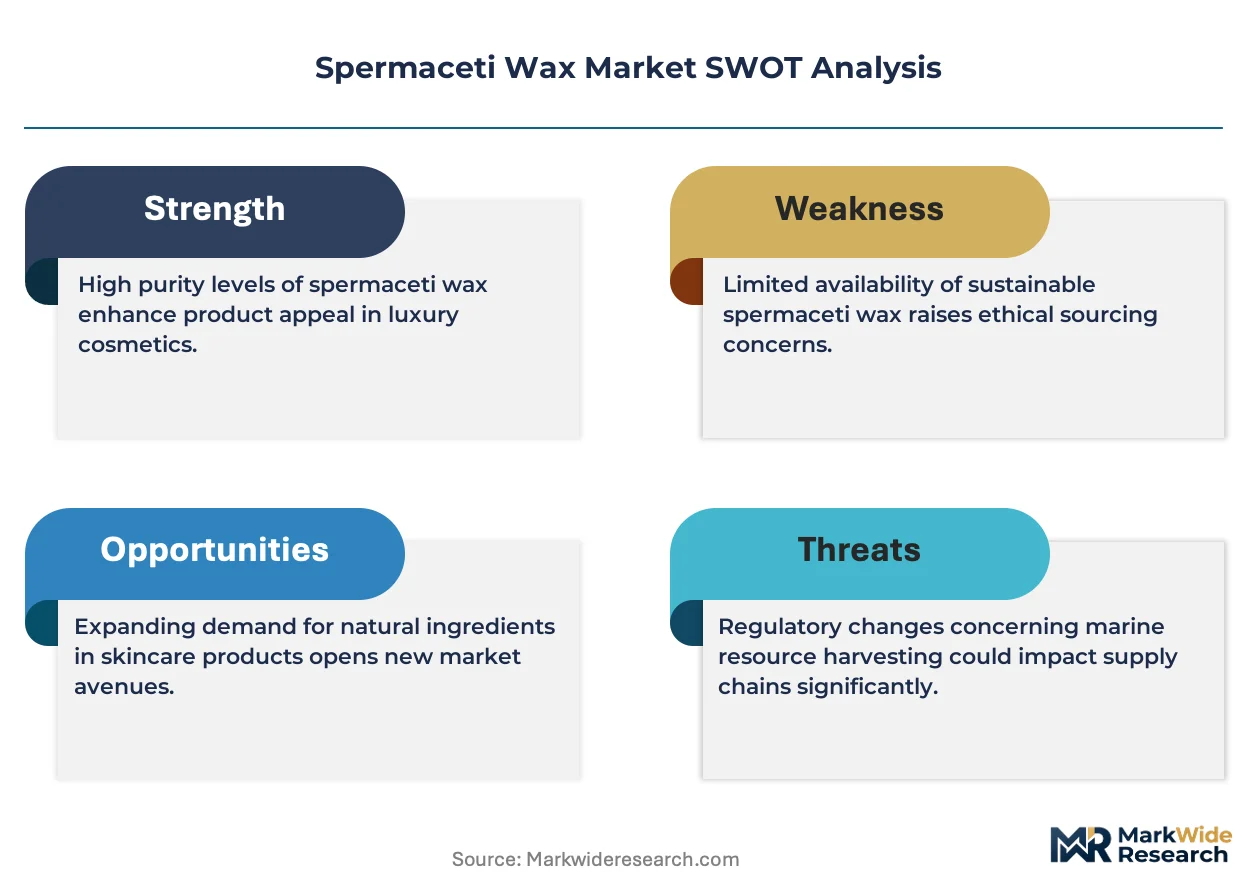
Regulatory oversight from the U.S. Marine Mammal Protection Act, the EU REACH framework, and Japan's METI chemical substance classifications collectively restrict natural spermaceti trade while channeling investment toward compliant synthetic pathways. FDA and EMA pharmaceutical excipient standards further differentiate grades accessible to drug manufacturers from general industrial supply. Stakeholders must track evolving cetacean product prohibitions and synthetic ester purity certifications to secure long-term formulation contracts.
Market Dynamics
Synthetic cetyl palmitate production is compressing natural spermaceti supply chains as marine conservation frameworks harden across multiple jurisdictions. This technological pivot reconfigures raw material sourcing, refinery investment patterns, and end-use certification requirements for cosmetic and pharmaceutical formulators.
Growth Catalysts
- EU REACH framework:Chemical substance registration protocols channel investment toward compliant synthetic ester pathways, accelerating laboratory-scale production capacity expansion in the Netherlands and Germany.
- Specialty candle makers:Artisanal producers in Japan and France absorb premium-grade synthetic wax for clean-burning formulations, creating stable demand anchors independent of mass-market paraffin substitution.
- Biotechnology fermentation:Microbial synthesis of wax esters is reducing reliance on petrochemical feedstocks, opening pharmaceutical-grade supply channels previously restricted by purity constraints.
Market Restraints
- Feedstock volatility:Palm oil and cetyl alcohol price swings compress blending margins for synthetic spermaceti compounders operating at sub-industrial scale.
- Japanese refinery concentration:Nippon Seiro's dominance in Asian pharmaceutical-grade output creates single-source vulnerability for regional drug excipient procurement.
- Paraffin substitution threat:Low-cost mineral wax alternatives capture mass-market candle applications, constraining synthetic spermaceti expansion beyond premium positioning.
Strategic Opportunities
- Indian personal care clusters:Underdeveloped domestic ester production creates import substitution potential as BIS standards mature for cosmetic-grade wax specifications.
- Pharmaceutical excipient certification:FDA and EMA compliance pathways for synthetic spermaceti open contract manufacturing opportunities for sterile formulation binders.
- Direct-to-formulator digital channels:Specialty chemical platforms are bypassing traditional distributor layers, enabling small-batch cosmetic laboratories to source certified grades without minimum order constraints.
Industry Challenges
- Pharmaceutical validation timelines:EMA excipient master file preparation demands 18-24 month documentation cycles, freezing capital in regulatory compliance before revenue realization.
- Legacy blending equipment incompatibility:Synthetic ester viscosity profiles require reactor reconfiguration for compounders transitioning from natural wax processing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spermaceti Wax Market |
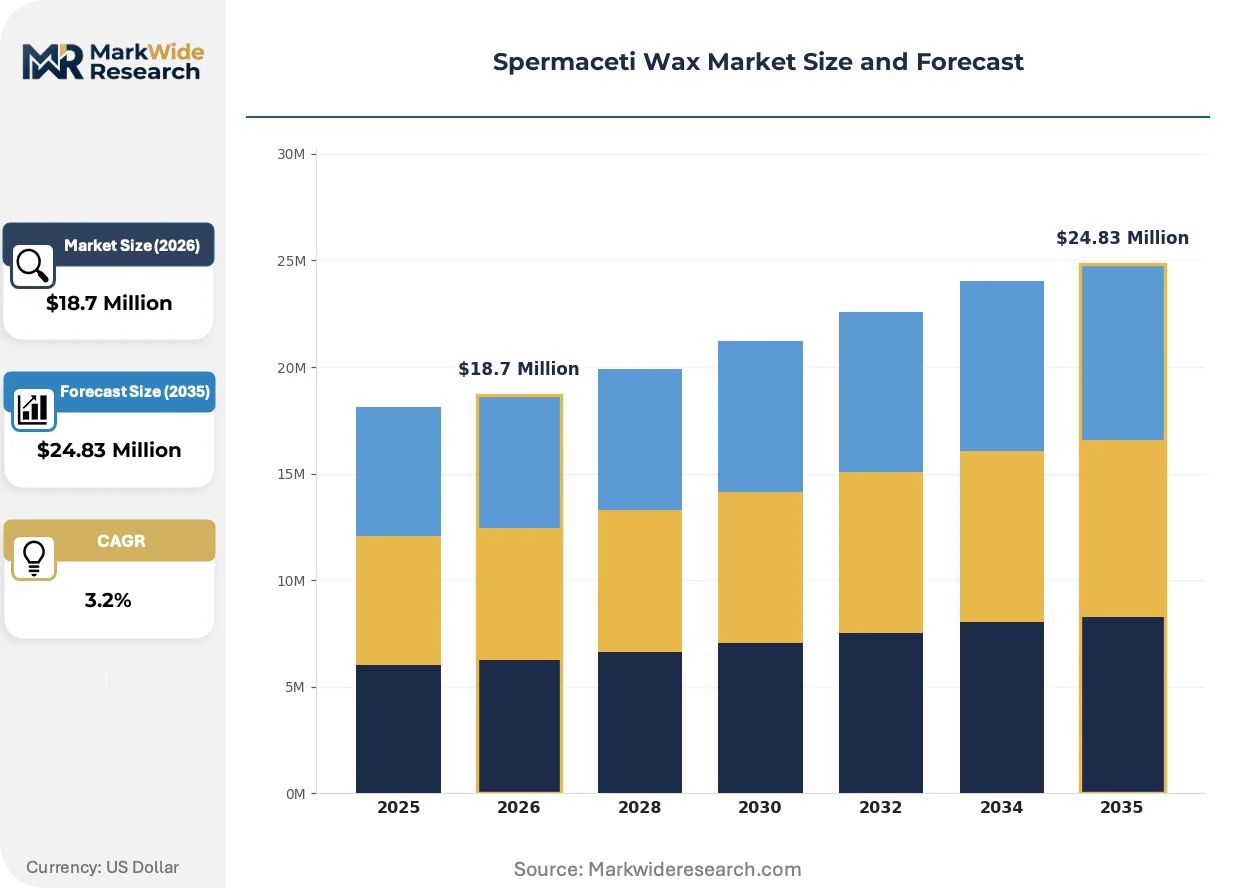
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $24.83 Million |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Spermaceti, Synthetic Spermaceti, Blended Wax, Refined Wax Application: Candles, Cosmetics, Pharmaceuticals, Lubricants End User: Personal Care Industry, Food Industry, Pharmaceutical Firms, Chemical Industry Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Koster Keunen, Nippon Seiro Co., Ltd., SER SpA, Paramelt BV, H&R Group, Spectrum Chemical Manufacturing Corp., Strahl & Pitsch, Nye Lubricants, The Frank B. Ross Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spermaceti Wax Market Evolving Landscape
Biotechnology-derived wax esters are disrupting petroleum-based synthetic production, while regulatory alignment across the US, EU, and Japan is standardizing purity benchmarks. These forces compress legacy supply chains and elevate certification as a competitive differentiator.
Enzymatic transesterification is supplanting traditional acid-catalyzed synthesis for cosmetic-grade spermaceti alternatives. Boutique formulators in France and Japan are adopting enzymatic batches for superior odor profiles and lower heavy-metal residuals. This biocatalytic shift is enabling premium pricing separation from commodity ester producers while compressing thermal processing energy requirements.
EMA's updated excipient risk assessment guidelines are tightening documentation requirements for synthetic wax binders in oral dosage forms. Drug manufacturers must now submit supply chain traceability data extending to fatty alcohol origins. Solid oral dose producers in Germany and Switzerland are responding by qualifying dual-source synthetic spermaceti suppliers to mitigate audit exposure.
Certification-driven procurement is consolidating buyer preference around ISO 22000 and EXCiPACT-certified suppliers. North American cosmetic brands are unbundling after-sales technical support from material supply contracts, purchasing formulation guidance separately through specialized consultancies. This service unbundling is most visible in New York and Los Angeles personal care clusters where rapid product iteration demands flexible external expertise.
Spermaceti Wax Market Segmentation
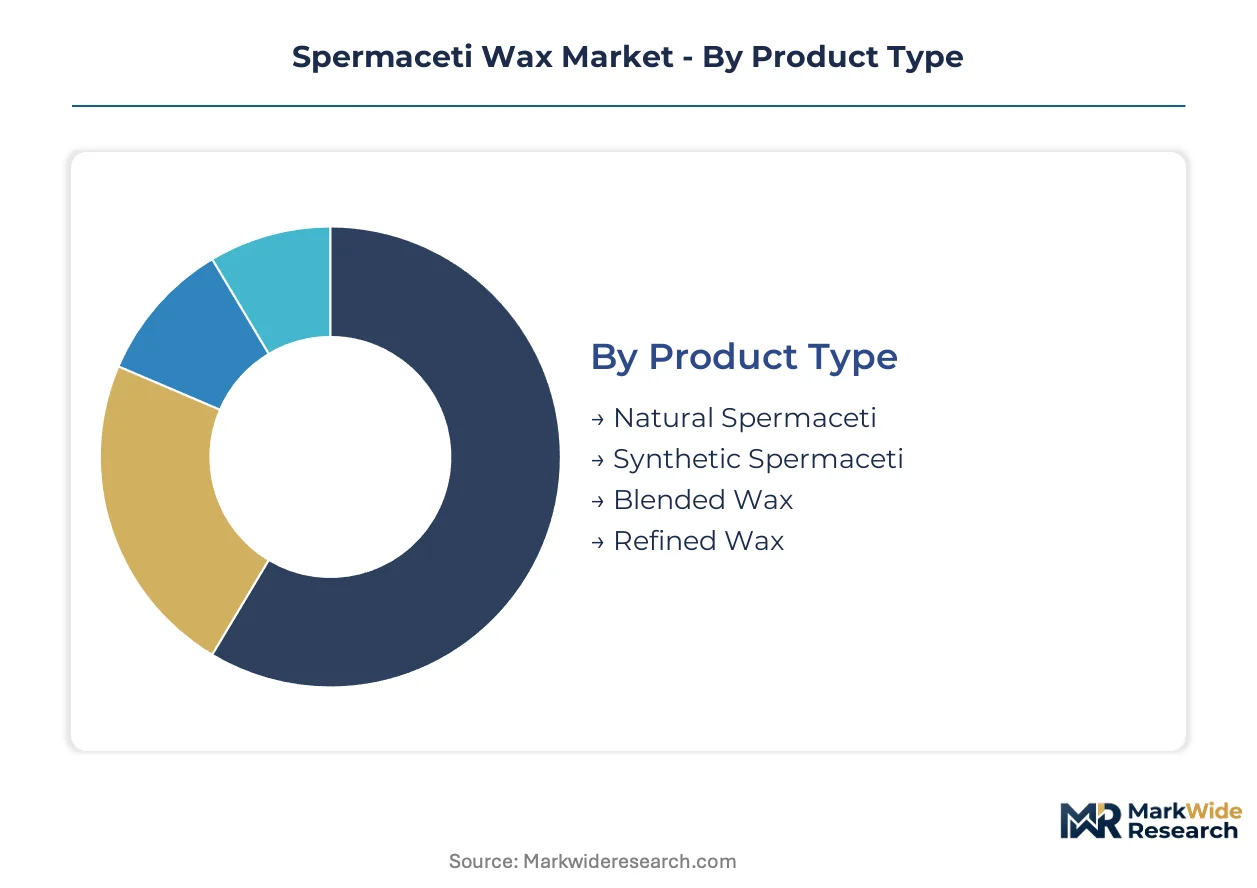
Spermaceti wax segmentation reflects the tension between heritage marine-derived supply and synthetic substitution pathways. Margin distribution varies sharply across purity grades and certification tiers, with pharmaceutical-grade synthetic esters commanding substantial premiums over commodity candle inputs.
Product Type:
Margin pools concentrate in pharmaceutical-grade synthetic and highly refined natural variants where excipient certification creates pricing power, while commodity candle-grade synthetics compete on feedstock cost efficiency.
- Natural Spermaceti:Historically extracted from sperm whale head cavities, this waxy ester now faces severe trade restrictions under the U.S. Marine Mammal Protection Act and EU cetacean product prohibitions. Surplus vintage stocks trade at collector premiums among heritage candle artisans in Nantucket and Mystic, Connecticut, though commercial viability is collapsing as conservation frameworks harden.
- Synthetic Spermaceti:Cetyl palmitate formulations synthesized from palm oil and cetyl alcohol feedstocks dominate contemporary supply, with enzymatic transesterification batches from Dutch and German producers achieving cosmetic-grade odor profiles. French boutique formulators and Japanese specialty candle makers absorb premium enzymatic output for clean-burning applications.
- Blended Wax:Paraffin-synthetic admixtures target cost-sensitive candle manufacturers seeking partial spermaceti performance at reduced input cost.
- Refined Wax:Multi-stage purification processes yield pharmaceutical-grade material meeting FDA and EMA excipient standards for oral dosage binders.
Refined Wax holds installed capacity. Synthetic Spermaceti is rotating up the share rankings.
Application:
Volume concentration sits in candles and cosmetics, though pharmaceutical applications generate disproportionate margin contribution through excipient certification requirements.
- Candles:Clean-burning properties and superior scent throw sustain demand among artisanal producers in France and Japan, where consumers pay premiums for petroleum-free alternatives. Specialty chandlers in Brooklyn and Portland source certified synthetic grades for luxury positioning against mass-market paraffin.
- Cosmetics:Emollient texture and oxidative stability drive formulation in premium skincare, with enzymatic-grade synthetics from Dutch suppliers penetrating Paris and Tokyo personal care laboratories. Koster Keunen's Netherlands extraction infrastructure anchors European cosmetic-grade supply.
- Pharmaceuticals:Tablet binding and controlled-release matrix applications demand EMA and FDA excipient master file documentation, freezing out uncertified suppliers.
- Lubricants:Niche precision instrument applications exploit low-temperature flow properties.
Candles anchor volume throughput. Pharmaceuticals is climbing the fastest on value contribution.
End User:
Customer-type differentiation tracks regulatory exposure, with pharmaceutical firms and personal care brands absorbing compliance costs that food and chemical industry buyers reject.
- Personal Care Industry:Premium skincare and color cosmetic formulators in New York, Los Angeles, and Paris specify enzymatic-grade synthetic spermaceti for texture stability and clean-label positioning.
- Food Industry:Limited confectionery glazing applications face substitution pressure from carnauba and beeswax alternatives.
- Pharmaceutical Firms:Solid oral dose manufacturers in Germany and Switzerland qualify dual-source synthetic spermaceti suppliers to mitigate EMA audit exposure under tightened excipient risk assessment guidelines.
- Chemical Industry:Industrial lubricant compounders represent price-sensitive demand with minimal certification requirements.
Pharmaceutical Firms hold qualification barriers. Personal Care Industry is expanding most quickly in absolute volume.
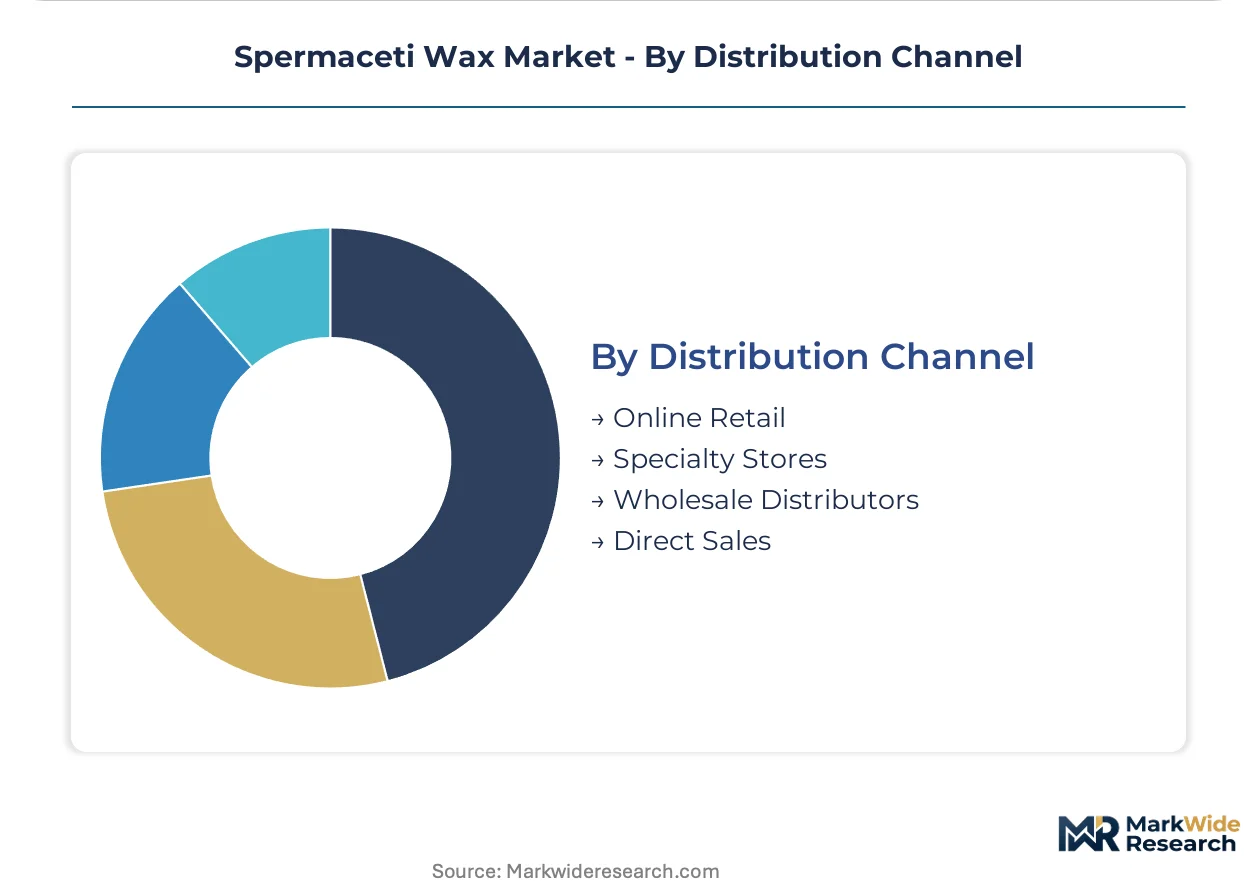
Distribution Channel:
Channel economics diverge sharply between high-touch specialty supply and emerging platform-driven procurement, with minimum order thresholds fragmenting access for small-batch formulators.
- Online Retail:Specialty chemical platforms enable direct-to-laboratory sourcing without distributor markups, particularly visible in Brooklyn and Los Angeles cosmetic clusters where rapid iteration demands flexible procurement.
- Specialty Stores:Heritage chandlery suppliers in Nantucket and Mystic maintain curated natural wax inventories for tourist and collector markets.
- Wholesale Distributors:Traditional chemical distributors aggregate pharmaceutical-grade supply for qualified drug manufacturers, embedding technical documentation and lot traceability.
- Direct Sales:Refinery operators including Nippon Seiro and Koster Keunen contract directly with large cosmetic and pharmaceutical accounts, bypassing intermediary layers.
Wholesale Distributors hold established pharmaceutical relationships. Online Retail is gaining share fastest among boutique formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France commands premium pricing for enzymatic-grade synthetic spermaceti, while Indian compounders absorb cost-sensitive candle-grade volumes. This asymmetry reflects divergent regulatory maturity and end-use certification requirements across consumer markets.
United States
Specialty chandlers in Brooklyn and Portland drive certified synthetic demand for clean-burning luxury positioning. The U.S. Marine Mammal Protection Act and FDA excipient standards channel all commercial supply toward synthetic pathways. Nantucket and Mystic, Connecticut maintain curated vintage natural wax inventories for heritage tourism markets.
France
Parisian boutique cosmetic laboratories absorb premium enzymatic batches for texture-stable skincare formulations. ANSM oversight aligns with REACH substance registration protocols for cosmetic-grade ester imports. Grasse fragrance clusters and Lyon personal care hubs concentrate formulation expertise for export-oriented brands.
Japan
Tokyo specialty candle makers anchor stable demand for petroleum-free clean-burning alternatives. METI chemical substance classifications restrict natural spermaceti trade while standardizing synthetic ester purity benchmarks. Osaka-Kobe industrial corridors host refining infrastructure serving pharmaceutical excipient qualification programs.
Germany
Solid oral dose manufacturers in Munich and Stuttgart qualify dual-source synthetic suppliers to mitigate EMA audit exposure. REACH framework registration demands channel investment toward compliant laboratory-scale production in the Netherlands and domestic chemical parks. Frankfurt distribution hubs aggregate pharmaceutical-grade supply for Central European drug manufacturers.
India
Mumbai and Bangalore personal care clusters create import substitution potential as BIS standards mature for cosmetic-grade wax specifications. Underdeveloped domestic ester production leaves cost-sensitive candle manufacturers dependent on Southeast Asian feedstock imports. Gujarat chemical processing zones offer blending infrastructure for emerging synthetic compounders.
Spermaceti Wax Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic-grade specialists commanding margin premiums while palm-oil-based compounders capture volume. The vendor base organizes around three strategic tiers: integrated refinery operators with extraction infrastructure, industrial-scale synthetic producers with petrochemical feedstock access, and boutique compounders serving artisanal end-users. Dominant competitive moves include backward integration into feedstock supply and certification-driven portfolio diversification toward pharmaceutical-grade output.
Within the integrated refinery tier, Koster Keunen and Nippon Seiro Co., Ltd. occupy positions anchored by European and Asian extraction infrastructure respectively. Strahl & Pitsch exemplifies the North American cosmetic-grade specialist archetype, serving personal care brands through formulation-focused supply relationships. These three entities represent distinct geographic and functional positioning without overlapping core competencies.
| Leading Market Players |
|---|
| Koster Keunen |
| Nippon Seiro Co., Ltd. |
| SER SpA |
| Paramelt BV |
| H&R Group |
| Spectrum Chemical Manufacturing Corp. |
| Strahl & Pitsch |
| Nye Lubricants |
| The Frank B. Ross Co. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Dutch enzymatic-grade producers and Parisian cosmetic laboratories lock in feedstock access while anchoring price visibility against palm oil volatility. These contracts insulate premium formulation houses from spot market swings while compressing margin flexibility for compounders serving price-sensitive candle manufacturers.
Pricing Analysis
Configured-to-order pricing spreads widen substantially against standard-grade synthetic spermaceti, with enzymatic batches commanding premiums based on odor profile purity and EMA excipient documentation depth. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and candle-grade levels stratifies buyer access, with FDA-certified pharmaceutical material showing least price sensitivity and commodity candle compounders absorbing maximum feedstock cost pressure. Pricing pressure stems from Malaysian palm oil price volatility transmitted through cetyl alcohol supply chains. Pharmaceutical firms demonstrate minimal price sensitivity due to regulatory switching costs, while Indian candle manufacturers face acute margin compression from paraffin substitution threats.
Supply Chain Analysis
Strategic stockpiling of cetyl alcohol feedstock dominates procurement strategy among European enzymatic producers, insulating batch consistency against Malaysian and Indonesian palm oil supply disruptions. Geographic supply concentrates in the Netherlands, Japan, and Germany, with Koster Keunen's extraction infrastructure and Nippon Seiro's refining complexes anchoring regional output. Raw material dependencies rest on palm oil derivatives, cetyl alcohol, and specialized lipase enzymes for biocatalytic production. Single-source vulnerability permeates Asian pharmaceutical-grade supply through Nippon Seiro's regional dominance. Distribution runs through wholesale chemical distributors for pharmaceutical accounts, while direct-to-laboratory platforms fragment cosmetic-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against low-cost paraffin and mineral wax alternatives that capture mass-market candle applications and erode synthetic spermaceti volume expansion.
For Market Incumbents: Compound certification barriers by securing dual-source EMA excipient master file documentation and anchoring pharmaceutical contract manufacturing relationships. Deepen backward integration into palm oil refining to neutralize feedstock volatility transmitted through Malaysian supply chains. Enzymatic production capacity expansion in the Netherlands reinforces margin position against commodity ester compounders. For New Entrants and Emerging Players: Differentiate on enzymatic biocatalytic production to access premium cosmetic-grade pricing tiers inaccessible to acid-catalyzed commodity producers. Target underdeveloped Indian personal care clusters where BIS standard maturation creates import substitution windows for domestic compounders. Direct-to-formulator digital channels enable laboratory-scale supply without distributor minimum order constraints. For Investors and Strategic Acquirers: Boutique enzymatic specialists with established Paris and Tokyo customer relationships represent priority acquisition archetypes for portfolio premiumization. Long-term viability hinges on synthetic pathway cost convergence against natural alternatives and regulatory permanence of cetacean product prohibitions. FDA or EMA certification pipeline velocity signals inflection timing for pharmaceutical-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive palm oil refining neutralizes Malaysian price volatility for enzymatic producers. |
| EMA Excipient Master File Certification | Documentation depth locks pharmaceutical manufacturers into qualified supplier relationships. |
| Enzymatic Production Capacity Expansion | Biocatalytic batches achieve odor profiles that acid-catalyzed synthesis cannot replicate. |
| Direct-to-Laboratory Digital Platform Launch | Brooklyn and Los Angeles cosmetic clusters source certified grades without distributor markups. |
| Dual-Source Supplier Qualification Programs | German solid oral dose manufacturers mitigate audit exposure under tightened EMA guidelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with specialty candle chandlers, cosmetic formulation chemists, pharmaceutical excipient procurement managers, and refinery operations directors. Secondary validation drew from customs trade databases, EMA excipient master file registries, FDA drug approval documentation, and REACH substance registration records. Bottom-up volume triangulation across grade tiers and end-use segments converged with top-down market sizing from production capacity aggregates.
Across the analysis window, the forecasting framework modeled product type substitution dynamics, application-grade margin stratification, end-user regulatory exposure tiers, and regional certification maturity patterns. CAGRs were derived from segment-level volume trajectories weighted by value-per-ton differentials across pharmaceutical, cosmetic, and candle applications. Feedstock cost elasticity and enzymatic capacity buildout schedules informed trajectory boundaries.
Material uncertainties — feedstock price shocks, regulatory prohibition extensions, and biotechnology fermentation breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding synthetic substitution velocity and conservation framework permanence. Revision becomes warranted when paraffin-wax price spreads cross thresholds that trigger mass-market formulation switching.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Specialty Coating Market
Specialty Materials
Hornbeam Market