
 Nanoencapsulation Market | 2026-2036
Nanoencapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoencapsulation Market Foresight
Multi-source procurement for active pharmaceutical ingredients is shifting toward captive nanoencapsulation capabilities as sponsors seek supply security. Evonik Industries leverages its lipid nanoparticle platform to anchor pharmaceutical partnerships across North America and Europe. Lonza Group sustains competitive positioning through integrated bioconjugation and nanoscale formulation services. BASF SE differentiates via high-throughput screening infrastructure that accelerates customer co-development timelines.
Nanoencapsulation encloses bioactive compounds within nanoscale carriers typically ranging from 10 to 1000 nanometers, using phospholipid bilayers, polymeric matrices, or solid lipid cores to protect payloads from degradation and enable targeted release. The technology serves pharmaceutical, nutraceutical, and agrochemical sectors by improving bioavailability, masking taste, and controlling release kinetics. Liposome-based systems lead current pharmaceutical revenue pools due to established regulatory pathways and manufacturing scalability, while polymeric nanoparticles represent the fastest-expanding category driven by mRNA vaccine platform adaptations and oncology pipeline diversification. Spray drying technology dominates industrial throughput for food and nutraceutical applications where thermal stability and cost efficiency outweigh precision requirements.
The FDA enforces current good manufacturing practice standards for nanoscale drug products through its emerging technology program, while EMA's reflection papers on nanomedicines impose additional characterization and stability testing burdens that elevate barrier to entry. REACH registration requirements in Europe and EPA pesticide tolerance frameworks in the United States further constrain formulation chemistry choices and environmental fate testing obligations. Stakeholders must monitor evolving pharmacopeial monographs for liposomes and polymeric nanoparticles, as harmonized standards between FDA and EMA will determine which manufacturing platforms achieve transatlantic commercial scalability without redundant qualification runs.
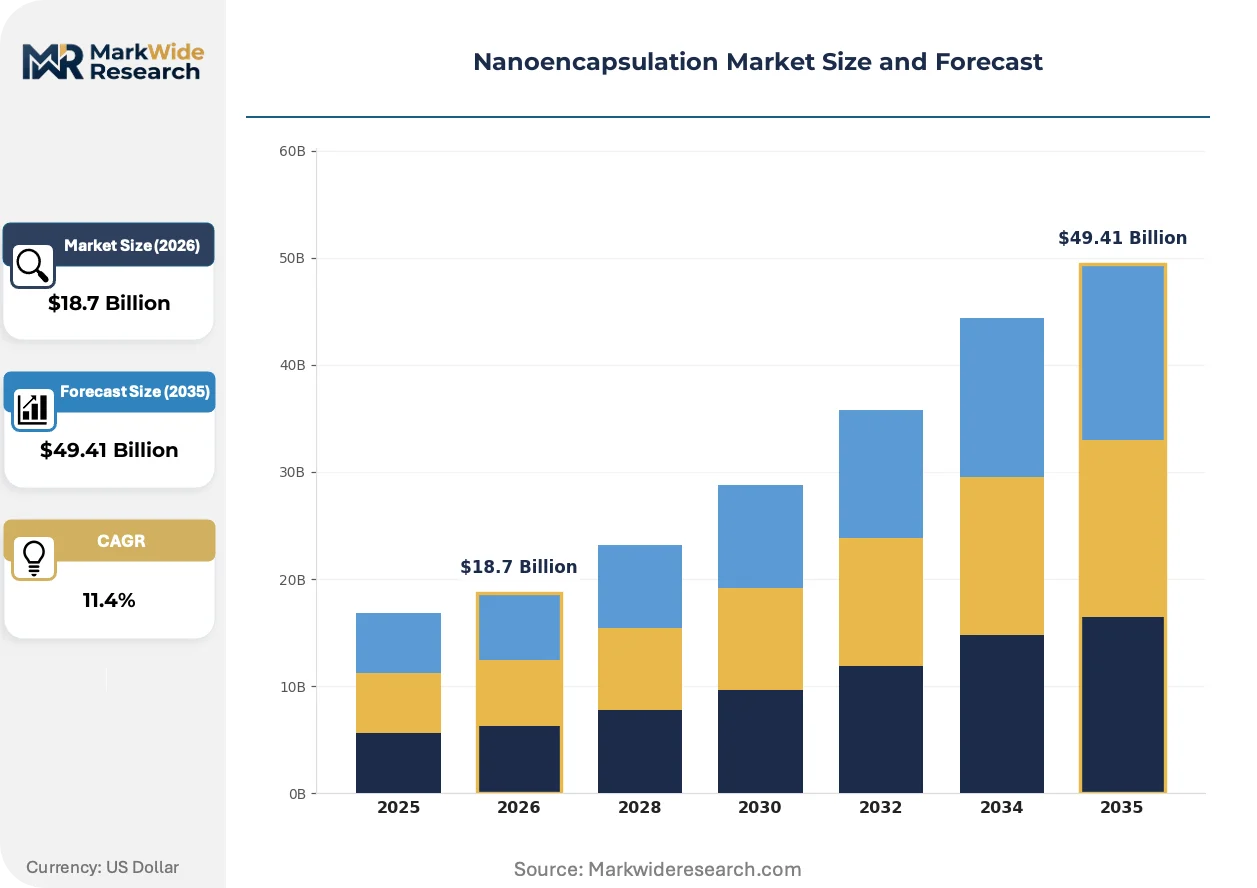
Market Dynamics
Pharmaceutical sponsors are internalizing nanoencapsulation capabilities to secure lipid nanoparticle supply chains for mRNA therapeutics, compressing the traditional contract manufacturing landscape and elevating captive production as the dominant structural force.
Growth Catalysts
- Lipid nanoparticle platform standardization:FDA's emerging technology program accelerates regulatory pathways for nucleic acid delivery systems, pulling investment into scalable manufacturing infrastructure.
- EMA quality-by-design mandates:European pharmaceutical sponsors upgrade formulation capabilities to meet tightened characterization requirements, expanding addressable market for precision encapsulation services.
- Japan:METI funding for advanced drug delivery systems concentrates R&D investment in Tokyo-Osaka pharmaceutical clusters, anchoring regional demand for phospholipid-based carriers.
Market Restraints
- Phospholipid supply concentration:Three suppliers dominate high-purity lipid feedstock for pharmaceutical-grade nanoparticles, creating input vulnerability for formulation developers.
- REACH registration burdens:ECHA's nanomaterial registration requirements impose extended environmental fate testing timelines that delay European commercialization by 18-24 months.
- Conventional liposome substitution:Established PEGylated liposome platforms in oncology limit pricing power for next-generation polymeric alternatives despite superior payload capacity.
Strategic Opportunities
- Agrochemical nanoformulation:EPA's pesticide tolerance frameworks create first-mover advantage for encapsulation technologies enabling controlled-release crop protection in US specialty agriculture.
- Continuous manufacturing convergence:Integration of microfluidic synthesis with process analytical technology reduces batch-to-batch variability, opening contract opportunities for mid-scale pharmaceutical sponsors.
- India:CDSCO's streamlined approval pathways for complex generics attract investment in local nanoencapsulation capacity serving domestic and export markets.
Industry Challenges
- Process analytical technology expertise:FDA's real-time release testing expectations outpace available talent pools for in-line particle characterization and multivariate data analysis.
- Equipment qualification timelines:Validating nanoscale milling and homogenization systems for GMP production extends facility commissioning by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoencapsulation Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Liposomes, Nanocapsules, Nanocrystals Technology: Coacervation, Solvent Evaporation, Nanoemulsion, Spray Drying End User: Pharmaceuticals, Food Industry, Cosmetics, Agriculture Application: Drug Delivery, Nutraceuticals, Food Preservation, Skin Care |
| Companies Covered | Blue California, Lonza Group, Evonik Industries, DuPont de Nemours, Cargill, BASF SE, NanoCarrier Co., Ltd., DSM, Aquanova AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoencapsulation Market Shifts & Advancements
Microfluidic manufacturing platforms are compressing development cycles for lipid nanoparticles while regulatory convergence between FDA and EMA reshapes qualification strategies. These forces are redirecting competitive investment toward integrated analytical and production capabilities.
Solid lipid nanoparticles are expanding into oral bioavailability enhancement for poorly soluble small molecules. Generic pharmaceutical manufacturers in India and Eastern Europe adopt these carriers to differentiate commodity portfolios. The technology is expanding into cost-sensitive therapeutic categories previously served by conventional solubilization approaches, compressing margins for older formulation technologies.
REACH nanomaterial registration requirements in Europe impose substance-by-substance characterization obligations that elevate documentation costs. Formulation developers must demonstrate environmental fate and ecotoxicology profiles for each novel carrier composition. Small and mid-scale sponsors in Germany and France are consolidating development pipelines to concentrate resources on highest-probability candidates.
Long-term supply agreements are displacing spot purchasing for pharmaceutical-grade lipids and polymers. Sponsors lock in multi-year contracts with specified volume tiers and quality benchmarks, transferring inventory risk to suppliers. This pattern concentrates most visibly in United States mRNA vaccine manufacturing networks where input security outweighs price optimization.
Nanoencapsulation Market Segmentation
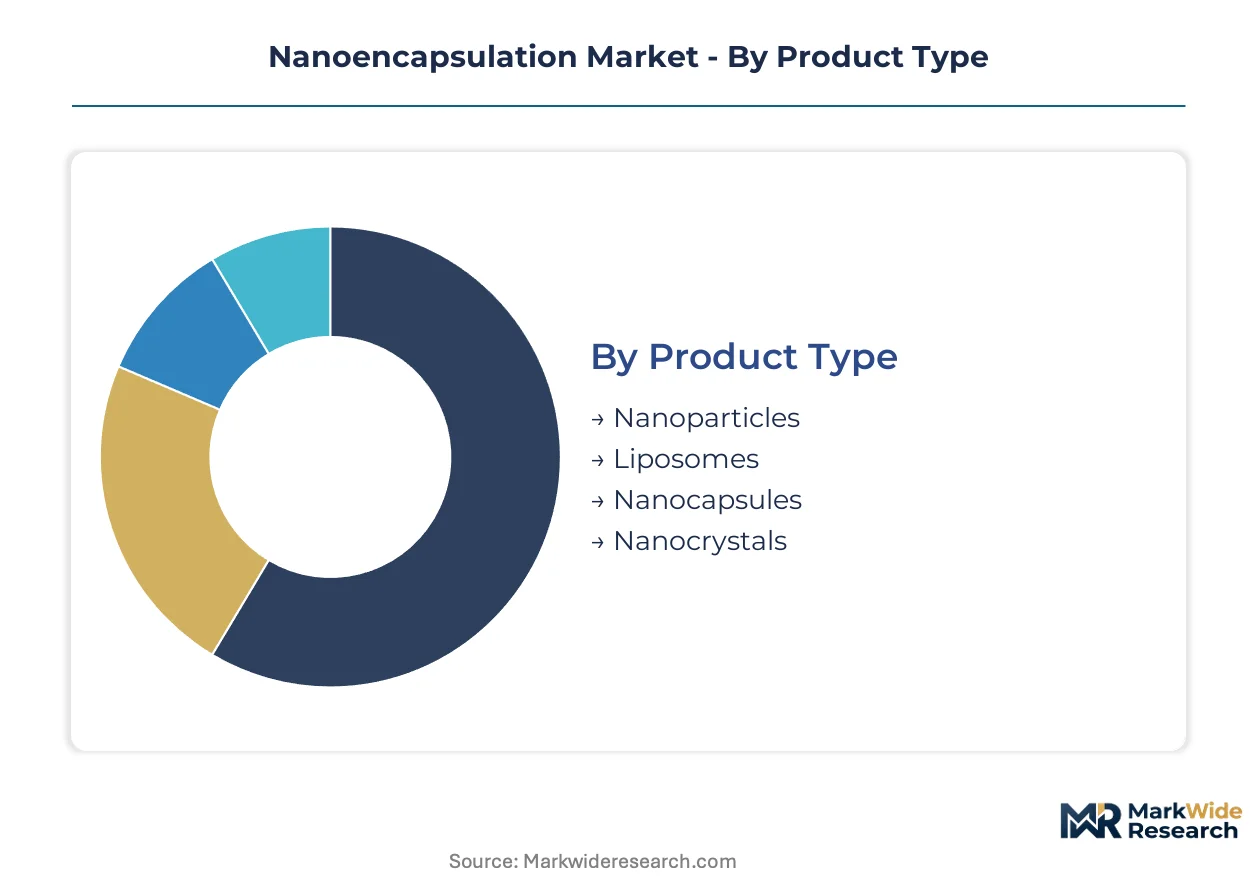
Carrier architecture and manufacturing modality determine performance specifications, regulatory pathways, and commercial scalability across nanoencapsulation deployments. Segmentation reveals where formulation investments concentrate and which technology platforms command premium positioning.
Product Type:
Structural composition dictates payload capacity, release kinetics, and biocompatibility profiles for downstream applications.
- Liposomes:Phospholipid bilayer vesicles enclose hydrophilic and hydrophobic compounds within aqueous cores and lipid membranes. FDA's established regulatory monographs for PEGylated liposome oncology products sustain manufacturing scale advantages in United States pharmaceutical corridors.
- Nanoparticles:Polymeric or lipid matrices ranging from 10-1000 nanometers protect actives from enzymatic degradation. mRNA vaccine platform adaptations are accelerating capacity buildouts in Germany and Japan where sponsors internalize lipid nanoparticle production.
- Nanocapsules:Reservoir-type carriers with liquid or semi-solid cores surrounded by polymeric shells enable burst or sustained release tuning. Agrochemical formulators in Brazil leverage these systems for controlled-release pesticide delivery under ANVISA tolerance frameworks.
- Nanocrystals:Pure drug nanoscale particles eliminate carrier materials entirely, maximizing payload density for poorly soluble small molecules. Generic manufacturers in India adopt this architecture for bioavailability enhancement of commodity APIs under CDSCO complex generic pathways.
Liposomes lead on scale; nanoparticles lead on momentum.
Technology:
Process selection balances precision, throughput, and capital intensity against target application requirements.
- Spray Drying:Atomization of liquid feedstocks into heated gas streams produces solid particulates with tunable density and morphology. Food and nutraceutical manufacturers in Italy and Spain prioritize this modality for thermal stability and cost efficiency at industrial scale.
- Solvent Evaporation:Organic phase dispersion into aqueous surfactant solutions followed by solvent removal yields uniform polymeric nanoparticles. Pharmaceutical sponsors in Switzerland deploy this method for oncology payload encapsulation requiring tight particle size distributions.
- Nanoemulsion:High-energy or low-energy phase inversion creates thermodynamically stable sub-micron droplets for topical and oral delivery. Cosmetics formulators in France utilize this approach for skin penetration enhancement under ANSM cosmetic safety guidelines.
- Coacervation:Phase separation of hydrocolloid polymers around core materials forms shell structures for taste masking and controlled release. Japanese nutraceutical producers apply this technology for functional food ingredient protection.
Spray drying dominates volume economics; solvent evaporation commands precision premiums.
End User:
Customer sector determines regulatory burden, specification stringency, and contract manufacturing versus captive production decisions.
- Pharmaceuticals:GMP-validated nanoencapsulation for nucleic acid therapeutics, oncology, and controlled-release small molecules. Sponsors in United States, Germany, and Japan are internalizing lipid nanoparticle capabilities to secure mRNA supply chains.
- Food Industry:Encapsulation of vitamins, probiotics, and bioactive compounds for stability and targeted release. European manufacturers navigate EFSA novel food authorization requirements for nanoscale ingredient safety assessments.
- Cosmetics:Skin delivery systems for anti-aging and UV protection actives. French and South Korean formulators drive demand for liposomal and nanoemulsion carriers under respective national cosmetic safety frameworks.
- Agriculture:Controlled-release formulations for crop protection and nutrient delivery. United States specialty agriculture adopts these systems under EPA pesticide tolerance frameworks to reduce environmental runoff.
Pharmaceuticals anchor value concentration; agriculture offers expansion headroom.
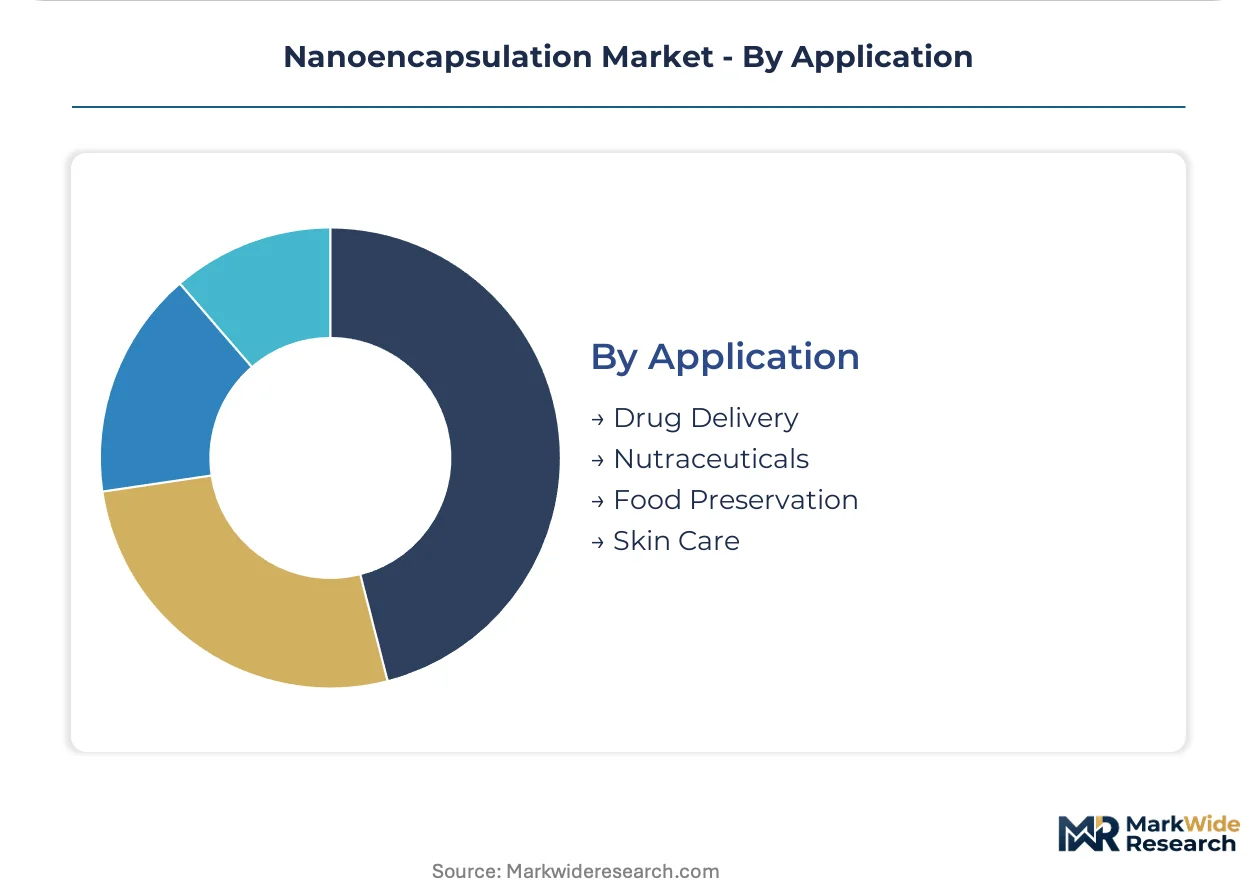
Application:
Functional use case shapes carrier design priorities and reimbursement or pricing dynamics.
- Drug Delivery:Targeted and controlled-release systems for improved pharmacokinetics and reduced toxicity. Lipid nanoparticle platforms for nucleic acid delivery represent the steepest expansion trajectory as sponsors diversify beyond infectious disease into oncology and rare disease.
- Nutraceuticals:Bioavailability enhancement for vitamins, minerals, and botanical extracts. Indian and Chinese manufacturers scale solid lipid nanoparticle production for oral supplement applications.
- Food Preservation:Antimicrobial and antioxidant encapsulation for shelf-life extension. Italian and Spanish food technology providers integrate spray-dried encapsulates into clean-label preservation strategies.
- Skin Care:Dermal penetration and stabilization of sensitive actives. South Korean cosmetics innovation clusters drive adoption of liposomal retinol and vitamin C delivery systems.
Drug delivery commands premium pricing; nutraceuticals scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka pharmaceutical corridor anchors international nanoencapsulation demand through METI-funded advanced drug delivery programs and concentrated lipid nanoparticle manufacturing infrastructure.
United States
mRNA vaccine manufacturing networks and nucleic acid therapeutic pipelines drive lipid nanoparticle demand across Massachusetts and North Carolina biotech clusters. FDA's emerging technology program accelerates regulatory pathways for nanoscale drug products. Greater Boston anchors captive production investments as pharmaceutical sponsors internalize formulation capabilities to secure supply chains.
Germany
EMA quality-by-design mandates and REACH nanomaterial registration requirements elevate manufacturing standards for pharmaceutical-grade carriers. ECHA's environmental fate testing timelines constrain commercialization schedules for novel formulations. The Rhine-Main pharmaceutical corridor concentrates precision encapsulation services as sponsors upgrade characterization capabilities.
Japan
METI funding for advanced drug delivery systems channels R&D investment toward phospholipid-based carriers in the Tokyo-Yokohama cluster. PMDA harmonization with FDA standards reduces redundant qualification burdens for trans-Pacific sponsors. Osaka-based manufacturers expand lipid nanoparticle capacity to serve domestic oncology and rare disease pipelines.
India
CDSCO streamlined approval pathways for complex generics attract investment in solid lipid nanoparticle production for bioavailability enhancement. Domestic pharmaceutical manufacturers scale encapsulation capacity to serve export markets across Southeast Asia and Africa. Hyderabad and Ahmedabad clusters concentrate contract formulation services for generic portfolio differentiation.
Switzerland
Swissmedic's precision regulatory framework supports high-value oncology payload development through solvent evaporation manufacturing. Basel-Zurich pharmaceutical corridors integrate nanoscale formulation with bioconjugation capabilities. Precision encapsulation services command premium positioning for niche therapeutic applications requiring tight particle size distributions.
Nanoencapsulation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue continuous manufacturing and microfluidic platform specialization. The competitive structure stratifies across three capability tiers: integrated pharmaceutical service providers, diversified chemical conglomerates with nanoscale formulation divisions, and specialized technology licensors. Strategic moves concentrate on captive supply chain consolidation and high-throughput screening infrastructure deployment.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries exemplify the diversified-tier archetype through integrated material science and pharmaceutical-grade carrier production. Lonza Group anchors the pharmaceutical service tier with combined bioconjugation and nanoscale formulation capabilities. These three entities represent distinct competitive positioning vectors: chemical feedstock integration, pharmaceutical manufacturing services, and hybrid platform technologies.
| Leading Market Players |
|---|
| Blue California |
| Lonza Group |
| Evonik Industries |
| DuPont de Nemours |
| Cargill |
| BASF SE |
| NanoCarrier Co., Ltd. |
| DSM |
| Aquanova AG |
| Others |
Supply & Pricing Matrix
Captive production integration by pharmaceutical sponsors anchors supply security premiums while compressing contract manufacturing margins across lipid nanoparticle value chains. Long-term offtake agreements with specified volume tiers transfer inventory risk to high-purity lipid suppliers in Germany and Japan, elevating pricing power for feedstock producers relative to formulation developers.
Pricing Analysis
Phospholipid and synthetic lipid cost pass-through dominates contract manufacturing quotations, with high-purity pharmaceutical-grade inputs commanding 40-60% of total formulation service pricing. Price differentiation rests on GMP certification tier and particle characterization depth, with FDA-emerging-technology-qualified facilities capturing premiums over standard-grade providers. Cost compression in standard liposome manufacturing intensifies as Indian and Chinese generic producers scale solid lipid nanoparticle capacity. Commodity nutraceutical encapsulation exhibits highest price sensitivity, while nucleic acid therapeutic sponsors demonstrate lowest sensitivity due to supply security priorities.
Supply Chain Analysis
Single-source vulnerability sits with German, Japanese, and United States suppliers of high-purity phospholipids and ionizable lipids for pharmaceutical-grade nanoparticles. Formulation developers draw from concentrated lipid feedstock, specialized milling equipment, and analytical instrumentation dependencies. Tariff exposure on imported excipients from China elevates landed cost volatility for European sponsors. Distribution runs through qualified contract manufacturing organizations and captive pharmaceutical production facilities, with spot purchasing displaced by multi-year supply agreements in mRNA vaccine manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoencapsulation market compounds steadily as nucleic acid therapeutic pipelines diversify beyond infectious disease into oncology and rare disease indications, anchoring durable demand for lipid nanoparticle manufacturing infrastructure.
For Market Incumbents: Lock in phospholipid supply agreements with volume commitments extending through the mid-term projection horizon to defend against emerging Indian and Chinese generic entrants. Secure FDA emerging technology program qualification for continuous manufacturing platforms before process analytical technology expertise shortages intensify. Prioritize backward integration into high-purity lipid synthesis to reduce feedstock cost pass-through vulnerability.
For New Entrants and Emerging Players: Microfluidic platform specialization offers entry leverage into mid-scale pharmaceutical sponsor segments underserved by large contract manufacturing organizations. Target agrochemical nanoformulation under EPA pesticide tolerance frameworks where first-mover advantage remains unclaimed by established pharmaceutical-focused incumbents. Deploy equipment-as-a-service models to bypass capital-intensive GMP facility commissioning timelines.
For Investors and Strategic Acquirers: Roll-up economics work for precision encapsulation service providers because EMA quality-by-design mandates and FDA characterization requirements are consolidating demand around qualified manufacturing platforms. The 5-10 year viability window favors targets with integrated analytical capabilities and transatlantic regulatory footprints. Monitor CDSCO approval velocity for complex generics as inflection indicator for Indian manufacturing export competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Pharmaceutical sponsors lock in lipid security under FDA emerging technology program standards. |
| Continuous Manufacturing Scale-Up | Microfluidic platform deployment reduces batch-to-batch variability for EMA quality-by-design compliance. |
| Backward Integration | Captive phospholipid synthesis insulates margins from German and Japanese supplier concentration. |
| Regulatory Qualification Investment | FDA emerging technology program entry accelerates nucleic acid therapeutic approval pathways. |
| Geographic Capacity Expansion | Indian and Chinese facilities capture CDSCO complex generic export demand across Southeast Asia. |
Research Methodology
Direct dialogue with formulation development executives, regulatory affairs directors at EMA and FDA, contract manufacturing procurement leads, and phospholipid supplier technical sales managers grounded qualitative findings. Secondary validation drew from FDA emerging technology program filings, EMA reflection papers on nanomedicines, CDSCO complex generic approval databases, and REACH nanomaterial registration disclosures. Bottom-up capacity assessments and top-down therapeutic pipeline valuations were triangulated against customs trade data for high-purity lipid imports.
Bottom-up modeling segmented revenue by carrier architecture, manufacturing technology, end-use sector, and therapeutic application area across the analysis window. Top-down validation cross-referenced pharmaceutical R&D expenditure patterns and nucleic acid therapeutic investment flows. CAGRs were derived from slope analysis of annual capacity buildouts against sponsor pipeline progression rates. Forecast inputs incorporated METI funding trajectories for Japanese advanced drug delivery and EPA pesticide tolerance framework evolution for US agrochemical applications.
The model holds under sustained nucleic acid therapeutic clinical success and stable phospholipid supply availability; deviation in regulatory harmonization timelines or lipid feedstock disruption would shift capacity utilization assumptions. Forecasts reflect documented base conditions without contingency for unforeseen therapeutic platform obsolescence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Alginate Films Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Compostable Cotton Swab Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Specialty Carbon Black Market