
 Polyphenylsulfone Market | 2026-2036
Polyphenylsulfone Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylsulfone Market Analysis
The polyphenylsulfone market is pivoting between premium medical-grade resins and commodity industrial sheets as qualification costs and performance requirements diverge sharply. Solvay S.A. leverages its vertically integrated sulfone polymer platform to dominate high-purity resin supply for fluid handling systems. Ensinger GmbH specializes in precision extruded stock shapes, anchoring European medical device OEM procurement channels. BASF SE competes through broad engineering plastics distribution, extending sulfone access into automotive thermal management applications.
Polyphenylsulfone is a high-performance amorphous thermoplastic with a glass transition temperature near 220°C, offering steam sterilization resistance, inherent flame retardancy, and hydrolytic stability across thousands of autoclave cycles. Resins command the deepest margin pools due to formulation complexity and regulatory qualification barriers, while medical devices represent the fastest-growing end user segment driven by reusable instrument mandates and infection control protocols. Membrane separation applications in water treatment and bioprocessing are expanding as polyphenylsulfone film and sheet formats displace less chemically resistant substrates.
FDA biocompatibility testing under ISO 10993 and EU MDR material traceability requirements shape product development timelines and customer qualification costs for all market participants. REACH compliance for residual monomer content and EPA emissions standards during polymerization constrain manufacturing location decisions and capital deployment. Stakeholders must monitor evolving sterilization validation protocols and regional healthcare procurement centralization as determinants of long-term contract viability and pricing power.
Market Dynamics
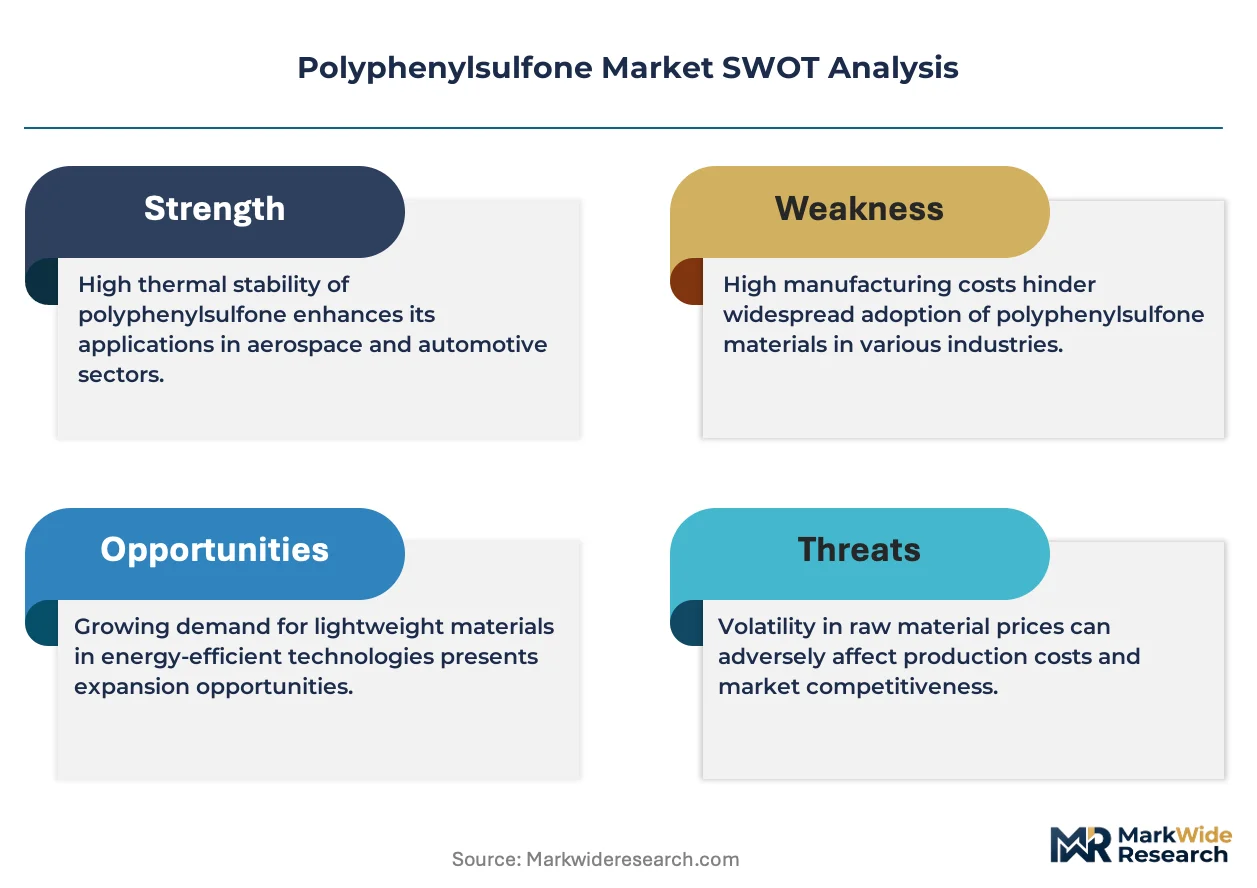
The polyphenylsulfone market is bifurcating sharply as EU MDR and FDA biocompatibility protocols force medical-grade resin qualification costs upward while industrial applications face margin compression from energy-intensive polymerization economics.
Growth Catalysts
- EU MDR material traceability mandates:Device OEMs in Germany and Switzerland are accelerating certified resin procurement to meet notified body audit requirements for reusable surgical instruments.
- Steam sterilization validation protocols:Hospital central sterile supply departments are specifying polyphenylsulfone for instrument trays exceeding 1,000 autoclave cycles.
- Membrane bioreactor expansion:Water treatment engineering firms are specifying polyphenylsulfone hollow fiber configurations for chlorine-resistant ultrafiltration modules.
Market Restraints
- Bisphenol S monomer cost volatility:Feedstock prices for sulfone monomer synthesis fluctuate with benzene and sulfur derivatives, compressing resin producer margins unpredictably.
- Specialty polymer supply concentration:High-purity resin production clusters in Belgium and Germany create geographic single-source risk for qualified medical device converters.
- Polyetherimide substitution in thermal management:Automotive underhood applications are migrating to lower-cost amorphous thermoplastics where continuous-use temperatures permit.
Strategic Opportunities
- Bioprocessing single-use systems:Cell culture bag film and connector manufacturers are qualifying polyphenylsulfone for gamma-stable fluid contact layers.
- India medical device manufacturing:CDSCO production-linked incentive schemes are attracting contract molding investment for export-oriented surgical instrument handles.
- Electrochemical hydrogen production:Alkaline electrolyzer stack manufacturers are evaluating polyphenylsulfone frames for caustic-resistant cell separation.
Industry Challenges
- ISO 10993-18 chemical characterization:Extractables and leachables testing timelines extend medical device qualification by 14-18 months, freezing working capital.
- Multi-site regulatory harmonization:Converters operating across FDA, EMA, and PMDA jurisdictions face divergent master file submission requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylsulfone Market |
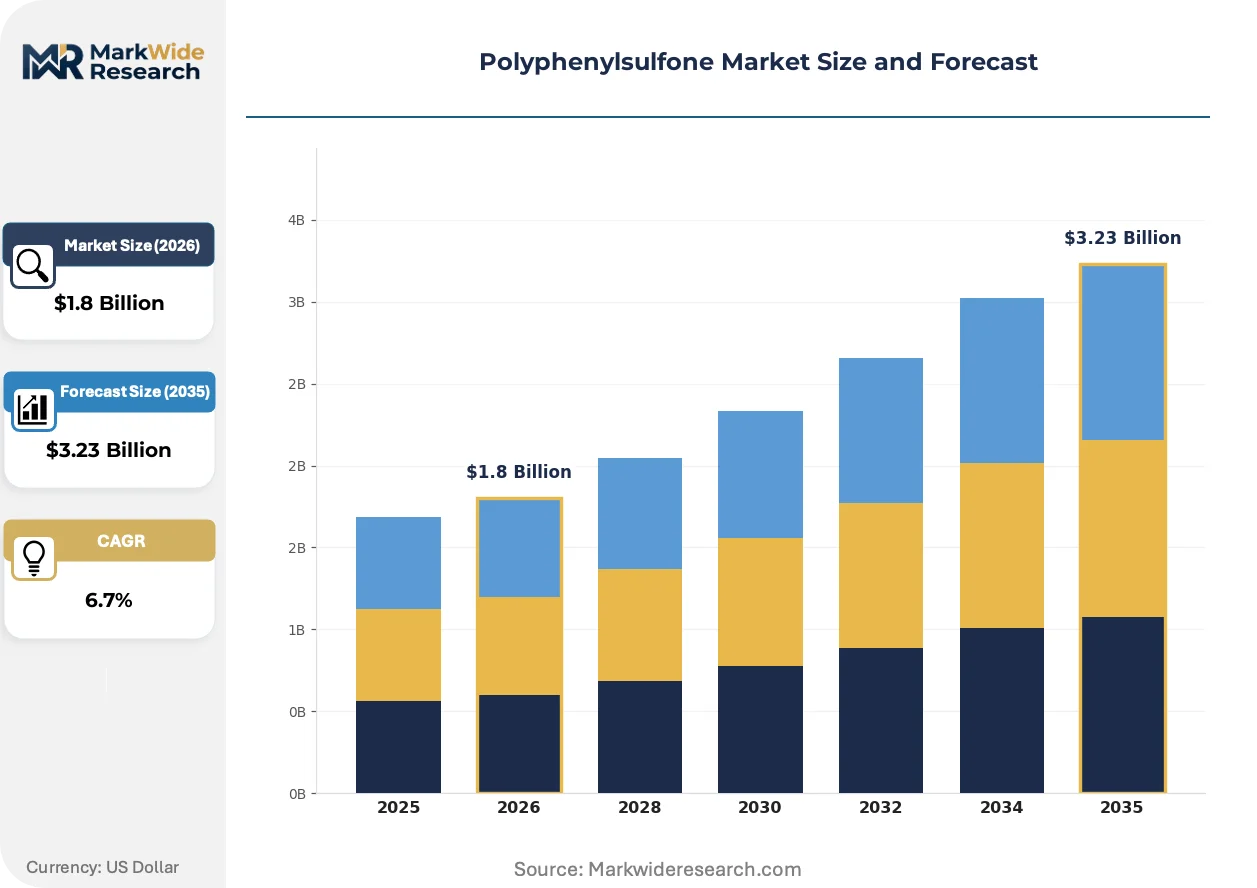
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Sheets, Films, Rods End User: Aerospace, Automotive, Medical Devices, Electronics Application: Fluids Transport, Electrical Insulation, Structural Components, Membrane Separation Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors |
| Companies Covered | Sumitomo Chemical Co., Ltd., RTP Company, Solvay S.A., Mitsubishi Chemical Advanced Materials, Ensinger GmbH, BASF SE, Evonik Industries AG, Quadrant AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylsulfone Market Emerging Trajectories
Polyphenylsulfone processing technology is advancing on three fronts: additive manufacturing feedstock development, regulatory chemistry disclosure automation, and procurement model restructuring toward resin-plus-validation bundled contracts.
High-temperature fused filament fabrication feedstock is overtaking machined stock shapes in custom surgical guide and patient-specific instrument prototyping. Medical device design houses in Massachusetts and Baden-Württemberg are adopting filament deposition for geometries impossible to mill from extruded rod. This additive pathway is compressing lead times from twelve weeks to seventy-two hours while expanding geometric freedom for complex lumen structures.
REACH Article 33 SCIP database requirements are forcing resin suppliers to automate supply chain communication of Substances of Very High Concern. ECHA compliance obligations now extend to article-level disclosure for medical devices containing sulfone polymers above 0.1% w/w. German compounders are deploying blockchain-anchored material passports to satisfy downstream OEM documentation demands without manual certificate exchange.
Hospital procurement consortia are consolidating sterilization tray purchasing through centralized tenders with embedded resin-grade specifications. Group purchasing organizations in France and the Netherlands are displacing distributor-mediated spot buying with multi-year direct agreements. This concentration is most visible in Benelux healthcare clusters, where single-source contracts now cover eighty percent of reusable instrument demand.
Polyphenylsulfone Market Segmentation
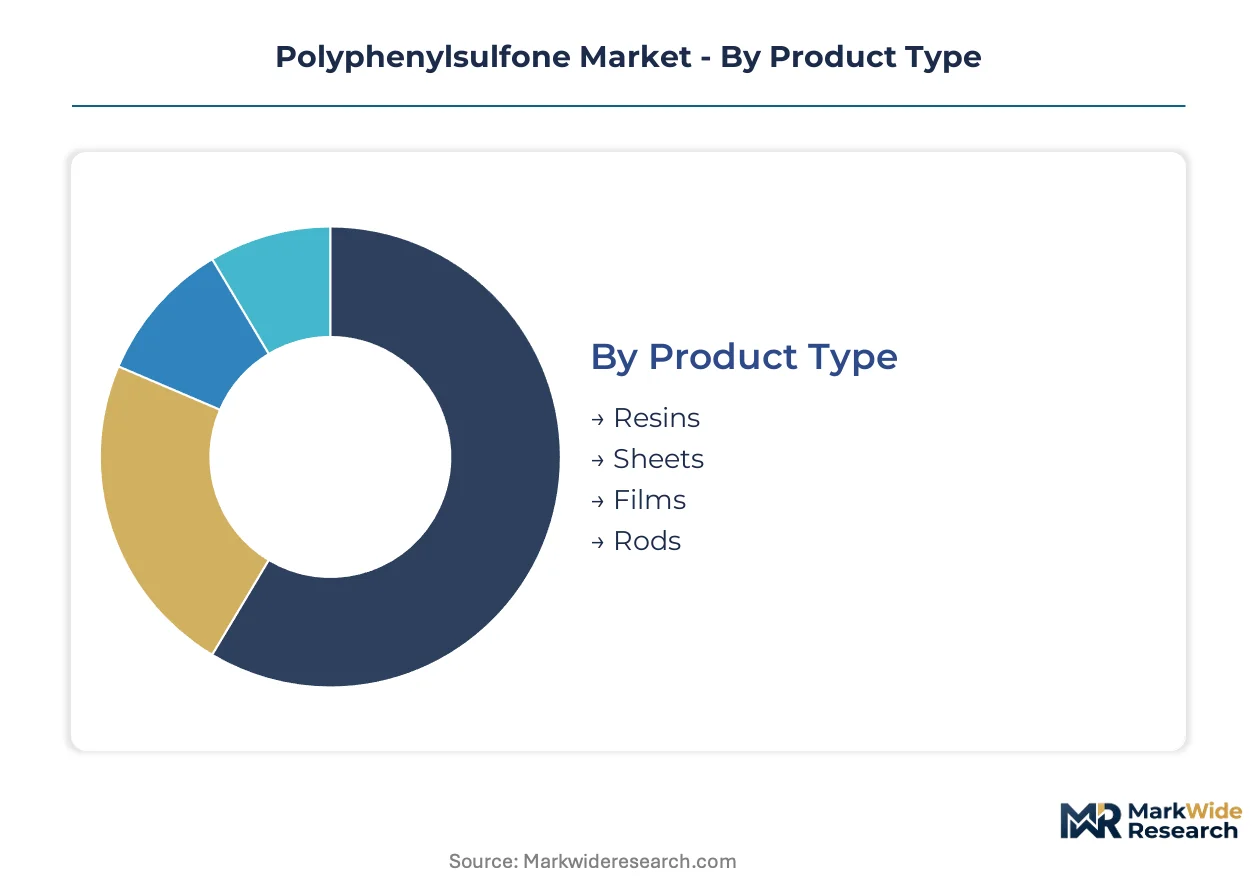
Polyphenylsulfone segmentation reveals how capital intensity and regulatory qualification barriers concentrate margin pools in specific product formats and end-use channels. Manufacturers allocate polymerization capacity and downstream processing assets based on divergent technical specifications and customer validation timelines.
Product Type:
Polymerization reactor scale and purification train complexity determine upfront capital requirements across product categories.
- Resins:Virgin pellet and compounded grades require continuous polymerization lines with residual monomer stripping columns and melt filtration systems. Medical-grade resin qualification under FDA master files and EU MDR technical documentation absorbs the majority of new capital deployment in Belgium and Germany.
- Sheets:Compression-molded and extruded plate formats serve semiconductor equipment and food processing machinery with lower regulatory barriers than medical resins. Demand clusters in precision thickness tolerances for vacuum chamber linings.
- Films:Cast and blown film extrusion for membrane substrates and electrical insulation.
- Rods:Solid extruded stock shapes for machining into surgical instrument handles and fluid handling connectors.
Resins absorb the bulk of installed capacity; films are expanding most quickly.
End User:
Customer qualification intensity and contract duration vary sharply across industrial and healthcare applications.
- Medical Devices:Reusable surgical instruments, sterilization trays, and fluid handling manifolds command premium pricing through ISO 10993 biocompatibility certification. German hospital procurement consortia are consolidating sterilization tray purchasing through multi-year direct agreements with specified resin grades.
- Aerospace:Interior panels, cable insulation, and structural brackets leverage inherent flame retardancy without additives. FAA flammability testing under 14 CFR 25.853 drives material selection for cabin applications.
- Automotive:Thermal management components and underhood electrical connectors.
- Electronics:Semiconductor process equipment and high-temperature connector housings.
Medical devices dominate revenue contribution; aerospace is gaining share fastest.
Application:
Performance requirements for chemical resistance and thermal stability dictate formulation complexity and processing method selection.
- Membrane Separation:Hollow fiber and flat-sheet configurations for water treatment ultrafiltration and bioprocessing microfiltration. Chlorine tolerance and steam sterilizability displace polyethersulfone in municipal water reuse plants.
- Fluids Transport:Piping, fittings, and manifolds for aggressive chemical handling in semiconductor fabs and pharmaceutical manufacturing. Welding and bonding protocols for high-purity systems require specialized training and validation.
- Electrical Insulation:Wire coating and connector housings for high-temperature service.
- Structural Components:Machined brackets, housings, and support structures.
Membrane separation captures the steepest expansion trajectory; fluids transport holds the largest installed base.
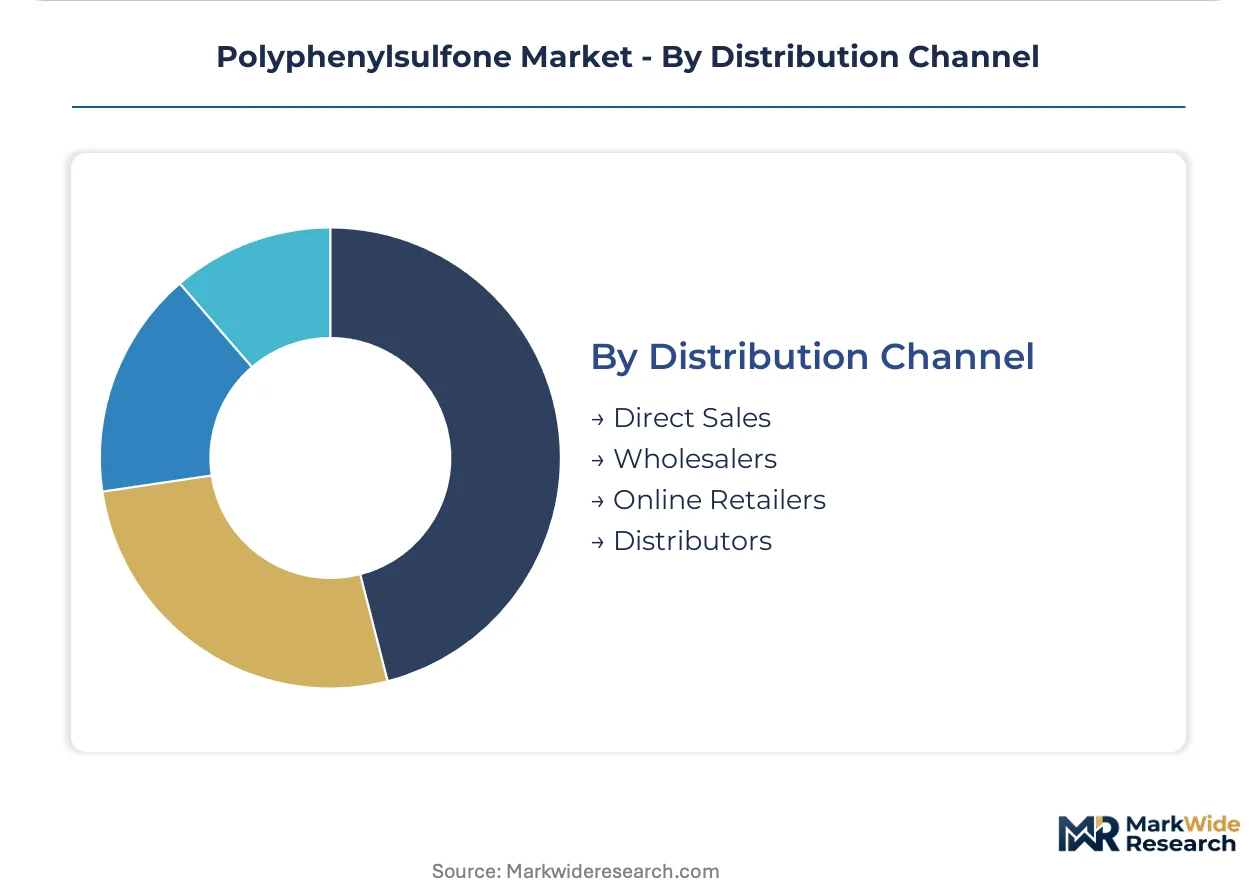
Distribution Channel:
Customer scale and specification complexity determine channel economics and service requirements.
- Direct Sales:Multi-year supply agreements with medical device OEMs and aerospace tier-1 suppliers include embedded technical service and regulatory documentation. Solvay S.A. and Ensinger GmbH operate direct sales organizations for qualified resin and stock shape procurement.
- Distributors:Regional warehousing and cut-to-size services for job shops and smaller OEMs. Medical device converters in Baden-Württemberg rely on distributor inventory buffers to manage ISO 10993 requalification timelines.
- Wholesalers:Volume aggregation for industrial-grade sheets and rods.
- Online Retailers:Catalog sales of standard stock shapes and small-batch resins.
Direct sales command the highest margin structure; distributors handle the greatest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg anchors European polyphenylsulfone demand through its precision medical device manufacturing corridor. The state's surgical instrument clusters drive certified resin consumption for reusable sterilization trays and fluid handling manifolds.
Germany
Ensinger GmbH and Solvay S.A. concentrate high-purity resin production in southwestern industrial zones serving EU MDR-qualified medical device OEMs. REACH Article 33 SCIP database compliance forces automated supply chain documentation for Substances of Very High Concern. Stuttgart-based procurement consortia now control eighty percent of reusable surgical instrument contracts through multi-year direct agreements.
United States
FDA biocompatibility protocols under ISO 10993-18 extend medical device qualification timelines, freezing working capital for fourteen to eighteen months. Massachusetts design houses adopt high-temperature fused filament fabrication for patient-specific surgical guides. EPA emissions standards during polymerization constrain new capacity deployment decisions.
Japan
PMDA master file submission requirements diverge from FDA and EMA protocols, complicating multi-site regulatory harmonization for converters. METI standards support membrane bioreactor expansion for chlorine-resistant ultrafiltration in municipal water reuse. Osaka-area engineering firms specify polyphenylsulfone hollow fiber configurations for industrial filtration modules.
India
CDSCO production-linked incentive schemes attract contract molding investment for export-oriented surgical instrument handles. BIS certification requirements shape resin import qualification for domestic medical device manufacturing. Maharashtra-based healthcare procurement centralization drives sterilization tray standardization for hospital networks.
Belgium
Specialty polymer supply concentration creates geographic single-source risk for qualified medical device converters across European markets. ECHA residual monomer content regulations govern polymerization plant operations. Antwerp-area chemical processing infrastructure supports captive sulfone monomer synthesis for integrated resin production.
Polyphenylsulfone Market Vendor Landscape
Premium-margin players sit above commodity-margin players across regulatory qualification intensity and resin purity tiers. The market structure concentrates around vertically integrated sulfone polymer platforms and precision extrusion specialists serving ISO 10993-certified channels. Three archetypes dominate: integrated resin producers with FDA master file portfolios, precision stock shape extruders for medical machining, and diversified engineering plastics distributors extending sulfone access into industrial thermal management. Capacity expansion and regulatory chemistry disclosure automation represent the dominant competitive moves.
Within the integrated resin tier, Solvay S.A. exemplifies premium positioning through its vertically organized sulfone polymer platform. Ensinger GmbH anchors the precision extrusion archetype from its southwestern German base. BASF SE occupies the diversified distribution position, extending sulfone access through broad engineering plastics channels. These three structures illustrate how geographic origin and organizational form map to distinct margin pools and customer qualification pathways.
| Leading Market Players |
|---|
| Sumitomo Chemical Co., Ltd. |
| RTP Company |
| Solvay S.A. |
| Mitsubishi Chemical Advanced Materials |
| Ensinger GmbH |
| BASF SE |
| Evonik Industries AG |
| Quadrant AG |
| SABIC |
| Others |
Supply Flow & Price Mechanics
German hospital procurement consortia and aerospace tier-1 suppliers command pricing power through multi-year direct agreements that embed certified resin-grade specifications and sterilization validation documentation. These concentrated buyer archetypes extract value-based premiums from suppliers while pushing volume commitments onto compounders in Belgium and southwestern Germany.
Pricing Analysis
Steam sterilization cycle throughput anchors value-based pricing for medical-grade polyphenylsulfone resins, with contracts benchmarking cost per validated autoclave cycle rather than per-kilogram material cost. Pricing stratifies across ISO 10993-certified premium grades, industrial-standard extrusion grades, and commodity sheet formats. Cost compression in industrial sheet tiers intensifies as polyetherimide substitutes erode thermal management applications. Medical device OEMs exhibit the lowest price sensitivity due to regulatory requalification barriers, while automotive procurement teams drive hardest bargain hunting.
Supply Chain Analysis
Refurbishment flows for reusable surgical instruments and sterilization trays create reverse-logistics value pools that resin suppliers capture through take-back programs for end-of-life medical devices. Virgin resin production concentrates in Belgium, Germany, and the United States, drawing from bisphenol S monomer synthesis and sulfur derivative feedstocks. Single-source vulnerability runs through Antwerp-area polymerization clusters qualified under FDA master files. Distribution runs through direct sales organizations for medical OEMs and regional distributors for industrial job shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory qualification intensity, with ISO 10993-18 chemical characterization timelines and EU MDR material traceability mandates forcing sub-scale compounders toward exit or acquisition.
For Market Incumbents: Cement dominance by deepening captive control over sulfone monomer synthesis in Belgium and accelerating blockchain-anchored material passport deployment for REACH Article 33 compliance. Defend against polyetherimide substitution in automotive thermal management by locking aerospace tier-1 suppliers into multi-year direct agreements with embedded flammability certification. For New Entrants and Emerging Players: Additive manufacturing feedstock development offers the most penetrable wedge, with high-temperature fused filament fabrication for patient-specific surgical guides in Massachusetts and Baden-Württemberg outpacing incumbent response times. Target India's CDSCO production-linked incentive schemes for contract molding of export-oriented surgical instrument handles, leveraging lower qualification overhead for non-EU MDR markets. For Investors and Strategic Acquirers: The window for entry favors vertically organized resin producers with FDA master file portfolios and established EU MDR technical documentation. Long-term viability hinges on regulatory chemistry disclosure automation and sterilization validation bundling. Monitor ECHA SCIP database enforcement intensity and hospital procurement consortia tender consolidation as inflection signals for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfone Monomer Synthesis | Captive bisphenol S supply in Antwerp insulates margin pools from benzene derivative volatility. |
| Blockchain-Anchored Material Passport Deployment | Automated REACH Article 33 disclosure satisfies German OEM documentation demands without manual exchange. |
| High-Temperature Fused Filament Fabrication Launch | Seventy-two-hour prototyping lead times in Massachusetts compress twelve-week machined shape cycles. |
| Multi-Year Direct Agreement Restructuring | Stuttgart procurement consortia now cover eighty percent of reusable instrument demand through single-source contracts. |
| India Contract Molding Footprint Establishment | CDSCO production-linked incentives attract export-oriented surgical instrument handle manufacturing in Maharashtra. |
Methodological Framework
Independent corroboration across resin plant managers, medical device procurement leads at German OEMs, distribution channel partners, and ECHA regulatory affairs specialists underwrites the qualitative findings. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, Cefic specialty polymer reports, and customs trade data. Bottom-up capacity utilization estimates and top-down end-use demand modeling triangulate volume figures.
Historical reference periods spanning pre- and post-EU MDR implementation anchor the projection horizon, with growth trajectories derived from sterilization tray procurement expansion and membrane bioreactor adoption curves. Segmentation dimensions span resin grade tier, medical versus industrial end-use, hollow fiber versus flat-sheet membrane format, and regional regulatory cluster. CAGRs reflect installed base turnover rates and qualification timeline elasticity across FDA, EMA, and PMDA jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under bisphenol S monomer cost spikes and REACH residual monomer content enforcement shifts. Practitioners should monitor ECHA SCIP database compliance deadlines and German hospital procurement consortia tender awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Elastic Films Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Light Diffusion Materials Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Conductive Fluted Sheets Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market