
 UK Lab-Grown Diamonds Market | 2026-2036
UK Lab-Grown Diamonds Market Size, Share, and Industry Trends Forecast 2026-2036
UK Lab-Grown Diamonds Market Analytics
Carbon-based crystalline structures are broadening access to gem-quality stones once reserved for mined supply chains. Diamond Foundry leverages in-house production of CVD rough to control quality from seed to polished stone. Pure Lab Diamonds anchors its position through direct-to-consumer channels that bypass traditional wholesale markups. KIRA differentiates via bespoke design services targeting ethically motivated purchasers.
Lab-grown diamonds are synthetic crystalline carbon materials produced through chemical vapour deposition or high-pressure high-temperature methods, achieving identical optical, physical and chemical properties to natural diamonds at typically lower carat prices. These stones serve commercial purposes spanning ornamental jewellery, industrial cutting tools, thermal management substrates and quantum sensing applications. The product type dimension shows gemstones capturing dominant volume share while industrial applications yield steadier contract-based revenue. Technology segmentation reveals CVD leading in larger stone production where clarity grades matter most, whereas HPHT retains cost advantages in smaller melee sizes.
The UK's Competition and Markets Authority enforces strict advertising standards on gem origin claims, compelling retailers to maintain auditable chain-of-custody documentation. BSI Group's ISO certification schemes for jewellery supply chains shape procurement criteria among major British retailers and export-oriented manufacturers. HMRC's rules of origin classification for synthetic stones affect cross-border tariff treatment and inventory valuation. Stakeholders must weigh CVD capacity expansion against HPHT yield economics while monitoring regulatory developments around carbon footprint labelling requirements.
Market Dynamics
The UK's Competition and Markets Authority has intensified enforcement on diamond origin claims, forcing retailers to rebuild supply chain documentation systems or face penalties. This regulatory pressure intersects with shifting bridal jewellery preferences toward certified lab-grown alternatives.
Growth Catalysts
- London's luxury retail corridor:Concentrated high-net-worth demand creates showroom visibility that accelerates consumer education and trial rates among England's bridal segment.
- CVD technology maturation:Larger stone production capabilities now deliver clarity grades matching premium mined equivalents, satisfying certification requirements from BSI Group's ISO schemes.
- Manchester manufacturing hub:Industrial diamond tool producers secure contract-based revenue streams that stabilize capacity utilization for synthetic rough suppliers.
Market Restraints
- Energy input volatility:CVD growth chambers require sustained high-temperature plasma environments, exposing producers to electricity tariff fluctuations.
- HPHT melee concentration:Smaller stone production remains concentrated among Asian supply bases, creating import dependency for British jewellery manufacturers.
- Mined diamond substitution threat:Natural stone prices adjust downward in response to synthetic penetration, compressing the price gap that drives lab-grown value propositions.
Strategic Opportunities
- Scotland's underpenetrated bridal market:Edinburgh and Glasgow retail networks show lower synthetic diamond penetration than England, presenting first-mover positioning potential.
- Carbon footprint labelling mandates:Anticipated HMRC rules on environmental disclosure would reward producers with verified low-emission growth processes.
- Quantum sensing applications:Nitrogen-vacancy centers in synthetic diamond substrates converge with UK university research clusters pursuing next-generation magnetometry devices.
Industry Challenges
- Gemological certification bottlenecks:Independent laboratory capacity constraints in London delay grading turnaround times, frustrating direct-to-consumer fulfilment models.
- Legacy inventory revaluation:Retailers holding mined diamond stock face balance sheet adjustments as synthetic alternatives reset consumer price expectations.
- Cross-border tariff complexity:HMRC's rules of origin classification for synthetic stones create valuation disputes that disrupt just-in-time inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Lab-Grown Diamonds Market |
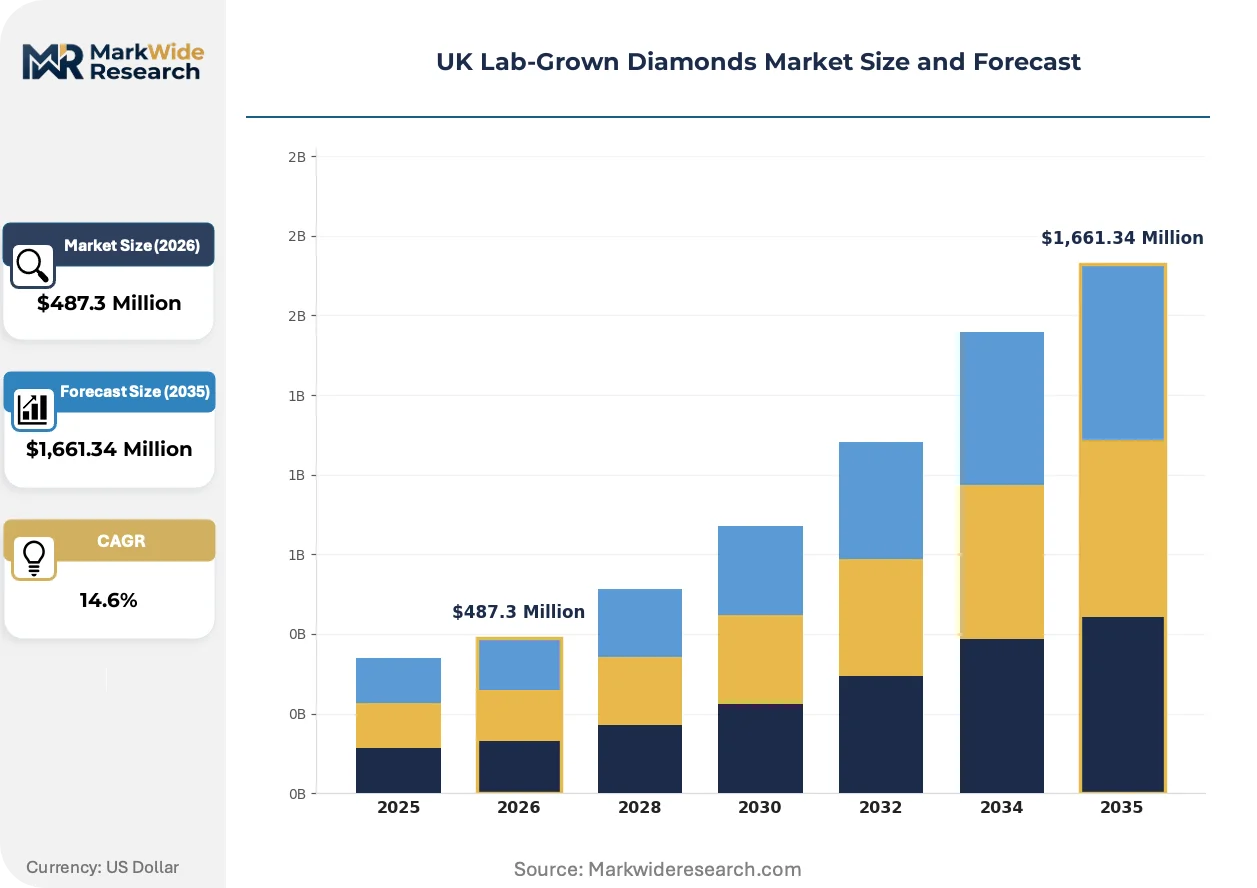
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gemstones, Jewelry, Industrial Applications, Cut Stones End User: Retail Consumers, Jewelers, Manufacturers, Designers Technology: CVD, HPHT, Diamaond Nano, Laser Scribing Distribution Channel: Online, Direct Sales, Retail Stores, Trade Shows |
| Companies Covered | Pure Lab Diamonds, KIRA, Asteria Diamonds, Brilliant Earth, Diamond Foundry, Synthetic Diamond Company, Green Rocks Diamonds, ALTR Created Diamonds, De Beers Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Lab-Grown Diamonds Market Evolving Landscape
Technology convergence and regulatory stringency are redefining how synthetic stones move from production to purchase, with implications for every layer of the UK value chain.
Chemical vapour deposition systems are expanding into larger stone formats previously dominated by mined supply. Bridal jewellers in England's southeast now specify CVD-origin diamonds above two carats for solitaire settings. The technology is compressing traditional wholesale markups as producers integrate polishing operations.
BSI Group's ISO certification schemes for jewellery supply chains now shape procurement criteria among major British retailers. The standard mandates auditable chain-of-custody documentation from growth facility to point of sale. Luxury department stores in London's Bond Street district have restructured supplier onboarding to comply.
Bridal buyers now prioritize third-party verification over brand heritage when selecting engagement stones. Direct-to-consumer channels capture preference share from traditional wholesale-retail pathways. Manchester's manufacturing hub reports accelerating orders from digitally native brands that bypass conventional distribution tiers.
UK Lab-Grown Diamonds Market Segmentation
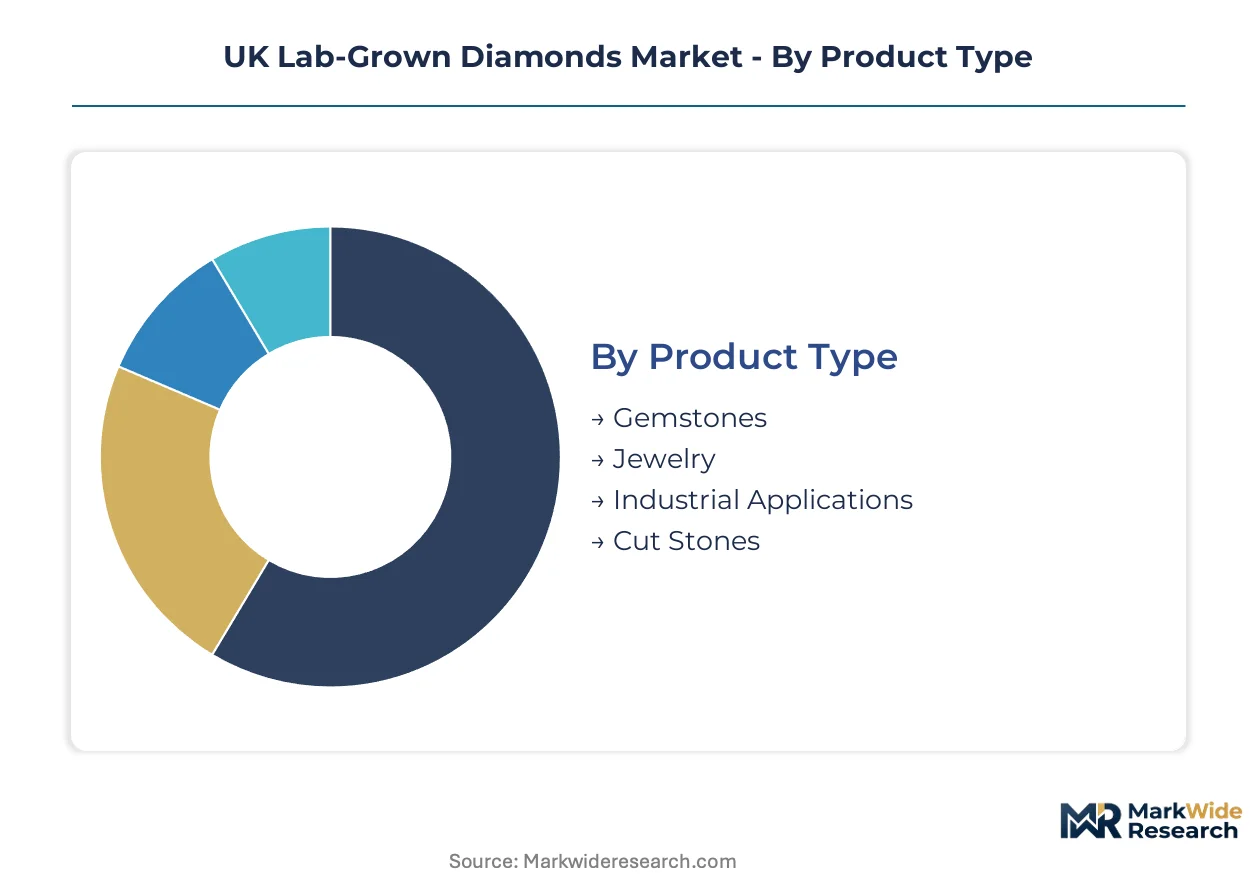
Segmentation in the UK lab-grown diamonds market reveals how production technology, buyer sophistication, and channel economics fragment demand across distinct commercial pathways. Each axis carries regulatory and margin implications that shape competitive positioning.
Technology:
CVD and HPHT growth methods diverge in capital intensity, energy consumption, and stone size capabilities, creating tiered supply economics for British buyers.
- CVD:Chemical vapour deposition builds diamond crystals through plasma-enhanced carbon gas precipitation, achieving exceptional clarity in stones above two carats. London's bridal jewellers specify CVD-origin diamonds for solitaire settings where certification from BSI Group's ISO schemes matters most. Energy input costs from sustained high-temperature plasma environments expose producers to electricity tariff volatility.
- HPHT:High-pressure high-temperature replication of natural diamond formation conditions delivers cost advantages in smaller melee sizes below 0.5 carats. Manchester's manufacturing hub sources HPHT rough for industrial cutting tools where thermal conductivity outweighs optical perfection. Import dependency on Asian supply bases creates inventory risk for British jewellery manufacturers.
- Diamond Nano:Engineered nanocrystalline structures serve quantum sensing substrates and thermal management applications with precise dimensional control.
- Laser Scribing:Post-growth inscription technology enables traceability marking without compromising gem structural integrity.
Mature deployment sits with HPHT for industrial contract volumes. Newer deployment is concentrated in CVD for certified gemstone applications.
Product Type:
Application-driven segmentation separates ornamental demand from functional industrial procurement, with divergent margin profiles and certification requirements.
- Gemstones:Faceted stones for jewellery settings command premium pricing contingent on third-party grading verification. Retail consumers in England's southeast prioritize certified lab-grown alternatives over mined equivalents for engagement purchases.
- Jewelry:Finished pieces incorporating lab-grown stones bypass traditional wholesale markups through direct-to-consumer channels. Edinburgh and Glasgow retail networks show underpenetrated bridal demand compared to England.
- Industrial Applications:Cutting tools, thermal substrates, and abrasive materials yield steadier contract-based revenue with less price volatility than gem markets. Manchester's tool producers secure long-term supply agreements stabilizing capacity utilization.
- Cut Stones:Polished rough from integrated growth facilities compresses traditional distribution tiers, capturing margin previously allocated to wholesale intermediaries.
Volume concentration rests with Industrial Applications. Value expansion is climbing the fastest in Gemstones.
End User:
Buyer sophistication ranges from individual consumers seeking ethical verification to manufacturers optimizing raw material specifications.
- Retail Consumers:Individual purchasers prioritize third-party certification over brand heritage when selecting engagement stones, driving direct-to-channel preference share.
- Jewelers:Independent and chain retailers rebuild supply chain documentation systems to satisfy the Competition and Markets Authority's tightened origin disclosure guidance.
- Manufacturers:Industrial tool producers in Manchester's hub specify thermal conductivity and hardness tolerances for cutting tool applications.
- Designers:Bespoke creators source verified low-emission growth processes in anticipation of HMRC carbon footprint labelling mandates.
Procurement volume concentrates with Manufacturers. Margin expansion is gaining share fastest among Designers.
Distribution Channel:
Channel economics determine how synthetic stones traverse from growth facility to end buyer, with implications for documentation burden and price transparency.
- Online:Digital native brands bypass conventional distribution tiers, accelerating consumer education through targeted transparency messaging.
- Direct Sales:Producer-to-buyer relationships capture margin compression benefits while maintaining auditable chain-of-custody documentation required by BSI Group standards.
- Retail Stores:Physical showrooms in London's Bond Street district restructure supplier onboarding to comply with Competition and Markets Authority enforcement.
- Trade Shows:Industry gatherings facilitate bulk procurement relationships for Manchester manufacturers securing industrial rough supply.
Established volume flows through Retail Stores. Channel shift is expanding most quickly in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's southeast corridor concentrates the highest bridal jewellery demand, with London's luxury retail network driving consumer education and trial rates for certified alternatives. Scotland and Wales present underpenetrated opportunities where synthetic stone awareness lags southern markets.
London and the Southeast
High-net-worth consumers in Bond Street showrooms specify CVD-origin stones above two carats for solitaire engagement settings. The Competition and Markets Authority's tightened origin disclosure guidance forces retailers here to rebuild auditable supply chain documentation systems. Canary Wharf financial services professionals accelerate direct-to-channel adoption through digitally native brands.
Midlands
Manufacturing tool producers in Birmingham's industrial corridor secure contract-based revenue from HPHT rough supply for cutting applications. HMRC's rules of origin classification for synthetic stones create valuation disputes that disrupt just-in-time inventory management for exporters. Leicester's jewellery manufacturing heritage supports secondary polishing operations for integrated growth facilities.
North England
Manchester's manufacturing hub anchors industrial diamond demand for thermal management substrates and abrasive materials. BSI Group's ISO certification schemes shape procurement criteria among tool producers seeking verified chain-of-custody documentation. Sheffield's advanced materials research clusters converge with synthetic diamond substrate development for quantum sensing applications.
Scotland
Edinburgh and Glasgow retail networks show lower synthetic diamond penetration than comparable English cities, presenting first-mover positioning potential for certified stone distributors. Scottish bridal buyers increasingly prioritize third-party verification over traditional brand heritage when selecting engagement stones. Aberdeen's energy sector engineering firms source industrial diamond cutting tools for offshore equipment maintenance.
Wales
Cardiff's emerging design community attracts bespoke jewellers targeting ethically motivated purchasers with verified low-emission growth process documentation. Swansea's manufacturing base supplies precision cutting tools to aerospace contractors requiring thermal conductivity specifications. Welsh retailers anticipate HMRC carbon footprint labelling mandates by restructuring supplier onboarding protocols.
UK Lab-Grown Diamonds Market Competitive Landscape
Capacity expansion dominates the current landscape as producers integrate polishing operations to capture margin previously allocated to wholesale intermediaries. The vendor base clusters around three strategic archetypes: vertically integrated growth-to-retail operators, direct-to-consumer digital natives, and legacy mined diamond houses with synthetic product lines. Technology licensing agreements and geographic expansion into underpenetrated regional markets represent the two dominant competitive moves reshaping positioning.
Among integrated production specialists, Diamond Foundry exemplifies the growth-to-polished-stone archetype through in-house CVD rough manufacturing. Pure Lab Diamonds anchors the direct-to-consumer tier with digital-first distribution bypassing traditional wholesale markups. KIRA occupies a position within the bespoke design segment, targeting ethically motivated purchasers with customized certification services.
| Leading Market Players |
|---|
| Pure Lab Diamonds |
| KIRA |
| Asteria Diamonds |
| Brilliant Earth |
| Diamond Foundry |
| Synthetic Diamond Company |
| Green Rocks Diamonds |
| ALTR Created Diamonds |
| De Beers Group |
| Others |
Value Network & Pricing Analysis
Bridal jewellers in England's southeast corridor anchor UK demand for certified CVD-origin stones above two carats, driving a three-tier pricing structure across premium, standard, and economy levels tied to BSI Group certification grades. This buyer concentration compresses wholesale markups as integrated producers capture margin through direct-to-consumer channels.
Pricing Analysis
Volume concentrates in smaller HPHT melee sizes where Asian supply bases compete on unit economics, while margin expansion accrues to larger CVD gemstones with third-party grading verification. Price differentiation hinges on certification tier from BSI Group's ISO schemes and clarity grades matching premium mined equivalents. Cost compression in the standard tier intensifies as natural stone prices adjust downward, narrowing the value proposition gap. Retail consumers show highest price sensitivity in sub-one-carat purchases, whereas high-net-worth buyers in London's Bond Street district exhibit elasticity for solitaire settings with full documentation.
Supply Chain Analysis
HMRC's rules of origin classification for synthetic stones reshape sourcing protocols, compelling British retailers to maintain auditable chain-of-custody documentation from growth facility to point of sale. Rough supply draws from India, China, and Singapore for HPHT melee, while CVD rough increasingly sources from integrated European and North American facilities with verified low-emission processes. Import dependency on Asian supply bases creates single-source vulnerability for smaller stone procurement. Distribution runs through direct-to-consumer digital channels and restructured retail showrooms in London's luxury corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK lab-grown diamonds market represents a consolidation play as the Competition and Markets Authority's tightened origin disclosure guidance forces smaller retailers to rebuild documentation systems or exit.
For Market Incumbents: Acquire gemological certification capacity in London to circumvent independent laboratory bottlenecks delaying grading turnaround times. Secure backward integration into CVD growth facilities to control quality from seed to polished stone and defend against emerging digitally native brands bypassing wholesale tiers. Prioritise BSI Group ISO scheme compliance as a barrier to entry against undercapitalised competitors. For New Entrants and Emerging Players: Begin with Scotland's underpenetrated bridal market where Edinburgh and Glasgow retail networks show lower synthetic diamond awareness than comparable English cities. Target bespoke design services for ethically motivated purchasers seeking verified low-emission growth process documentation, leveraging direct-to-consumer transparency messaging to build trust without legacy brand heritage. For Investors and Strategic Acquirers: The window for entry favours vertically integrated growth-to-retail operators with captive CVD capacity and established certification relationships. Long-term viability hinges on positioning ahead of anticipated HMRC carbon footprint labelling mandates that would reward producers with auditable low-emission processes. Watch for inflection signals in quantum sensing substrate development converging with Sheffield's advanced materials research clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CVD Growth | In-house rough production captures margin from seed to polished stone while ensuring BSI Group certification compliance. |
| Direct-to-Consumer Channel Expansion | Digital native brands bypass wholesale markups and accelerate transparency messaging to ethically motivated bridal buyers. |
| Carbon Footprint Verification Program | Anticipated HMRC environmental disclosure rules would reward producers with documented low-emission growth processes. |
| Scotland Market Entry | Edinburgh and Glasgow retail networks present first-mover positioning potential with lower synthetic penetration than England. |
| Quantum Sensing Substrate Development | Nitrogen-vacancy centers in synthetic diamond converge with Sheffield research clusters pursuing magnetometry applications. |
Research Methodology
Trade databases, BSI Group certification registries, and HMRC customs classifications formed the secondary backbone, supplemented by primary interviews with CVD growth facility operators, independent gemological laboratory directors, bridal jewellery procurement managers at London department stores, and Manchester industrial tool manufacturers. The analysis triangulates bottom-up capacity estimates from named growth facilities against top-down demand projections from retail channel audits.
Historical trendline analysis of CVD and HPHT capacity deployment patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include production technology, product type, end user sophistication, and distribution channel economics. CAGRs derive from fitted growth curves adjusted for regulatory enforcement intensity and technology maturation timelines, with specific inputs from electricity tariff volatility and certification capacity constraints.
Underlying measurement precision varies by segment; gemstone applications with third-party grading carry tighter precision than industrial contract volumes. Forecasts reflect documented assumptions about CVD technology adoption curves and regulatory implementation timelines. Anticipated carbon footprint labelling mandates and natural stone price adjustments represent primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Open Cell Foam Market
Specialty Materials
Barium Borate Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Nanoencapsulation Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
PVB Interlayers Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Global PMMA Microspheres Market