
 Compostable Cotton Swab Market | 2026-2036
Compostable Cotton Swab Market Size, Share, and Industry Trends Forecast 2026-2036
Compostable Cotton Swab Market Insights
Asset-light contract manufacturing is reshaping who can compete in compostable cotton swabs. Unilever leverages its global procurement scale to source FSC-certified bamboo at volume. Groupe Lemoine anchors European production with vertically integrated stick-forming operations in France. The Humble Co. differentiates through pharmacy-exclusive distribution and plastic-negative packaging claims.
Compostable cotton swabs replace petroleum-based plastic stems with bamboo, paper, or certified bioplastic alternatives designed to break down in industrial composting facilities within 90 to 180 days. The product serves personal hygiene, cosmetic application, and medical specimen collection where single-use sterility remains non-negotiable. Bamboo stick variants command the widest retail placement due to supply chain maturity and consumer familiarity with the material. Medical care applications generate tighter margin pools because ISO 13485 compliance and sterilization validation raise barriers to entry. Eco-friendly wrapping formats are gaining fastest among direct-to-consumer channels where unboxing sustainability influences repeat purchase rates.
REACH restricts persistent organic pollutants in imported bamboo treatments. The EU Green Deal pushes member states toward extended producer responsibility for single-use hygiene articles. FDA regulates medical-grade swabs through quality system requirements that compostable entrants must satisfy. Stakeholders should monitor whether industrial composting infrastructure expansion outpaces product certification timelines.
Market Dynamics
Extended producer responsibility mandates under the EU Green Deal are forcing swab manufacturers to redesign supply chains around certified compostable materials, while REACH compliance requirements for bamboo treatments create certification bottlenecks that favor scaled producers.
Growth Catalysts
- REACH-compliant material mandates:ECHA enforcement of persistent organic pollutant restrictions in imported bamboo accelerates substitution of conventional plastic stems across European personal care aisles.
- Industrial composting infrastructure:Facility expansion in Germany and France enables verified end-of-life claims that retail buyers now require for shelf placement.
- Drugstore chain de-stocking policies:dm-drogerie markt and Rossmann elimination of plastic-stemmed alternatives concentrates demand for certified compostable variants.
Market Restraints
- FSC-certified bamboo supply concentration:Sourcing from certified plantations in Zhejiang and Anhui provinces creates geographic dependency and harvest-season volatility.
- ISO 13485 sterilization validation costs:Medical-grade compliance requires gamma irradiation facilities that compostable entrants lack, blocking higher-margin specimen collection applications.
- Industrial composting access gaps:Home composting incompatibility limits consumer value proposition in regions without municipal organic waste collection.
Strategic Opportunities
- Pharmacy-exclusive distribution channels:Apotheke networks in Austria and Switzerland offer premium positioning with lower slotting fees than mass retail.
- Plastic-negative packaging certification:Partnerships with rePurpose Global enable quantified ocean plastic recovery claims that direct-to-consumer brands leverage for subscription retention.
- EU Green Deal extended producer responsibility expansion:Pending inclusion of single-use hygiene articles in national EPR schemes will mandate compostable formats by default.
Industry Challenges
- ISO 17025 laboratory certification timelines:Third-party compostability verification by TÜV or DIN CERTCO requires 6-12 month validation cycles that delay product launches.
- Stick-forming equipment retooling:Conversion from plastic injection molding to bamboo fiber compression demands capital expenditure that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compostable Cotton Swab Market |
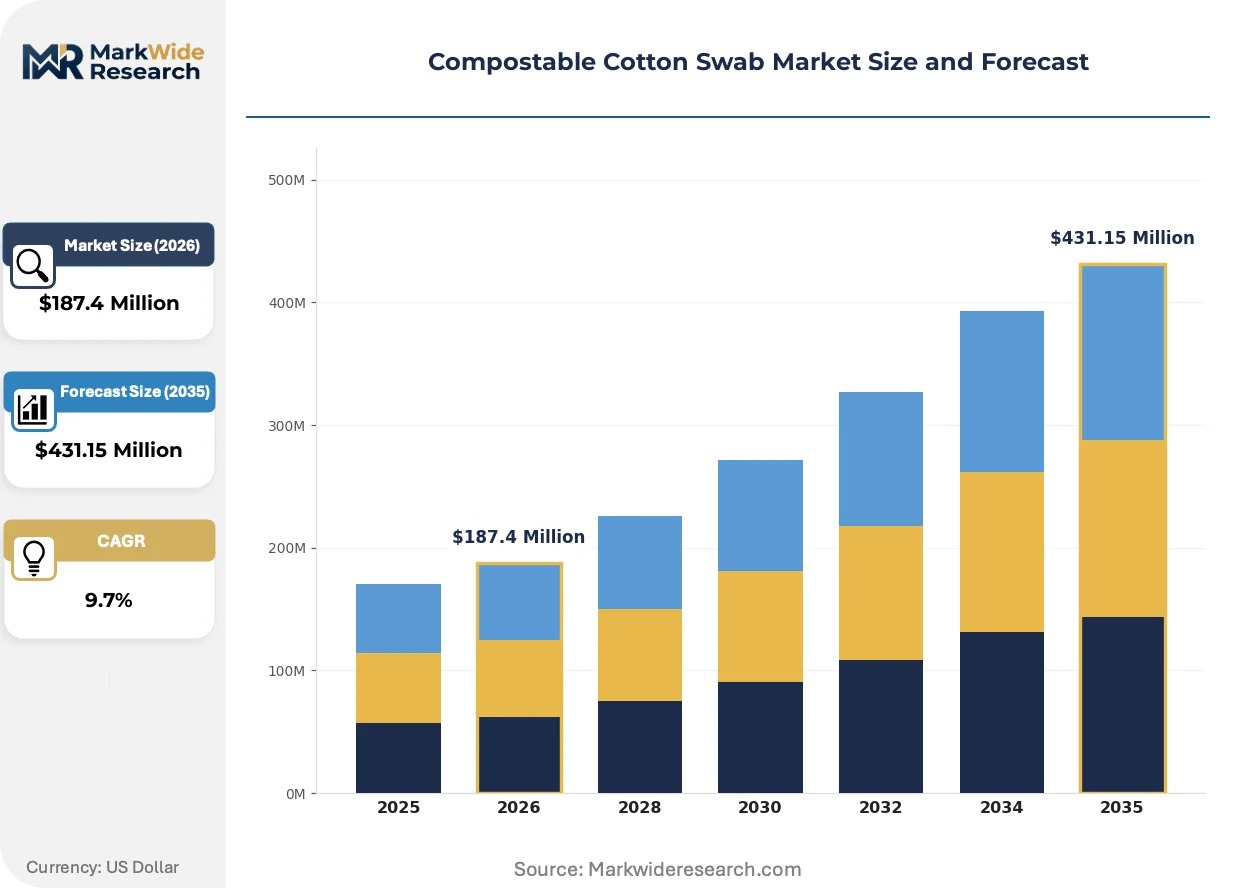
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton Tip, Bamboo Stick, Paper Stick, Bioplastic Stem Application: Personal Care, Medical Care, Infant Care, Industrial Cleaning End User: Pharmacies, Specialty Clinics, Baby Care Centers, Manufacturing Units Packaging Type: Box Pack, Blister Pack, Bulk Packaging, Eco-friendly Wrapping |
| Companies Covered | Q-tips, Unilever, Groupe Lemoine, Sanyo Co., Ltd., Hydrophil, The Humble Co., Jieyang Top-Tip's Daily Use Products, Puritan Medical Products, LastObject, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compostable Cotton Swab Market Trends and Innovations
Digital traceability systems are penetrating compostable cotton swab supply chains, enabling batch-level certification verification that retail procurement teams now mandate. Material science advances in fiber binding and moisture resistance are expanding application scope beyond cosmetic use.
Blockchain-enabled supply chain tracking is digitizing provenance documentation for FSC-certified bamboo sticks. dm-drogerie markt and Douglas now require QR-code-accessible harvest-to-shelf records for all compostable personal care listings. This transparency infrastructure compresses supplier qualification cycles from months to weeks while excluding uncertified competitors.
REACH Annex XVII updates are tightening restrictions on formaldehyde-releasing preservatives in bamboo treatments. German manufacturers face reformulation deadlines that favor suppliers with in-house chemical compliance teams. The medical specimen collection segment responds by accelerating ISO 13485 certification timelines to maintain hospital procurement eligibility.
Subscription-based replenishment models are displacing single-unit pharmacy purchases among urban millennials. The Humble Co. and comparable direct-to-consumer brands capture recurring revenue through plastic-negative membership tiers. France and Benelux markets exhibit the highest conversion rates, where municipal composting infrastructure validates consumer environmental claims.
Compostable Cotton Swab Market Segmentation
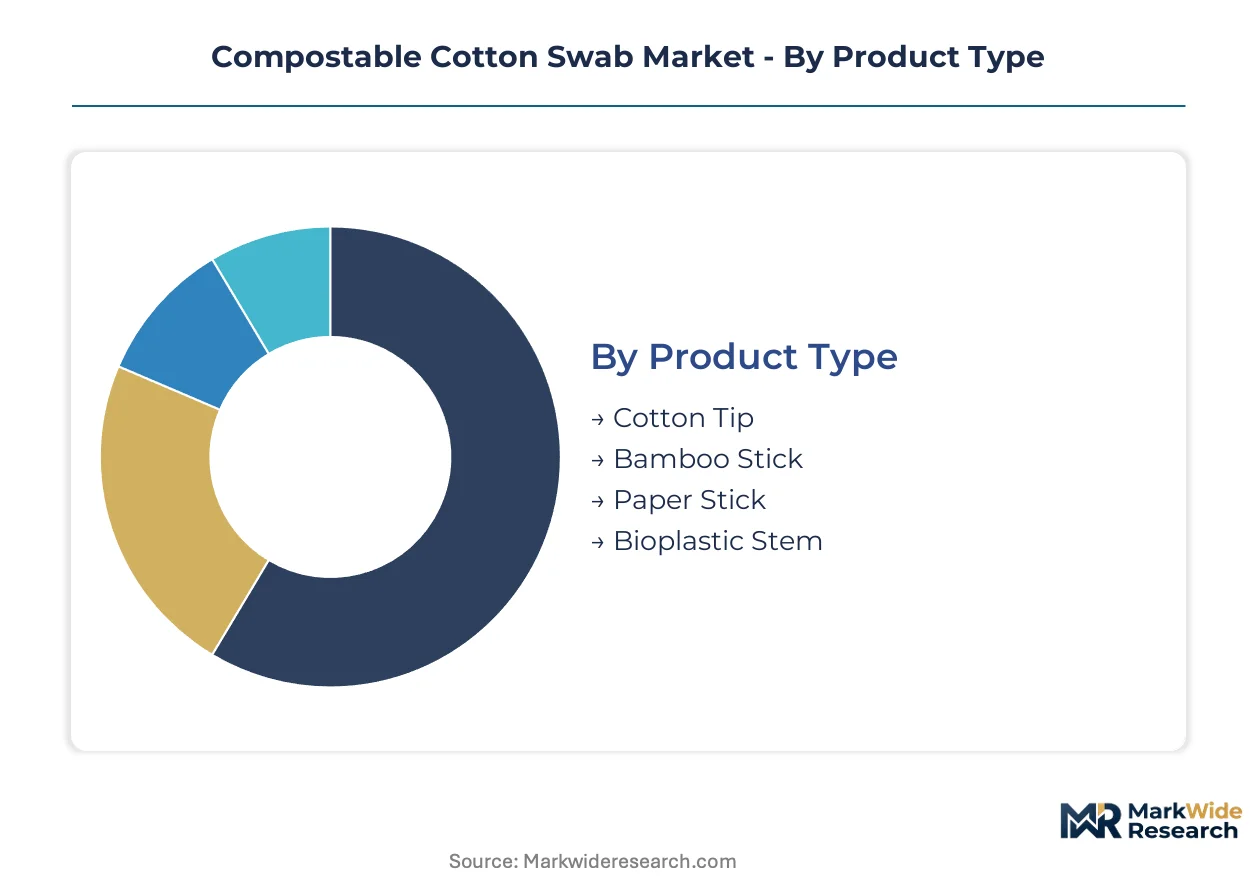
Compostable cotton swab manufacturers configure production lines around material specifications and sterilization requirements that vary sharply across end-use contexts. Segmentation reveals where ISO 13485 compliance creates margin premiums versus where FSC certification alone suffices for shelf placement.
Product Type:
After-sales service intensity diverges materially across stick compositions, with medical-grade bioplastic variants requiring gamma irradiation documentation that bamboo suppliers rarely maintain.
- Bamboo Stick:Compressed fiber construction leverages mature supply chains from Zhejiang and Anhui provinces. German drugstore chains dm-drogerie markt and Rossmann concentrate procurement here due to consumer familiarity and established FSC traceability systems.
- Bioplastic Stem:Certified compostable polymers such as PLA and PHA demand industrial composting infrastructure for end-of-life validation. Medical specimen collection applications generate premium positioning where ISO 13485 sterilization compliance blocks bamboo competitors from hospital procurement.
- Cotton Tip:Pharmaceutical-grade bleached cotton dominates medical applications requiring lint-free performance.
- Paper Stick:Molded pulp alternatives serve cost-sensitive personal care segments with shorter composting cycles.
By volume, Bamboo Stick leads. By growth pace, Bioplastic Stem is ahead.
Application:
Cost tier stratification separates cosmetic use cases from clinical environments where sterility documentation commands 40-60% price premiums.
- Personal Care:Cosmetic application and daily hygiene represent the baseline volume segment. EU Green Deal extended producer responsibility mandates are accelerating substitution of petroleum-based plastic stems in German and French retail channels.
- Medical Care:Specimen collection and wound cleaning require gamma irradiation validation and ISO 13485 quality systems. REACH-compliant material mandates from ECHA restrict preservative treatments, narrowing the supplier base to manufacturers with in-house chemical compliance teams.
- Infant Care:Hypoallergenic claims and pediatric safety certifications drive pharmacy-exclusive distribution in Austria and Switzerland.
- Industrial Cleaning:Electronics and precision manufacturing adopt lint-free variants for contamination-sensitive environments.
Personal Care generates absolute volume. Medical Care captures margin concentration.
End User:
Customer type determines whether procurement emphasizes recurring subscription models or institutional tender processes with 12-18 month qualification cycles.
- Pharmacies:Apotheke networks in German-speaking Europe stock premium-positioned variants with plastic-negative packaging certifications. The Humble Co. and comparable direct-to-consumer brands leverage pharmacy exclusivity for subscription retention.
- Specialty Clinics:Dermatology and otolaryngology practices specify medical-grade bioplastic stems with batch-level traceability documentation.
- Baby Care Centers:Pediatric facilities mandate choking-hazard testing and hypoallergenic material declarations beyond standard compostability certification.
- Manufacturing Units:Electronics assembly and pharmaceutical production facilities procure lint-free industrial variants through B2B distributors.
Pharmacies anchor consumer-facing volume. Specialty Clinics drive specification upgrades.
Packaging Type:
Supply concentration in FSC-certified paperboard creates geographic dependency for brands pursuing plastic-negative claims.
- Eco-friendly Wrapping:Unbleached kraft paper and water-based adhesives enable quantified ocean plastic recovery partnerships. Direct-to-consumer subscription models in France and Benelux exhibit highest conversion rates where municipal composting infrastructure validates environmental claims.
- Blister Pack:Molded fiber or bio-based film alternatives serve retail visibility requirements while maintaining industrial compostability. Douglas and comparable beauty retailers now mandate QR-code-accessible provenance documentation.
- Box Pack:Standard cardboard packaging dominates mass retail placement with lower unit economics.
- Bulk Packaging:Institutional and industrial procurement favors reduced packaging ratios for cost efficiency.
Eco-friendly Wrapping is expanding most quickly in direct-to-consumer channels. Blister Pack retains retail dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in compostable cotton swabs tilt toward European net importing, with Asian manufacturing clusters supplying certified bamboo sticks to German and French distribution hubs. The EU Green Deal's extended producer responsibility mandates create regulatory pull that concentrates procurement in member states with mature industrial composting infrastructure.
Germany
dm-drogerie markt and Rossmann have executed systematic de-stocking of plastic-stemmed alternatives, concentrating shelf space for FSC-certified bamboo variants. ECHA enforcement of REACH Annex XVII restrictions on formaldehyde-releasing preservatives forces reformulation timelines that favor suppliers with in-house chemical compliance teams. The Rhine-Ruhr industrial corridor hosts stick-forming equipment conversion facilities retooling from plastic injection molding to bamboo fiber compression.
France
Municipal composting infrastructure in Paris and Lyon validates consumer environmental claims, driving subscription-based replenishment models among urban millennials. The EU Green Deal pushes national extended producer responsibility schemes toward inclusion of single-use hygiene articles. Groupe Lemoine anchors European production with vertically integrated operations in the Hauts-de-France region, controlling stick-forming through final packaging.
United Kingdom
Douglas and comparable beauty retailers now mandate QR-code-accessible provenance documentation for all compostable personal care listings. Post-Brexit regulatory divergence from REACH creates dual certification burdens for suppliers serving both UK and EU markets. The Midlands logistics cluster handles cross-channel distribution for brands pursuing pharmacy-exclusive positioning in continental Europe.
United States
FDA quality system requirements for medical-grade swabs create sterilization validation barriers that compostable entrants must satisfy for hospital procurement eligibility. EPA guidance on industrial composting facility standards remains fragmented across state jurisdictions, limiting verified end-of-life claims in regions without municipal organic waste collection. The Northeast corridor exhibits highest direct-to-consumer conversion rates for plastic-negative subscription models.
China
FSC-certified bamboo supply concentrates in Zhejiang and Anhui provinces, creating geographic dependency and harvest-season volatility for European importers. The country's national standards body aligns GB certification with ISO 17025 laboratory protocols to accelerate third-party compostability verification timelines. Yangtze River Delta manufacturing hubs supply compressed fiber stick components to brands pursuing REACH-compliant European market entry.
Compostable Cotton Swab Market Competitive Landscape
On the supply side, the industry is bifurcating between scaled FMCG conglomerates with global procurement leverage and specialized sustainability brands with pharmacy-exclusive distribution relationships. Three archetypes dominate: multinational consumer goods houses with FSC-certified bamboo volume contracts, European vertically integrated manufacturers controlling stick-forming through final packaging, and direct-to-consumer challengers monetizing plastic-negative certification through subscription retention. Competitive moves concentrate on strategic partnerships with industrial composting facility operators and backward integration into certified plantation sourcing.
Within the multinational tier, Unilever leverages global procurement scale across personal care portfolios. Groupe Lemoine occupies a position as the vertically integrated European anchor with captive stick-forming capabilities. The Humble Co. exemplifies the direct-to-consumer archetype, building subscription retention through pharmacy exclusivity and quantified environmental claims.
| Leading Market Players |
|---|
| Q-tips |
| Unilever |
| Groupe Lemoine |
| Sanyo Co., Ltd. |
| Hydrophil |
| The Humble Co. |
| Jieyang Top-Tip's Daily Use Products |
| Puritan Medical Products |
| LastObject |
| Others |
Pricing and Supply Chain Analysis
Zhejiang and Anhui provinces govern downstream pricing power through FSC-certified bamboo harvest cycles that concentrate raw material supply in two Chinese regions. Seasonal volatility in these provinces transmits directly to European contract renegotiations, where German drugstore chains leverage volume commitments to compress supplier margins during peak harvest periods.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the compostable cotton swab market. Price differentiation separates ISO 13485-certified medical-grade bioplastic stems from FSC-certified bamboo variants for personal care, with sterilization validation costs widening spreads. Pricing pressure stems from REACH-compliant bamboo treatment reformulation requirements that raise input costs for smaller manufacturers. Mass retail buyers exhibit highest price sensitivity, while pharmacy-exclusive channels absorb premiums for plastic-negative packaging certifications.
Supply Chain Analysis
Export-control regimes limiting flows of gamma irradiation equipment constrain medical-grade sterilization capacity expansion outside established manufacturing hubs. Geographic supply concentration centers on China for FSC-certified bamboo, France for vertically integrated stick-forming operations, and Germany for REACH-compliant chemical treatment facilities. Raw material dependencies include bleached pharmaceutical-grade cotton, compressed bamboo fiber, and certified compostable biopolymers. Single-source vulnerability in Zhejiang plantation certification creates harvest-season disruption risk. Distribution runs through drugstore chain central buying offices and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compostable cotton swab market is recovering from a cyclical trough driven by EU Green Deal extended producer responsibility implementation timelines that compressed 2024-2025 procurement cycles. Regulatory clarity on national EPR schemes is restoring visibility for capital deployment decisions.
For Market Incumbents: Harden supply chain resilience through backward integration into certified plantation sourcing in Anhui province, reducing harvest-season price volatility exposure. Secure ISO 17025 laboratory partnerships to compress compostability verification cycles from 12 months to 6 months, blocking mid-tier competitors from retail shelf placement. The priority lever rests on controlling FSC traceability documentation that dm-drogerie markt and Douglas now mandate.
For New Entrants and Emerging Players: Build out pharmacy-exclusive distribution in Austria and Switzerland where Apotheke networks offer lower slotting fees than German mass retail. Target infant care applications with hypoallergenic certification requirements that create defensible positioning against commodity bamboo variants. The most penetrable white space sits in plastic-negative subscription models for urban millennials in France and Benelux.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU Green Deal mandates will default single-use hygiene articles to compostable formats under pending EPR expansions. Acquisition targets with captive ISO 13485 sterilization capabilities command scarcity premiums as hospital procurement eligibility barriers rise. The signal to watch is industrial composting infrastructure buildout pace relative to product certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Plantation Sourcing | FSC traceability control secures dm-drogerie markt and Rossmann shelf placement against uncertified competitors. |
| ISO 13485 Sterilization Certification Investment | Gamma irradiation validation unlocks hospital procurement eligibility and 40-60% price premiums in medical care. |
| Pharmacy-Exclusive Distribution Expansion | Apotheke network positioning in German-speaking Europe enables subscription retention through plastic-negative membership tiers. |
| Digital Traceability System Deployment | Blockchain-enabled harvest-to-shelf records satisfy Douglas QR-code mandates and compress supplier qualification cycles. |
| REACH-Compliant Chemical Treatment Reformulation | In-house compliance teams capture market share as ECHA enforcement eliminates formaldehyde-releasing preservative suppliers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with supply chain directors at drugstore chains, procurement managers at bamboo fiber processors, regulatory affairs leads at compostable material certifiers, and sustainability officers at personal care brands; and secondary validation through ECHA REACH Annex XVII filings, TÜV and DIN CERTCO compostability registries, FSC chain-of-custody databases, and EU member state extended producer responsibility scheme documentation. Bottom-up volume triangulation across material type, application, and end-user segments was cross-checked against top-down market sizing from trade flow analysis.
Forecast inputs included stick-forming equipment conversion timelines, industrial composting facility expansion pipelines, and REACH enforcement intensity trajectories across the analysis window. Segmentation dimensions modeled encompass material composition, sterilization requirement tier, distribution channel type, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical substitution rates for plastic-stemmed alternatives against regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated FSC-certified bamboo plantation harvest yield projections and ISO 17025 laboratory capacity expansion plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated European manufacturers or scaled Asian fiber processors would shift outcomes. Material shifts in EU Green Deal EPR inclusion timing or ECHA enforcement priority would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Silicone Film Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Reflective Polarizing Films Market
Specialty Materials
Plastic Dielectric Films Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Solar Control Films Market