
 Refined Wax Market | 2026-2036
Refined Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Wax Market Analytics
Aftermarket service revenue for wax blending and custom formulation is reshaping profit pools across the value chain. Sasol Limited leverages its Fischer-Tropsch synthetic wax capacity to dominate specialty industrial grades in Europe. ExxonMobil Corporation anchors North American supply through integrated refinery operations in Texas and Louisiana. China National Petroleum Corporation extends its position via captive feedstock access from domestic crude allocation.
Refined wax comprises hydrocarbon mixtures purified through solvent deoiling, hydrotreating, or fractional crystallization to achieve controlled melting points between 46°C and 68°C and oil content below 0.5%. These specifications serve as binders, moisture barriers, and gloss agents across packaging, personal care, and rubber processing. Paraffin wax still occupies the largest volume share in candle making and food coating, though synthetic wax from gas-to-liquids plants is displacing conventional grades in high-performance adhesives. Cosmetic grade commands the steepest premium due to FDA and EU cosmetic regulation compliance burdens, while industrial grade competes chiefly on bulk pricing and logistics reliability.
REACH registration requirements in Europe, FDA food-contact regulations under 21 CFR 172.886, and China's GB standards for food packaging materials collectively elevate compliance costs for cross-border suppliers. EPA emissions rules for petroleum refining in the United States further constrain domestic paraffin output and redirect investment toward synthetic pathways. Buyers should monitor feedstock arbitrage between slack wax and natural gas liquids, as this spread determines which production routes sustain margin viability.
Market Dynamics
Synthetic wax production via Fischer-Tropsch gas-to-liquids technology is compressing traditional petroleum refining economics, forcing capacity reallocation toward specialty grades with certified purity profiles.
Growth Catalysts
- Cosmetic formulation expansion:South Korean skincare manufacturers are scaling refined wax procurement for K-beauty export formulations targeting North American and European retail channels.
- REACH purity escalation:ECHA registration thresholds for candle-grade imports are tightening residual oil content specifications, filtering out low-cost suppliers and elevating compliant producers.
- Food packaging barrier demand:GB standards compliance for direct food contact is accelerating hydrotreated paraffin substitution of mineral oil-saturated alternatives in China's dairy and confectionery sectors.
Market Restraints
- Feedstock volatility:Slack wax availability fluctuates with fuel oil refining margins, compressing margin predictability for solvent deoiling operators in the US Gulf Coast.
- Supply concentration:Germany's Cologne-Leverkusen chemical corridor hosts disproportionate European blending capacity, creating single-point vulnerability for just-in-time automotive and rubber customers.
- Natural wax substitution:Carnauba and candelilla waxes are capturing premium cosmetic and dental applications where plant-origin claims command retail price premiums.
Strategic Opportunities
- Biodegradable packaging films:Polymer-grade microcrystalline wax is penetrating compostable food wrap formulations as manufacturers seek moisture-barrier performance without fossil-derived plastic content.
- Pharmaceutical ointment bases:USP-grade white petrolatum specifications are opening formulation partnerships between refiners and topical drug developers seeking single-source excipient qualification.
- Carbon border adjustment positioning:EU CBAM preparatory phase is incentivizing synthetic wax producers with integrated carbon capture to document lifecycle emissions for tariff advantage.
Industry Challenges
- Hydrotreater catalyst expertise:Deep desulfurization and color removal to sub-0.5 Saybolt requires specialized process engineering talent scarce outside major integrated refiners.
- Multi-jurisdiction certification lag:Simultaneous FDA 21 CFR 172.886, REACH Annex XV, and MFDS cosmetic ingredient filings extend product launch timelines by 18-24 months for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Wax Market |
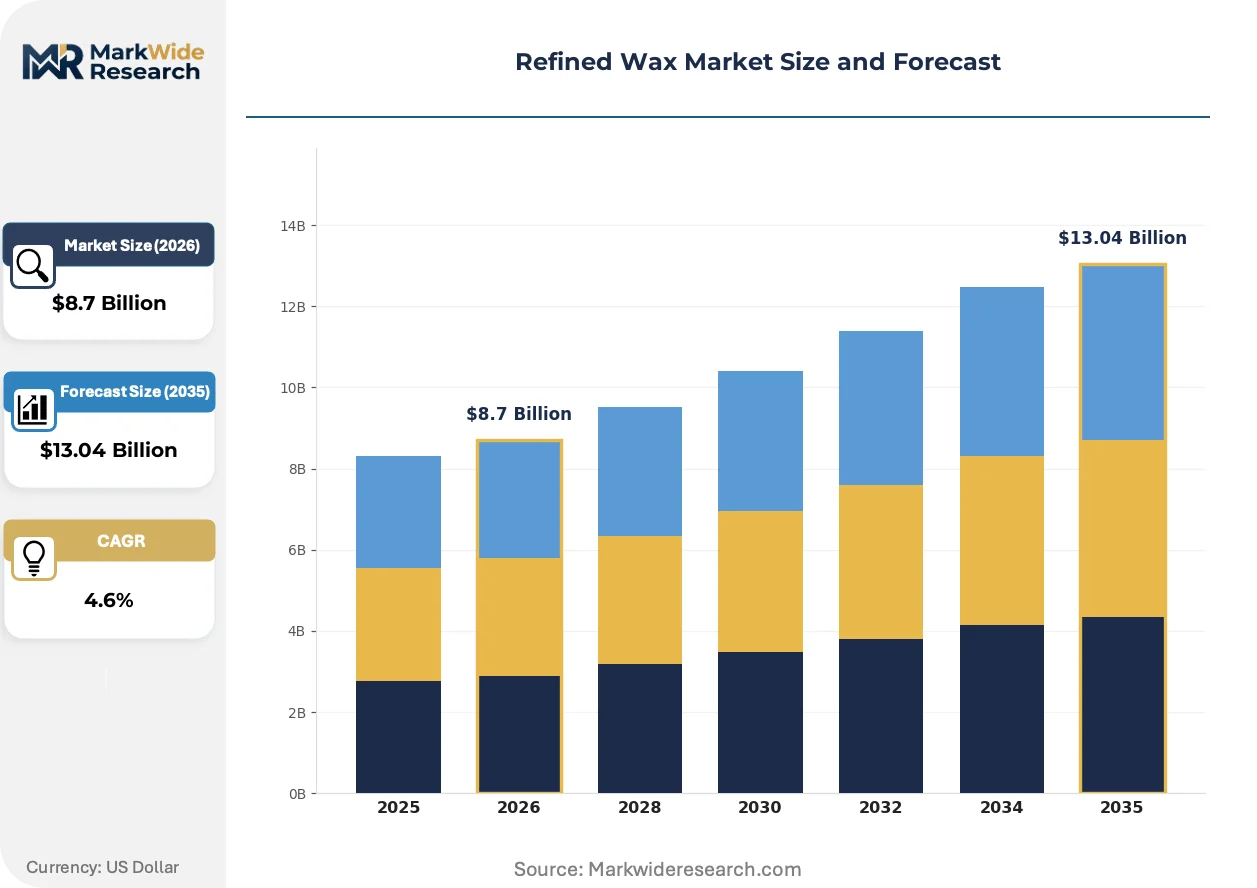
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Microcrystalline Wax, Synthetic Wax, Palm Wax End Use Industry: Cosmetics, Food Packaging, Candle Making, Industrial Applications Form: Beads, Blocks, Pastes, Sheets Grade: Food Grade, Industrial Grade, Cosmetic Grade, Pharmaceutical Grade |
| Companies Covered | Sasol Limited, ExxonMobil Corporation, China National Petroleum Corporation, Sinopec Corp., Royal Dutch Shell plc, Nippon Seiro Co., Ltd., The International Group, Inc., Repsol S.A., Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Wax Market Evolving Landscape
Process intensification and digital quality control are compressing batch-to-batch variability, enabling specification-grade wax supply to precision industries previously served only by synthetic alternatives.
Gas-to-liquids Fischer-Tropsch synthetic wax is migrating from high-performance adhesive formulations into mainstream packaging hot-melts as cost parity with hydrotreated slack wax improves. European tape and label converters are qualifying GTL grades for freezer-grade applications. This technology diffusion is eroding the historical price premium commanded by petroleum-derived microcrystalline wax in sub-70°C service conditions.
EPA refinery emissions rules under the Clean Air Act are constraining domestic US paraffin output and redirecting capital toward synthetic production pathways with lower stack emissions profiles. Texas and Louisiana facilities face MACT standard compliance deadlines that favor gas-based feedstock conversion over crude oil atmospheric distillation. The regulatory pressure is accelerating import dependence for conventional candle and food-coating grades.
Formulation houses are consolidating supplier relationships around integrated refiners offering certified lot traceability and co-developed custom melting point profiles. South Korean cosmetics OEMs now require blockchain-documented feedstock origin for ESG disclosure to European retail partners. This buyer concentration is squeezing independent blenders without captive laboratory or regulatory affairs capabilities.
Refined Wax Market Segmentation
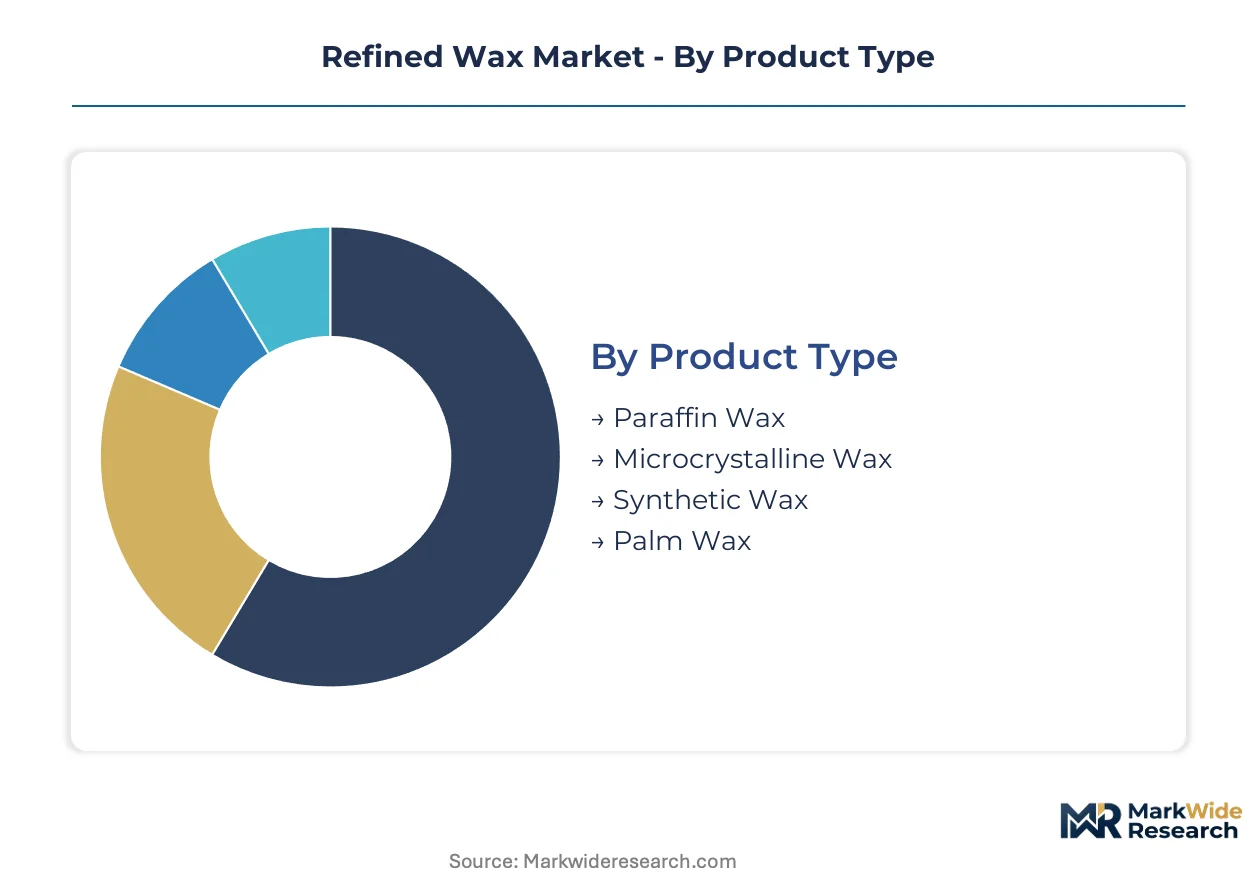
Refined wax procurement decisions hinge on specification-grade alignment between supplier capabilities and end-use regulatory requirements. Buyers segment supply by purity thresholds, physical form, and certification burden rather than commodity pricing alone. Each segmentation dimension carries distinct aftermarket service intensity, from custom melting point blending to blockchain-documented lot traceability.
Product Type:
Aftermarket service intensity varies sharply across production routes, with synthetic wax requiring the most technical support for adhesive formulation partnerships.
- Paraffin Wax:Hydrocarbon mixtures refined from slack wax through solvent deoiling achieve melting points between 46°C and 68°C with oil content below 0.5%. Demand concentrates in Germany's candle manufacturing clusters around Cologne, where REACH compliance documentation now exceeds product cost for small-batch imports.
- Synthetic Wax:Fischer-Tropsch gas-to-liquids output delivers narrower molecular weight distribution and superior thermal stability versus petroleum-derived grades. South Korean packaging converters are qualifying GTL material for freezer-grade hot-melt adhesives, displacing microcrystalline wax in sub-70°C applications.
- Microcrystalline Wax:Higher molecular weight and branching density yield flexible films with excellent moisture barrier properties. FDA 21 CFR 172.886 compliance dominates procurement criteria for US food coating applications.
- Palm Wax:Natural-origin positioning serves premium cosmetic and dental segments where plant-derived claims command retail price premiums. Supply reliability fluctuates with Malaysian and Indonesian crude palm oil export policies.
Paraffin wax holds the largest share; momentum sits with synthetic wax.
End Use Industry:
Margin structures diverge by certification burden, with cosmetic and pharmaceutical applications commanding steepest premiums for purity documentation.
- Cosmetics:K-beauty export formulations from South Korea require blockchain-documented feedstock origin for ESG disclosure to European retail partners. MFDS cosmetic ingredient filings extend supplier qualification timelines by 12-18 months.
- Food Packaging:China's GB standards for direct food contact accelerate hydrotreated paraffin substitution of mineral oil-saturated alternatives in dairy and confectionery barrier coatings.
- Candle Making:REACH Annex XV residual oil specifications are filtering low-cost suppliers from European import channels. German retailers now demand ECHA registration certificates for shelf placement.
- Industrial Applications:Rubber processing and automotive sealant manufacturers prioritize logistics reliability and bulk pricing over certification depth. Texas and Louisiana refiners anchor North American supply through integrated operations.
Candle making retains volume leadership; cosmetics represents the fastest-growing trajectory.
Form:
Physical configuration determines handling infrastructure requirements and melting equipment capital expenditure for downstream processors.
- Beads:Uniform pellet geometry enables precise metering in automated hot-melt adhesive production lines. European tape and label converters specify bead form for high-speed coating operations.
- Blocks:Traditional slab format persists in artisan candle manufacturing and small-batch cosmetics compounding where melting kettles predominate.
- Pastes:Pre-liquefied consistency eliminates heating stage for topical pharmaceutical ointment bases. USP-grade white petrolatum specifications drive procurement from certified refiners.
- Sheets:Controlled thickness enables direct lamination in food wrap and flexible packaging applications. Compostable film developers specify polymer-grade microcrystalline wax sheets for biodegradable moisture barriers.
Beads dominate industrial procurement; pastes are climbing fastest in pharmaceutical partnerships.
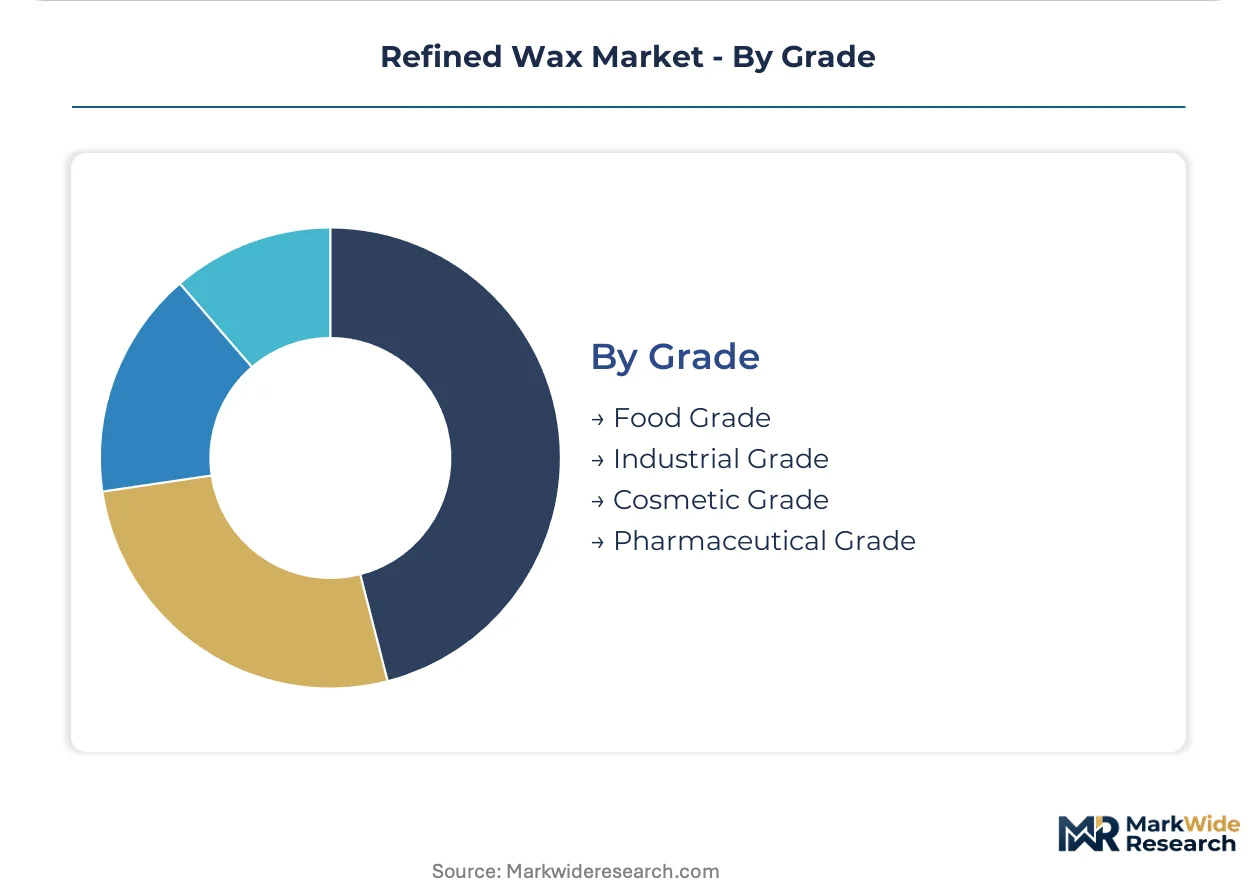
Grade:
Certification tier directly determines addressable market scope and pricing power, with multi-jurisdiction filings becoming table stakes for premium positioning.
- Cosmetic Grade:FDA and EU cosmetic regulation compliance burdens create steep barriers to entry. Simultaneous REACH Annex XV and MFDS filings extend product launch timelines by 18-24 months for cross-border suppliers.
- Food Grade:EPA refinery emissions rules constrain domestic US paraffin output, redirecting investment toward synthetic pathways with lower stack emissions profiles.
- Industrial Grade:Bulk pricing and logistics reliability compete chiefly on feedstock arbitrage between slack wax and natural gas liquids. Germany's Cologne-Leverkusen corridor hosts disproportionate European blending capacity.
- Pharmaceutical Grade:USP monograph compliance opens formulation partnerships between refiners and topical drug developers seeking single-source excipient qualification.
Industrial grade captures volume leadership; pharmaceutical grade shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. South Korea prioritizes cosmetic-grade procurement for K-beauty exports. Germany concentrates on REACH-compliant candle and industrial grades. China scales food-packaging barrier applications under tightening GB standards.
United States
Hot-melt adhesive manufacturers drive synthetic wax qualification for freezer-grade tape and label applications. EPA refinery emissions rules under the Clean Air Act constrain domestic paraffin output from Texas and Louisiana facilities. The US Gulf Coast chemical corridor redirects investment toward gas-to-liquids pathways with lower stack emissions profiles.
Germany
Candle manufacturers around Cologne and Leverkusen demand ECHA registration certificates for retail shelf placement. REACH Annex XV residual oil specifications filter low-cost import suppliers from European channels. The North Rhine-Westphalia chemical corridor hosts disproportionate blending capacity for automotive and rubber customers.
South Korea
Cosmetics OEMs scale refined wax procurement for skincare formulations targeting North American and European retail channels. MFDS cosmetic ingredient filings extend supplier qualification timelines by 12-18 months. Seoul Capital Area formulation houses now require blockchain-documented feedstock origin for ESG disclosure compliance.
China
Dairy and confectionery processors accelerate hydrotreated paraffin substitution of mineral oil-saturated barrier coatings. GB standards for direct food contact elevate compliance costs for cross-border suppliers. Yangtze River Delta packaging converters dominate domestic procurement volume.
Japan
Precision adhesive formulators seek narrower molecular weight distribution for high-performance industrial applications. METI industrial standards guide synthetic wax adoption in electronics packaging. Chubu region chemical manufacturers anchor domestic specialty grade consumption.
Refined Wax Market Competitive Landscape
Capability concentration sits with integrated refiners commanding hydrotreater catalyst expertise and multi-jurisdiction certification infrastructure; scale advantage sits with national oil companies with captive feedstock access. The vendor base organizes around three strategic archetypes: Fischer-Tropsch synthetic specialists, integrated petroleum refiners, and regional blending houses. Dominant competitive moves include backward integration into gas-to-liquids production and geographic expansion through formulation partnerships.
Among integrated petroleum refiners, ExxonMobil Corporation anchors North American supply through Texas and Louisiana refinery operations. Sasol Limited occupies a distinctive position as a Fischer-Tropsch synthetic wax producer leveraging gas-to-liquids capacity. China National Petroleum Corporation exemplifies the national oil company archetype with captive domestic crude allocation securing feedstock advantage.
| Leading Market Players |
|---|
| Sasol Limited |
| ExxonMobil Corporation |
| China National Petroleum Corporation |
| Sinopec Corp. |
| Royal Dutch Shell plc |
| Nippon Seiro Co., Ltd. |
| The International Group, Inc. |
| Repsol S.A. |
| Clariant AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in Germany's hydrotreater-equipped refineries is elevating pricing power for REACH-compliant producers while forcing buyers toward longer contract structures. This utilization squeeze concentrates supplier leverage in the Cologne-Leverkusen corridor and reshapes procurement risk calculations across European candle and automotive sealant markets.
Pricing Analysis
Long-term offtake agreements dominate refined wax procurement for industrial-grade buyers seeking margin predictability amid feedstock volatility. Three-tier pricing structure across cosmetic, food, and industrial certification levels captures the steepest premium for simultaneous FDA and REACH compliance. Cost compression in candle-grade paraffin is intensifying because EPA refinery emissions rules constrain domestic US atmospheric distillation capacity. Rubber processors and bulk adhesive manufacturers exhibit highest price sensitivity, while K-beauty cosmetics OEMs prioritize blockchain-documented origin over unit cost.
Supply Chain Analysis
Upstream slack wax availability fluctuates with fuel oil refining margins across the US Gulf Coast, Germany, and China. Crude oil atmospheric distillation, natural gas liquids, and Fischer-Tropsch synthesis feed three distinct production pathways with divergent carbon intensity profiles. Single-source vulnerability concentrates in Germany's chemical corridor, where disproportionate blending capacity serves just-in-time automotive customers. Distribution runs through integrated refiners with captive laboratory services, squeezing independent blenders without certification infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as biodegradable packaging films and pharmaceutical ointment bases open specification-grade demand previously served only by synthetic alternatives.
For Market Incumbents: Build certification moats through simultaneous FDA 21 CFR 172.886, REACH Annex XV, and MFDS cosmetic ingredient filings that extend competitor qualification timelines. Anchor capacity additions in Texas and Louisiana gas-to-liquids pathways to escape EPA refinery emissions constraints on atmospheric distillation. Capture backward integration into hydrotreater catalyst expertise, scarce talent outside major integrated refiners. For New Entrants and Emerging Players: Southeast Asian pharmaceutical compounding represents underpenetrated white space where USP-grade white petrolatum specifications exceed available certified supply. Target South Korean cosmetics OEMs requiring blockchain-documented feedstock origin for ESG disclosure to European retail partners. Enter through formulation partnerships with tape and label converters qualifying GTL material for freezer-grade hot-melt adhesives. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refiners offering certified lot traceability and co-developed custom melting point profiles. Long-term viability favors synthetic wax producers with integrated carbon capture positioning for EU CBAM tariff advantage. Watch feedstock arbitrage spreads between slack wax and natural gas liquids as the inflection signal determining which production routes sustain margin viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gas-to-Liquids Production | Sasol Limited leverages Fischer-Tropsch capacity to escape petroleum refining emissions constraints. |
| Long-term Supply Agreement with Cosmetics OEMs | Blockchain-documented origin terms satisfy ESG disclosure requirements for K-beauty export channels. |
| Green Manufacturing Transition with Carbon Capture | EU CBAM preparatory phase rewards documented lifecycle emissions for tariff positioning. |
| Joint Venture for Pharmaceutical Grade Qualification | USP monograph compliance opens single-source excipient partnerships with topical drug developers. |
| Capacity Expansion in Food Packaging Barrier Coatings | China's GB standards accelerate hydrotreated paraffin substitution in dairy and confectionery sectors. |
Research Methodology
A standing panel of refinery operations managers, cosmetics formulation chemists, packaging procurement leads, and regulatory affairs directors provided ongoing calibration against trade flows and capacity utilization signals. Primary interviews with hydrotreater process engineers and candle manufacturing plant managers combined with customs data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up segment sizing triangulated against top-down feedstock consumption estimates across petroleum refining and gas-to-liquids pathways.
Scenario bracketing anchored projections across conservative, baseline, and aggressive adoption paths for synthetic wax penetration in packaging adhesives. Segmentation modeling spanned grade tier, end-use industry, physical form, and regional production hub across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating REACH compliance cost pass-through and K-beauty export volume trajectories. Feedstock arbitrage spreads and hydrotreater capacity utilization served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by national oil companies with captive crude allocation would shift outcomes through price-undercutting in industrial-grade bulk markets. Cross-checking against EIA refinery utilization data and Yangtze River Delta packaging converter procurement surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market