
 Speech to Speech Translation Market | 2026-2036
Speech to Speech Translation Market Size, Share, and Industry Trends Forecast 2026-2036
Speech to Speech Translation Market Outlook
Modular API bundling is rebalancing how enterprise buyers procure speech translation capabilities, shifting from monolithic platforms to mix-and-match components. Microsoft Corporation leverages its Azure cloud backbone to anchor enterprise-grade deployments across hybrid environments. Google LLC differentiates through deep neural network specialization in low-resource language pairs. iFLYTEK dominates Mandarin-centric embedded systems for consumer electronics and smart devices.
Speech to speech translation denotes real-time conversion of spoken utterances from one natural language into another, employing acoustic modeling, neural machine translation, and vocoder synthesis to preserve semantic content, prosody, and speaker identity with sub-second latency. Its primary commercial purpose is eliminating human interpreter dependency in high-velocity communication scenarios. Cloud service deployments capture the largest margin pools as enterprises prioritize scalable infrastructure over capital-intensive on-premise installations. Neural networks represent the fastest-expanding technology segment, displacing statistical models in accuracy-critical government and healthcare applications. Mobile application adoption among travelers remains volume-heavy but price-compressed.
The EU AI Act imposes risk-classification and conformity assessment obligations on automated translation systems processing biometric data, compelling vendors to rearchitect voice pipelines for auditability. The FDA regulates speech translation devices marketed for clinical diagnostic support, requiring software-as-medical-device validation that lengthens commercialization timelines. China's SAMR enforces algorithmic recommendation provisions on consumer-facing translation apps, mandating user consent frameworks. Stakeholders must monitor divergence between privacy-centric European standards and performance-permissive Asian regulatory environments when allocating R&D and compliance budgets.
Market Dynamics
Neural acoustic modeling is fragmenting vendor control over speech translation pipelines, enabling enterprises to swap encoder, translation, and synthesis modules from different suppliers rather than accepting bundled platforms.
Growth Catalysts
- Defense procurement mandates:United States federal agencies are expanding real-time translation system deployments for cross-border intelligence operations, creating sustained demand for secure, low-latency infrastructure.
- EU AI Act compliance requirements:Algorithmic transparency obligations for biometric data processing are compelling vendors to rearchitect voice pipelines, opening consulting and certification service revenue streams.
- Edge computing maturation:On-device neural inference is enabling offline speech translation in consumer electronics, reducing cloud dependency for Mandarin-centric smart device manufacturers.
Market Restraints
- GPU compute cost volatility:Training and inference for large-scale neural translation models remains tied to NVIDIA supply concentration, squeezing margin structures for mid-tier vendors.
- FDA software-as-medical-device validation:Clinical diagnostic support applications face 18-36 month commercialization timelines, freezing capital deployment in healthcare verticals.
- Low-resource language data scarcity:Insufficient parallel corpora for African and Indigenous language pairs caps addressable market expansion outside major commercial languages.
Strategic Opportunities
- India's BIS certification pathway:Standardized testing frameworks for AI-enabled voice systems are creating first-mover advantage for vendors establishing local compliance infrastructure.
- Telehealth interpreter unbundling:Healthcare systems are separating translation services from platform vendors, opening API-only supplier relationships.
- Convergence of speech synthesis and voice biometrics:Unified pipelines preserving speaker identity across languages are enabling new enterprise security and personalization applications.
Industry Challenges
- Phonetic transcription specialist scarcity:Linguists capable of annotating low-resource language audio for neural training command premium compensation, constraining model expansion velocity.
- Legacy telephony integration complexity:PSTN and VoIP infrastructure in government and healthcare settings requires custom middleware development, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech to Speech Translation Market |
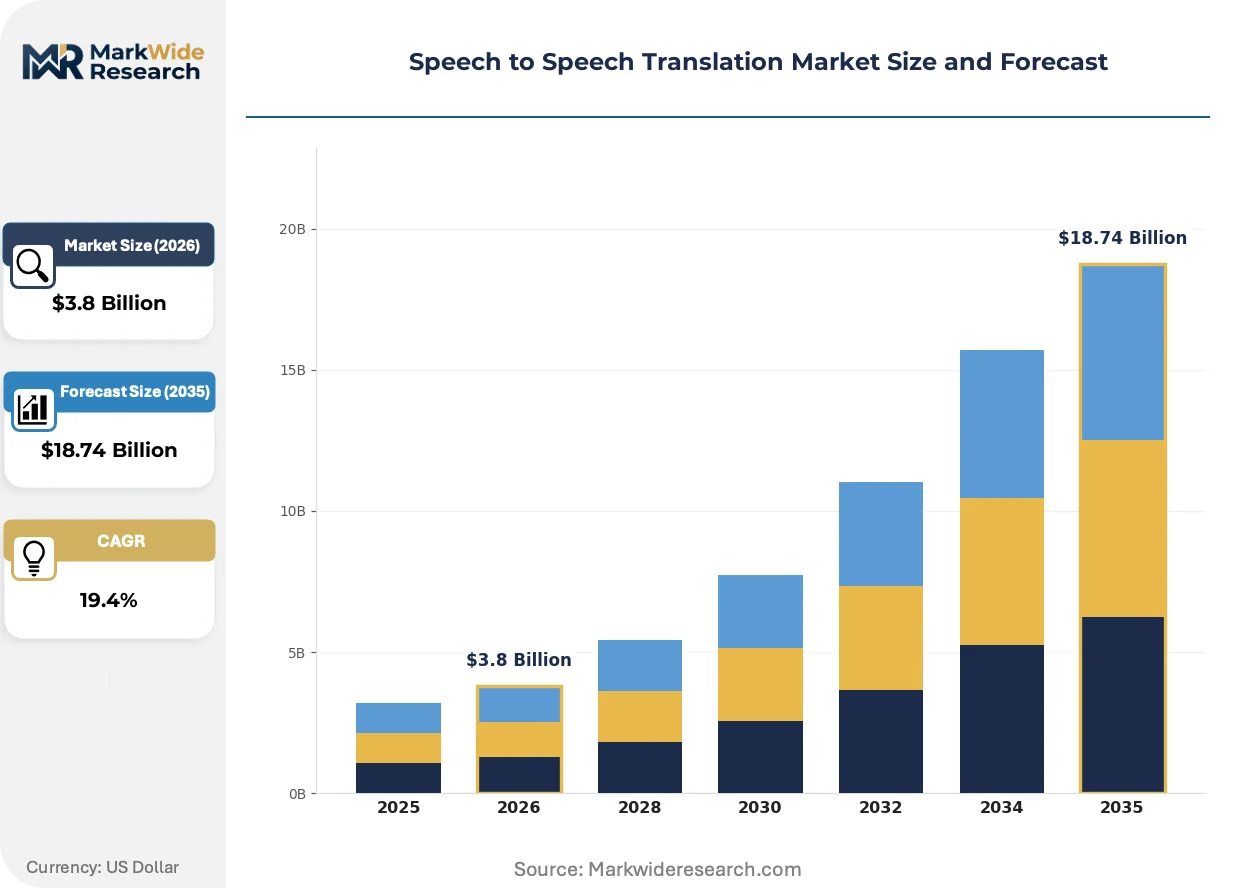
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-based, Mobile Application, Embedded Software, Cloud Service End User: Travelers, Corporations, Educational Institutions, Government Agencies Technology: Neural Networks, Statistical Models, Machine Learning, Voice Recognition Deployment: On-premise, SaaS, Hybrid, Open Source |
| Companies Covered | Meta Platforms Inc., iFLYTEK, Microsoft Corporation, IBM Corporation, Apple Inc., Google LLC, Baidu Inc., Naver Corporation, Amazon.com Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech to Speech Translation Market Strategic Shifts
Architectural decomposition is replacing monolithic speech translation stacks with interoperable components, shifting competitive advantage from end-to-end accuracy to modular swapability and latency optimization.
Self-supervised pretraining for acoustic representations is modularizing how enterprises procure speech capabilities. Defense contractors and financial services firms are adopting encoder modules from specialized vendors while retaining proprietary translation layers. This decomposition is compressing vendor lock-in and accelerating procurement cycles for hybrid cloud deployments.
The EU AI Act's risk-classification framework is mandating conformity assessments for biometric voice processing. Vendors serving European enterprise and public sector clients must document training data provenance and algorithmic decision logic. Healthcare and law enforcement applications face the strictest documentation burdens, driving consolidation toward vendors with established audit infrastructure.
Enterprise buyers are unbundling translation services from unified communications platforms. Fortune 500 technology and professional services firms are sourcing speech APIs directly from neural specialists rather than accepting bundled offerings from incumbent collaboration vendors. This disintermediation is most pronounced in the United States, where federal contracting rules favor component-level procurement transparency.
Speech to Speech Translation Market Segmentation
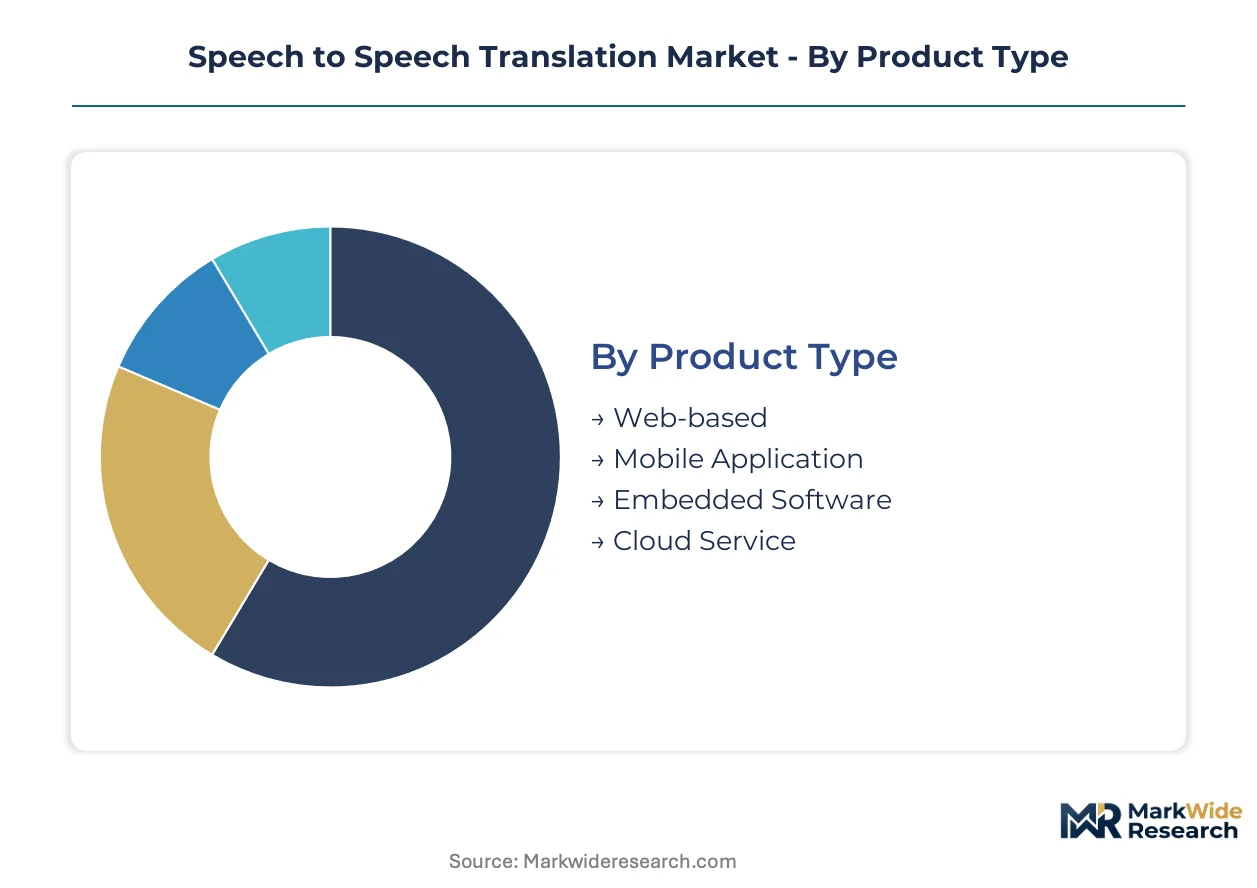
Speech translation procurement splits sharply between latency-sensitive edge deployments and scalable cloud infrastructure, with buyer priorities diverging across security mandates, language coverage needs, and integration complexity. Understanding these segment boundaries clarifies where vendor specialization creates sustainable margin pools versus commodity competition.
Product Type:
Buyers in this category separate by connectivity constraints and processing location requirements, with offline functionality commanding premium positioning.
- Cloud Service:Scalable API architectures enable real-time translation with centralized model updates and enterprise-grade SLAs. United States federal contractors prioritize these deployments for cross-border intelligence operations requiring secure, auditable infrastructure with sub-second latency guarantees.
- Embedded Software:On-device neural inference eliminates network dependency for consumer electronics manufacturers. Mandarin-centric smart device producers in Shenzhen and Beijing leverage these systems to reduce cloud costs and comply with data localization requirements under China's SAMR algorithmic recommendation provisions.
- Mobile Application:Volume-heavy consumer tools for travelers with price-compressed monetization through subscriptions or advertising.
- Web-based:Browser-accessible translation for occasional enterprise use without installation overhead.
Volume sits with Cloud Service; growth tilts toward Embedded Software.
End User:
Procurement sophistication varies dramatically across this category, from standardized consumer subscriptions to multi-year government contracts with security clearances.
- Government Agencies:Defense and intelligence buyers mandate FIPS 140-2 encryption, air-gapped deployment options, and supply chain provenance documentation. United States Department of Defense contracts for real-time translation systems are accelerating deployment of secure, on-premise infrastructure with specialized low-resource language support for African and Middle Eastern operations.
- Corporations:Fortune 500 technology and professional services firms unbundle translation APIs from unified communications platforms. These buyers prioritize modular interoperability, hybrid cloud flexibility, and direct neural specialist relationships over bundled incumbent offerings.
- Educational Institutions:Universities and research organizations with constrained IT budgets favor open-source or academic-licensed solutions.
- Travelers:Price-sensitive consumer segment driving volume through app stores with minimal switching costs.
Revenue concentrates with Government Agencies; expansion climbs fastest among Corporations.
Technology:
Architecture choices here determine accuracy thresholds, training data requirements, and computational cost structures that reshape competitive positioning.
- Neural Networks:Deep learning architectures with transformer-based encoders and attention mechanisms achieve state-of-the-art accuracy in low-resource language pairs. Healthcare diagnostic support applications under FDA software-as-medical-device validation rely on these systems, though commercialization timelines extend 18-36 months.
- Voice Recognition:Acoustic modeling pipelines converting speech to phonetic representations before translation. Defense contractors and financial services firms adopt specialized encoder modules from niche vendors while retaining proprietary downstream layers, compressing vendor lock-in.
- Machine Learning:Broader category encompassing supervised and semi-supervised approaches with moderate accuracy and lower compute requirements.
- Statistical Models:Legacy phrase-based systems displaced by neural approaches in accuracy-critical applications but retained for resource-constrained edge devices.
Investment flows heaviest into Neural Networks; Voice Recognition gains share through modular procurement patterns.
Deployment:
Infrastructure location decisions reflect data sovereignty requirements, latency tolerances, and capital expenditure preferences across buyer segments.
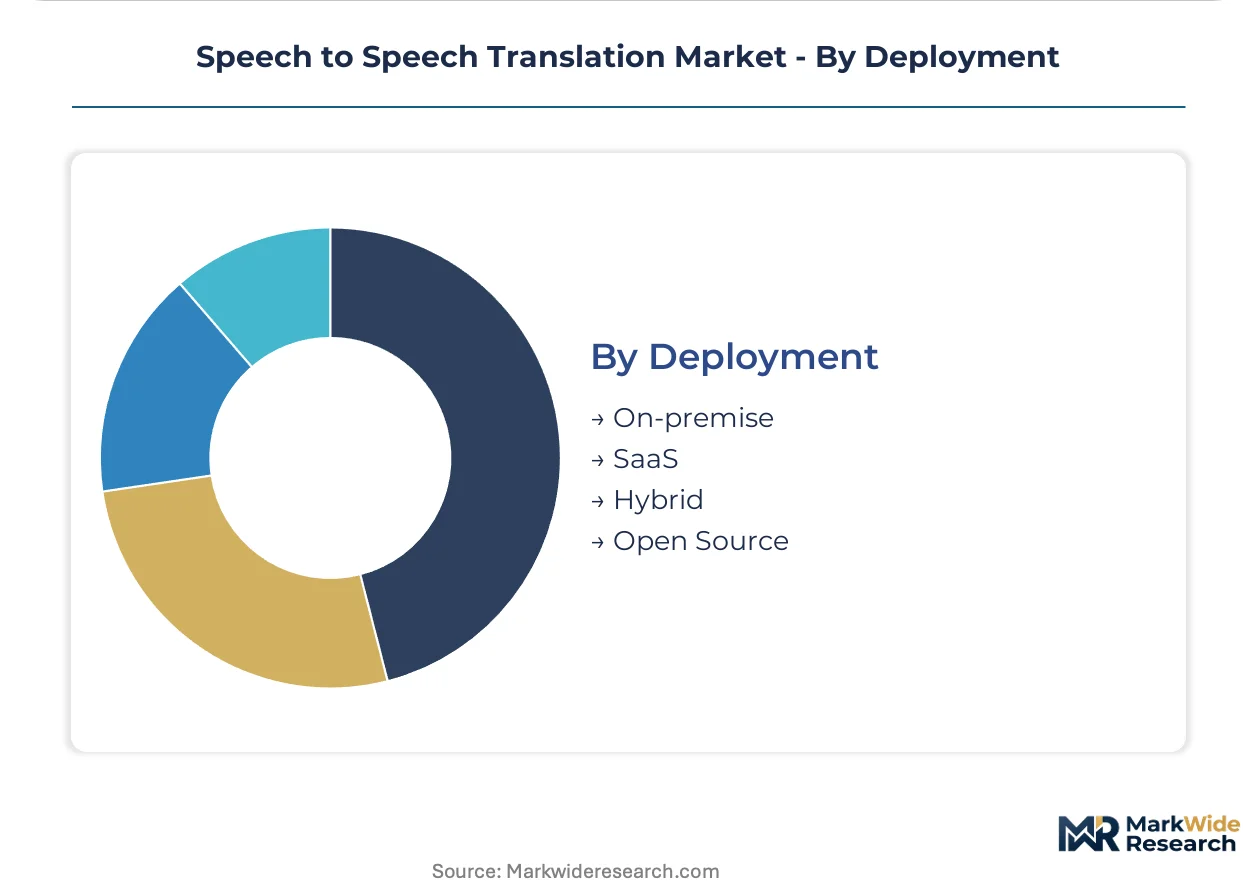
- On-premise:Dedicated hardware installations within buyer-controlled facilities with full data custody. EU AI Act compliance for biometric voice processing drives European healthcare and law enforcement buyers toward these deployments, requiring documented training data provenance and algorithmic audit trails.
- Hybrid:Split architectures processing sensitive audio on-device while leveraging cloud resources for model updates and non-critical workloads. India's BIS certification pathway for AI-enabled voice systems is creating first-mover advantage for vendors establishing local compliance infrastructure supporting these configurations.
- SaaS:Fully managed cloud subscriptions with minimal IT overhead for small and mid-sized enterprises.
- Open Source:Community-maintained frameworks with customization flexibility but without vendor support guarantees.
Adoption clusters around Hybrid; steepest expansion trajectory belongs to On-premise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest share of enterprise-grade speech translation infrastructure while China dominates embedded software manufacturing for consumer electronics. Production clusters concentrate in Shenzhen's hardware ecosystem and Seattle's cloud computing corridor.
United States
Defense procurement from the Department of Defense and intelligence agencies drives demand for secure, low-latency systems with air-gapped deployment options. The FDA regulates clinical diagnostic support applications under software-as-medical-device frameworks, extending commercialization timelines. Seattle and Northern Virginia host the primary cloud infrastructure clusters serving federal contractors.
China
Smart device manufacturers in Shenzhen and Beijing generate volume demand for Mandarin-centric embedded translation systems with on-device neural inference. SAMR enforces algorithmic recommendation provisions mandating user consent frameworks on consumer-facing applications. The Pearl River Delta manufacturing hub supplies neural-acoustic hardware to domestic electronics brands.
Germany
Automotive OEMs and industrial automation firms procure hybrid cloud deployments for multilingual factory floor communication. The EU AI Act imposes conformity assessment obligations on biometric voice processing systems, requiring documented training data provenance. Munich and Stuttgart anchor the industrial AI development clusters serving automotive translation needs.
India
Enterprise IT modernization and government digitization programs expand demand for API-first translation infrastructure. BIS certification pathways for AI-enabled voice systems create compliance barriers favoring early entrants with local testing infrastructure. Bangalore and Hyderabad concentrate software development centers serving domestic and export markets.
United Kingdom
Financial services firms and professional services companies unbundle translation APIs from unified communications platforms for regulatory auditability. GDPR requirements intersect with EU AI Act provisions for biometric data processing in cross-border deployments. London's fintech corridor drives demand for real-time multilingual compliance documentation.
Speech to Speech Translation Market Competitive Environment
The competitive structure tilts toward cloud hyperscalers with modular API architectures. Three distinct tiers operate: vertically integrated platform vendors, specialized neural acoustic model providers, and regional embedded software specialists. Consolidation pressure concentrates among mid-tier vendors facing GPU compute cost volatility. Dominant competitive moves include strategic API bundling partnerships and geographic compliance infrastructure expansion.
Within the cloud hyperscaler tier, Microsoft Corporation and Google LLC exemplify platform-scale positioning, while iFLYTEK occupies a distinct archetype as a Mandarin-specialized embedded systems provider. Meta Platforms Inc. represents social-platform integration of translation capabilities. These three anchors demonstrate how competitive positioning fragments across deployment modalities rather than consolidating around unified end-to-end solutions.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| iFLYTEK |
| Microsoft Corporation |
| IBM Corporation |
| Apple Inc. |
| Google LLC |
| Baidu Inc. |
| Naver Corporation |
| Amazon.com Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive GPU sourcing from NVIDIA anchors vendor cost structures and pricing power across deployment tiers, with hyperscalers leveraging volume commitments to compress mid-tier margin structures while specialized encoder vendors extract premiums through scarce phonetic transcription expertise.
Pricing Analysis
Margin tightening in cloud API tiers reflects hyperscaler bundling strategies that commoditize standalone translation services, while embedded software premiums persist for Mandarin-centric systems serving China's data localization mandates. Three-tier pricing structure across enterprise, professional, and consumer levels separates FIPS 140-2 certified government deployments from standard corporate SLAs and price-compressed traveler applications. Cost-down pressure on neural training accelerates as defense contractors unbundle encoder modules from translation layers. Government agencies exhibit lowest price sensitivity due to security mandates; mobile travelers face highest elasticity with minimal switching costs.
Supply Chain Analysis
Phonetic transcription specialist scarcity in India and the Philippines constrains model expansion velocity for low-resource African and Indigenous language pairs. Hardware production clusters in Taiwan, South Korea, and China supply neural-acoustic inference chips to Shenzhen smart device manufacturers. The supply chain draws from NVIDIA GPU concentration, specialized microphone array components, and rare earth elements for edge computing fabrication. Single-source vulnerability in GPU supply creates procurement risk for mid-tier vendors without hyperscaler volume commitments. Distribution runs through direct federal contracting channels in the United States, OEM integration partnerships in China, and API marketplace platforms for enterprise developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPU compute concentration props pricing across deployment tiers, with NVIDIA supply scarcity creating sustained margin pressure that favors vertically integrated hyperscalers over component specialists.
For Market Incumbents: Anchor defensive positioning through exclusive encoder module partnerships that lock out modular procurement alternatives, while accelerating FIPS 140-2 certification investment to capture sustained Department of Defense contract flows. Counter emerging API-only entrants by embedding translation layers within unified communications platforms that resist unbundling. Prioritize backward integration into phonetic transcription workforce pipelines in India to secure low-resource language training data access. For New Entrants and Emerging Players: The premium-to-economy gap in healthcare diagnostic support creates white-space opportunity for FDA-validated neural systems serving 18-36 month commercialization timelines that freeze hyperscaler capital deployment. Target India's BIS certification pathway for AI-enabled voice systems as the most penetrable regulatory entry point, leveraging local testing infrastructure partnerships. Pursue telehealth interpreter unbundling as the primary go-to-market angle, selling API-only relationships to hospital systems separating translation from platform vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of specialized encoder vendors with established phonetic transcription workforces and low-resource language coverage. Long-term viability favors modular API architectures over monolithic platforms as enterprise procurement patterns shift toward component swapability. Monitor FDA software-as-medical-device validation timelines as the critical inflection signal—acceleration in approval velocity would unlock frozen healthcare capital and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Modular API Architecture Development | Enables enterprise buyers to swap encoder, translation, and synthesis components from different suppliers. |
| FIPS 140-2 Certification Investment | Unlocks United States Department of Defense contracts requiring air-gapped deployment options. |
| Phonetic Transcription Workforce Pipeline | Secures scarce linguistic expertise for low-resource African and Indigenous language model training. |
| EU AI Act Compliance Infrastructure | Documents training data provenance for biometric voice processing in European healthcare and law enforcement. |
| Edge Neural Inference Optimization | Reduces cloud dependency for Shenzhen smart device manufacturers under China's SAMR data localization provisions. |
Study Parameters
Multi-period observation of hyperscaler capex disclosures, federal contract award databases, and BIS certification timelines anchored the trend analysis, supplemented by interviews with CTOs at Fortune 500 technology firms, IT procurement officers at defense contractors, platform engineers at cloud infrastructure providers, and integration specialists at telehealth systems. Secondary validation drew from SEC filings, App Annie mobile download metrics, FDA software-as-medical-device submission databases, and EU AI Act conformity assessment registries. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices mapped neural network training costs, GPU pricing volatility, and regulatory compliance timelines across product type, end user, technology, and deployment segmentation dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical procurement velocity and forward-looking federal budget appropriations. Industry-specific inputs included phonetic transcription labor availability indices and low-resource language parallel corpus development rates.
Inputs from federal contracting databases and hyperscaler infrastructure disclosures were available through the study window; gaps in classified defense procurement volumes introduce uncertainty bands around government segment sizing. Forecasts reflect documented assumptions regarding GPU supply normalization and FDA validation timeline stability. Material deviation in NVIDIA supply concentration or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Global Communications Interface Market
Communication Services
Global Passenger Information System Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Managed Communication Services Market
Communication Services
Audio Conferencing Services Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Video Managed Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Industrial Communication Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Meeting Solutions Market