
 Rich Communications Suite Services and Subscribers Market | 2026-2036
Rich Communications Suite Services and Subscribers Market Size, Share, and Industry Trends Forecast 2026-2036
Rich Communications Suite Services and Subscribers Market Analytics
The capital-intensity divergence between cloud-native platforms and legacy telecom infrastructure is rotating competitive dynamics toward hybrid deployment models. Google LLC leverages its Android ecosystem to anchor RCS messaging standards across device manufacturers. Huawei Technologies sustains significant manufacturing scale in network equipment that supports carrier-grade RCS core infrastructure. Ericsson competes through specialized telecommunications software that integrates messaging, voice, and video services for mobile operators.
Rich Communications Suite services encompass IP-based multimedia communication platforms that unify messaging, voice, video, and file sharing through protocols such as RCS, WebRTC, and SIP over packet-switched networks. These systems replace circuit-switched SMS and MMS infrastructure, enabling read receipts, typing indicators, high-resolution media transfer, and interactive business-to-consumer transactions across smartphones and enterprise endpoints. Cloud-based deployment models are capturing the fastest expansion as SMEs seek subscription flexibility without capital expenditure on session border controllers and media servers. Messaging services dominate current revenue pools, while video segments are deepening engagement metrics as enterprises integrate rich communications into customer service workflows.
The GSMA governs universal RCS profile standards that determine interoperability between carrier networks and device ecosystems, directly shaping market access for platform vendors. National regulators including the FCC in the United States and TRAI in India influence spectrum allocation and net neutrality frameworks that affect quality-of-service guarantees for real-time communications. Stakeholders must monitor evolving encryption mandates and data localization requirements that will determine architectural choices between centralized cloud hubs and distributed edge deployments.
Market Dynamics
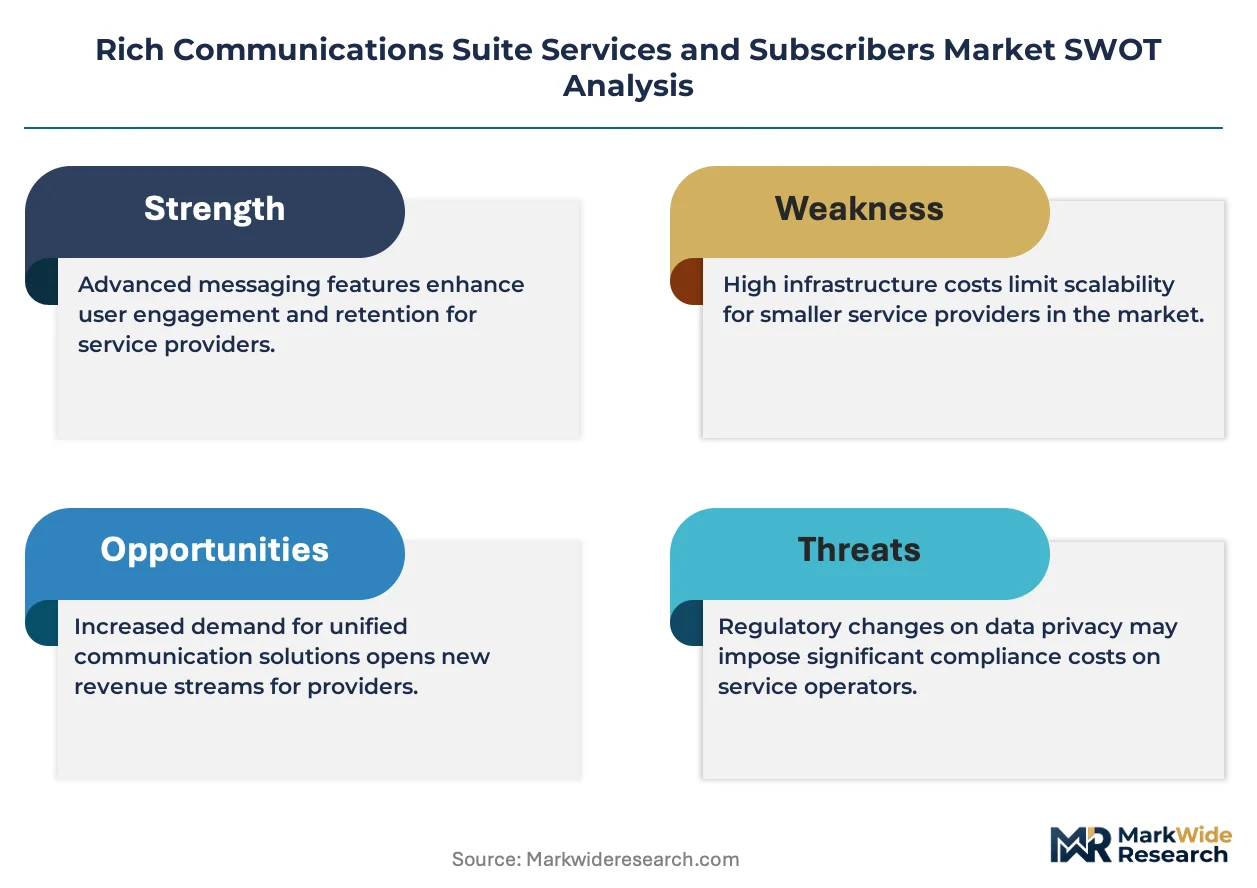
The transition from circuit-switched SMS infrastructure to IP-based RCS protocols is forcing carriers to rearchitect core networks while enterprise messaging volumes surge. This technology displacement concentrates investment in cloud-native session border controllers and edge media processing nodes.
Growth Catalysts
- 5G Standalone Deployment:South Korean carriers SK Telecom, KT Corporation, and LG Uplus have achieved near-complete RCS subscriber coverage through 5G SA core investments. The GSMA's network APIs accelerate carrier onboarding.
- Enterprise Messaging Migration:Business-to-consumer transactional messaging is displacing SMS for banking alerts, delivery notifications, and appointment scheduling across healthcare and logistics end-uses.
- Universal Profile Mandates:The GSMA's RCS Universal Profile 2.4 standardizes interoperability, reducing fragmentation that previously stalled carrier adoption in fragmented European markets.
Market Restraints
- Apple Ecosystem Exclusion:iOS devices lack native RCS support, fragmenting reach and forcing enterprises to maintain parallel SMS fallback infrastructure for complete subscriber coverage.
- Legacy SS7 Interconnect Costs:Carriers must sustain expensive signaling system 7 gateways during the transition period, duplicating operational expenditure across hybrid network phases.
- Edge Infrastructure Capex Burden:Low-latency media processing requires distributed edge nodes, concentrating investment risk among tier-2 carriers with constrained balance sheets.
Strategic Opportunities
- India Digital Payments Integration:TRAI's push for enriched business messaging aligns with UPI transaction growth, creating white space for RCS-enabled payment confirmations and merchant discovery.
- Rich Card Commerce:Interactive product carousels and in-thread checkout are emerging applications displacing mobile web redirects for retail and travel bookings.
- WebRTC Convergence:Browser-based real-time communications are merging with RCS client capabilities, enabling seamless desktop-to-mobile handoff without app downloads.
Industry Challenges
- Interoperability Testing Complexity:Multi-vendor RCS core deployments from Mavenir, ZTE, and Cisco require extensive lab validation, extending carrier launch timelines.
- Encryption Standard Fragmentation:Google's E2EE implementation diverges from carrier-managed keys, complicating compliance with data localization mandates in Saudi Arabia and Turkey.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rich Communications Suite Services and Subscribers Market |
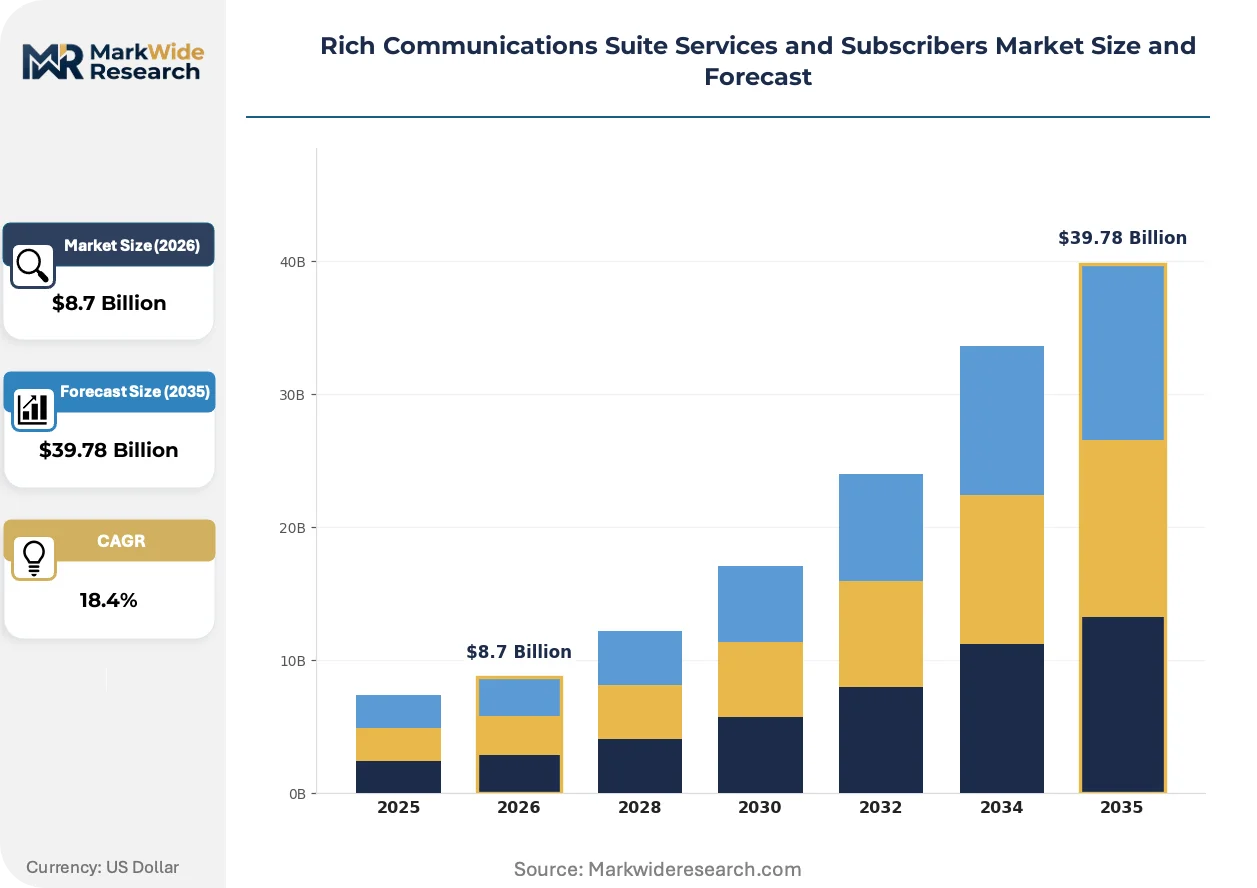
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Messaging, Voice, Video, File Sharing Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, SMEs, Individual Consumers, Government Technology: WebRTC, SIP, VoIP, RCS |
| Companies Covered | Google LLC, Huawei Technologies, AT&T Inc., Verizon Communications Inc., Vodafone Group plc, Ericsson, Tata Communications, Twilio Inc., Orange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rich Communications Suite Services and Subscribers Market Evolving Landscape
Artificial intelligence integration and edge computing architectures are compressing latency thresholds while expanding service richness. These shifts demand new capital allocation patterns across carrier infrastructure and enterprise software stacks.
RCS Business Messaging is miniaturizing the customer service technology stack by embedding chatbot intelligence, payment rails, and CRM integration directly within native messaging threads. Large retailers and airlines are deploying rich cards for boarding passes and order tracking, eliminating standalone app dependencies. The technology is miniaturizing enterprise software footprints while deepening engagement metrics through persistent thread continuity.
The EU's Digital Markets Act interoperability mandates are forcing gatekeeper platforms to open messaging APIs to competing services. This regulatory pressure is accelerating RCS standardization as a compliance pathway for dominant messaging platforms. European carriers are positioning RCS hubs as regulated alternatives to proprietary messaging networks, capturing enterprise messaging traffic previously routed through OTT applications.
Subscription-based deployment models are displacing perpetual licensing for RCS platform access among mid-market enterprises. SMEs are prioritizing usage-based pricing over capital expenditure on session border controllers and media servers. This preference shift is most visible in Southeast Asian markets where cloud-native RCS platforms from regional software vendors are capturing share from traditional telecom equipment suppliers.
Rich Communications Suite Services and Subscribers Market Segmentation
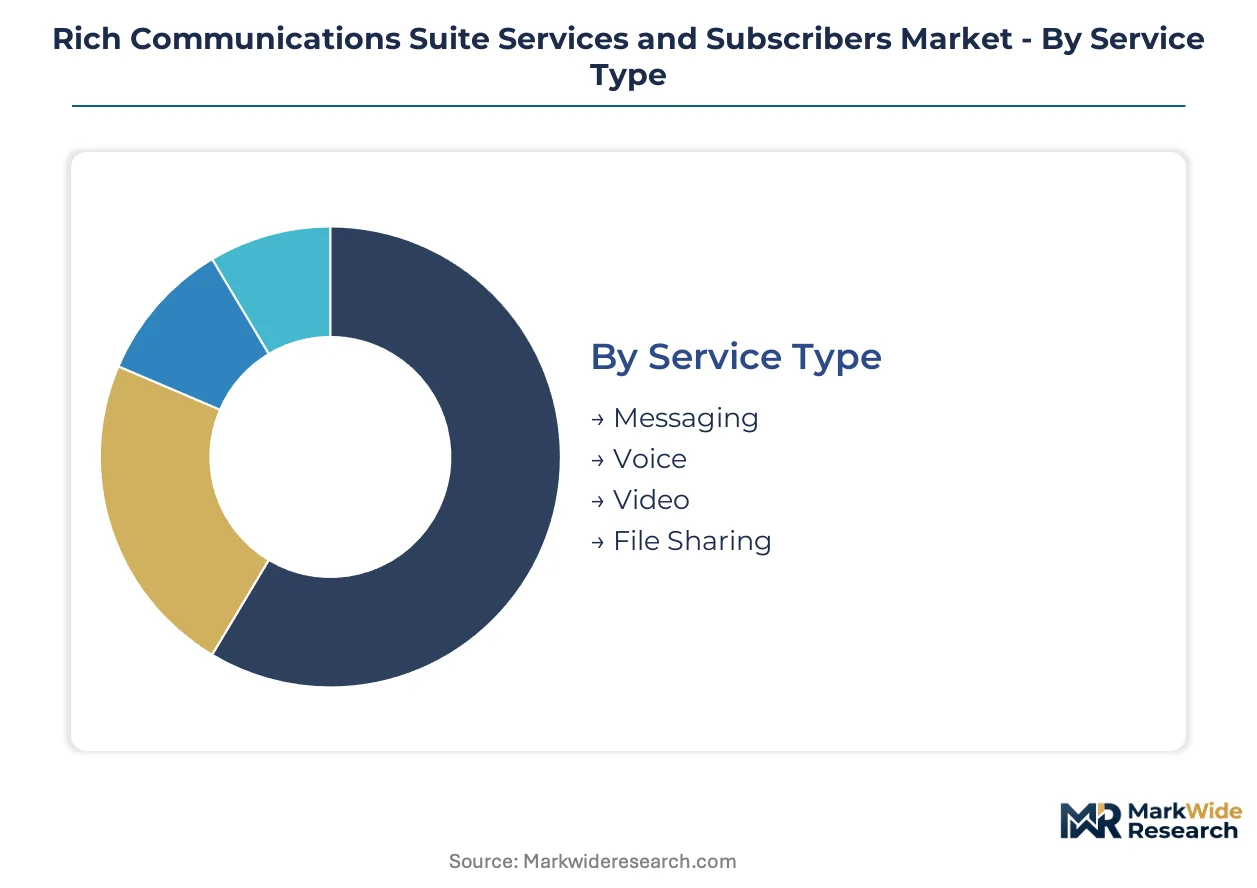
Segmentation in Rich Communications Suite services reveals distinct procurement patterns across carrier networks and enterprise IT stacks. Service providers configure pricing and delivery architectures differently for messaging-heavy deployments versus integrated voice-video platforms.
Service Type:
Messaging services flow through carrier billing systems and enterprise SaaS marketplaces, while voice and video segments concentrate in direct OEM relationships with network equipment vendors.
- Messaging:RCS Business Messaging protocols embed read receipts, typing indicators, and interactive rich cards within native messaging threads. Banking alerts and delivery notifications in South Korea and India concentrate demand as carriers replace SMS infrastructure with IP-based delivery.
- Voice:HD voice over LTE and 5G networks leverages AMR-WB and EVS codecs for carrier-grade call quality. Enterprise contact centers in Germany and Japan drive adoption as they migrate from TDM trunking to SIP-based session management.
- Video:Carrier-integrated video calling and enterprise conferencing solutions.
- File Sharing:High-resolution media transfer and document collaboration within messaging threads.
By volume, Messaging leads. By growth pace, Video is gaining share fastest as enterprises embed visual customer service workflows.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from subscription-based cloud consumption favored by mid-market buyers.
- Cloud-Based:Multi-tenant SaaS platforms eliminate session border controller and media server capex for SMEs. Southeast Asian markets show concentration as regional software vendors displace traditional telecom equipment suppliers through usage-based pricing.
- Hybrid:Split architectures maintain sensitive call control on-premises while bursting media processing to public cloud. Financial services in Singapore and healthcare providers in Switzerland favor this model for data residency compliance.
- On-Premises:Dedicated infrastructure for tier-1 carriers and defense-grade deployments.
- Managed Services:Outsourced operations with SLA-backed availability guarantees.
Cloud-Based deployments dominate new customer acquisition. Hybrid architectures show the steepest expansion trajectory among regulated industries.
End User:
Customer type determines integration complexity, with enterprises demanding CRM connectors and SMEs prioritizing rapid deployment.
- Enterprises:Large organizations require omnichannel integration with Salesforce, ServiceNow, and proprietary customer databases. Airlines and retailers in the United States deploy rich cards for boarding passes and order tracking to eliminate standalone app dependencies.
- SMEs:Mid-market buyers favor pre-configured templates and subscription pricing without dedicated IT staff. India's UPI-integrated merchant messaging demonstrates traction among small businesses seeking payment confirmation automation.
- Individual Consumers:Subscriber services bundled with mobile tariffs.
- Government:Secure communications for public sector and emergency services.
Enterprises command the highest per-seat revenue. SMEs represent the fastest-growing customer acquisition channel.
Technology:
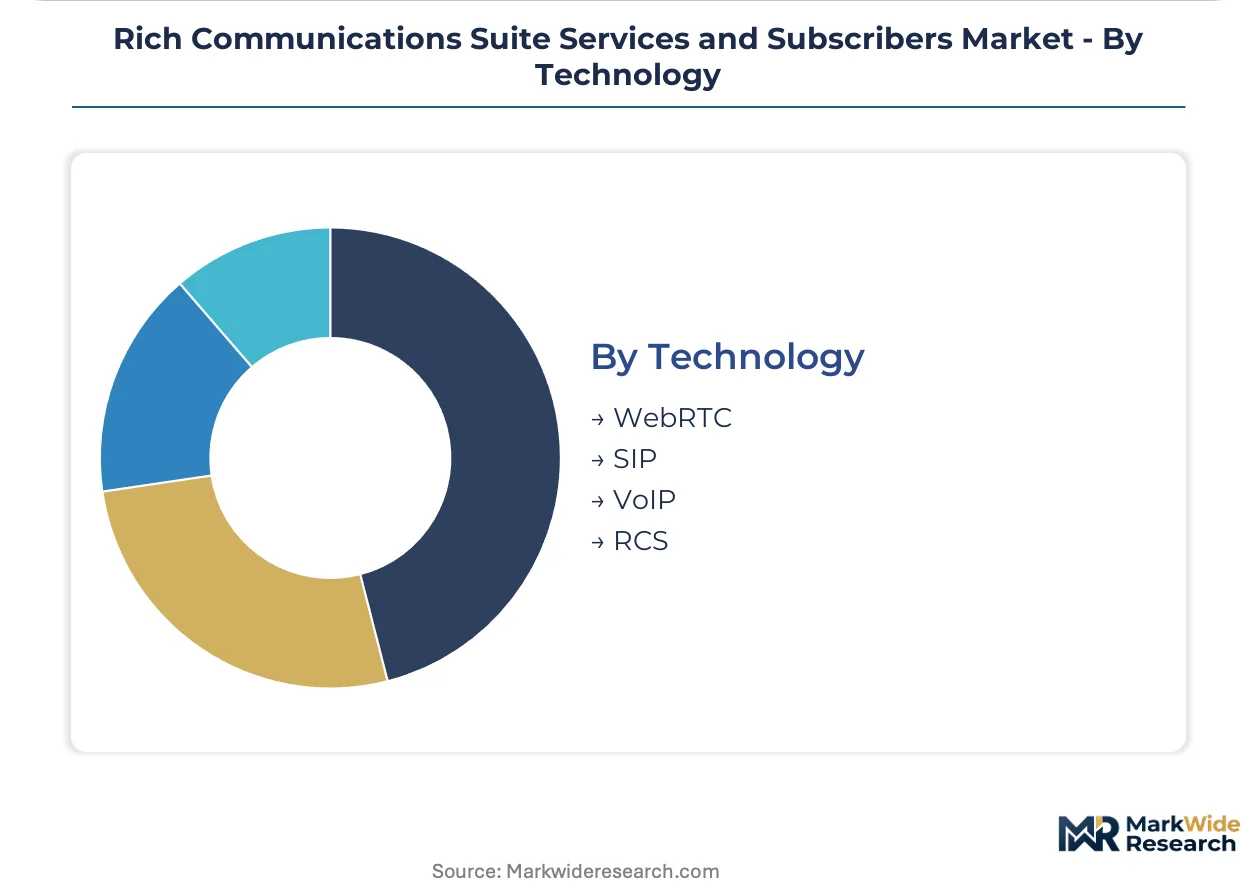
Technology selection hinges on interoperability requirements and ecosystem control, with RCS and WebRTC competing for browser-native and carrier-integrated use cases.
- RCS:GSMA-governed Universal Profile standardizes carrier-to-carrier messaging interoperability. South Korean operators SK Telecom, KT Corporation, and LG Uplus demonstrate complete subscriber coverage through 5G SA core integration.
- WebRTC:Browser-based real-time communications enable desktop-to-mobile handoff without application downloads. European enterprise software vendors leverage this for seamless customer service workflows across devices.
- SIP:Session Initiation Protocol for enterprise trunking and unified communications.
- VoIP:Packet-switched voice delivery over unmanaged internet connections.
RCS anchors carrier messaging strategies. WebRTC expands most quickly in enterprise SaaS integrations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. South Korean carriers absorb premium infrastructure costs for complete RCS coverage, while Indian SMEs drive price-sensitive volume through cloud-native deployments. European markets split between regulated compliance investments and cost-constrained mid-market adoption.
South Korea
SK Telecom, KT Corporation, and LG Uplus have achieved near-complete RCS subscriber penetration through 5G standalone core investments. The Ministry of Science and ICT mandates interoperability standards that accelerate carrier onboarding. Seoul anchors deployment density with enterprise messaging trials in Gangnam's financial district.
United States
Enterprise messaging migration concentrates among airlines and retailers deploying rich cards for boarding passes and order tracking. The FCC governs spectrum allocation and net neutrality frameworks affecting quality-of-service guarantees. Silicon Valley cloud-native vendors and Dallas-Fort Worth telecom hubs compete for carrier infrastructure contracts.
Germany
Enterprise contact centers drive HD voice adoption as they migrate from TDM trunking to SIP-based session management. The EU Digital Markets Act interoperability mandates force gatekeeper platforms to open messaging APIs. Frankfurt's financial services cluster favors hybrid deployments for data residency compliance.
India
UPI-integrated merchant messaging demonstrates traction among small businesses seeking payment confirmation automation. TRAI pushes enriched business messaging standards aligned with digital payment growth. Mumbai's banking sector and Bangalore's SaaS vendors anchor regional demand concentration.
Japan
Enterprise contact centers in Tokyo and Osaka drive adoption of carrier-integrated video calling for customer service workflows. METI influences industrial standards for real-time communications quality. The Kanto region's manufacturing base trials RCS-enabled supply chain notifications.
Rich Communications Suite Services and Subscribers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Cloud-native platform vendors capture SME volume through subscription flexibility, while telecom equipment incumbents anchor carrier-grade infrastructure deployments. Strategic archetypes include Android ecosystem platform operators, network equipment manufacturers, and API-first enterprise communications specialists. Dominant competitive moves encompass hybrid deployment model diversification and vertical integration into edge media processing capabilities.
Within the platform operator tier, Google LLC exemplifies ecosystem-driven standard setting through Android messaging integration. Huawei Technologies and Ericsson occupy positions as network infrastructure anchors, with the former representing manufacturing scale and the latter specialized telecommunications software integration. These three entities collectively illustrate the competitive tension between consumer-facing platform control and carrier-facing infrastructure supply.
| Leading Market Players |
|---|
| Google LLC |
| Huawei Technologies |
| AT&T Inc. |
| Verizon Communications Inc. |
| Vodafone Group plc |
| Ericsson |
| Tata Communications |
| Twilio Inc. |
| Orange |
| Others |
Value Network & Pricing Analysis
Cloud-native session border controllers replacing on-premises hardware simultaneously redistribute supply geography toward Southeast Asian software vendors and compress capital expenditure barriers for SME buyers. This substitution dynamic erodes pricing power among legacy telecom equipment manufacturers while enabling usage-based subscription models that align vendor revenue with customer transaction volumes.
Pricing Analysis
Managed services and SLA-backed support contracts drive lifetime value beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration complexity and uptime guarantees. Cost compression in the economy tier is intensifying because regional cloud vendors from Southeast Asia compete on usage-based rates. SMEs exhibit highest price sensitivity, while tier-1 carriers prioritize carrier-grade reliability over per-seat cost.
Supply Chain Analysis
Strait of Malacca transit underwrites semiconductor component delivery timelines for media processing hardware. Manufacturing concentrates in China, South Korea, and Taiwan for network equipment and edge computing nodes. Component sourcing draws from TSMC foundries, Samsung memory fabrication, and Foxconn assembly operations. Single-source vulnerability persists in advanced 5G baseband chipsets. Distribution runs through carrier procurement departments and enterprise SaaS marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as enterprise messaging demand splinters across regulated financial services, price-sensitive SME merchants, and consumer-facing rich card commerce. This demand-side shift creates distinct buyer archetypes with incompatible procurement preferences.
For Market Incumbents: Fortify carrier relationships through 5G SA core integration investments that embed RCS infrastructure deeper into network architecture. Defend against cloud-native challengers by certifying hybrid deployment models for data residency compliance in Frankfurt and Singapore financial hubs. Prioritize backward integration into edge media processing silicon to capture margin from latency-sensitive video workflows. For New Entrants and Emerging Players: SME merchant messaging in India represents the most penetrable white-space target, where UPI-integrated payment confirmations lack sophisticated rich card implementations. Target healthcare appointment scheduling and logistics delivery notifications in Southeast Asian markets where legacy SMS infrastructure creates service gaps. Pursue channel partnerships with regional SaaS vendors already embedded in small business accounting and inventory systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud communications platforms that consolidated during earlier UCaaS expansion. Five-to-ten year viability hinges on RCS Universal Profile adoption velocity versus WebRTC browser-native alternatives. Monitor GSMA network API standardization progress as inflection indicator for carrier onboarding economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Certification | Enables data residency compliance for Singapore and Frankfurt financial services clusters. |
| Rich Card Commerce Platform Launch | Embeds payment rails and CRM integration directly within RCS messaging threads for retailers. |
| 5G SA Core Partnership | Accelerates carrier onboarding through GSMA network API standardization in South Korea. |
| Edge Media Processing Acquisition | Captures low-latency video workload margins from tier-2 carriers with constrained balance sheets. |
| WebRTC Convergence Development | Enables seamless desktop-to-mobile handoff without application downloads for European enterprises. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with carrier network architects, enterprise IT procurement officers, RCS platform engineers, and SaaS vendor product managers; and secondary validation against GSMA technical specifications, TRAI regulatory filings, FCC spectrum allocation records, and hyperscaler messaging infrastructure disclosures. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against carrier capital expenditure patterns anchored value estimates.
Across the analysis window, the forecasting framework modeled service type segmentation, deployment model migration patterns, end-user procurement complexity tiers, and technology protocol adoption trajectories. CAGRs derived from carrier infrastructure investment cycles and enterprise SaaS subscription renewal rates. Key inputs included 5G standalone deployment timelines and Universal Profile version adoption curves.
Underlying assumptions cover sustained carrier RCS infrastructure investment, GSMA interoperability standard enforcement, and enterprise messaging volume displacement from SMS, with deviation risk concentrated in Apple ecosystem participation decisions and encryption mandate fragmentation across Saudi Arabia and Turkey. Practitioners should keep alternative scenarios live as regulatory data localization requirements and device ecosystem control points evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Walkie Talkie Market
Communication Services
Web Conferencing Market
Communication Services
Dispatch Console Market
Communication Services
Video Conferencing Market
Communication Services
Global Call Center Platform Market
Communication Services
Postal Services Market
Communication Services
Message Handling Systems Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Industrial Communication Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Latin America Postal Service Market
Communication Services
Push-To-Talk Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Audio Conferencing Services Market
Communication Services
Pcaas Market