
 Meeting Solutions Market | 2026-2036
Meeting Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Meeting Solutions Market Insights
Enterprise reseller channels is reshaping how meeting solutions reach end customers, with distributors now bundling hardware, software, and managed services into unified contracts. Zoom Video Communications leverages its brand recognition to sustain direct-to-enterprise relationships alongside these channel shifts. Microsoft Corporation anchors its position through deep integration with productivity suites that span email, document collaboration, and video conferencing. Cisco Systems differentiates through dedicated meeting room hardware that enterprises deploy for executive and board-level environments.
Meeting solutions encompass software platforms, hardware endpoints, and managed services that enable real-time audio, video, and data collaboration across distributed participants, typically requiring sub-150 millisecond latency for natural conversation flow and AES-256 encryption for enterprise security compliance. Cloud-based deployment models lead revenue generation as organizations abandon capital-intensive on-premise infrastructure for subscription consumption. Video conferencing within product type categories captures the largest addressable base, while collaboration tools that embed document sharing and persistent workspaces represent the fastest-expanding margin pool as vendors bundle adjacent functionality.
FCC net neutrality frameworks and FTC consumer protection standards shape how US providers manage traffic prioritization and data handling in hosted meeting services, while GDPR and the EU AI Act impose cross-border data residency and algorithmic transparency obligations on platforms serving European enterprises. ISO/IEC 27001 certification has become a baseline procurement filter for government agencies and regulated industries selecting meeting infrastructure. Stakeholders must monitor how evolving encryption backdoor debates and sovereignty requirements fragment platform architectures across jurisdictional boundaries.
Market Dynamics
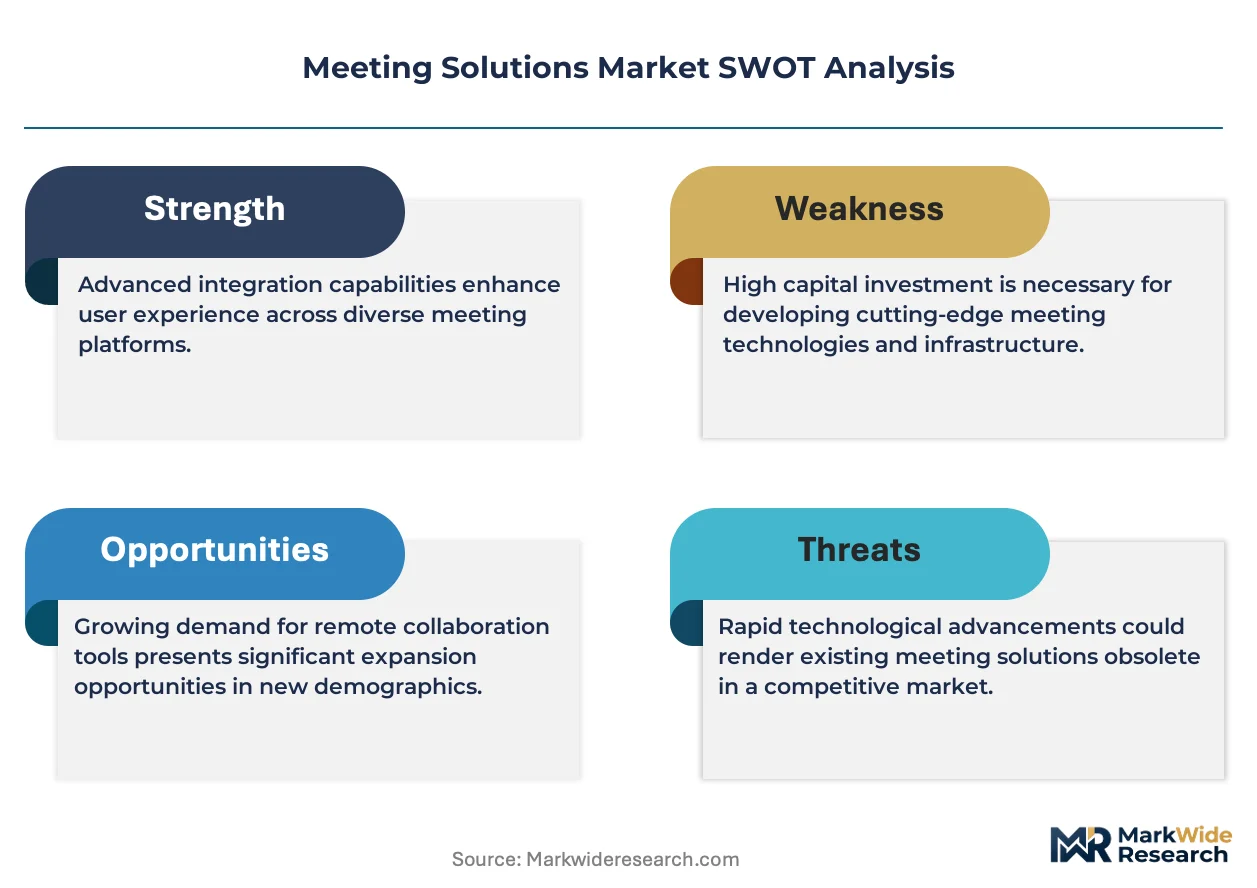
Hybrid work infrastructure mandates are forcing enterprises to rebuild physical-digital meeting environments, compressing procurement cycles and bundling hardware-software-service contracts into unified vendor relationships.
Growth Catalysts
- EU NIS2 Directive:Cybersecurity compliance deadlines are accelerating cloud migration timelines for European enterprises, expanding managed service attach rates.
- Healthcare sector digitization:HIPAA-covered entities are deploying encrypted video platforms for telemedicine workflows, creating specialized procurement verticals.
- AI-powered transcription:Real-time meeting summarization is reducing post-meeting documentation overhead, driving premium tier subscriptions.
Market Restraints
- Semiconductor supply concentration:Video codec chip fabrication relies on Taiwan-based foundries, exposing hardware endpoint production to geopolitical disruption.
- GDPR data residency friction:Cross-border meeting traffic faces sovereignty-driven architecture fragmentation, raising operational complexity for multinational deployments.
- WebRTC browser standardization:Inconsistent codec support across Safari, Chrome, and Edge creates interoperability gaps requiring client-side software workarounds.
Strategic Opportunities
- India SME penetration:PLI scheme incentives for electronics manufacturing are reducing hardware costs for domestic mid-market buyers.
- ISO/IEC 27001 bundling:Certification-inclusive pricing is opening regulated industry segments previously blocked by procurement security filters.
- Spatial audio-VR convergence:Immersive meeting room experiences are creating new hardware refresh cycles for executive board environments.
Industry Challenges
- Legacy PBX integration:SIP trunk configuration complexity is extending deployment timelines for enterprises with on-premise telephony investments.
- Encryption key management:BYOK (bring-your-own-key) implementations require specialized DevOps talent scarce outside major technology hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meeting Solutions Market |
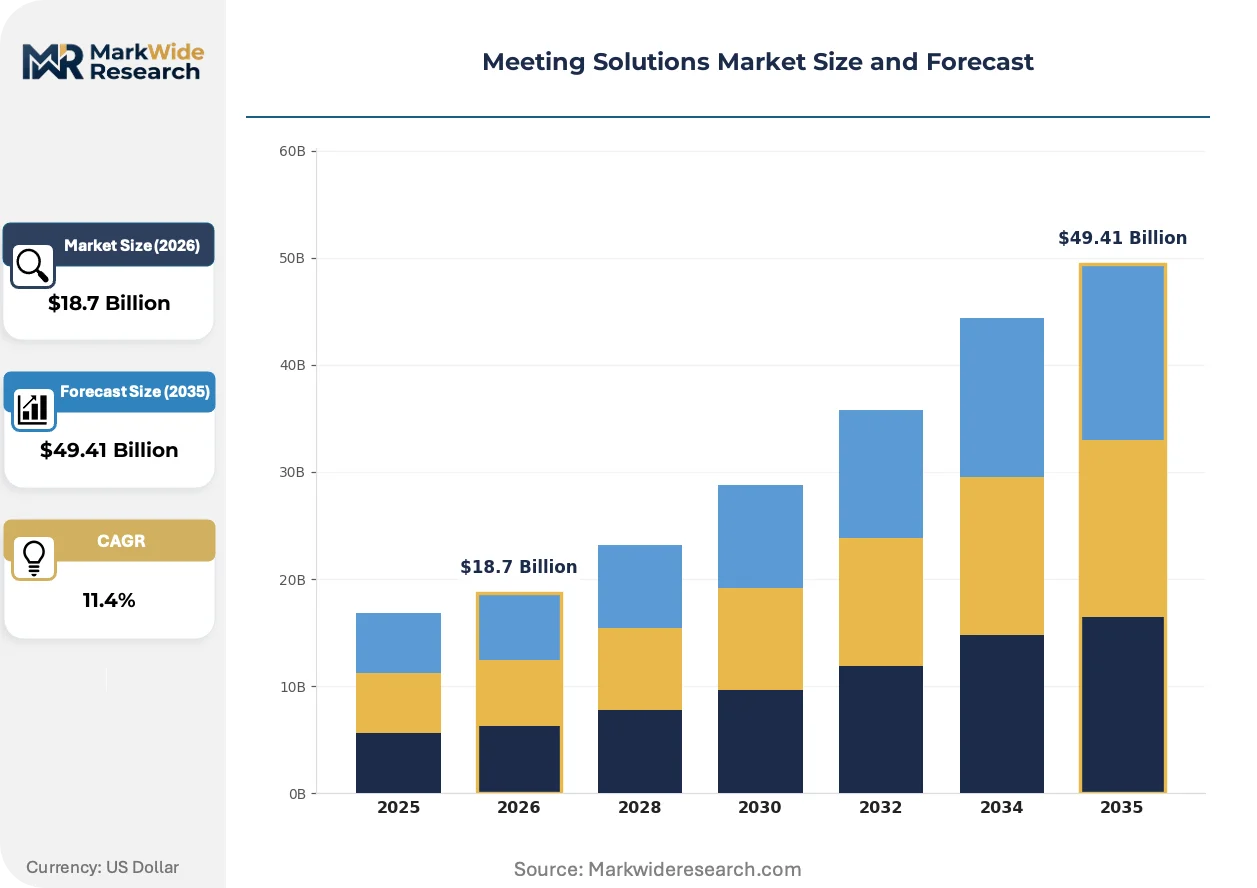
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing, Collaboration Tools, Document Sharing, Meeting Rooms Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile End User: Enterprises, Educational Institutions, Government Agencies, Freelancers Integration Level: Full Integration, Partial Integration, Standalone, Custom Solutions |
| Companies Covered | Google LLC, BlueJeans Network, Zoom Video Communications, Avaya Holdings Corp., LogMeIn, Microsoft Corporation, RingCentral, Lifesize, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meeting Solutions Market Trends and Innovations
Artificial intelligence inference at the edge is restructuring how meeting platforms process audio, video, and contextual data, reducing cloud egress costs while enabling real-time features previously requiring datacenter round-trips.
AI noise suppression running on endpoint hardware is collapsing the distinction between dedicated meeting room systems and commodity laptops. Financial services compliance teams are adopting these capabilities fastest, replacing hardware DSP investments with software-defined audio pipelines. The compression of hardware-software boundaries is forcing AV integrators to retrain technical staff around cloud configuration rather than physical installation.
GDPR Article 35 data protection impact assessments are mandating algorithmic transparency for AI-enabled meeting features. European procurement teams are now requiring documented logic for speaker identification and sentiment analysis tools. German automotive manufacturers have delayed platform selections pending vendor compliance documentation, creating competitive advantage for providers with pre-certified AI governance frameworks.
Enterprise buying committees are consolidating vendor relationships around productivity suite ecosystems rather than best-of-breed point solutions. Mid-market IT departments are abandoning standalone video contracts in favor of bundled Microsoft or Google workspace commitments. This concentration pattern is most pronounced in United States healthcare and professional services verticals, where procurement standardization reduces support ticket fragmentation.
Meeting Solutions Market Segmentation
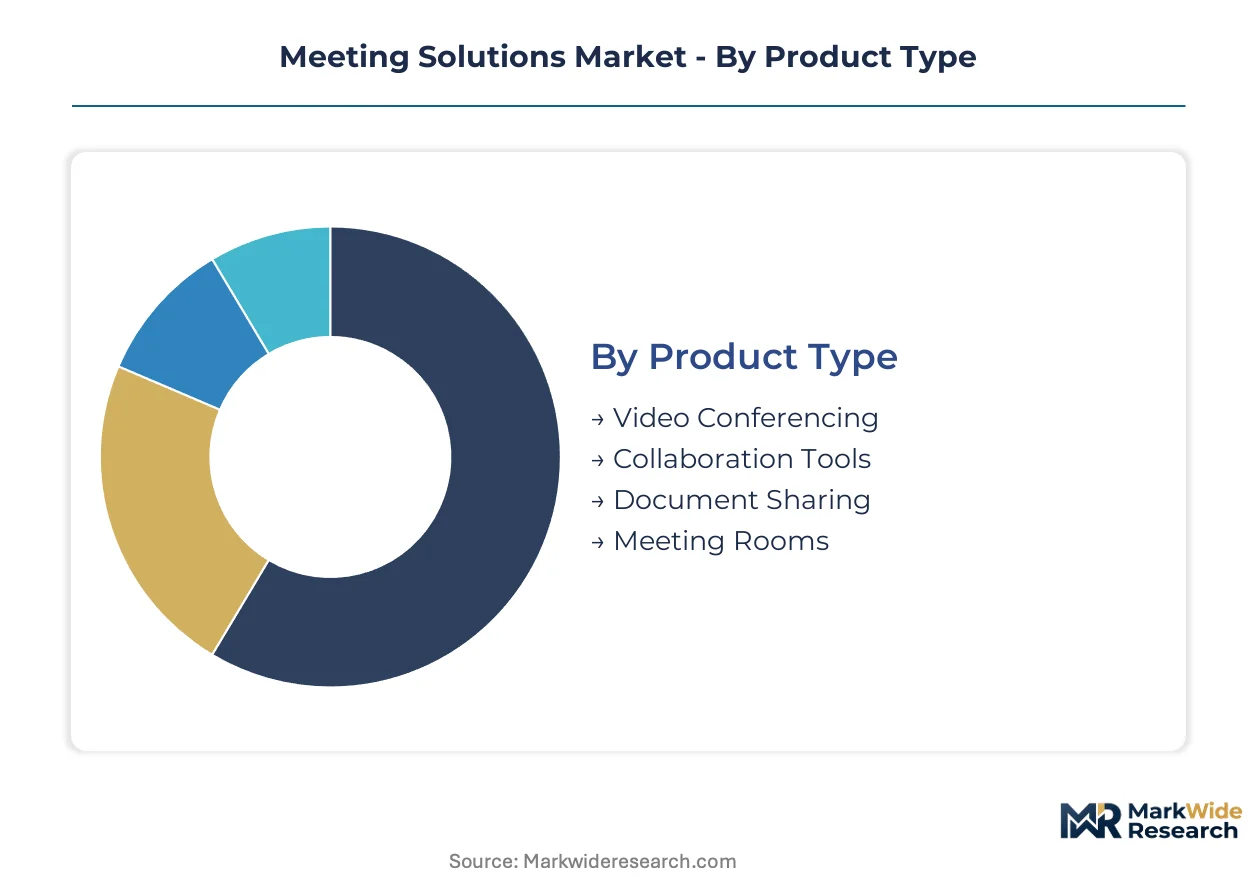
Meeting solutions vendors architect product portfolios around four intersecting dimensions that determine procurement workflows and margin structures. Deployment models dictate recurring revenue predictability, while integration requirements filter vendor shortlists before price negotiation begins.
Product Type:
Mature video conferencing platforms anchor enterprise procurement, while emerging categories reshape how organizations conceptualize meeting workflows beyond synchronous video.
- Video Conferencing:Real-time audio-video platforms requiring sub-150 millisecond latency for natural conversation flow, typically delivered via cloud infrastructure with AES-256 encryption. Healthcare systems in the United States concentrate replacement demand here as HIPAA-covered entities retire legacy telemedicine infrastructure for integrated platforms.
- Collaboration Tools:Persistent workspace applications embedding document co-editing, threaded messaging, and asynchronous project tracking alongside synchronous features. German automotive manufacturers are expanding procurement of these tools under EU AI Act algorithmic transparency mandates that require documented logic for AI-enabled features.
- Document Sharing:Secure file synchronization and version control systems integrated into meeting workflows.
- Meeting Rooms:Purpose-built hardware-software bundles for executive and board-level physical environments.
Video Conferencing retains volume leadership; Collaboration Tools holds the steepest expansion curve.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models that dominate new procurement.
- Cloud-Based:Subscription-consumed infrastructure eliminating datacenter capital expenditure, with vendors managing encryption key rotation and datacenter residency compliance. European enterprises accelerate migration here under NIS2 Directive cybersecurity deadlines that compress procurement cycles.
- Hybrid:Architectures splitting sensitive processing on-premise while leveraging cloud scale for distribution, common in financial services with legacy compliance investments. Japanese financial institutions concentrate demand for these configurations where METI guidelines intersect with internal risk frameworks.
- On-Premise:Self-managed infrastructure retained by organizations with specialized sovereignty or latency requirements.
- Mobile:Endpoint-optimized delivery for field workforce and distributed contractor access.
Cloud-Based commands the dominant procurement share; Hybrid deployment is climbing fastest among regulated verticals.
End User:
Customer type determines contract structure complexity and support service attach rates.
- Enterprises:Organizations with 1,000+ employees purchasing unified hardware-software-service contracts through consolidated vendor relationships. United States healthcare and professional services verticals concentrate here as procurement standardization reduces support ticket fragmentation.
- Educational Institutions:K-12 and higher education buyers with semester-based procurement cycles and accessibility compliance requirements.
- Government Agencies:Public sector entities requiring ISO/IEC 27001 certification and documented supply chain provenance as baseline procurement filters.
- Freelancers:Individual practitioners purchasing through self-service channels with minimal implementation support.
Enterprises generate the largest contract values; Educational Institutions are expanding procurement most quickly as hybrid learning infrastructure becomes permanent.
Integration Level:
Application depth filters vendor selection before pricing enters negotiation, with integration complexity extending deployment timelines.
- Full Integration:Native embedding within productivity suite ecosystems spanning email, document collaboration, and video conferencing. Mid-market IT departments in the United States concentrate procurement here, abandoning standalone video contracts for bundled Microsoft or Google workspace commitments.
- Partial Integration:API-connected workflows linking meeting platforms to adjacent business applications without native unification.
- Standalone:Point solutions requiring manual data transfer between systems, now largely displaced in enterprise segments.
- Custom Solutions:Bespoke development for specialized compliance or workflow requirements in defense and intelligence sectors.
Full Integration captures the dominant procurement preference; Custom Solutions maintains premium pricing power despite limited volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC net neutrality frameworks and FTC consumer protection standards anchor United States procurement criteria, while GDPR and the EU AI Act impose cross-border data residency obligations on platforms serving European enterprises. Japanese METI guidelines intersect with internal risk frameworks to shape hybrid deployment preferences among financial institutions.
United States
Healthcare systems concentrate replacement demand as HIPAA-covered entities retire legacy telemedicine infrastructure for integrated platforms. FCC frameworks shape traffic prioritization and data handling in hosted meeting services. Greater Boston and Pacific Northwest clusters drive enterprise adoption of AI-powered transcription features.
Germany
Automotive manufacturers expand procurement of collaboration tools under EU AI Act algorithmic transparency mandates requiring documented logic for AI-enabled features. GDPR Article 35 data protection impact assessments mandate algorithmic transparency for AI-enabled meeting features. Bavaria and Baden-Württemberg industrial clusters delay platform selections pending vendor compliance documentation.
Japan
Financial institutions concentrate demand for hybrid deployment configurations where METI guidelines intersect with internal risk frameworks. The country's central bank and financial regulators emphasize operational resilience for critical digital infrastructure. Tokyo and Osaka metropolitan areas anchor enterprise procurement of purpose-built meeting room hardware.
India
PLI scheme incentives for electronics manufacturing reduce hardware costs for domestic mid-market buyers. TRAI regulations shape data localization requirements for cloud-hosted communication services. Maharashtra and Karnataka technology corridors drive SME penetration of subscription-consumed meeting infrastructure.
United Kingdom
Professional services verticals concentrate procurement standardization efforts to reduce support ticket fragmentation. UK GDPR and Information Commissioner's Office guidance shape algorithmic transparency requirements for AI-enabled features. London and Southeast England clusters anchor enterprise reseller channel consolidation.
Meeting Solutions Market Competitive Landscape
Productivity suite integrators and dedicated video platform specialists split the market into competing ecosystem logics. Consolidation pressures favor vendors bundling hardware, software, and managed services into unified contracts. Two strategic archetypes dominate: suite-native providers leveraging email and document collaboration integration, and best-of-breed specialists defending through meeting room hardware differentiation. Competitive moves concentrate on strategic partnerships with enterprise reseller channels and portfolio diversification into adjacent collaboration tools.
Within the suite-native tier, Microsoft Corporation and Google LLC exemplify productivity ecosystem anchoring, while Zoom Video Communications occupies a position representing direct-to-enterprise brand recognition alongside channel shifts. Cisco Systems sits within the hardware-differentiated archetype, exemplifying dedicated meeting room system specialization for executive environments. These three company structures represent the dominant competitive positioning patterns visible across the vendor landscape.
| Leading Market Players |
|---|
| Google LLC |
| BlueJeans Network |
| Zoom Video Communications |
| Avaya Holdings Corp. |
| LogMeIn |
| Microsoft Corporation |
| RingCentral |
| Lifesize |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Semiconductor supply concentration in Taiwan-based foundries determines both the premium commanded by configured-to-order hardware endpoints and the vulnerability of standard-tier pricing to geopolitical disruption. Enterprise buyers face widening spreads between certified supply chains and commodity alternatives as export controls reshape component availability.
Pricing Analysis
Configured-to-order meeting room systems command substantial premiums over standard cloud subscriptions due to ISO/IEC 27001 certification requirements and on-premise hardware deployment. Pricing stratifies across premium, standard, and economy tiers based on encryption key management complexity and managed service attach rates. Cost compression in the standard tier is intensifying because mid-market IT departments consolidate around bundled productivity suite contracts. Educational institutions exhibit highest price sensitivity, while financial services buyers prioritize compliance-grade offerings regardless of cost.
Supply Chain Analysis
Export-control restrictions on advanced video codec chips limit flows from Taiwan and South Korea to certain end-use categories, compressing hardware availability timelines for sovereign-sensitive deployments. Component sourcing draws from Taiwan for semiconductors, China for camera modules, and Mexico for final assembly of North American-bound endpoints. Single-source vulnerability concentrates in 7nm and below fabrication capacity. Distribution runs through enterprise reseller channels that bundle hardware procurement with managed service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meeting solutions market represents a high-growth disruption as EU AI Act algorithmic transparency mandates force platform architecture redesigns. This regulatory inflection compresses procurement cycles while elevating compliance-certified vendors.
For Market Incumbents: Pre-empt margin erosion from productivity suite bundling by deepening hardware-software integration in executive meeting room environments. Invest in pre-certified AI governance frameworks before German automotive manufacturers complete vendor shortlists. Channel control through exclusive reseller partnerships defends against direct-to-enterprise disintermediation.
For New Entrants and Emerging Players: Establish a beachhead in India's SME segment where PLI scheme incentives reduce hardware cost barriers for domestic mid-market buyers. Target educational institutions with semester-based procurement cycles and accessibility compliance requirements. A certification-inclusive pricing model opens regulated verticals previously blocked by security procurement filters.
For Investors and Strategic Acquirers: EU NIS2 Directive implementation reshapes the acquisition landscape by accelerating cloud migration timelines and expanding managed service attach rates. Long-term viability centers on vendors with sovereign-compliant data residency architectures and AI transparency documentation. Watch for platform selections delayed pending vendor compliance documentation as the inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Framework Certification | EU AI Act compliance documentation unlocks German automotive procurement verticals. |
| Hardware-Software Bundle Expansion | Integrated meeting room systems capture executive environments resistant to suite consolidation. |
| Managed Service Attach Rate Growth | NIS2 Directive deadlines accelerate European enterprise migration to subscription-consumed infrastructure. |
| Spatial Audio-VR Convergence Investment | Immersive boardroom experiences create hardware refresh cycles distinct from commodity video. |
| Enterprise Reseller Channel Partnership | Unified contract bundling defends against direct-to-enterprise disintermediation by platform specialists. |
Research Methodology
Initial hypotheses were tested against primary input from CIOs, IT procurement officers, AV integration specialists, and channel distribution partners and refined through secondary validation across vendor SEC filings, hyperscaler capex disclosures, Gartner enterprise software tracking, and EU regulatory implementation notices. Bottom-up demand modeling across deployment modes and organization sizes was triangulated against top-down market sizing from infrastructure spending indicators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled across product type, deployment architecture, end-user scale, and integration complexity tiers. CAGRs were derived from fitted growth curves applied to adoption penetration rates and replacement cycle compression. Forecast inputs incorporated NIS2 Directive compliance deadlines and healthcare telemedicine infrastructure replacement waves.
Stress conditions across semiconductor supply disruption severity, cross-border data residency enforcement intensity, and productivity suite bundling penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and enterprise procurement standardization patterns. Material shifts in encryption backdoor legislation or foundry capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Latin America Postal Service Market
Communication Services
Industrial Communication Market
Communication Services
Consumer Communication Services Market
Communication Services
Voice Commerce Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Dispatch Console Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Walkie Talkie Market
Communication Services
Outbound Telemarketing Market
Communication Services
Push-To-Talk Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Cloud Communication Platform Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Postal Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Voip Services Market