
 Far-Field Speech and Voice Recognition Market | 2026-2036
Far-Field Speech and Voice Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
Far-Field Speech and Voice Recognition Market Analysis
Automotive cockpit integration is restructuring how semiconductor suppliers prioritize far-field microphone arrays and edge AI voice processing. NXP Semiconductors leverages its automotive-grade portfolio to anchor in-vehicle voice control systems across European and North American OEM programs. Qualcomm competes through Snapdragon platform integration that bundles acoustic echo cancellation with on-device natural language processing. Knowles Corporation specializes in MEMS microphone miniaturization for multi-microphone beamforming configurations that dominate premium smart speaker builds.
Far-field speech and voice recognition encompasses audio capture and processing systems designed to isolate and interpret spoken commands from distances exceeding one meter amid ambient noise, relying on microphone arrays with beamforming algorithms and acoustic echo cancellation to achieve signal clarity. The primary commercial purpose centers on enabling hands-free human-machine interaction in shared acoustic environments where near-field microphones fail. AI Algorithms represent the fastest-expanding technology segment as on-device neural processing displaces cloud-dependent inference for latency-sensitive applications. Smart Speakers remain the largest product type by installed base though Conference Phones are capturing disproportionate margin growth as enterprise hybrid work patterns stabilize. Automotive end-user applications are accelerating fastest among verticals as cabin voice control becomes standard in electric vehicle architectures.
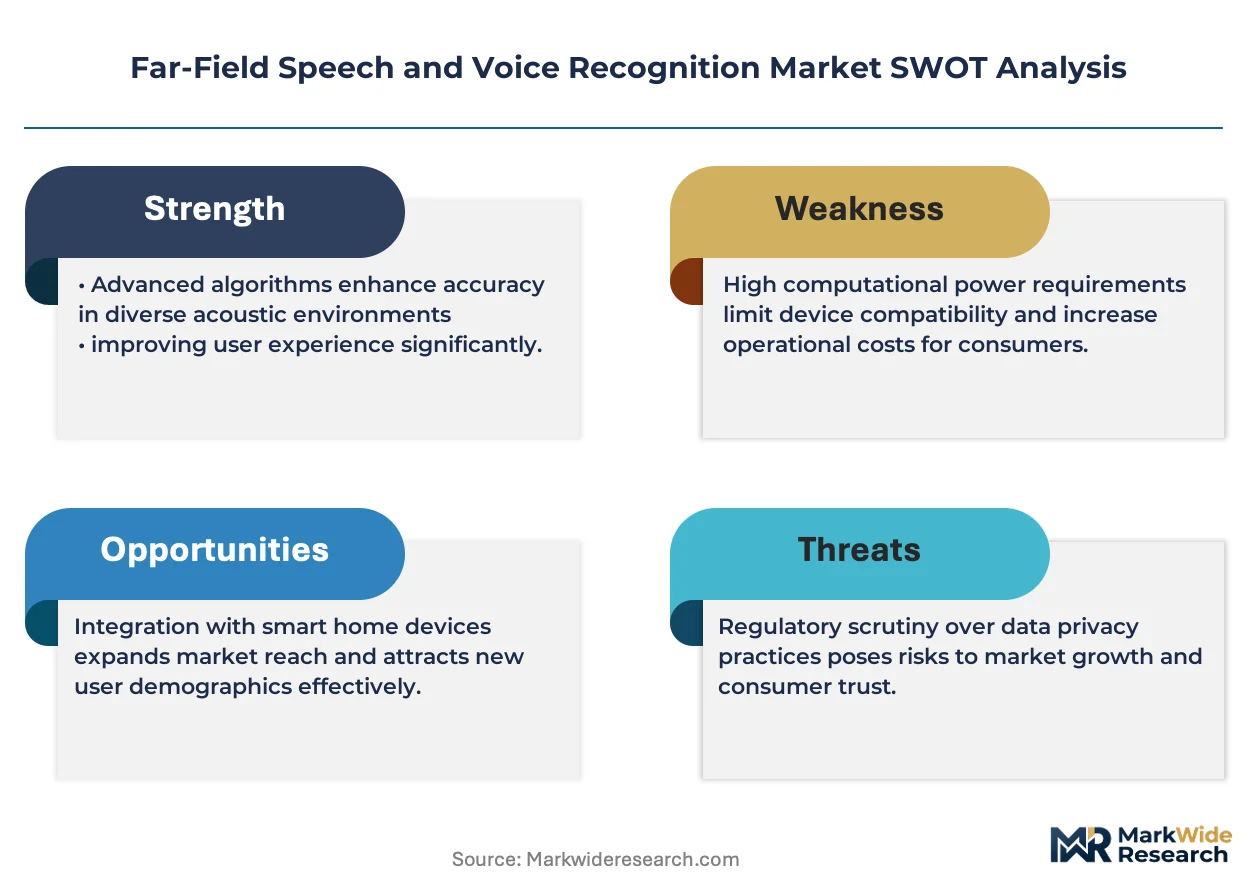
FCC equipment authorization requirements govern radio-enabled voice devices in the United States while the EU AI Act imposes risk classification obligations on biometric voice recognition systems sold in Europe. GDPR data minimization principles constrain cloud voice storage architectures and push vendors toward edge-computing implementations that process utterances locally. Stakeholders must monitor evolving algorithmic accountability standards across multiple jurisdictions while calibrating R&D allocation between cloud accuracy and privacy-preserving on-device inference.
Market Dynamics
Automotive cockpit integration is restructuring procurement priorities among OEMs, forcing semiconductor suppliers to prioritize edge AI voice processing over cloud-dependent architectures. This shift is compressing development cycles for far-field microphone arrays while elevating compliance burdens under emerging biometric regulations.
Growth Catalysts
- EU AI Act Risk Classification:Mandatory conformity assessments for biometric voice recognition systems sold in Europe are accelerating vendor investment in privacy-preserving edge computing architectures that process utterances locally.
- Electric Vehicle Cabin Architectures:Standardized voice control integration in EV platforms is absorbing multi-microphone beamforming configurations as baseline equipment across premium and mid-tier vehicle segments.
- Shenzhen-Hangzhou Manufacturing Clusters:Concentrated smart home device production in these Chinese cities is driving economies of scale for MEMS microphone components and neural processing units.
Market Restraints
- GDPR Data Minimization Constraints:Cloud voice storage architectures face structural limitations under European data protection principles, forcing costly reengineering toward on-device inference models.
- MEMS Foundry Concentration:Advanced microphone manufacturing depends on limited Taiwan and South Korea fabrication capacity, creating supply vulnerability for beamforming array production.
- Acoustic Echo Cancellation Complexity:Technical limitations in separating voice commands from cabin audio output in automotive environments require specialized DSP engineering that extends development timelines.
Strategic Opportunities
- Enterprise Conference Phone Modernization:Hybrid work stabilization is creating white space for far-field systems that integrate acoustic echo cancellation with on-device natural language processing in corporate meeting rooms.
- India Smart Home Penetration:Underdeveloped voice-controlled appliance adoption in Indian urban households presents expansion potential for Mandarin-speaking manufacturers seeking geographic diversification.
- CE Marking Harmonization:Unified European conformity assessment procedures for radio-enabled voice devices are reducing fragmentation costs for vendors targeting multiple EU member states.
Industry Challenges
- Edge AI Talent Scarcity:Shortage of engineers proficient in neural network quantization for resource-constrained voice processors is delaying product roadmaps at mid-tier semiconductor suppliers.
- FCC Equipment Authorization Timelines:Radio-enabled voice device certification in the United States requires extended testing cycles for electromagnetic compatibility that compress market entry windows.
- Legacy Vehicle Platform Integration:Retrofitting far-field voice control into existing automotive electrical architectures demands complex middleware development that strains OEM-Supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Far-Field Speech and Voice Recognition Market |
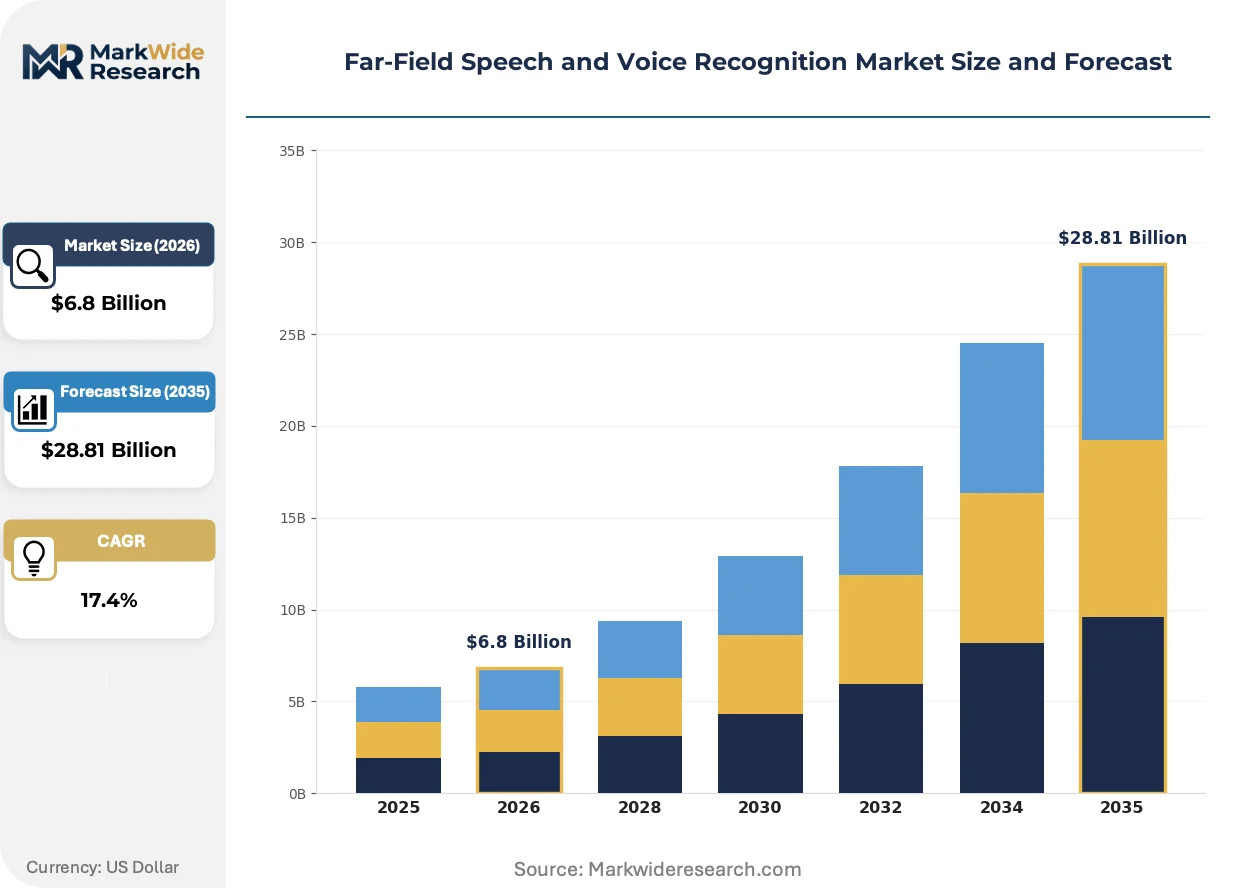
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
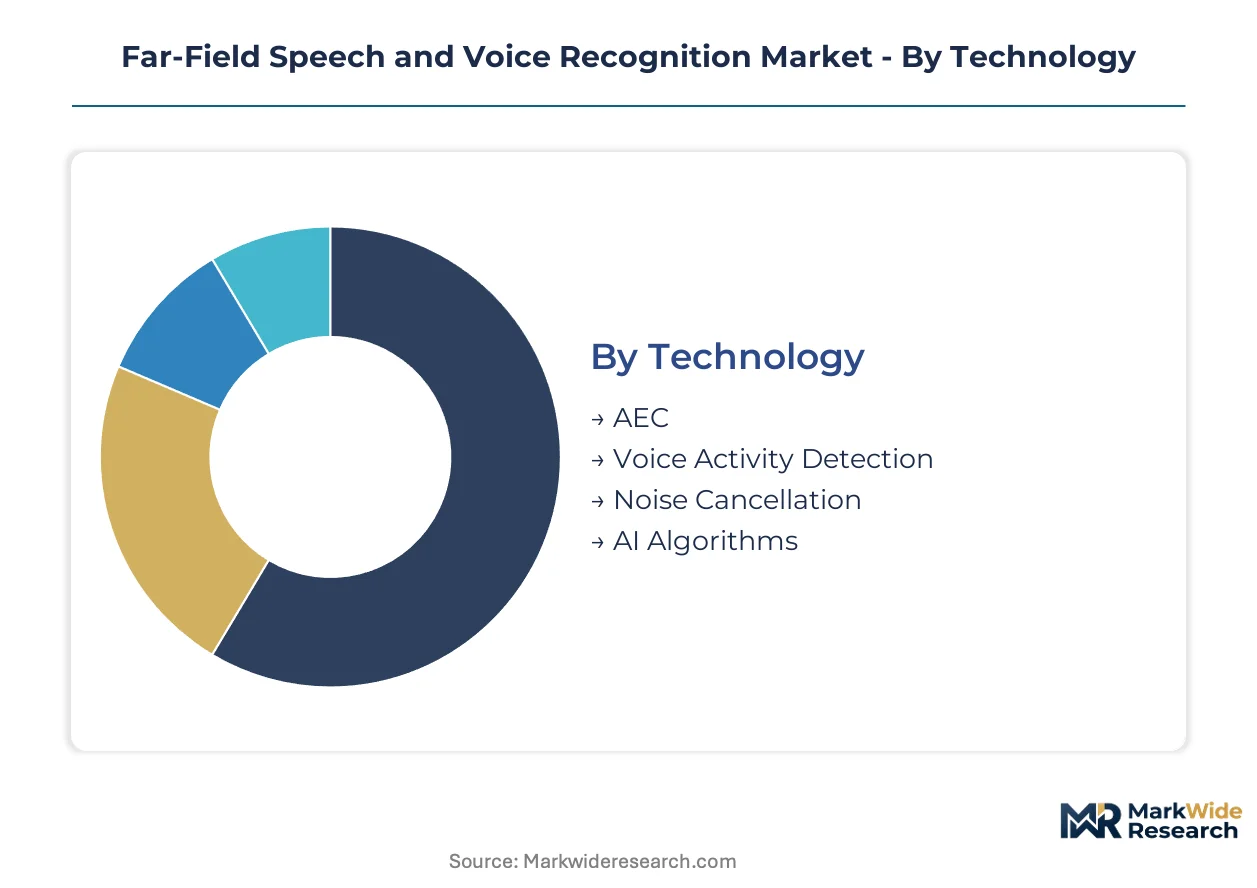
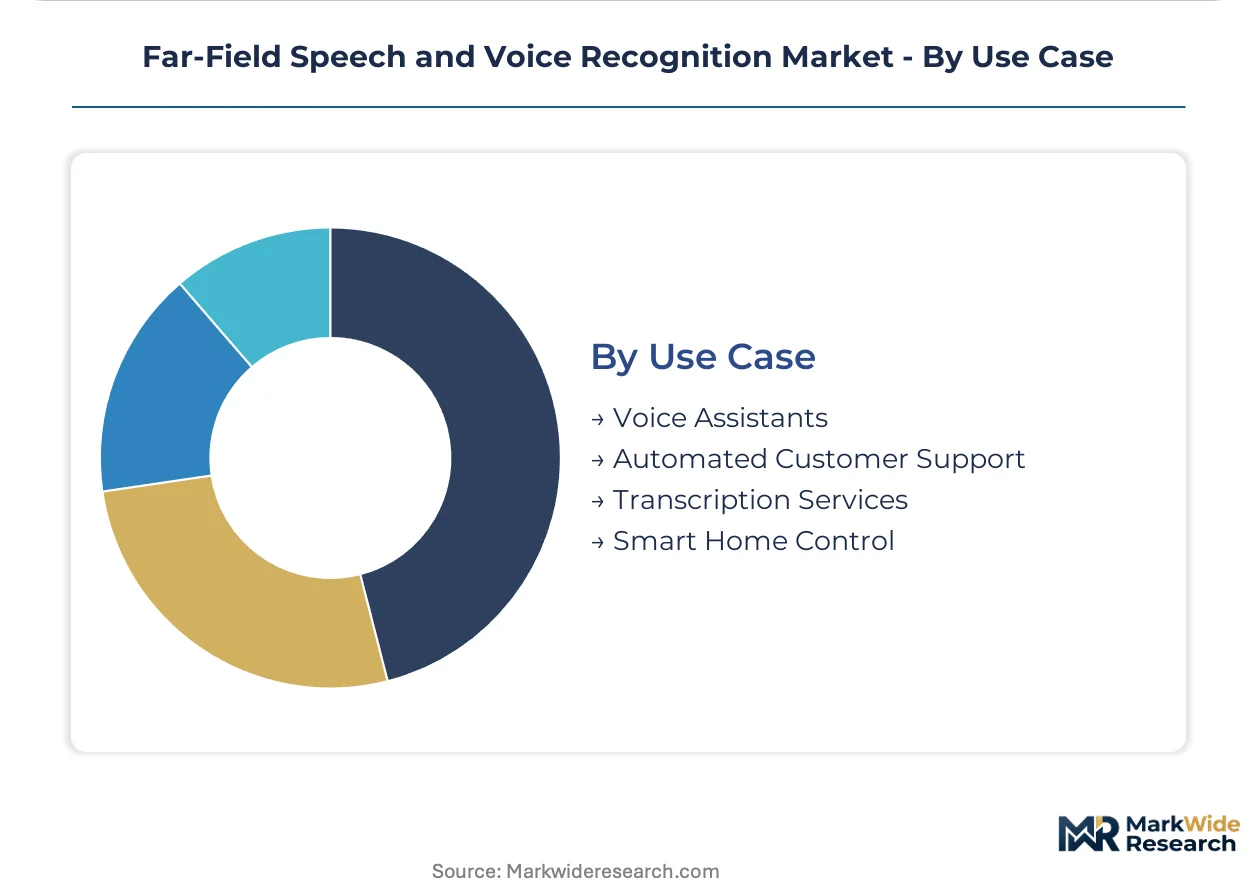
| Segmentation | Technology: AEC, Voice Activity Detection, Noise Cancellation, AI Algorithms Product Type: Smart Speakers, Conference Phones, Wearable Devices, Home Appliances End User: Consumer Electronics, Automotive, Healthcare, Industrial Applications Use Case: Voice Assistants, Automated Customer Support, Transcription Services, Smart Home Control |
| Companies Covered | NXP Semiconductors, STMicroelectronics, Qualcomm, Infineon Technologies, Knowles Corporation, Harman International, Cirrus Logic, Microchip Technology, Synaptics Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Far-Field Speech and Voice Recognition Market Emerging Trajectories
Edge AI inference is absorbing voice processing workloads previously routed to cloud infrastructure, compressing latency metrics while elevating hardware complexity requirements. This architectural pivot is reshaping competitive positioning across microphone array suppliers and neural processing unit vendors.
Neural network quantization for voice recognition is absorbing computational workloads previously handled by datacenter GPUs, enabling real-time command interpretation on battery-constrained devices. Automotive OEMs in Germany and Japan are adopting these architectures fastest, integrating them into electric vehicle cockpit systems that demand sub-200-millisecond response times. The shift is absorbing margin from cloud API providers while concentrating value capture in edge silicon and embedded software stacks.
The EU AI Act imposes risk classification obligations on biometric voice recognition systems, requiring high-risk applications to maintain detailed technical documentation and human oversight protocols. Industrial consequence includes mandatory conformity assessments that extend product launch timelines by 6-12 months for European market entry. Smart speaker vendors are responding by bifurcating product lines into privacy-preserving edge-only configurations for Europe versus cloud-enhanced variants for less regulated markets.
Enterprise procurement of voice-enabled conference systems is consolidating around integrated platform vendors that bundle hardware, acoustic processing software, and meeting management applications. Channel disruption is displacing standalone audio equipment distributors in favor of IT-managed service contracts that include device lifecycle support. This pattern is most visible in North American Fortune 500 deployments, where facilities management teams are ceding technology acquisition authority to centralized procurement functions.
Far-Field Speech and Voice Recognition Market Segmentation
Far-field speech and voice recognition procurement diverges sharply across application environments, with automotive OEMs prioritizing sub-200-millisecond latency while smart home buyers optimize for cost-per-microphone array. Technology selection directly determines whether processing occurs at the edge or in cloud infrastructure, with profound implications for compliance architecture and recurring revenue models.
Technology:
Semiconductor buyers prioritize latency specifications and privacy architecture when selecting signal processing technologies for voice-enabled products.
- AI Algorithms:Neural network quantization enables real-time command interpretation on battery-constrained devices without cloud dependency. German and Japanese automotive OEMs are absorbing these architectures fastest for electric vehicle cockpit integration where GDPR data minimization constraints favor local processing.
- Acoustic Echo Cancellation (AEC):DSP-based separation of voice commands from simultaneous audio output requires specialized engineering for automotive cabin environments. Technical complexity extends development timelines for Tier-1 suppliers serving premium vehicle programs.
- Voice Activity Detection:Low-power silicon implementations trigger wake-word processing while conserving battery in wearable form factors.
- Noise Cancellation:Beamforming array processing isolates target speech from ambient interference in shared acoustic spaces.
Volume sits with Acoustic Echo Cancellation; growth tilts toward AI Algorithms.
Product Type:
Enterprise procurement patterns now favor integrated platform vendors over standalone hardware distributors in corporate meeting room deployments.
- Smart Speakers:Multi-microphone beamforming configurations dominate residential installations, with Shenzhen and Hangzhou manufacturing clusters driving MEMS component economies of scale. Privacy-preserving edge-only variants are bifurcating from cloud-enhanced models under EU AI Act risk classification requirements.
- Conference Phones:Hybrid work stabilization is capturing disproportionate margin growth as IT-managed service contracts displace traditional audio equipment channels. Fortune 500 facilities teams are ceding acquisition authority to centralized procurement functions that bundle hardware with meeting management applications.
- Wearable Devices:Miniaturized microphone arrays face battery and thermal constraints in wrist-worn and ear-worn form factors.
- Home Appliances:Voice control integration is shifting from premium to mid-tier washing machines, refrigerators, and climate systems.
Installed base concentrates in Smart Speakers; Conference Phones are climbing the fastest.
End User:
Compliance burden intensity varies dramatically across verticals, with biometric voice recognition in healthcare triggering the most stringent documentation requirements.
- Automotive:Standardized voice control integration is absorbing multi-microphone configurations as baseline equipment across electric vehicle platforms. Cabin architectures demand specialized acoustic echo cancellation to separate commands from infotainment audio output.
- Consumer Electronics:Smart home device manufacturing clusters around Shenzhen supply global demand for voice-controlled appliances, though Indian urban households remain underpenetrated for Mandarin-speaking manufacturers seeking geographic diversification.
- Healthcare:HIPAA constraints in the United States and GDPR biometric provisions in Europe impose documentation and human oversight protocols on clinical voice recognition deployments.
- Industrial Applications:Factory floor noise environments require robust microphone array specifications for hands-free equipment control.
Revenue concentrates in Consumer Electronics; Automotive is gaining share fastest.
Use Case:
Monetization models diverge between one-time hardware sales and recurring API access, with transcription services commanding the highest per-minute software margins.
- Voice Assistants:Wake-word detection and natural language understanding dominate consumer interaction patterns, with edge inference displacing cloud routing for latency-sensitive automotive and wearable applications.
- Smart Home Control:Appliance command integration is expanding from lighting and climate to security systems and kitchen equipment.
- Automated Customer Support:Enterprise call center deployments are consolidating around platform vendors that bundle acoustic processing with CRM integration.
- Transcription Services:Real-time meeting documentation and medical dictation require highest-accuracy speech-to-text models.
Transaction volume sits with Voice Assistants; expansion tilts toward Transcription Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing gravity concentrates in East Asian fabrication clusters while consumption spreads across automotive and smart home markets in North America and Europe. Shenzhen and Hangzhou anchor MEMS microphone and neural processing unit production. Regulatory divergence between GDPR-constrained Europe and FCC-governed United States is fragmenting product architectures.
United States
Automotive OEMs in Detroit and Silicon Valley are standardizing cabin voice control across electric vehicle platforms. FCC equipment authorization requirements govern radio-enabled voice devices with extended electromagnetic compatibility testing cycles. Austin and Boston host edge AI engineering talent pools developing neural network quantization for automotive inference.
Germany
Premium automotive manufacturers in Munich and Stuttgart demand sub-200-millisecond voice response times for cockpit integration. KBA vehicle type approval intersects with EU AI Act risk classification for biometric voice recognition systems. Fraunhofer research institutes in Dresden anchor acoustic echo cancellation algorithm development for Tier-1 suppliers.
China
Smart home device manufacturing clusters in Shenzhen and Hangzhou drive economies of scale for MEMS microphone components. MIIT radio transmission regulations govern wireless voice-enabled equipment certification. Beijing-Tianjin-Hebei corridor hosts neural processing unit design houses serving domestic automotive OEMs.
Japan
Automotive electronics suppliers in Nagoya and Tokyo are integrating multi-microphone beamforming into electric vehicle architectures. METI industrial standards guide voice recognition system interoperability. Kyushu semiconductor fabrication facilities supply specialized DSP components for acoustic processing.
South Korea
Consumer electronics manufacturers in Seoul and Suwon are miniaturizing microphone arrays for wearable voice applications. MFDS medical device regulations constrain clinical voice recognition deployments. Busan-Ulsan industrial corridor hosts MEMS foundry capacity critical for beamforming array production.
Far-Field Speech and Voice Recognition Market Vendor Landscape
Top-tier vendors anchor automotive-grade silicon and edge AI processing, while mid-tier specialists concentrate on MEMS microphone miniaturization and acoustic software stacks. The vendor base stratifies across three tiers: integrated platform providers bundling hardware and inference software, component specialists delivering microphone arrays and DSPs, and pure-play algorithm houses licensing neural network models. Dominant competitive moves include vertical integration into captive MEMS fabrication and strategic partnerships between semiconductor suppliers and automotive Tier-1 integrators.
Within the integrated platform tier, NXP Semiconductors and Qualcomm exemplify vendors bundling edge AI voice processing with automotive-grade silicon portfolios. Knowles Corporation occupies a position among MEMS microphone specialists serving multi-microphone beamforming configurations. STMicroelectronics and Infineon Technologies represent European semiconductor houses competing through automotive certification depth and acoustic processing IP.
| Leading Market Players |
|---|
| NXP Semiconductors |
| STMicroelectronics |
| Qualcomm |
| Infineon Technologies |
| Knowles Corporation |
| Harman International |
| Cirrus Logic |
| Microchip Technology |
| Synaptics Incorporated |
| Others |
Supply Flow & Price Mechanics
EU AI Act risk classification mandates gate qualified supply access for biometric voice recognition systems, bifurcating product architectures between edge-only privacy-preserving configurations for Europe and cloud-enhanced variants for less regulated markets. This regulatory moat concentrates premium-tier pricing power among vendors with pre-certified edge AI silicon portfolios while forcing margin compression on cloud-dependent entrants facing 6-12 month conformity assessment delays.
Pricing Analysis
Price erosion across automotive-grade microphone arrays traces to Shenzhen-Hangzhou manufacturing cluster scale economies and MEMS component commoditization. Three-tier pricing structure separates automotive-certified edge AI processors from standard smart speaker silicon and economy-tier appliance voice modules. Cost-down pressure accelerates in consumer electronics as Knowles Corporation and Cirrus Logic compete on MEMS miniaturization. Enterprise conference phone buyers exhibit lowest price sensitivity due to IT-managed service contract bundling, while smart home OEMs in India drive hardest bargain negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea MEMS foundry capacity for beamforming array fabrication. Advanced microphone manufacturing draws from specialized DSP wafer processing in Kyushu, Japan and neural packaging in Busan-Ulsan corridor. Raw material dependencies span silicon wafers, rare-earth magnets for speaker integration, and cobalt for battery-constrained wearable form factors. Tariff exposure looms where US FCC equipment authorization intersects with China MIIT radio transmission regulations. Distribution runs through automotive Tier-1 integrators for cabin voice systems and IT-managed service providers for enterprise conference deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Far-Field Speech and Voice Recognition Market functions as a cost-of-compliance story where EU AI Act documentation burdens create sustainable barrier-to-entry moats for edge AI silicon vendors with pre-built conformity assessment pathways. Regulatory fragmentation between GDPR-constrained Europe and FCC-governed United States rewards architectural flexibility over single-market optimization.
For Market Incumbents: Hedge biometric classification risk by accelerating neural network quantization R&D for automotive sub-200-millisecond latency requirements. Deepen backward integration into captive MEMS fabrication to offset Taiwan foundry concentration vulnerability. Defend against Qualcomm Snapdragon platform bundling by anchoring European OEM relationships through KBA type approval pre-certification. For New Entrants and Emerging Players: IT-managed service providers represent the most accessible channel partner type for enterprise conference phone modernization white space. Target Indian urban households for geographic diversification beyond Shenzhen-Hangzhou manufacturing cluster dependence. Pursue go-to-market angle through acoustic echo cancellation software licensing to mid-tier automotive Tier-1 suppliers lacking in-house DSP engineering. For Investors and Strategic Acquirers: EU AI Act conformity assessment timeline compression is the leading indicator that edge AI talent scarcity will concentrate value capture among pre-certified vendors. Five-to-ten year viability favors semiconductor houses with automotive-grade portfolio depth over pure-play algorithm licensors. Acquisition target archetype: mid-cap MEMS microphone specialists with beamforming IP and existing European OEM relationships. Watch for inflection where German KBA accelerates type approval timelines for electric vehicle cabin architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Platform Integration | Bundles acoustic echo cancellation with on-device natural language processing for automotive OEMs. |
| Automotive Certification Pathway | Accelerates KBA type approval and EU AI Act conformity assessment for biometric voice systems. |
| MEMS Fabrication Scale-Up | Captures beamforming array demand from electric vehicle cockpit standardization programs. |
| Enterprise Channel Partnership | Displaces standalone audio distributors through IT-managed service contract consolidation. |
| Geographic Manufacturing Expansion | Reduces Taiwan foundry dependence via Kyushu DSP component and Busan packaging diversification. |
Methodological Framework
SEC 10-K filings, MIIT radio transmission certification databases, and EU AI Act technical documentation formed the secondary backbone for vendor capability mapping and regulatory pathway analysis. Primary interviews with automotive Tier-1 supplier procurement officers, edge AI semiconductor R&D directors, and enterprise IT facilities managers validated architectural pivot timing and compliance burden quantification. Bottom-up triangulation across microphone array bill-of-materials cost structures and top-down reconciliation against OEM platform integration timelines anchored volume and value estimates.
Historical trendline analysis of smart speaker installed base evolution and electric vehicle cockpit voice control penetration informed projection framework construction across the analysis window. Segmentation modeling incorporated technology type, product form factor, end-use vertical, and regional regulatory cluster dimensions. CAGRs derived from weighted average of neural processing unit shipment trajectories and acoustic software licensing revenue patterns, with automotive latency specification tightening and GDPR data minimization constraints as primary demand shifters.
Caveats apply where EU AI Act implementing guidance revision or FCC electromagnetic compatibility testing timeline extension could materially shift the outlook. MEMS foundry capacity constraints, Taiwan geopolitical risk, and edge AI engineering talent scarcity represent specific revision triggers for voice recognition market trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Artificial Intelligence in Supply Chain Management Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market