
 Audio Conferencing Services Market | 2026-2036
Audio Conferencing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Conferencing Services Market Analysis
HD voice and noise-cancellation tier upgrades is reorganizing competitive priorities across the Audio Conferencing Services landscape. Microsoft Teams leverages its enterprise software integration to sustain platform stickiness among Fortune 500 accounts. Cisco Webex anchors its position through hardened security certifications for government and financial services verticals. Zoom competes aggressively on freemium-to-paid conversion mechanics in the mid-market segment.
Audio conferencing services deliver real-time voice communication infrastructure enabling multi-party business conversations through packet-switched or circuit-switched networks, typically operating at 20 Hz to 20 kHz frequency response with sub-150 millisecond latency thresholds for perceptual synchrony. Cloud-based systems now command the largest revenue pool as enterprises retire legacy PSTN bridges, while hybrid solutions represent the fastest-expanding deployment architecture for organizations navigating regulatory data-sovereignty constraints. Managed services within the deployment dimension capture disproportionate margin contribution due to custom SLA engineering and dedicated support staffing.
FCC net-neutrality frameworks and GDPR data-localization mandates in Europe shape cross-border service architectures, compelling vendors to certify regional data residency and encryption protocols. HIPAA compliance requirements in US healthcare verticals and Japan's METI cybersecurity guidelines for critical infrastructure further segment addressable market access. Stakeholders must weigh sovereign cloud requirements against unified global platform economics when selecting vendor partnerships and infrastructure placement.
Market Dynamics
Enterprise migration from on-premises PBX infrastructure to cloud-native collaboration stacks is compressing deployment timelines and forcing vendors to absorb integration complexity that previously sat with IT departments.
Growth Catalysts
- FCC Net-Neutrality Frameworks:Stable traffic prioritization rules in the United States reduce latency variability for real-time voice packets, enabling service-level guarantees that enterprise procurement teams demand.
- Healthcare Vertical Expansion:HIPAA-mandated encryption and audit-log requirements in US medical systems create compliance-driven replacement cycles for non-conforming legacy bridges.
- Japan METI Cybersecurity Guidelines:Critical infrastructure designations for financial and energy sectors accelerate certified-cloud procurement timelines among domestic enterprises.
Market Restraints
- Data-Sovereignty Compliance Costs:GDPR localization mandates in Germany and France force redundant infrastructure deployment, raising unit economics for cross-border service delivery.
- Legacy PSTN Interconnection Fees:Incumbent telecom carriers in Japan and Germany maintain termination-rate structures that inflate hybrid-deployment operating expenditures.
- Audio Codec Patent Pools:Licensing complexity surrounding Opus and AAC-LD implementations creates royalty-stack uncertainty for mid-tier platform vendors.
Strategic Opportunities
- India Enterprise Digitization:PLI scheme incentives for IT hardware manufacturing coincide with TRAI cloud-telephony liberalization, opening mid-market SaaS penetration.
- AI-Native Noise Suppression:Convergence of machine-learning inference at the edge with packet-level audio processing enables premium-tier service differentiation without hardware endpoints.
- Outcome-Based Support Contracts:Channel partners in the United States are bundling managed SLA engineering with hardware lifecycle services, capturing margin beyond pure software subscriptions.
Industry Challenges
- Real-Time Network Engineering Talent:Scarce expertise in WebRTC optimization and jitter-buffer tuning constrains vendor scaling in competitive hiring markets.
- Legacy Integration Complexity:SIP trunk interoperability with decades-old PBX configurations consumes disproportionate professional-services capacity during enterprise migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Conferencing Services Market |
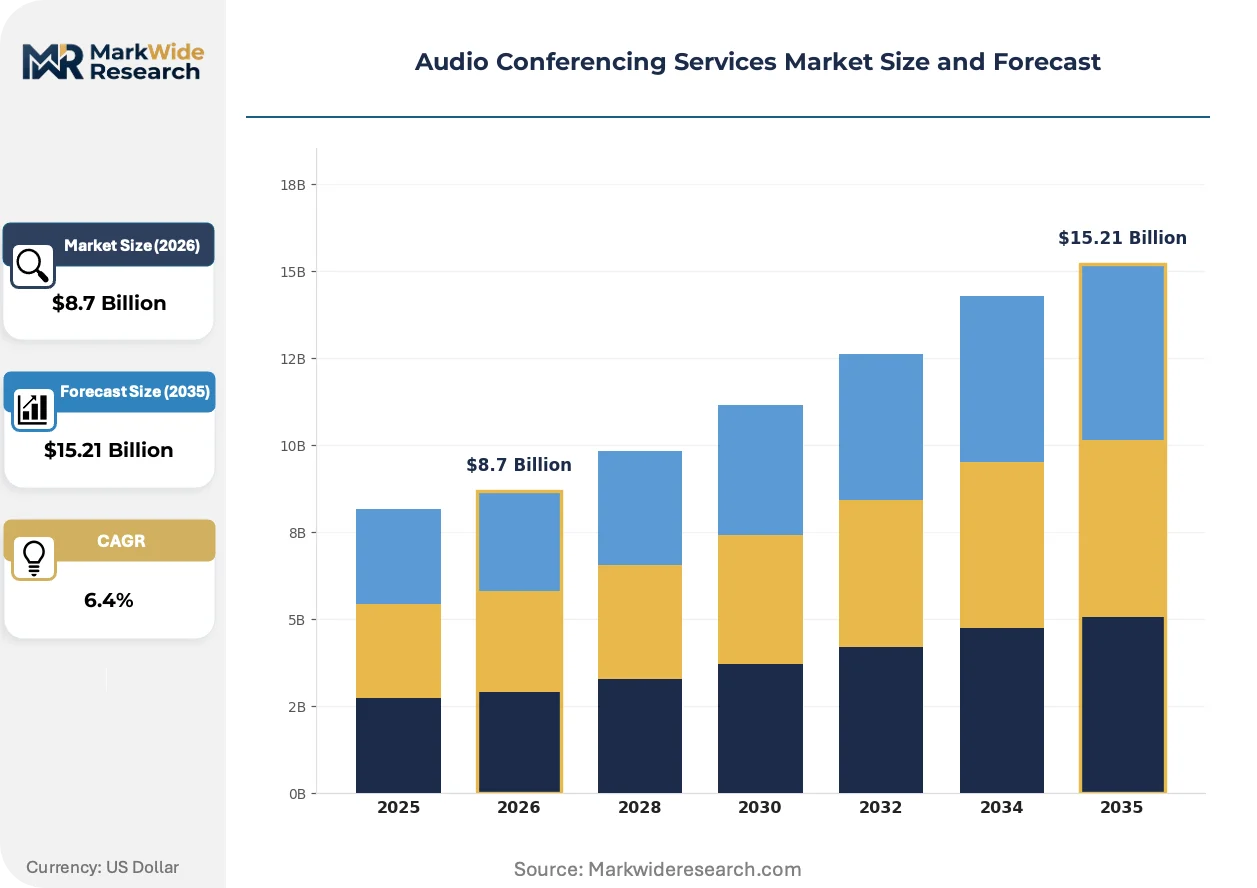
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Lines, Cloud-Based Systems, PSTN Services, Hybrid Solutions End User: Enterprises, Small Businesses, Educational Institutions, Government Agencies Deployment: On-Premise, Managed Services, SaaS, VoIP Feature: Recording Capabilities, Call Analytics, Screen Sharing, Multi-Participant Handling |
| Companies Covered | Cisco Webex, Microsoft Teams, Nextiva, 8x8, Vonage, RingCentral, GoToMeeting, Dialpad, Zoom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Conferencing Services Market Emerging Trajectories
Audio conferencing architecture is fragmenting from monolithic platforms into composable service layers, enabling buyers to swap components without full-stack replacement. This modularity is redistributing value capture across the supply chain.
Spatial audio and directional voice rendering are decomposing the traditional conference bridge into individualized audio streams. Enterprise buyers in financial services and legal verticals are piloting these capabilities for sensitive negotiations. The technology is decomposing vendor lock-in by standardizing 3D audio object formats across competing platforms.
GDPR Article 44 transfer mechanisms and EU AI Act risk-classification rules are reshaping how US-based vendors architect European data residency. Service providers must now maintain logically separated infrastructure footprints with distinct encryption key custody. German automotive and pharmaceutical enterprises are demanding sovereign-cloud certifications that exceed baseline compliance, compressing vendor qualification timelines.
Buyer committees are unbundling hardware procurement from software licensing, treating endpoints as interchangeable commodities. Systems integrators and value-added resellers in the United States are capturing this disaggregation by certifying multi-vendor interoperability. Healthcare and education verticals show the most aggressive unbundling, driven by capital-budget constraints and device-refresh cycles that no longer align with software contract renewals.
Audio Conferencing Services Market Segmentation
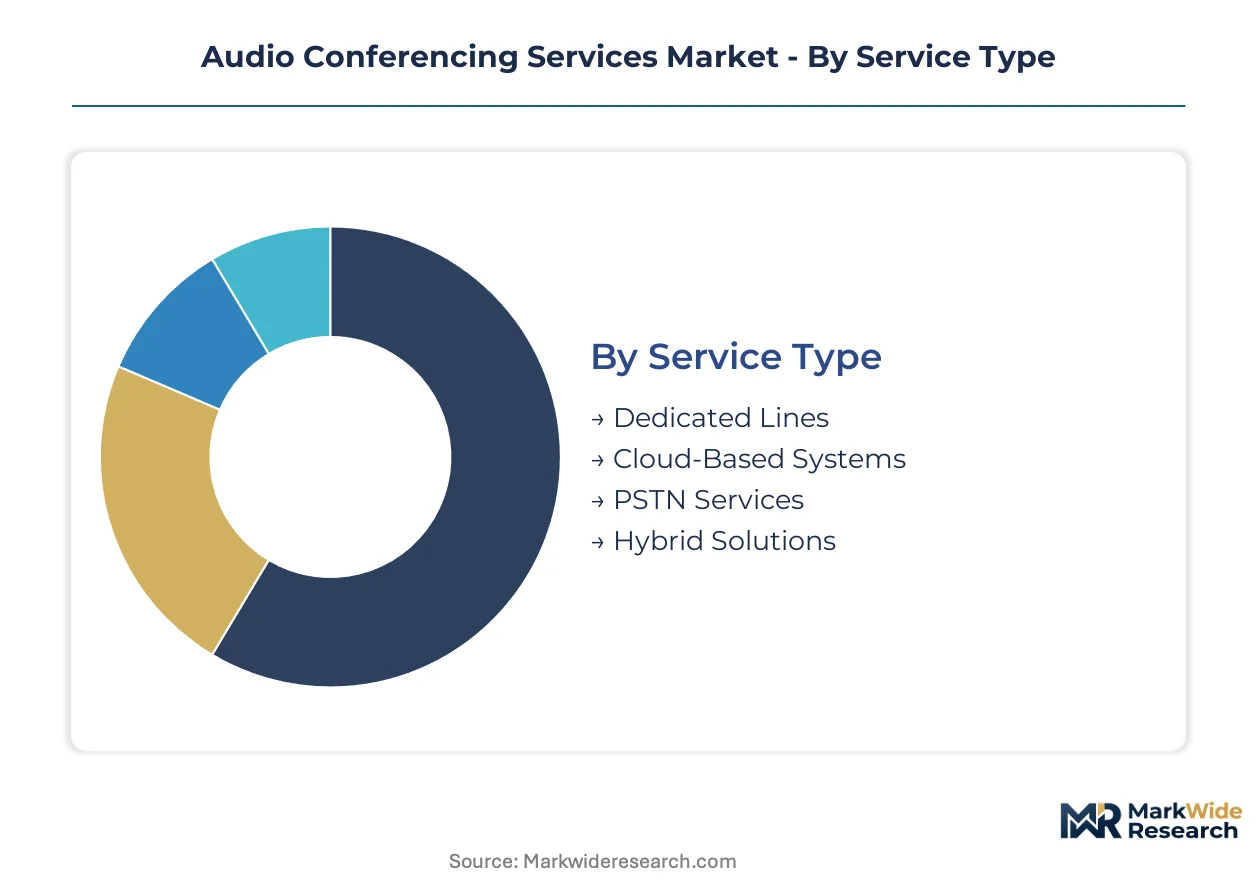
Audio conferencing services fragment across multiple technical and commercial dimensions that determine procurement pathways, margin structures, and vendor qualification requirements. Understanding how these segments map to channel economics and buyer decision-making enables precise targeting of infrastructure investments and partnership strategies.
Service Type:
Channel mix varies sharply: cloud-based systems flow primarily through direct enterprise sales and hyperscaler marketplaces, while PSTN services retain incumbent telecom distribution and hybrid solutions deploy through systems integrators.
- Cloud-Based Systems:Fully virtualized conferencing infrastructure operating over IP networks with elastic capacity scaling and API-native integration. Demand concentrates among Fortune 500 enterprises in the United States pursuing IT modernization mandates, constrained by GDPR data-residency requirements in European deployments.
- Hybrid Solutions:Architectures combining on-premises audio bridges with cloud burst capacity for peak-load handling. Financial services and energy sector buyers in Japan favor this model under METI cybersecurity guidelines requiring localized call processing for critical infrastructure.
- Dedicated Lines:Circuit-switched leased-line services with guaranteed bandwidth allocation.
- PSTN Services:Legacy public switched telephone network conferencing with per-minute billing.
By volume, PSTN Services leads. By growth pace, Cloud-Based Systems is ahead.
End User:
Cost tier stratification dominates: enterprises command premium SLAs and dedicated support staffing, while small businesses drive freemium-to-paid conversion volumes and educational institutions prioritize capital-efficient procurement.
- Enterprises:Multi-site organizations requiring 99.999% uptime guarantees, global dial-in number provisioning, and custom integration with identity management systems. Procurement in the United States accelerates through federal telework mandates and large-scale collaboration platform consolidation.
- Government Agencies:Public sector entities with hardened security certification requirements and sovereign data custody obligations. German federal and state-level buyers enforce BSI compliance baselines that disqualify non-EU-hosted alternatives.
- Small Businesses:Organizations under 500 employees with pay-per-use pricing preference.
- Educational Institutions:Universities and K-12 systems with semester-based licensing cycles.
Enterprises generate the largest revenue pool. Government Agencies show the steepest compliance-driven replacement trajectory.
Deployment:
Customer type determines architecture selection: regulated industries retain on-premise control, mid-market buyers adopt SaaS simplicity, and complex enterprises purchase managed services for operational offload.
- Managed Services:Fully outsourced conferencing operations including capacity planning, help desk staffing, and custom SLA engineering. Healthcare verticals in the United States deploy this model to satisfy HIPAA audit-log and encryption key custody requirements without internal telephony expertise.
- SaaS:Browser and mobile-native conferencing with automatic updates and usage-based billing. Small and mid-sized businesses across India leverage TRAI-liberalized cloud telephony for rapid deployment without capital expenditure.
- On-Premise:Customer-operated hardware and software within owned data centers.
- VoIP:Voice-over-IP implementations using existing data network infrastructure.
By margin contribution, Managed Services leads. By adoption velocity, SaaS is expanding most quickly.
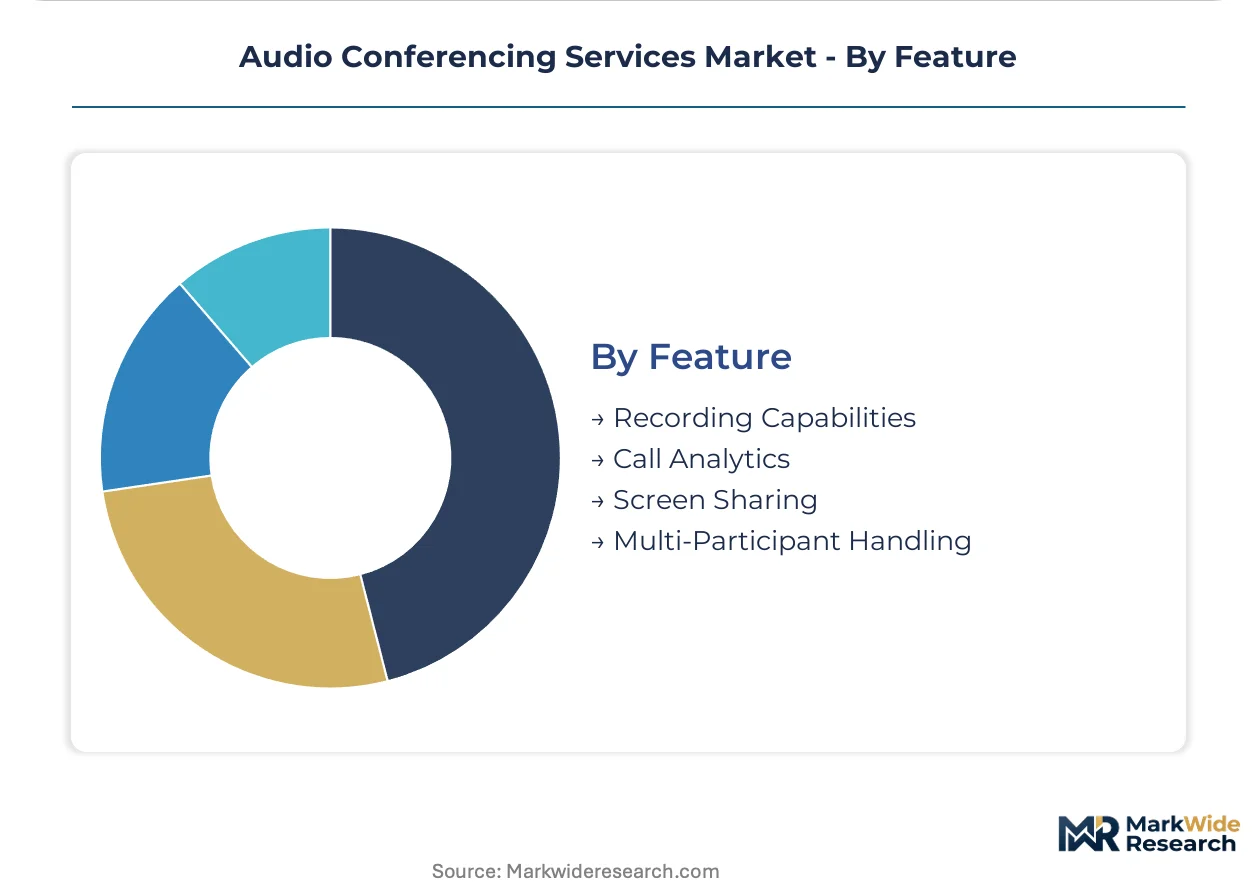
Feature:
Maturity curves separate commoditized baseline capabilities from premium differentiation: multi-participant handling and screen sharing are now table stakes, while AI-enhanced analytics and spatial recording command pricing premiums.
- Call Analytics:Real-time and post-call intelligence including sentiment scoring, talk-time distribution, and automated action-item extraction. Legal and financial services buyers in the United States pilot these capabilities for compliance documentation and negotiation intelligence.
- Recording Capabilities:Persistent call capture with searchable transcript generation and retention policy automation. Healthcare providers deploy this feature under HIPAA requirements for telehealth session documentation.
- Screen Sharing:Synchronous visual content broadcast integrated with audio streams.
- Multi-Participant Handling:Bridge capacity scaling and moderator controls for large conferences.
Multi-Participant Handling holds the largest installed base. Call Analytics is gaining share fastest among premium-tier buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure clusters most densely in the United States, where hyperscaler cloud regions and enterprise procurement density create scale advantages. Regulatory fragmentation across Germany, Japan, and India is forcing multi-tenant architecture investments that reshape cost structures.
United States
Federal telework mandates and Fortune 500 IT modernization programs drive cloud-native conferencing procurement at scale. FCC net-neutrality frameworks stabilize traffic prioritization for real-time voice packets, enabling SLA guarantees that enterprise buyers require. Silicon Valley and Seattle hyperscaler regions host the dominant infrastructure footprints for North American service delivery.
Germany
Automotive and pharmaceutical enterprises demand sovereign-cloud certifications exceeding baseline GDPR compliance, compressing vendor qualification timelines. BSI federal security baselines and state-level procurement rules disqualify non-EU-hosted alternatives for government agencies. Frankfurt and Munich clusters concentrate certified data center capacity for regulated verticals.
Japan
METI cybersecurity guidelines for critical infrastructure accelerate certified-cloud procurement among financial and energy sector buyers. Hybrid deployment architectures dominate as organizations retain localized call processing for compliance-sensitive operations. Tokyo and Osaka metropolitan areas anchor domestic vendor partnerships and systems integrator networks.
India
PLI scheme incentives for IT hardware manufacturing coincide with TRAI cloud-telephony liberalization, opening mid-market SaaS penetration. Enterprise digitization across banking and IT services verticals creates demand for managed conferencing operations without capital expenditure. Bengaluru and Hyderabad technology corridors concentrate domestic platform development and channel partner ecosystems.
United Kingdom
Financial services regulatory pressure and legal sector confidentiality requirements sustain premium-tier procurement for encrypted conferencing capabilities. Post-Brexit data adequacy negotiations with the EU reshape cross-border service architectures for multinational enterprises. London's fintech cluster drives early adoption of AI-enhanced call analytics and compliance documentation tools.
Audio Conferencing Services Market Vendor Landscape
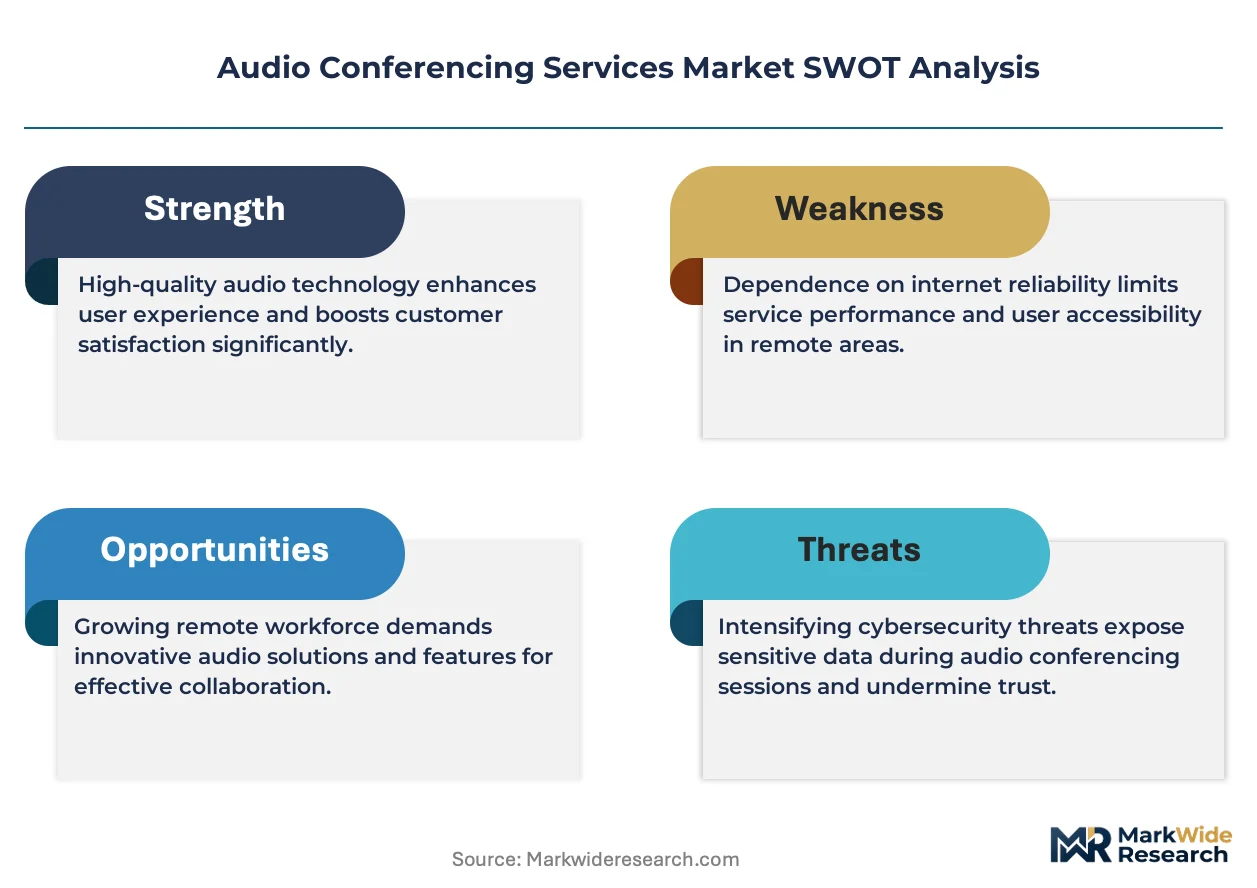
Concentration sits with platform-native hyperscalers that bundle conferencing within broader collaboration suites. The vendor landscape stratifies into three tiers: integrated productivity-stack providers, standalone UCaaS specialists, and telecom-anchored legacy operators. Consolidation pressure intensifies as enterprise buyers reduce vendor counts through platform standardization. Strategic moves center on security certification accumulation for regulated verticals and AI-native feature differentiation.
Within the integrated-platform tier, Microsoft Teams and Cisco Webex occupy positions defined by enterprise software ecosystem lock-in and hardened government certifications respectively. Zoom exemplifies the freemium-scale archetype that converted pandemic-era adoption into sustained mid-market penetration. Among standalone UCaaS providers, RingCentral and 8x8 represent the subscription-revenue model built on multi-channel communication unification.
| Leading Market Players |
|---|
| Cisco Webex |
| Microsoft Teams |
| Nextiva |
| 8x8 |
| Vonage |
| RingCentral |
| GoToMeeting |
| Dialpad |
| Zoom |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day provisioning cycles for cloud infrastructure capacity anchor vendor cost structures and compress margin flexibility for mid-tier platform providers competing against hyperscaler bundles. This lead-time band reflects concentrated hyperscaler dominance in the United States and Germany, where FCC net-neutrality stability and GDPR data-residency mandates respectively shape procurement economics and infrastructure placement decisions.
Pricing Analysis
GDPR Article 44 transfer mechanisms dictate the pricing tier structure across European deployments, forcing vendors to maintain sovereign-cloud premiums for German automotive and pharmaceutical buyers. Three-tier pricing structure across premium, standard, and economy levels separates managed SLA engineering with dedicated support staffing from self-service SaaS tiers and basic PSTN bridging. Cost compression in the mid-market SaaS tier is intensifying because hyperscaler bundling absorbs standalone conferencing functionality into productivity-suite subscriptions. Small businesses exhibit highest price sensitivity, while government agencies in Japan and Germany demonstrate lowest elasticity due to compliance-driven procurement mandates.
Supply Chain Analysis
Submarine cable landing stations in the United States, Japan, and United Kingdom constitute critical chokepoints for trans-Pacific and trans-Atlantic latency-sensitive voice traffic. Cloud infrastructure draws from hyperscaler data center clusters in Northern Virginia, Frankfurt, and Tokyo, while specialized audio processing hardware sources from Taiwan and South Korea. Single-source vulnerability concentrates in hyperscaler compute tenancy agreements that lock vendors into specific regional availability zones. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and telecom carrier channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Unified communications platforms with embedded conferencing functionality threaten standalone audio conferencing vendors with functional absorption, forcing incumbents to defend through vertical specialization and compliance certification accumulation.
For Market Incumbents: Secure hardened government security certifications for financial services and healthcare verticals before competitor accumulation closes qualification windows. Deepen backward integration into edge audio processing hardware to reduce hyperscaler compute dependency and improve latency performance for spatial audio deployments. METI cybersecurity guideline evolution in Japan presents both threat and lever for certified-cloud positioning. For New Entrants and Emerging Players: AI-native noise suppression at the packet level offers under-served differentiation for legal and financial services buyers piloting sensitive negotiation capabilities. Target India enterprise digitization through TRAI-liberalized cloud telephony and PLI scheme hardware incentives, where mid-market SaaS penetration remains below saturation. Go-to-market angle: bundle managed SLA engineering with outcome-based support contracts capturing margin beyond software subscriptions. For Investors and Strategic Acquirers: Carve-out targets emerge from telecom-anchored legacy operators with stranded PSTN infrastructure and enterprise customer relationships but lacking cloud-native development capacity. Long-term viability centers on platform consolidation into productivity-suite ecosystems or vertical specialization into compliance-intensive regulated industries. Signal to watch: hyperscaler acquisition of standalone UCaaS specialists with government certification portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 44 and BSI baselines in Germany disqualify non-EU-hosted alternatives for automotive procurement committees. |
| AI-Native Feature Integration | Machine-learning inference at the edge enables premium-tier differentiation without hardware endpoint dependencies for financial services pilots. |
| Vertical Specialization | HIPAA-mandated encryption and audit-log engineering captures healthcare replacement cycles in United States medical systems. |
| Channel Partnership Restructuring | Systems integrators in the United States capture hardware-software unbundling through multi-vendor interoperability certification. |
| Geographic Expansion | TRAI cloud-telephony liberalization and PLI scheme incentives open mid-market SaaS penetration across India banking and IT services verticals. |
Methodological Framework
A standing panel of platform engineering leads, enterprise IT procurement officers, channel partner principals, and regulatory compliance directors provided ongoing calibration against market developments throughout the study period. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed collaboration vendors, hyperscaler capex disclosures, TRAI regulatory notifications, and METI cybersecurity guideline publications. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from enterprise software spending benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with particular attention to cloud infrastructure capacity expansion trajectories and enterprise collaboration platform consolidation patterns. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, feature complexity level, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating vendor revenue disclosures, procurement pipeline visibility, and technology substitution elasticity estimates for PSTN-to-IP migration.
Material uncertainties — sovereign cloud requirement evolution, hyperscaler bundling acceleration, and audio codec patent pool litigation outcomes — sit outside the modeled envelope and could compress or extend forecast ranges. Practitioners should keep alternative scenarios live as FCC net-neutrality framework durability and EU AI Act risk-classification implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Broadcasting Solutions Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Video Managed Services Market
Communication Services
Mobile Messaging Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Video Conferencing Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Meeting Solutions Market
Communication Services
North America Postal Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Latin America Postal Service Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Global Passenger Information System Market
Communication Services
Global Call Center Platform Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market