
 Global Passenger Information System Market | 2026-2036
Global Passenger Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Passenger Information System Market Foresight
LED display panels are restructuring cost economics across passenger information hardware as transit agencies replace aging fluorescent and LCD signage with energy-efficient alternatives. Siemens AG leverages its rail signaling heritage to dominate European platform display contracts. Hitachi, Ltd. anchors its position through in-house production of edge-computing nodes for real-time arrival prediction. Thales Group differentiates via cybersecurity-hardened audio-visual integration for metro networks.
A passenger information system comprises networked hardware and software that delivers real-time transit data through audio announcements, visual displays, and mobile interfaces, typically operating on IP-based architectures with sub-second latency requirements for arrival-time accuracy. Its primary commercial purpose is reducing passenger uncertainty, improving fleet utilization, and enabling revenue protection through crowd-flow management. Visual display solutions lead installed base volumes across rail transit and airport applications, while cloud-based deployment modes represent the fastest-expanding segment as operators seek centralized fleet management. Multilingual support functions command premium pricing in international gateway hubs where passenger demographics span multiple language groups.
The EU AI Act and GDPR impose algorithmic transparency and data-processing constraints on predictive arrival systems that leverage passenger behavioral data. The US Federal Transit Administration and Japan's METI both mandate accessibility standards for audio-visual announcements, directly shaping product specification requirements for vendors seeking public procurement eligibility. Stakeholders must monitor how emerging cybersecurity certification regimes for connected transit infrastructure reshape vendor qualification criteria and contract award patterns.
Market Dynamics
Real-time data latency requirements below one second are compressing hardware refresh cycles across transit agencies, forcing simultaneous upgrades of edge-computing nodes, display networks, and IP backbone infrastructure.
Growth Catalysts
- EU Green Deal multimodal mandates:The framework requires seamless passenger information handoffs between rail, bus, and micro-mobility networks, compelling operators to replace siloed legacy systems with unified platforms.
- Edge-computing hardware:Localized processing at station level reduces cloud dependency for arrival predictions, cutting bandwidth costs while meeting sub-second latency thresholds for platform displays.
- India's high-speed rail corridor buildout:Dedicated freight and passenger corridors spanning Delhi-Mumbai and Delhi-Kolkata routes are specifying integrated passenger information systems as standard infrastructure.
Market Restraints
- Semiconductor supply concentration:Edge-computing node production depends on advanced chip fabrication concentrated in Taiwan and South Korea, exposing project timelines to foundry capacity constraints.
- GDPR algorithmic transparency requirements:The EU AI Act mandates explainable logic for predictive arrival systems using passenger behavioral data, extending development cycles and compliance costs.
- Legacy analog audio infrastructure:Decades-old copper-based public address systems in established metro networks create integration friction with IP-based visual display networks.
Strategic Opportunities
- Brazil's urban rail privatization wave:São Paulo and Rio de Janeiro concession agreements specify passenger experience upgrades as performance metrics, opening greenfield system deployments.
- 5G-Advanced and Wi-Fi 6 convergence:Combined low-latency cellular and high-density wireless enable seamless passenger information continuity across underground, surface, and open-air transit segments.
- US Federal Transit Administration accessibility mandates:Updated ADA requirements for audio-visual announcements create retrofit demand across 7,500+ transit agencies eligible for federal capital grants.
Industry Challenges
- Cybersecurity certification timelines:Emerging IEC 62443 compliance regimes for connected transit infrastructure extend vendor qualification periods by 12-18 months.
- Multilingual content localization:International gateway hubs require simultaneous support for 8-12 language groups, straining content management workflows and display bandwidth allocation.
- Interoperability with legacy SCADA:Integration between modern passenger information platforms and decades-old train control systems demands custom protocol gateways that fragment vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Passenger Information System Market |
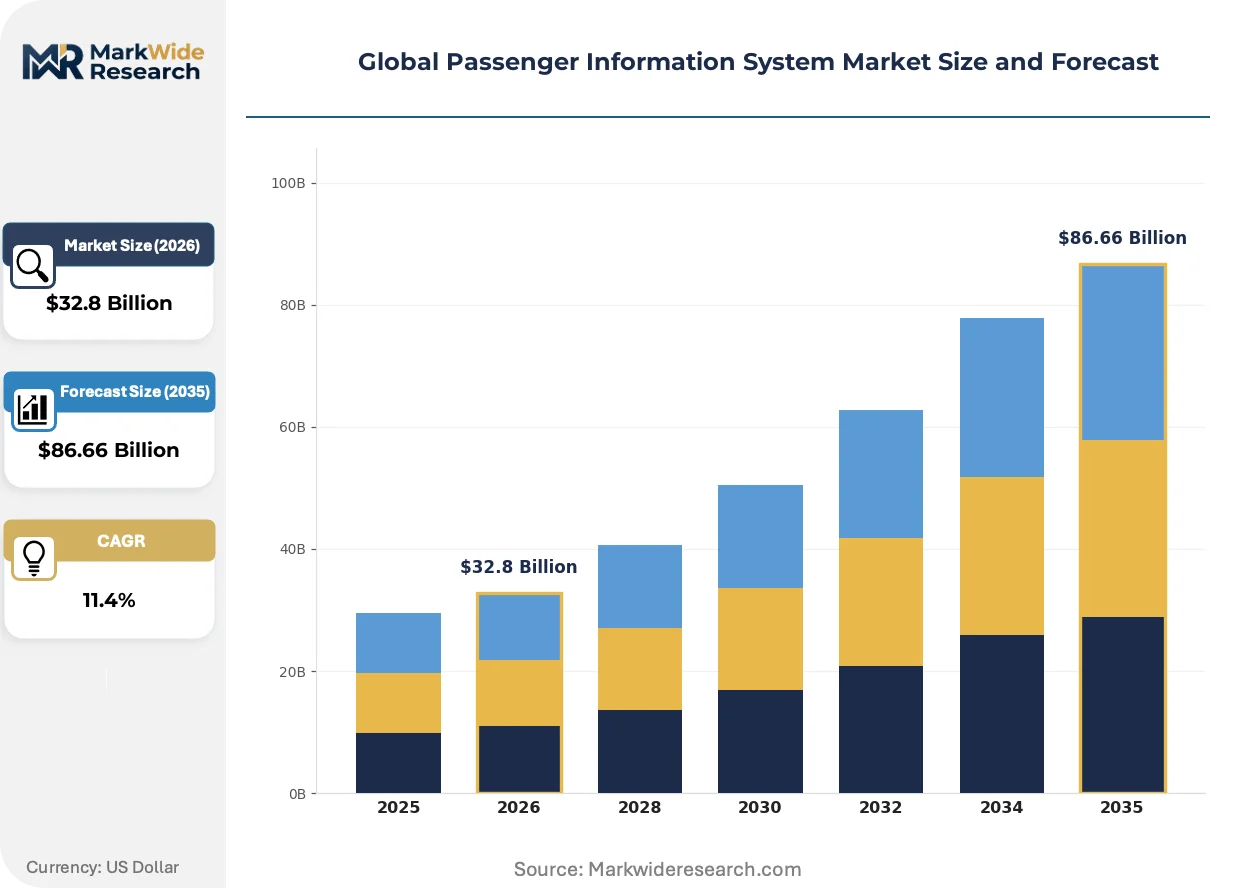
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Audio Announcement, Visual Display, Real-Time Tracking, Emergency Notification, Multilingual Support Deployment Mode: On-Premise, Cloud-Based, Hybrid Solutions, Edge Computing Application: Rail Transit, Airports, Bus Terminals, Ferry Services, Metro Networks End User: Transportation Authorities, Transit Operators, Airport Operators, Fleet Managers |
| Companies Covered | Alstom SA, Siemens AG, Wabtec Corporation, Hitachi, Ltd., Cisco Systems, Inc., Cubic Corporation, Huawei Technologies Co., Ltd., Advantech Co., Ltd., Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Passenger Information System Market Shifts & Advancements
Digital twin architectures are migrating from aviation and manufacturing into transit operations, enabling predictive maintenance of passenger information hardware before field failures disrupt service.
Computer vision-based crowd density estimation is automating platform safety alerts and dynamic train capacity messaging. Operators in Japan's JR East and Germany's Deutsche Bahn are deploying camera-to-display pipelines that trigger real-time boarding guidance without human intervention. The technology is automating the shift from schedule-based to condition-based passenger communication, compressing the functional gap between control centers and platform edge.
The EU AI Act's risk classification framework for algorithmic decision-making is tightening procurement specifications for predictive arrival systems. Vendors must now document training data provenance and model interpretability to qualify for public contracts in France, Germany, and the Netherlands. Rail operators are responding by bifurcating procurement into explainable-rule-based systems for high-risk passenger safety applications and machine-learning components for lower-risk informational displays.
Transit agencies are consolidating vendor relationships around full-stack service contracts that bundle hardware, software, and decade-long maintenance under single-source accountability. This displaces the traditional split between display manufacturers, software integrators, and facilities maintenance contractors. The model is most visible in China's state-owned railway procurement, where CRRC and its subsystem suppliers now deliver turnkey passenger information infrastructure with guaranteed uptime penalties.
Global Passenger Information System Market Segmentation
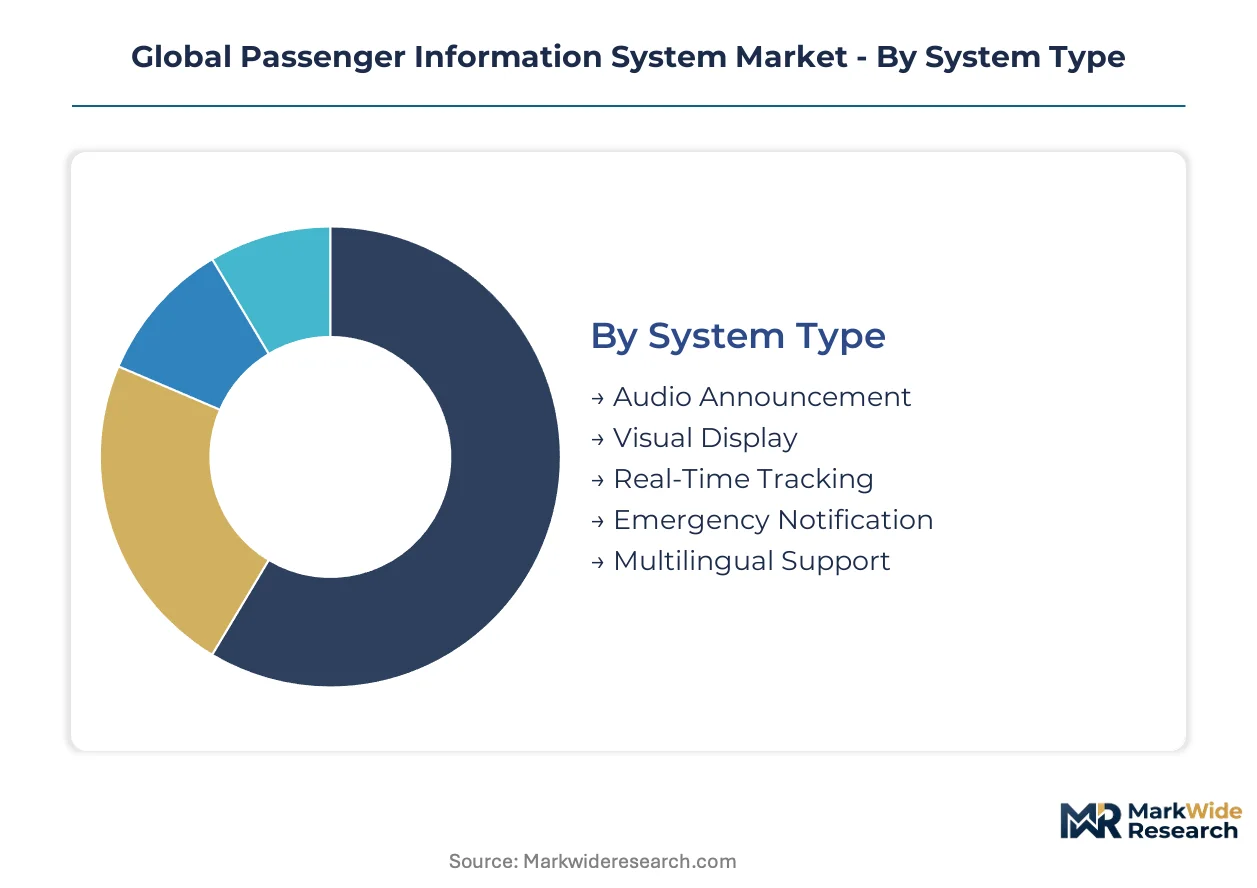
Transit operators segment passenger information investments by latency tolerance, infrastructure legacy, and passenger density. Procurement patterns diverge sharply between greenfield corridors specifying unified platforms and retrofit markets patching aging copper-based systems with IP overlays.
System Type:
Standardization dominates audio and emergency functions while visual and multilingual systems demand heavy customization for station architecture and demographic profiles.
- Visual Display:LED panels now displace fluorescent and LCD legacy across European platform retrofits. Deutsche Bahn's corridor modernization concentrates demand in Germany for weather-hardened outdoor signage with sub-second refresh rates.
- Audio Announcement:IP-based voice synthesis systems integrate with legacy copper PA infrastructure through protocol gateways. US transit agencies facing FTA accessibility mandates drive replacement cycles for ADA-compliant announcements.
- Real-Time Tracking:GPS-IMU fusion systems for bus and ferry fleets.
- Emergency Notification:IEC 62443-hardened mass alert platforms for metro networks.
- Multilingual Support:Simultaneous 8-12 language rendering for international gateway hubs.
Leading the category by volume: Visual Display. Expanding most quickly: Multilingual Support.
Deployment Mode:
Cost tiering separates high-availability edge deployments from centralized cloud architectures with tolerance for 2-3 second latency.
- Edge Computing:Localized processing nodes at station level eliminate cloud dependency for arrival predictions. JR East in Japan deploys Hitachi-built edge hardware to meet sub-second latency thresholds for platform displays.
- Cloud-Based:Centralized fleet management platforms enable multi-agency coordination. India's high-speed rail corridor buildout specifies cloud architectures for Delhi-Mumbai and Delhi-Kolkata route integration.
- On-Premise:Air-gapped server installations for cybersecurity-critical metro networks.
- Hybrid Solutions:Split architectures with edge display control and cloud analytics aggregation.
Climbing the fastest: Cloud-Based. Dominant installed base: On-Premise.
Application:
Passenger density and dwell time shape specification intensity across transport modes.
- Rail Transit:High-speed and commuter corridors demand synchronized multi-station display networks with SCADA integration. China's state-owned railway procurement bundles turnkey passenger information with guaranteed uptime penalties.
- Metro Networks:Underground environments require hardened hardware with 5G-Advanced backhaul continuity. São Paulo and Rio de Janeiro privatization agreements specify passenger experience upgrades as performance metrics.
- Airports:Gate-to-baggage claim wayfinding with flight system integration.
- Bus Terminals:Lower-specification LED installations with solar backup power.
- Ferry Services:Marine-grade enclosures with salt corrosion resistance.
Steepest expansion trajectory: Metro Networks. Largest installed base: Rail Transit.
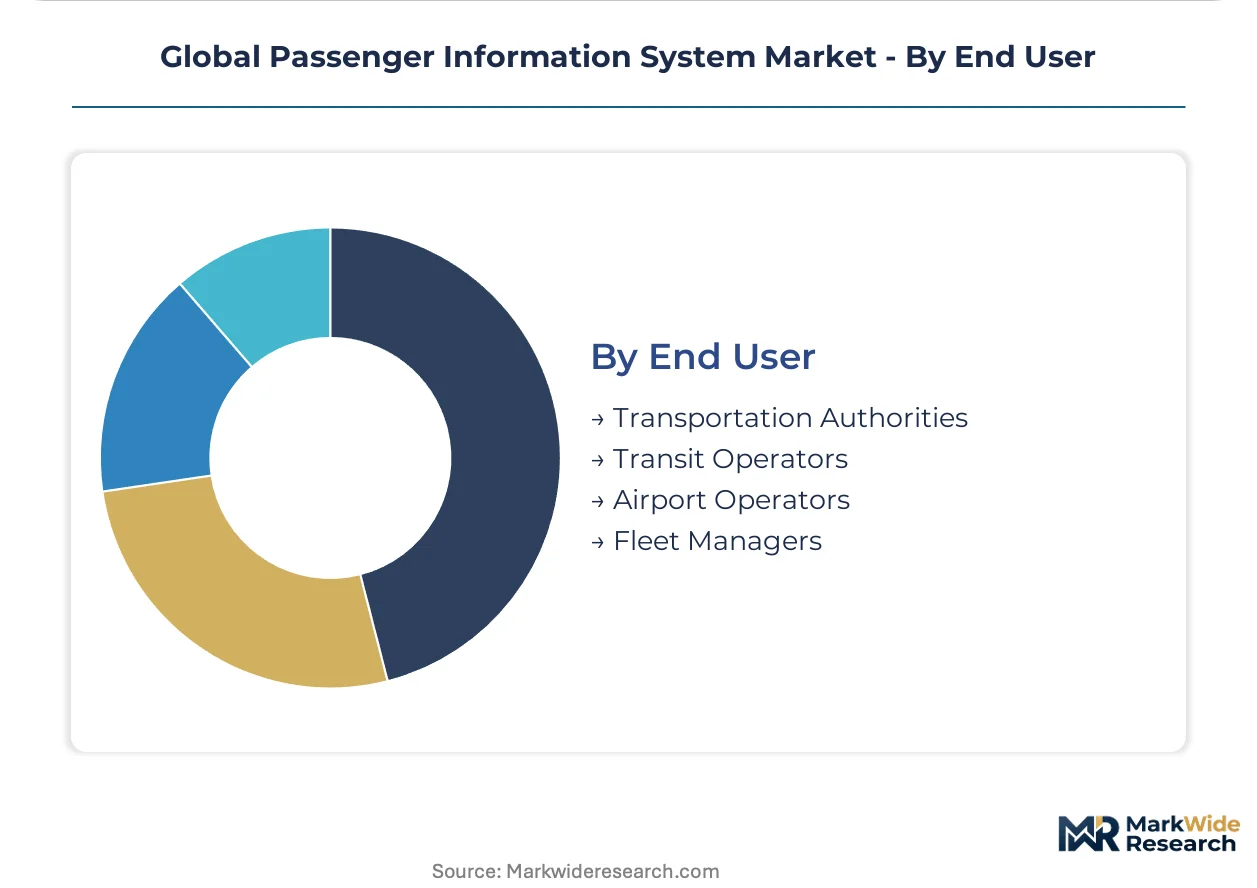
End User:
Procurement authority fragmentation creates diverging vendor engagement models across public and private operators.
- Transportation Authorities:Multi-modal oversight bodies mandate unified passenger information standards across bus, rail, and micro-mobility networks under EU Green Deal compliance frameworks.
- Transit Operators:Operating concession holders prioritize uptime-guaranteed service contracts with single-source accountability.
- Airport Operators:Privatized terminal managers with retail revenue protection priorities.
- Fleet Managers:Bus and ferry operators with vehicle-level installation requirements.
Gaining share fastest: Transit Operators. Procurement volume leader: Transportation Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for rail manufacturing in China concentrate passenger information system demand through state-backed procurement bundling. Transit agencies in Germany, Japan, and India anchor regional investment cycles through corridor modernization programs. Regulatory mandates across multiple jurisdictions reshape specification requirements for real-time data platforms.
China
State-owned railway procurement bundles turnkey passenger information infrastructure with guaranteed uptime penalties across high-speed rail corridor expansions. The MIIT mandates cybersecurity certification for connected transit systems under GB standards. CRRC and subsystem suppliers dominate deployments in the Yangtze River Delta corridor linking Shanghai to Nanjing.
Germany
Deutsche Bahn's corridor modernization concentrates demand for weather-hardened outdoor LED signage with sub-second refresh rates. The EU Green Deal's multimodal mandates require seamless passenger information handoffs between rail, bus, and micro-mobility networks. Siemens AG leverages its rail signaling heritage to capture platform display contracts across Bavaria and North Rhine-Westphalia.
Japan
JR East deploys edge-computing hardware to meet sub-second latency thresholds for platform displays across Tokyo and Osaka metropolitan networks. METI accessibility standards for audio-visual announcements directly shape product specifications for public procurement eligibility. Hitachi, Ltd. anchors its position through in-house production of edge-computing nodes for real-time arrival prediction in the Kanto region.
India
Dedicated freight and passenger corridors spanning Delhi-Mumbai and Delhi-Kolkata routes specify integrated passenger information systems as standard infrastructure. The PLI scheme for electronics manufacturing incentivizes domestic assembly of display panels and computing nodes. Transit agencies in Maharashtra and Gujarat pilot cloud-based fleet management platforms for multi-agency coordination.
United States
The FTA's updated ADA requirements for audio-visual announcements create retrofit demand across transit agencies eligible for federal capital grants. Cybersecurity-hardened mass alert platforms face extended IEC 62443 compliance timelines that reshape vendor qualification periods. Cubic Corporation and Wabtec Corporation position for accessibility-mandated upgrades in California and New York Metro systems.
Global Passenger Information System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack service contracts displacing traditional splits between display manufacturers, software integrators, and facilities maintenance contractors. The vendor base concentrates around rail signaling heritage, telecommunications infrastructure, and industrial automation capabilities. Two strategic archetypes dominate: integrated platform providers bundling hardware-software-maintenance under single-source accountability, and component specialists supplying edge-computing nodes or display panels to system integrators. M&A activity targets cybersecurity capabilities for connected transit infrastructure, while capacity expansion focuses on localized production to mitigate semiconductor supply concentration risks.
Among European-anchored conglomerates, Alstom SA and Siemens AG exemplify the integrated platform archetype through turnkey rail infrastructure delivery. Thales Group occupies a position emphasizing cybersecurity-hardened audio-visual integration for metro network applications. Hitachi, Ltd. represents the edge-computing specialization vector through captive production of localized processing nodes. These three companies illustrate how rail signaling heritage, telecommunications infrastructure, and industrial automation capabilities respectively anchor competitive positioning in a market consolidating around decade-long service contracts with guaranteed uptime penalties.
| Leading Market Players |
|---|
| Alstom SA |
| Siemens AG |
| Wabtec Corporation |
| Hitachi, Ltd. |
| Cisco Systems, Inc. |
| Cubic Corporation |
| Huawei Technologies Co., Ltd. |
| Advantech Co., Ltd. |
| Thales Group |
| Others |
Supply & Pricing Matrix
LED display panel manufacturing migration from fluorescent and LCD legacy production is compressing unit economics while simultaneously redistributing component sourcing toward semiconductor fabrication hubs in Taiwan and South Korea. This technology transition concentrates procurement leverage among transit agencies with scale to mandate decade-long service contracts bundling hardware, software, and uptime guarantees.
Pricing Analysis
High-volume display deployments capture margin through economies of scale while premium multilingual and edge-computing configurations sustain pricing power. Three-tier pricing structure across premium, standard, and economy levels segments by latency tolerance, cybersecurity certification grade, and after-sales bundling intensity. Cost compression in standard LED installations intensifies because foundry capacity constraints for advanced edge-computing chips limit supply elasticity. Municipal transportation authorities exhibit highest price sensitivity due to federal grant dependency, whereas privatized metro operators in Brazil and India demonstrate lowest sensitivity given performance-metric contract structures.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and China's MIIT cybersecurity certification mandates are forcing subsystem suppliers to establish domestic assembly capacity or forfeit public procurement eligibility. Advanced chip fabrication concentrates in Taiwan and South Korea, while LED panel production clusters in China and Vietnam. Edge-computing node production draws from 7nm and 5nm foundry capacity, memory modules, and industrial-grade enclosure materials. Single-source vulnerability in semiconductor supply exposes project timelines to foundry allocation decisions. Distribution runs through rail system integrators and direct procurement by state-owned railway operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints for edge-computing nodes prop pricing power for vendors with captive chip supply agreements or alternative architecture designs. Transit agencies face extended qualification timelines, compressing competitive windows for new subsystem suppliers.
For Market Incumbents: Deploy cybersecurity certification pre-investment to compress IEC 62443 compliance timelines before competitor qualification. Deepen backward integration into edge-computing node design to offset foundry allocation risk from Taiwan concentration. Capture platform display contracts through bundled hardware-software-maintenance service models that displace fragmented vendor ecosystems. Threat: cloud-native entrants with software-defined architectures bypassing legacy SCADA integration requirements. For New Entrants and Emerging Players: Launch via cybersecurity-specialist positioning targeting IEC 62443-hardened mass alert platforms for metro networks in Brazil's privatizing corridors. White-space concentrates in multilingual content management systems for international gateway hubs requiring 8-12 simultaneous language renders. Most penetrable segment: cloud-based fleet management platforms for India's high-speed rail corridor buildout. Go-to-market angle: pilot-to-production contracts with guaranteed latency performance thresholds. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated rail infrastructure conglomerates seeking full-stack passenger information capabilities. Long-term viability favors vendors with demonstrated SCADA interoperability and decade-long service contract track records. Acquisition target archetype: edge-computing specialists with in-house chip design or protocol gateway engineering. Signal to watch: IEC 62443 certification completion rates as vendor qualification bottleneck indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Node Localization | Mitigates Taiwan foundry concentration risk while meeting India's PLI domestic-content thresholds. |
| Cybersecurity Certification Acceleration | IEC 62443 pre-compliance compresses vendor qualification timelines by 12-18 months in EU procurement. |
| Multilingual Platform Development | Captures premium pricing in Dubai, Singapore, and Frankfurt gateway hub expansions requiring 8-12 language support. |
| SCADA Protocol Gateway Engineering | Enables integration revenue from decades-old train control systems in Deutsche Bahn and JR East networks. |
| Cloud-Edge Hybrid Architecture Deployment | Addresses India's high-speed rail corridor specifications for centralized fleet management with sub-second platform latency. |
Research Methodology
Document review covered regulatory filings from the EU AI Act and GDPR implementation guidance, India's PLI scheme notifications, and FTA accessibility mandate updates, complemented by interviews with transit agency procurement directors, rail system integrators, edge-computing hardware engineers, and cybersecurity compliance officers. Secondary validation drew from MIIT GB standard publications, IEC 62443 certification databases, and state-owned railway procurement bulletins. Bottom-up sizing of display panel shipments and edge-computing node deployments triangulated against top-down transit infrastructure investment flows.
Segmentation outputs across system type, deployment mode, application, and end user were modeled with latency tolerance and infrastructure legacy as cross-cutting dimensions. CAGR derivation synthesized historical procurement cycle analysis with projected corridor modernization timelines and regulatory mandate enforcement schedules. Industry-specific inputs included semiconductor foundry capacity allocation forecasts and cybersecurity certification pipeline tracking.
Foundry capacity constraints, regulatory timeline slippage, and transit agency budget authorization delays are the dominant revision risks to deployment assumptions. Forecasts reflect documented procurement specifications and qualification timelines without projecting policy acceleration or supply chain disruption scenarios. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Audio Conferencing Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Global Communications Interface Market
Communication Services
Walkie Talkie Market
Communication Services
Latin America Postal Service Market
Communication Services
Managed Communication Services Market
Communication Services
Outbound Telemarketing Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
Voip Services Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Global Call Center Platform Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Web Conferencing Market