
 High Performance Message Infrastructure Market | 2026-2036
High Performance Message Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Message Infrastructure Market Intelligence
GDPR data-localization enforcement is shifting the cost-of-entry calculus for message infrastructure vendors serving European enterprises. IBM sustains deep integration with legacy mainframe environments that dominate continental banking cores. Solace specializes in low-latency event streaming for capital markets participants navigating MiFID II transaction reporting. Microsoft extends cloud-native messaging through Azure Service Bus, competing directly with Amazon Web Services in hybrid deployment scenarios.
High performance message infrastructure encompasses software and hardware systems engineered to route, queue, and stream data packets with sub-millisecond latency, typically leveraging in-memory processing, kernel-bypass networking, and protocol optimizations such as zero-copy transfer to sustain throughput exceeding one million messages per second. Its primary commercial purpose is enabling real-time decisioning across distributed applications where delayed information propagation translates directly into operational loss or regulatory penalty. Cloud-based deployment now captures the fastest expansion as enterprises retire on-premise data centers, while event-driven technology leads margin pools because it commands premium pricing for complex stream-processing capabilities. Telecommunications end users anchor volume demand through 5G network slicing and IoT orchestration requirements.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules collectively reshape product roadmaps by mandating audit trails, explainability hooks, and cross-border data governance controls within messaging layers. FDA 21 CFR Part 11 and HIPAA impose comparable integrity constraints on healthcare message flows, narrowing the vendor set to those with certified compliance frameworks. Stakeholders must evaluate whether their infrastructure investments anticipate the convergence of data sovereignty laws with real-time AI inference requirements before procurement cycles lock in multi-year commitments.
Market Dynamics
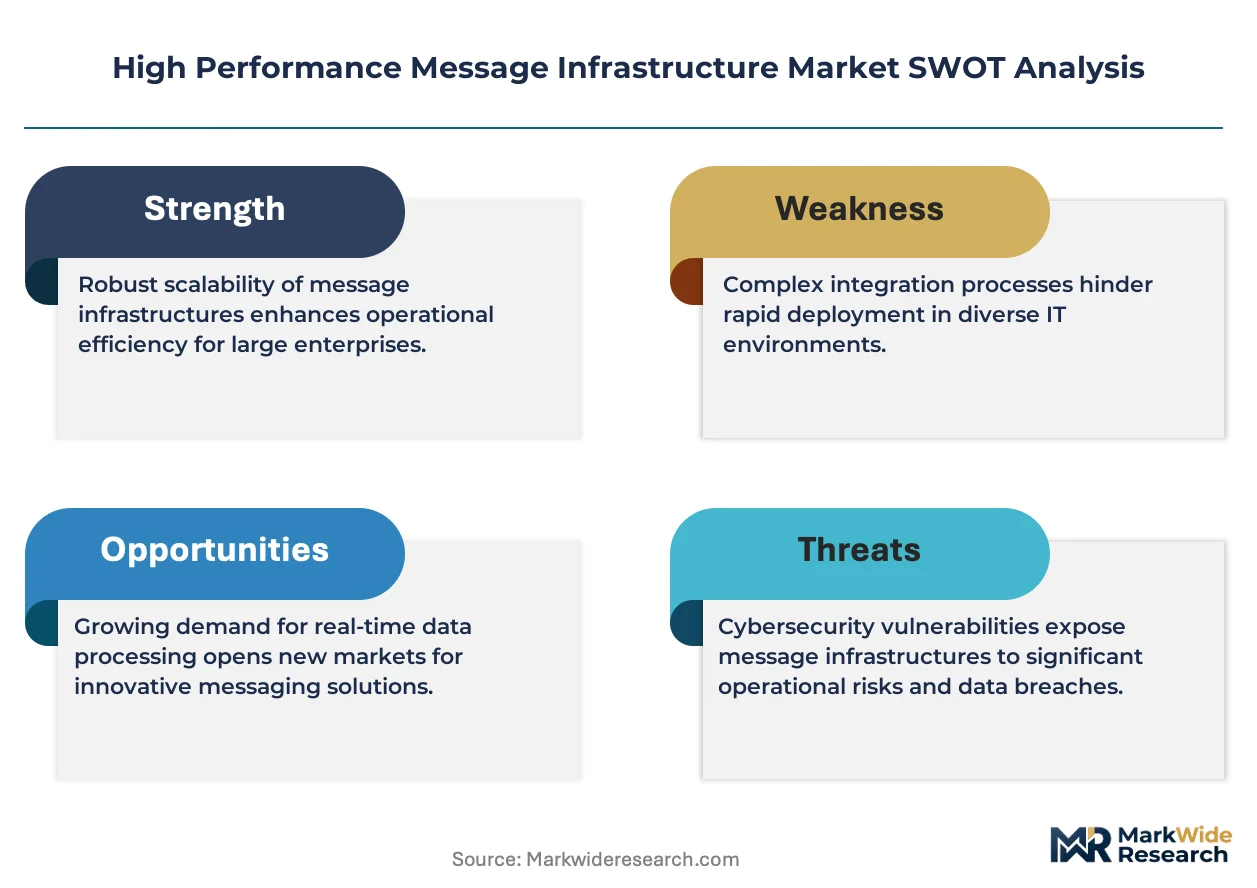
Event-driven architecture adoption across financial services is compressing procurement cycles and forcing infrastructure vendors to embed compliance hooks directly into message routing layers.
Growth Catalysts
- MiFID II transaction reporting mandates:European capital markets firms must capture and timestamp every order event, driving demand for sub-millisecond messaging fabrics with immutable audit trails.
- Kernel-bypass networking:DPDK and RDMA technologies eliminate operating system overhead, enabling throughput exceeding one million messages per second for high-frequency trading platforms.
- Singapore digital payment corridor:The city-state's real-time gross settlement infrastructure anchors Asia-Pacific demand for low-latency message queuing between correspondent banks.
Market Restraints
- Silicon supply concentration:Advanced FPGA and SmartNIC fabrication depends on Taiwan-based foundries, creating geopolitical exposure for hardware-accelerated messaging deployments.
- GDPR cross-border friction:Data localization requirements block seamless cloud replication between EU and non-EU zones, fragmenting unified message topologies.
- Legacy mainframe entrenchment:Continental European banks retain billions of lines of COBOL business logic, slowing migration to cloud-native event streaming platforms.
Strategic Opportunities
- Healthcare real-time telemetry:FDA 21 CFR Part 11 validation requirements for electronic records create premium pricing potential for compliant message infrastructure in hospital networks.
- EU AI Act explainability mandates:Automated decision systems must provide audit trails back to source data events, embedding message brokers as governance infrastructure.
- 5G network slicing orchestration:Telecommunications operators in Germany and the United States require deterministic latency guarantees for industrial IoT message flows.
Industry Challenges
- Kernel-bypass engineering scarcity:Developers proficient in DPDK, RDMA, and zero-copy networking command compensation premiums that inflate implementation costs.
- Hybrid integration complexity:Enterprises must bridge on-premise message buses with cloud-native event grids without breaking transactional consistency guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Message Infrastructure Market |
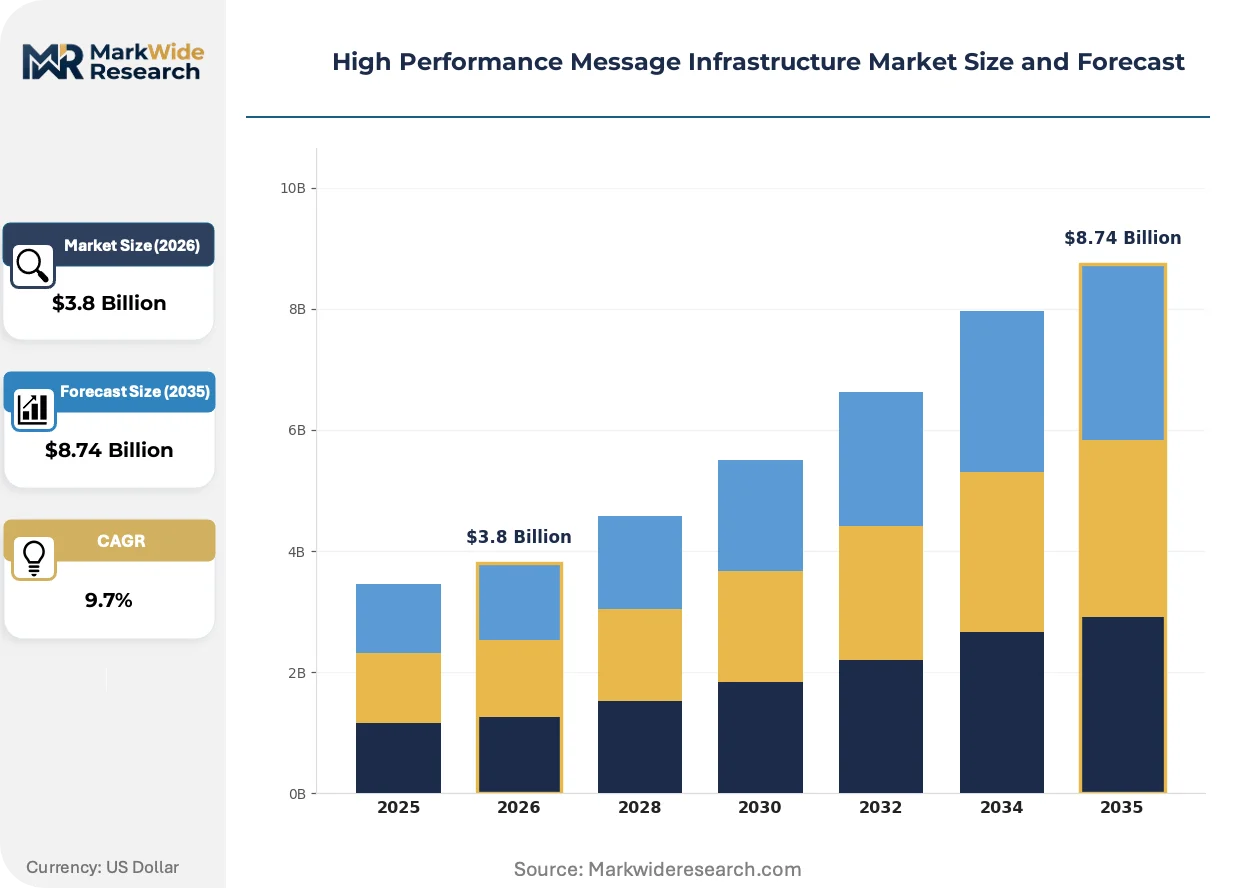
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud Service Type: Managed Services, Professional Services, Consulting, Training Technology: Message Queuing, Publish-Subscribe, Streaming, Event-Driven End User: Telecommunications, Finance, Retail, Healthcare |
| Companies Covered | Amazon Web Services, IBM, Oracle, Red Hat, TIBCO Software, Solace, Microsoft, Salesforce, Confluent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Message Infrastructure Market Strategic Shifts & Innovations
Event streaming platforms are absorbing functions previously handled by separate databases, analytics engines, and workflow orchestrators, collapsing architectural layers into unified data planes.
Apache Pulsar's tiered storage architecture is modularizing the separation of hot and cold message retention, allowing capital markets firms to query historical tick data without maintaining separate data lakes. Tier-1 banks in New York and London are deploying this topology to compress infrastructure footprints. The technology is modularizing how compliance teams reconstruct trade sequences across multi-year horizons without provisioning dedicated archival clusters.
The EU AI Act's risk classification framework is mandating event traceability for high-risk automated systems, requiring message brokers to embed provenance metadata at the packet level. Medical device manufacturers and algorithmic trading shops face the steepest compliance burdens. German automotive suppliers are retrofitting message infrastructure to capture sensor-to-decision audit trails for autonomous driving validation submissions to KBA.
Consumption-based pricing for message throughput is displacing perpetual licensing in enterprise procurement, compressing vendor cash conversion cycles while lowering barriers for episodic workloads. Capital markets technology budgets in Singapore and Switzerland are piloting this model for seasonal stress testing and regulatory reporting bursts. The shift is most visible among hedge funds and proprietary trading shops that message volumes spike during macroeconomic volatility windows.
High Performance Message Infrastructure Market Segmentation
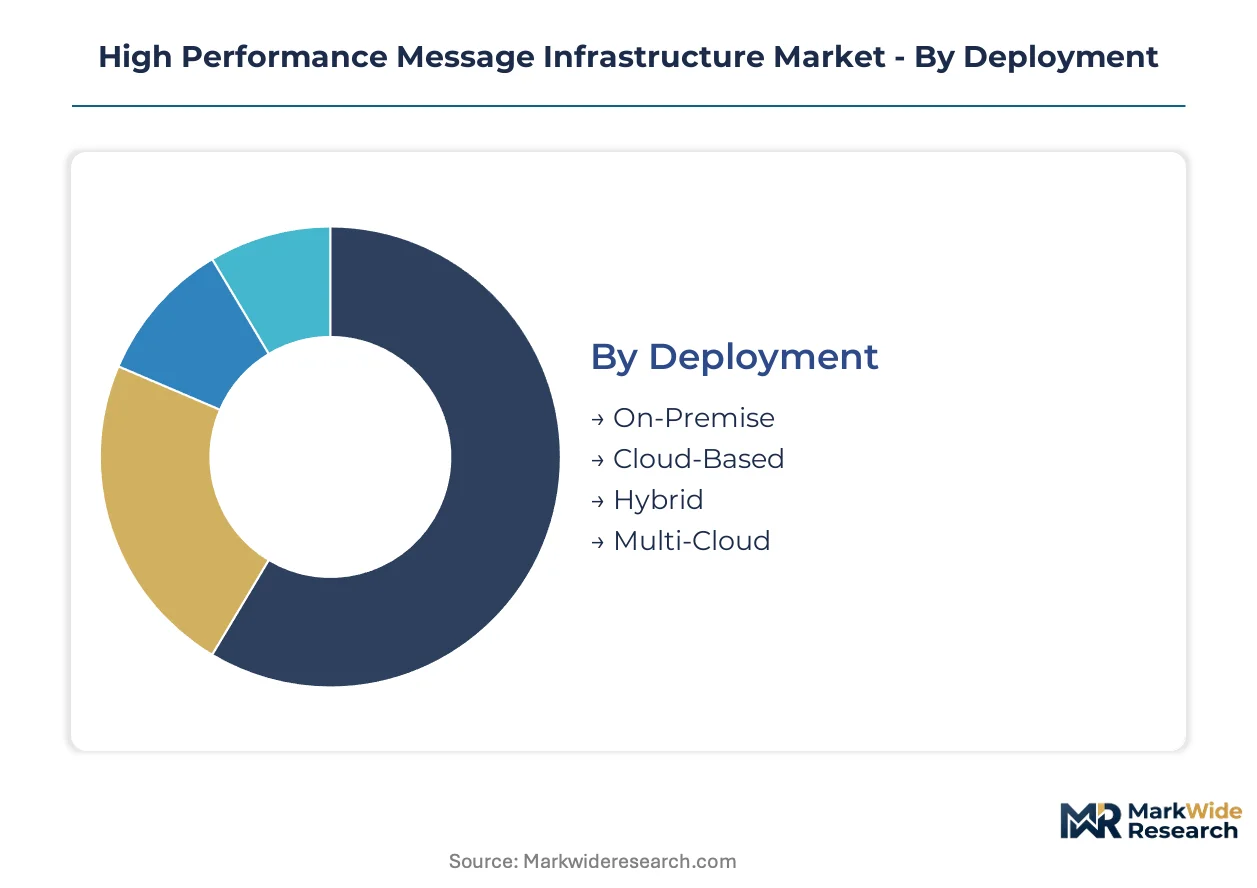
High performance message infrastructure procurement varies sharply by operational context. Deployment topology dictates latency budgets and compliance exposure. Technology selection determines whether enterprises can satisfy sub-millisecond requirements for algorithmic trading or 5G network slicing.
Deployment:
Supply concentration in certified cloud regions is reshaping how enterprises balance latency against data sovereignty mandates.
- On-Premise:Dedicated hardware installations leverage kernel-bypass networking and FPGA acceleration to achieve sub-100-microsecond latency. Continental European banks under GDPR localization requirements retain these deployments for core trading systems despite higher capital intensity.
- Cloud-Based:Hyperscaler-hosted message brokers abstract infrastructure management while introducing cross-availability-zone latency variability. Singaporean digital payment platforms and US fintechs dominate consumption as they prioritize elastic scaling over deterministic performance.
- Hybrid:Split architectures route sensitive workloads through on-premise fabric while bursting analytical streams to cloud tiers. German automotive suppliers deploying autonomous driving validation pipelines favor this topology to satisfy KBA audit requirements.
- Multi-Cloud:Active-active configurations across AWS, Azure, and Google Cloud eliminate single-vendor dependency. Financial services firms in Switzerland pilot these deployments for regulatory reporting resilience.
On-Premise retains the bulk of installed capacity; Cloud-Based is expanding most quickly.
Service Type:
Margin capture concentrates in recurring revenue streams that embed compliance automation.
- Managed Services:Vendors operate message infrastructure on client behalf, assuming uptime SLAs and patch management burden. HIPAA-covered entities in US healthcare networks prefer this model to offload FDA 21 CFR Part 11 validation overhead.
- Professional Services:Custom integration engineering bridges legacy mainframe message buses with modern event streaming platforms. COBOL-intensive European banks represent the primary demand concentration.
- Consulting:Architecture assessments and migration roadmapping for event-driven transformations. Capital markets technology teams in London and New York commission these engagements for MiFID II timestamp compliance.
- Training:Certification programs for DPDK, RDMA, and zero-copy networking proficiency. Kernel-bypass engineering scarcity drives premium pricing for these curricula.
Managed Services absorbs the bulk of vendor revenue; Professional Services is climbing the fastest as migration backlogs accumulate.
Technology:
Functional boundaries between messaging patterns are collapsing as unified platforms absorb multiple semantics.
- Message Queuing:Point-to-point delivery with guaranteed persistence and dead-letter handling. Retail order management systems in the United States rely on these patterns for inventory synchronization across distributed warehouses.
- Publish-Subscribe:Broadcast distribution to multiple consumers without producer awareness of subscriber topology. Telecommunications operators leverage this for 5G network slicing orchestration.
- Streaming:Ordered, append-only log structures enabling replay and time-travel queries. Tier-1 banks deploy Apache Pulsar tiered storage to compress historical tick data footprints.
- Event-Driven:Reactive architectures triggering automated workflows upon state changes. EU AI Act explainability mandates are embedding provenance capture directly into these brokers.
Event-Driven commands premium pricing; Streaming is gaining share fastest as queryable retention becomes standard.
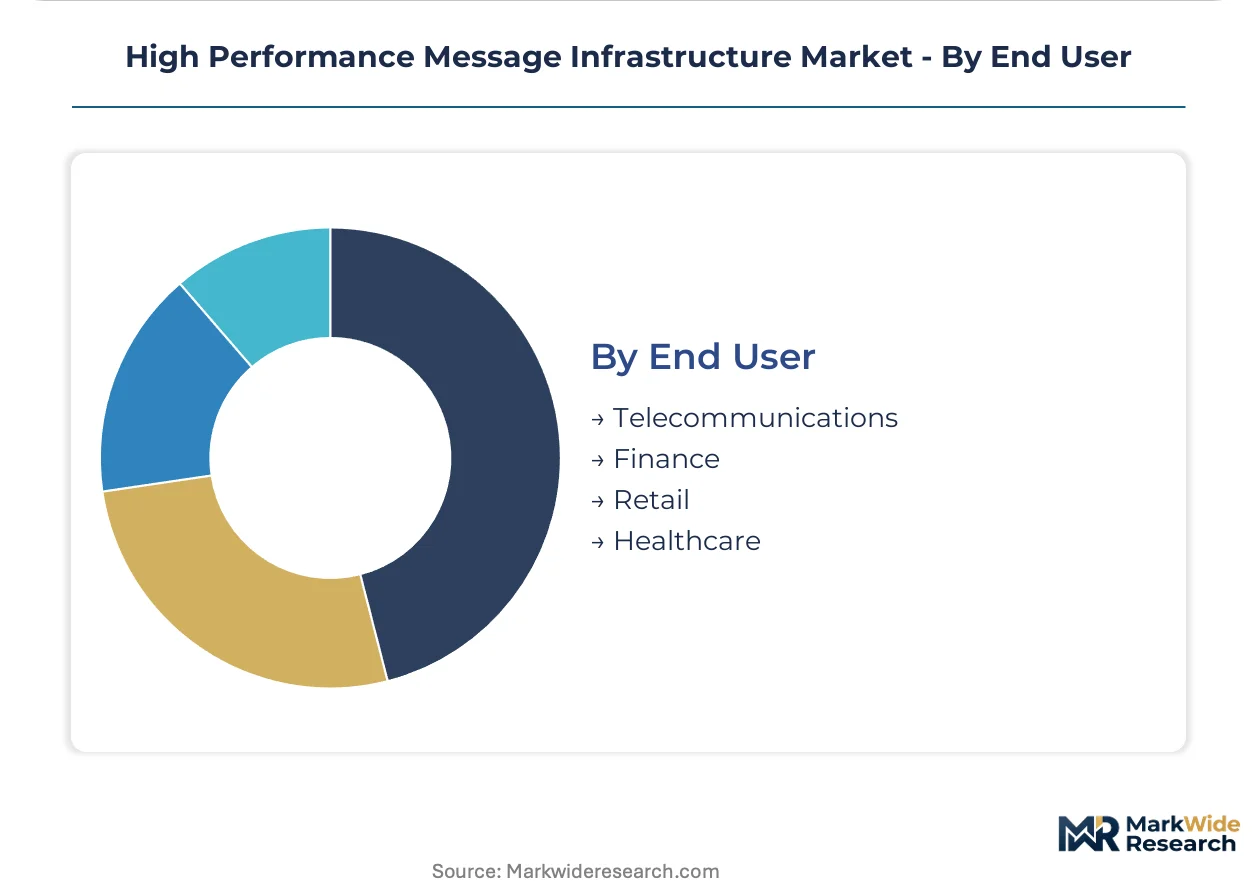
End User:
Latency requirements and regulatory exposure vary dramatically across verticals.
- Telecommunications:5G core networks and IoT orchestration demand deterministic latency for industrial automation. German and US operators anchor volume procurement.
- Finance:High-frequency trading and real-time risk management require sub-millisecond propagation with immutable audit trails. Singapore, Switzerland, and the United States host the densest deployments.
- Retail:Omnichannel inventory visibility and personalized recommendation engines. Real-time basket analysis drives adoption among US and European digital commerce platforms.
- Healthcare:Connected medical devices and telemetry networks requiring FDA-validated message integrity. Hospital networks in the United States face the steepest compliance burdens under HIPAA.
Telecommunications absorbs the bulk of hardware-accelerated messaging capacity; Finance is expanding most quickly as algorithmic trading volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's digital payment corridor tax incentives and Germany's Industry 4.0 investment credits concentrate procurement for low-latency message infrastructure. These zones attract capital markets firms and automotive suppliers seeking compliant, high-throughput data fabrics.
Germany
Automotive suppliers in Baden-Württemberg and Bavaria drive demand for deterministic message routing in autonomous driving validation pipelines. KBA mandates sensor-to-decision audit trails under EU AI Act high-risk system classifications. Frankfurt's high-frequency trading clusters anchor financial services procurement for sub-millisecond event streaming.
United States
SEC cybersecurity disclosure rules and HIPAA compliance requirements shape infrastructure procurement across financial and healthcare verticals. New York and Chicago trading venues demand kernel-bypass networking for algorithmic execution. Silicon Valley cloud-native fintechs favor consumption-based messaging models for elastic scaling.
Singapore
The Monetary Authority of Singapore's real-time gross settlement infrastructure anchors Asia-Pacific demand for cross-border payment message queuing. Local digital banking licenses have proliferated since 2020, expanding addressable market for event-driven architectures. Marina Bay financial district hosts dense concentrations of proprietary trading operations.
Switzerland
FINMA regulatory frameworks and banking secrecy modernization drive demand for immutable message audit trails in private wealth management. Zurich and Geneva private banks pilot multi-cloud message topologies for regulatory reporting resilience. The country's pharmaceutical clusters in Basel impose FDA 21 CFR Part 11 validation requirements on manufacturing telemetry networks.
United Kingdom
MiFID II transaction reporting mandates continue to shape capital markets infrastructure procurement post-Brexit. London's Tier-1 banking technology teams commission professional services for timestamp compliance and legacy mainframe integration. The FCA's operational resilience requirements accelerate retirement of on-premise message buses in favor of cloud-native alternatives.
High Performance Message Infrastructure Market Key Industry Players
United States hyperscalers anchor one tier; European and Canadian specialists hold differentiated positions in regulated verticals. The vendor base organizes around three strategic archetypes: cloud-native platform providers, legacy-integrated mainframe specialists, and low-latency capital markets pure-plays. Consolidation pressure intensifies as event-streaming platforms absorb adjacent database and analytics functions. Geographic expansion and compliance certification represent the dominant competitive moves.
Within the cloud-native tier, Amazon Web Services and Microsoft exemplify scale-driven platform strategies, occupying positions that leverage hyperscaler infrastructure for elastic message throughput. Solace represents the low-latency specialist archetype, with its geographic naming suggesting Canadian origins and a positioning focused on capital markets latency requirements. These three anchors illustrate how competitive positioning splits between horizontal scale and vertical specialization.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM |
| Oracle |
| Red Hat |
| TIBCO Software |
| Solace |
| Microsoft |
| Salesforce |
| Confluent |
| Others |
Cost & Logistics Intelligence
Kernel-bypass networking adoption is simultaneously compressing hardware procurement costs and concentrating supply leverage among FPGA and SmartNIC vendors with Taiwan-based fabrication access. This technology transition rewards early adopters with latency advantages while penalizing laggards with escalating replacement cycles and compliance-driven refresh mandates.
Pricing Analysis
Lead-time premiums dominate pricing structures, with sub-100-microsecond latency configurations commanding substantial uplifts over standard cloud-hosted alternatives. Three-tier pricing structure across premium, standard, and economy levels separates kernel-bypass hardware deployments from managed service subscriptions and consumption-based metered throughput. Cost compression in cloud-native tiers is intensifying because hyperscaler competition erodes per-message margins. Hedge funds and proprietary trading shops exhibit the highest price sensitivity due to episodic volume spikes, while Tier-1 banks under MiFID II mandates absorb premium pricing for immutable audit trail guarantees.
Supply Chain Analysis
Advanced FPGA and SmartNIC fabrication rests on Taiwan-based foundries, with secondary concentration in South Korea and the United States for specialized packaging and testing. Critical inputs include silicon wafers, high-bandwidth memory modules, and proprietary networking ASICs. Single-source vulnerability around Taiwan Strait geopolitical exposure threatens hardware-accelerated messaging deployments. Distribution runs through direct vendor relationships with capital markets technology teams, supplemented by systems integrators serving European banking cores with legacy mainframe bridging requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kernel-bypass engineering scarcity props pricing power across the infrastructure layer, as qualified DPDK and RDMA developers remain concentrated among a handful of specialized vendors and consulting practices.
For Market Incumbents: Anticipate consolidation pressure as event-streaming platforms absorb adjacent database and analytics functions. Defend installed base through deepened mainframe integration certifications for continental European banks and embedded compliance automation for EU AI Act high-risk system classifications. Prioritize capacity addition in Singapore and Germany to anchor proximity to densest trading and payment corridor demand. For New Entrants and Emerging Players: Launch via consumption-based pricing models targeting episodic workloads in hedge fund stress testing and regulatory reporting bursts. Healthcare real-time telemetry under FDA 21 CFR Part 11 validation requirements represents the most penetrable vertical, with hospital networks seeking to offload compliance overhead. Partner with systems integrators possessing COBOL-intensive European banking relationships to accelerate legacy bridge deployments. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler tuck-in acquisitions of low-latency specialists and private equity consolidation of compliance-automation capabilities. Long-term viability hinges on sustained differentiation against cloud-native platform commoditization. Watch kernel-bypass engineering talent migration rates as the inflection indicator for vendor margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Embedding | EU AI Act explainability mandates are forcing provenance capture directly into message broker architectures. |
| Hybrid Deployment Expansion | German automotive suppliers favor split topologies to satisfy KBA audit requirements for autonomous driving validation. |
| Kernel-Bypass Talent Acquisition | DPDK and RDMA proficiency scarcity inflates implementation costs and creates defensive moats for certified vendors. |
| Tiered Storage Integration | Apache Pulsar's modular separation of hot and cold retention compresses infrastructure footprints for Tier-1 banks. |
| Multi-Cloud Resilience Piloting | Swiss private banks deploy active-active configurations across hyperscalers for regulatory reporting continuity. |
Research Approach
Multi-period observation of message throughput benchmarks, latency compliance certifications, and procurement cycle timing anchored the trend analysis, supplemented by interviews with platform engineers at capital markets technology teams, CTOs at Singaporean digital payment platforms, integration specialists serving European banking cores, and procurement officers at German automotive suppliers. Secondary validation drew from SEC cybersecurity disclosure filings, EBA stress test technical standards, Monetary Authority of Singapore payment infrastructure reports, and hyperscaler capex allocation disclosures. Bottom-up vendor revenue triangulation against top-down end-user IT spend estimates calibrated market sizing.
Segment-weighting approaches modeled deployment topology, service type, technology pattern, and end-user vertical dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted growth curves incorporating kernel-bypass adoption rates and cloud migration velocity by jurisdiction. Industry-specific inputs included MiFID II transaction reporting mandate compliance deadlines and EU AI Act risk classification implementation timelines.
Geopolitical disruption to Taiwan-based semiconductor fabrication, abrupt shifts in GDPR cross-border data governance enforcement, and accelerated cloud-native platform commoditization are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Message Handling Systems Market
Communication Services
Voip Services Market
Communication Services
Audio Conferencing Services Market
Communication Services
Latin America Postal Service Market
Communication Services
North America Postal Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Web Conferencing Market
Communication Services
Global Critical Communication Market
Communication Services
Outbound Telemarketing Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Dispatch Console Market
Communication Services
Pcaas Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market