
 Machine Translation Software Market | 2026-2036
Machine Translation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Translation Software Market Outlook
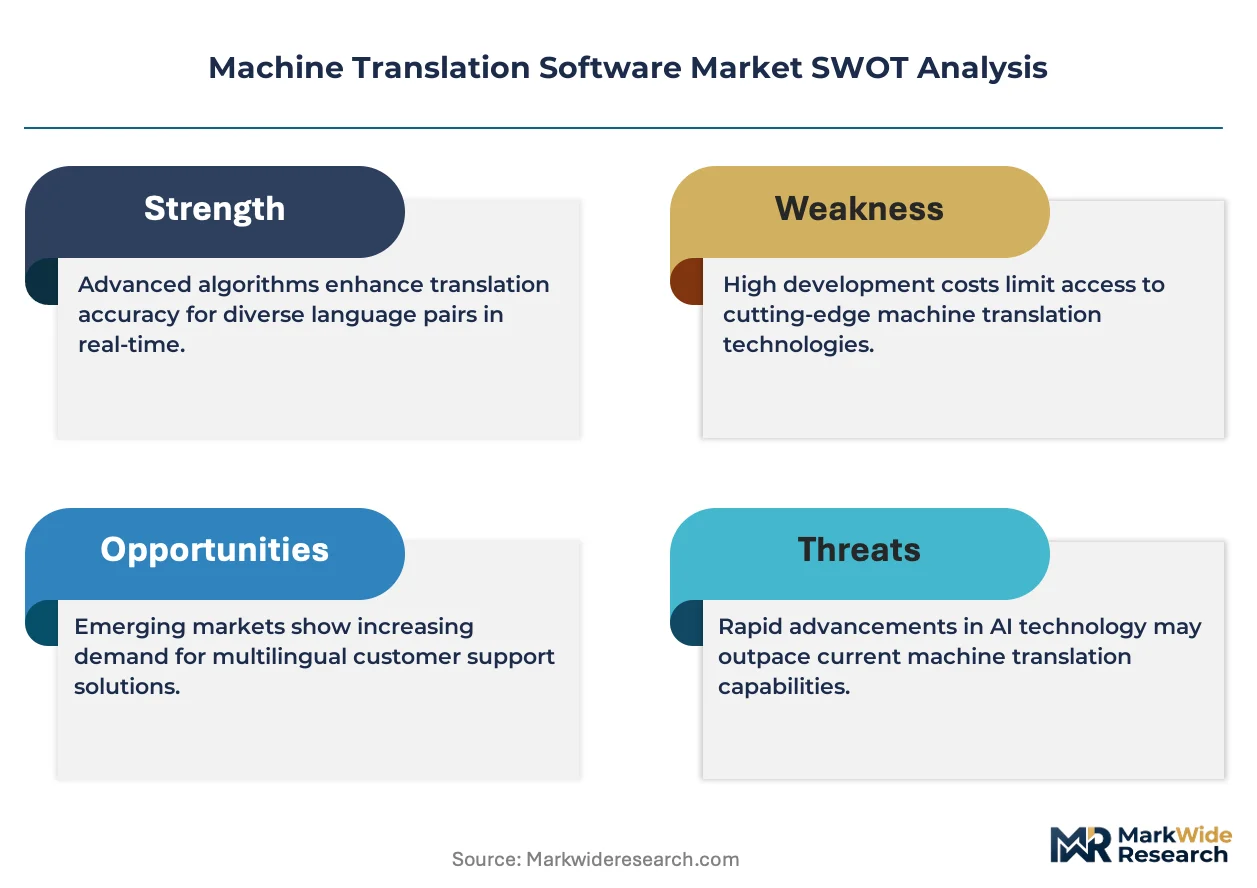
Neural machine translation quality tiers are unwinding legacy statistical approaches across enterprise procurement cycles. Google LLC leverages its transformer architecture investments to sustain dominance in cloud-based deployment pipelines. DeepL GmbH competes on European language-pair accuracy, while Microsoft Corporation anchors corporate demand through Teams and Azure integration.
Machine translation software refers to computational systems that automatically convert text or speech between languages using algorithmic models, with neural network architectures now achieving BLEU scores above human baselines for select language pairs. These systems serve commercial and institutional users requiring scalable multilingual communication without proportional human translator expansion. Cloud-based deployment leads volume adoption due to elastic scaling for episodic translation workloads, while neural network technology captures the fastest expansion as enterprises retire rule-based legacy installations. Document translation applications currently hold the deepest margin pools given compliance and legal review requirements.
FDA scrutiny of software-as-a-medical-device is extending to clinical trial documentation translation tools, while the EU AI Act mandates risk classification for high-stakes automated translation in judicial and healthcare contexts. ISO 17100 quality standards for translation services are shaping procurement specifications for government agency buyers across OECD markets. Stakeholders must monitor emerging liability frameworks for machine-generated errors in regulated industries and calibrate human-in-the-loop investments accordingly.
Market Dynamics
Transformer-based neural architectures are compressing deployment timelines for enterprise translation infrastructure. Procurement committees now weight BLEU score parity against integration friction, accelerating displacement of statistical machine translation estates.
Growth Catalysts
- E-commerce localization mandates:Platform operators in Germany and France require real-time multilingual product catalogs. Automated translation pipelines reduce time-to-market for cross-border listings.
- EU AI Act compliance infrastructure:Risk classification requirements for high-stakes automated translation in judicial and healthcare contexts are forcing regulated enterprises to upgrade legacy systems.
- Clinical trial documentation expansion:FDA scrutiny of software-as-a-medical-device extends to translation tools supporting multi-site pharmaceutical studies. Sponsors invest in auditable machine translation workflows.
Market Restraints
- Compute cost volatility:Neural model inference requires GPU clusters. Cloud pricing fluctuations compress margins for high-volume document translation providers.
- Training data concentration:High-quality parallel corpora for low-resource language pairs concentrate in academic and governmental archives. Commercial access terms constrain model development.
- Liability framework ambiguity:ISO 17100 quality standards do not resolve fault attribution for machine-generated errors in regulated industries. Legal departments impose conservative human-in-the-loop ratios.
Strategic Opportunities
- India's pharmaceutical export documentation:CDSCO regulatory filings require English-Hindi technical translation at scale. Domestic software vendors lack specialized life sciences training data.
- Speech-to-speech convergence:Neural machine translation is merging with text-to-speech synthesis. Real-time multilingual video conferencing represents untapped enterprise demand.
- Japan METI localization subsidies:Small and medium exporters receive grants for automated translation adoption. Government procurement specifications favor BLEU-certified solutions.
Industry Challenges
- Computational linguist scarcity:Rare language expertise and neural architecture optimization skills concentrate in elite research labs. Enterprise teams struggle to staff model fine-tuning functions.
- Legacy middleware integration:Document management systems from the 2010s lack API-native architectures. Custom connector development consumes implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Translation Software Market |
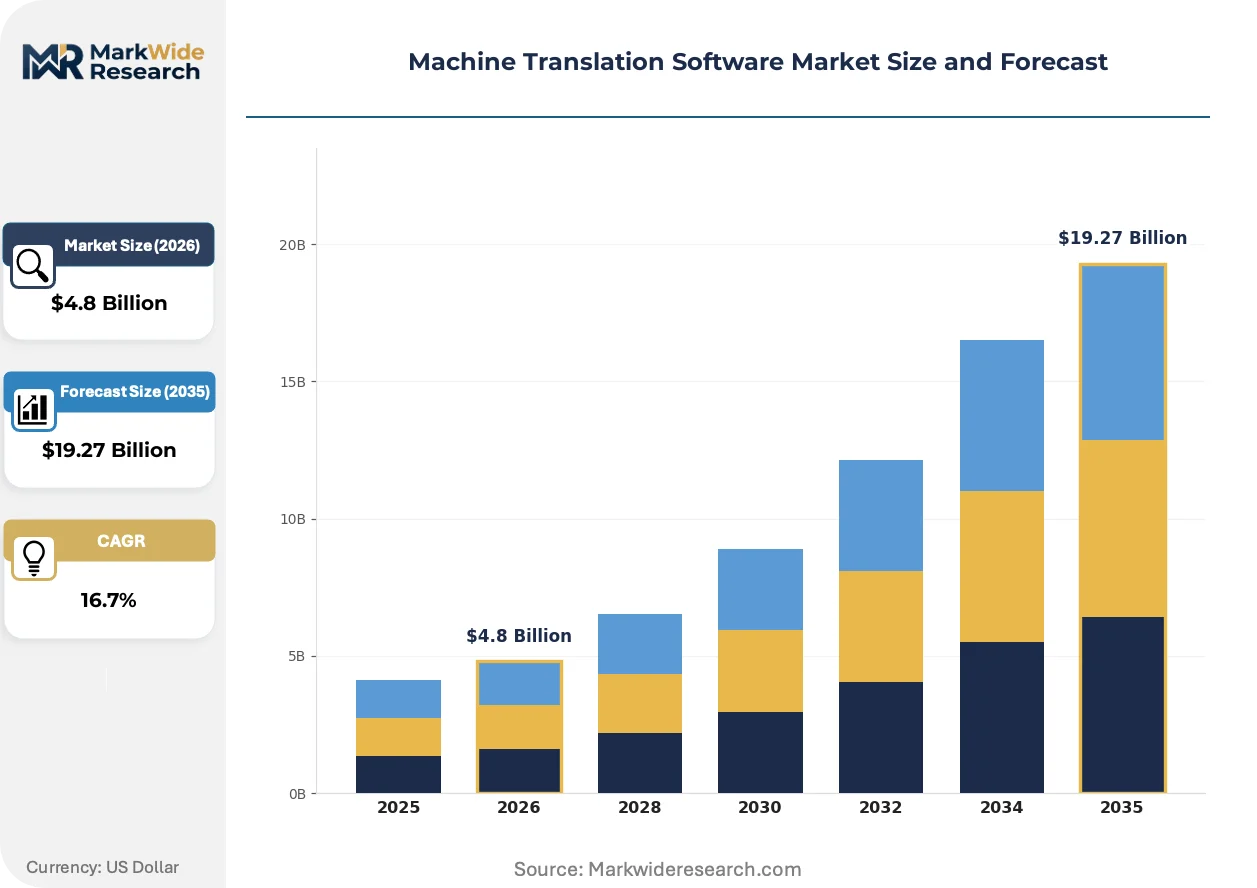
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Technology: Neural Networks, Statistical Models, Rule-Based Systems, Hybrid Approaches End User: Corporations, Educational Institutions, Government Agencies, NGOs Application: Real-Time Translation, Document Translation, Website Localization, Audio Translation |
| Companies Covered | Google LLC, Microsoft Corporation, Amazon Web Services Inc., DeepL GmbH, IBM Corporation, SYSTRAN International Co. Ltd., Lionbridge Technologies Inc., Welocalize Inc., Baidu Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Translation Software Market Strategic Shifts
Multimodal neural architectures are collapsing the boundary between text, speech, and visual translation. Enterprise buyers now evaluate unified platforms rather than point solutions for language tasks.
Large language models fine-tuned for translation tasks are displacing purpose-built neural machine translation systems in pilot deployments. Fortune 500 technology procurement teams test unified generative platforms against specialized engines. Consolidation of vendor relationships and compression of annual software budgets follow successful pilots.
The EU AI Act mandates risk classification for high-stakes automated translation in judicial and healthcare contexts. Legal translation service providers must document human oversight protocols and model training provenance. German court systems and French hospital networks are first movers in procuring compliant infrastructure.
Subscription pricing for translation APIs is fragmenting into consumption-based tiers tied to document complexity scores. Enterprise procurement teams negotiate separate rate cards for marketing content versus regulatory submissions. This unbundling is most visible in US pharmaceutical and medical device verticals where FDA submission costs dominate localization budgets.
Machine Translation Software Market Segmentation
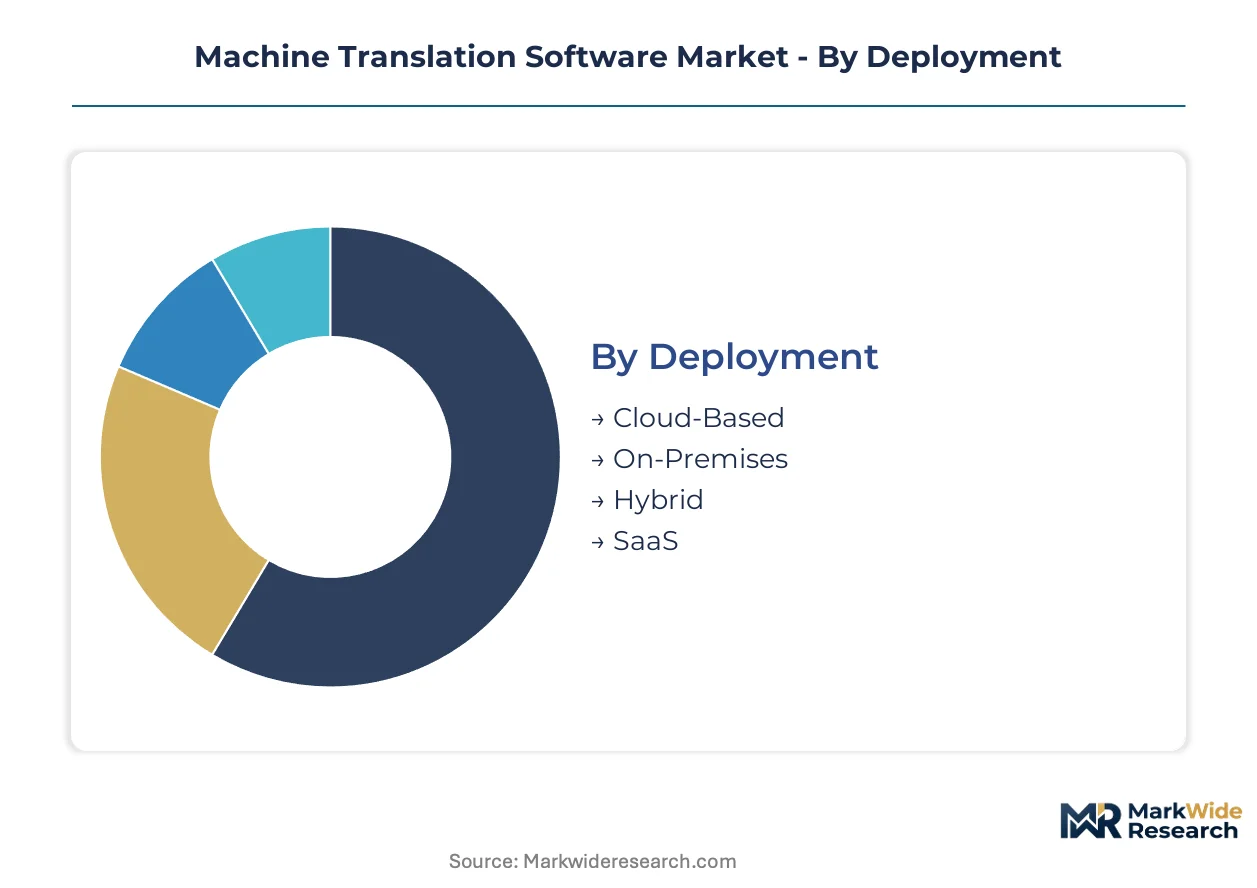
Machine translation software procurement varies sharply by deployment sensitivity, with regulated industries imposing distinct compliance architectures on each segment. Buyers calibrate total cost of ownership against data sovereignty requirements and inference latency tolerances.
Deployment:
EU AI Act risk classifications and FDA software-as-a-medical-device scrutiny create divergent procurement specifications across infrastructure models.
- Cloud-Based:Elastic GPU clusters serve episodic translation workloads without capital expenditure. Pharmaceutical sponsors in Germany and France favor this model for clinical trial documentation where audit trails must demonstrate human oversight protocols per EU AI Act mandates.
- On-Premises:Air-gapped installations host classified diplomatic communications and proprietary industrial engineering documentation. German automotive exporters deploy these systems to protect battery chemistry specifications from third-party cloud exposure.
- Hybrid:Sensitive pre-processing occurs locally before cloud-based neural inference. Japanese pharmaceutical firms use this architecture to isolate patient identifiers while leveraging transformer-scale models.
- SaaS:Browser-accessible translation portals with consumption-based metering. Small and medium exporters in India access METI-equivalent subsidy programs through certified SaaS procurement.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Technology:
BLEU score benchmarks and training data accessibility determine enterprise displacement timelines from legacy architectures.
- Neural Networks:Transformer architectures achieve superhuman translation quality for high-resource language pairs. Industrial exporters in Germany demand these systems for technical documentation where ISO 17100 compliance requires auditable quality metrics.
- Statistical Models:Phrase-based systems persist in low-connectivity environments and legacy middleware integrations. Government archives in India maintain these installations for Hindi-English judicial documentation where retraining costs exceed replacement budgets.
- Rule-Based Systems:Handcrafted linguistic rules govern highly regulated terminology domains. French hospital networks retain these for medical device labeling where predicate device equivalence demands deterministic output.
- Hybrid Approaches:Neural engines with rule-based post-editing constraints. CDSCO regulatory filings in India require this architecture to balance automation scale with pharmacovigilance terminology precision.
Procurement momentum concentrates in Neural Networks; Hybrid Approaches gain share in regulated verticals.
End User:
Budget scale and compliance obligation intensity segment buyer behavior across institutional categories.
- Corporations:Enterprise procurement committees negotiate separate rate cards for marketing content versus regulatory submissions. US medical device manufacturers dominate volume through FDA submission localization budgets.
- Educational Institutions:Research libraries and international student services drive demand for low-resource language pairs. Academic access terms for parallel corpora constrain commercial model development.
- Government Agencies:OECD procurement specifications increasingly reference ISO 17100 and EU AI Act compliance infrastructure. German court systems mandate human-in-the-loop ratios for judicial translation.
- NGOs:Humanitarian documentation and refugee processing require rapid-deployment translation capabilities. Grant-funded operations favor SaaS consumption models over capital-intensive installations.
Revenue concentration sits with Corporations; compliance complexity peaks with Government Agencies.
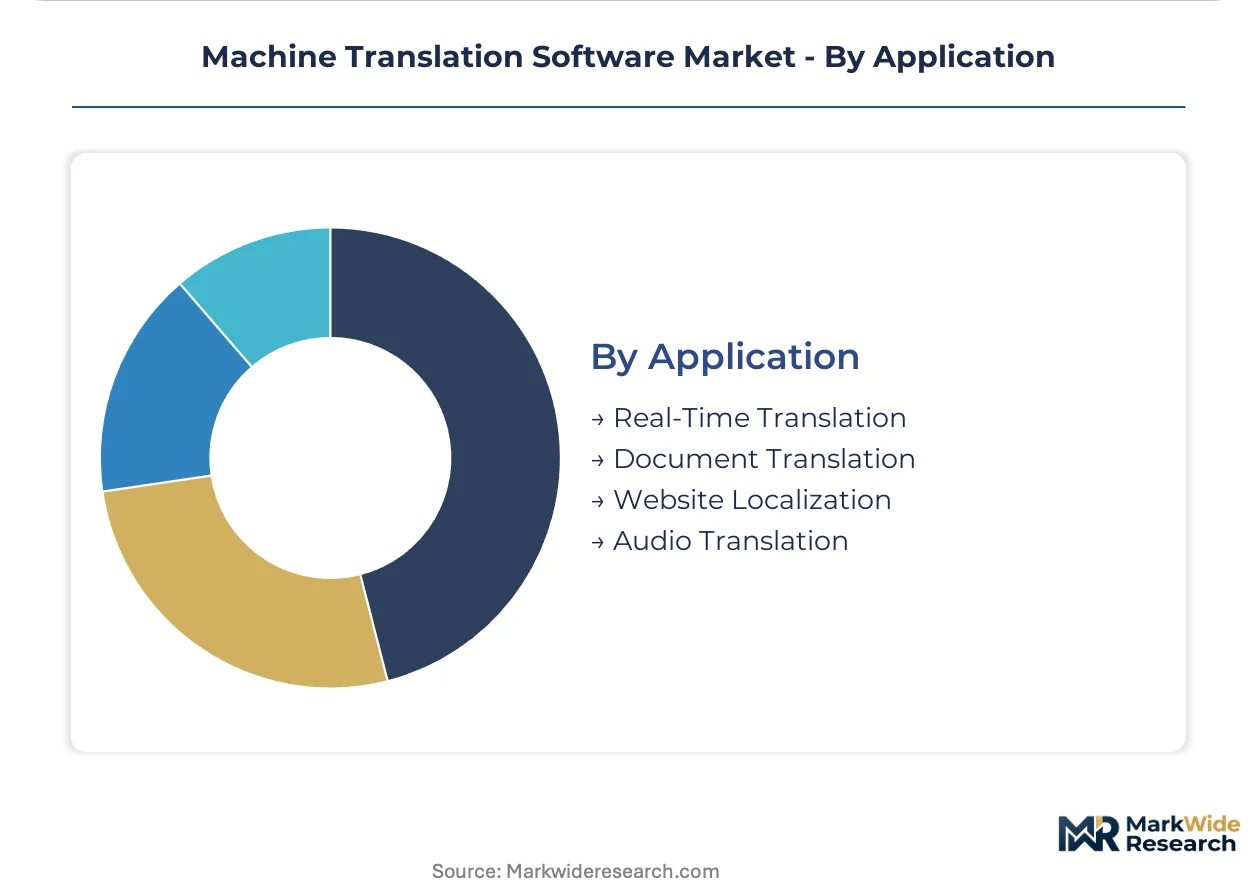
Application:
Latency requirements and review cycle depth determine margin architecture across use cases.
- Real-Time Translation:Sub-second inference for video conferencing and customer service chat. E-commerce platforms in Germany and France deploy these for cross-border product catalog queries.
- Document Translation:Batch processing with legal review workflows and version control. This application commands the deepest margin pools given compliance and liability frameworks.
- Website Localization:Continuous deployment pipelines for multilingual content management. Marketing content volume scales elastically without proportional human translator expansion.
- Audio Translation:Speech-to-text neural pipelines feeding translation engines. Real-time multilingual video conferencing represents untapped enterprise demand as text-to-speech synthesis converges.
Margin depth favors Document Translation; adoption velocity favors Real-Time Translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transformer architecture development concentrates in the United States and Germany, where cloud infrastructure density and research university networks feed specialized neural model training. Demand dispersion follows industrial export corridors and regulatory compliance mandates across distinct national procurement specifications.
United States
Pharmaceutical sponsors and medical device manufacturers drive enterprise procurement for FDA-compliant translation workflows. The FDA's software-as-a-medical-device scrutiny extends to clinical trial documentation tools, forcing auditable machine translation investments. Boston and San Francisco Bay Area biotech clusters anchor demand concentration for regulatory submission localization.
Germany
Automotive exporters and industrial machinery manufacturers require ISO 17100-certified technical translation for cross-border engineering documentation. The EU AI Act mandates risk classification for automated translation in judicial contexts, compelling German court systems to upgrade legacy infrastructure. Stuttgart and Munich engineering hubs concentrate procurement for battery chemistry and precision manufacturing documentation.
Japan
METI localization subsidies accelerate small and medium exporter adoption of BLEU-certified translation platforms. Government procurement specifications favor automated solutions for technical documentation export compliance. Osaka and Nagoya manufacturing belts generate concentrated demand for English-Japanese industrial translation at scale.
India
Pharmaceutical export documentation to CDSCO requires English-Hindi technical translation capabilities that domestic vendors struggle to supply. The country's national pharmaceutical regulator imposes strict pharmacovigilance terminology standards on regulatory filings. Hyderabad and Mumbai life sciences clusters drive specialized neural model procurement for generic drug export compliance.
France
Hospital networks and medical device labeling operations demand deterministic translation output for predicate device equivalence documentation. The EU AI Act risk classification framework applies to healthcare automated translation, requiring human oversight protocol documentation. Paris and Lyon healthcare technology procurement teams lead compliant infrastructure adoption.
Machine Translation Software Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with transformer-scale neural architectures concentrating among hyperscale cloud operators while specialized accuracy providers compete on European language-pair performance. The vendor base separates into three strategic tiers: infrastructure-integrated platforms, accuracy-specialized engines, and service-augmented localization providers. Dominant competitive moves include API ecosystem expansion and vertical integration into document management workflows.
Within the accuracy-specialized tier, DeepL GmbH exemplifies European language-pair optimization, while Google LLC and Microsoft Corporation anchor the infrastructure-integrated archetype through cloud platform dominance. These three occupy positions that represent distinct competitive vectors: neural architecture scale, regional linguistic precision, and enterprise software integration depth.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Amazon Web Services Inc. |
| DeepL GmbH |
| IBM Corporation |
| SYSTRAN International Co. Ltd. |
| Lionbridge Technologies Inc. |
| Welocalize Inc. |
| Baidu Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 17100 quality certification gates both supplier qualification and price differentiation simultaneously, forcing vendors to invest in auditable human-in-the-loop infrastructure before accessing premium procurement channels. German industrial exporters and US pharmaceutical sponsors demand certified workflows, compressing margins for uncertified competitors while rewarding compliance-heavy providers with rate premiums.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for high-stakes automated translation in judicial and healthcare contexts. Three-tier pricing structure across premium, standard, and economy levels separates BLEU-certified enterprise deployments from uncertified SaaS consumption. Cost compression in the economy tier is intensifying because GPU cluster pricing volatility erodes per-document margins. Small and medium exporters in subsidy-dependent markets exhibit highest price sensitivity, while FDA-regulated pharmaceutical sponsors show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Strategic stockpiling of training data and GPU compute capacity dominates inventory strategy over just-in-time approaches, given the concentration of high-quality parallel corpora in academic and governmental archives. Supply concentrates in the United States, Germany, and China for transformer-scale model development, with proprietary training data sets serving as critical inputs alongside NVIDIA GPU clusters and cloud infrastructure. Single-source vulnerability around CUDA-dependent inference hardware threatens supply continuity. Distribution runs through API-first platforms and direct enterprise sales channels, with hyperscaler marketplaces capturing growing procurement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of computational linguists with rare language expertise and neural architecture optimization skills constrains vendor scaling velocity, creating defensive moats for incumbents with captive talent pools and acquisition vulnerabilities for challengers.
For Market Incumbents: Shield proprietary training data advantages through exclusive licensing agreements with academic archives and governmental language institutes. Fortify API ecosystem stickiness by embedding translation pipelines into document management workflows, neutralizing substitution threats from large language model platforms. Prioritize backward integration into GPU cluster operations to dampen cloud pricing volatility exposure. For New Entrants and Emerging Players: METI certification fast-tracks in Japan offer subsidized market entry for BLEU-certified solutions targeting small and medium exporters. Exploit underpenetrated speech-to-speech convergence opportunities in real-time multilingual video conferencing, where enterprise procurement specifications remain nascent. Lead with consumption-based SaaS metering to bypass capital-intensive on-premises sales cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across neural model training operations as transformer-scale architectures demand exponentially larger compute investments. Long-term viability favors platforms with diversified revenue across regulated verticals rather than horizontal generalists. Watch for FDA software-as-a-medical-device enforcement actions as inflection indicator for compliance-premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding translation APIs into Microsoft Teams and Azure ecosystems anchors corporate procurement decisions. |
| Acquisition of Specialist Firm | Buying rare-language computational linguist teams accelerates low-resource pair model development timelines. |
| Geographic Expansion | Establishing India operations captures CDSCO pharmaceutical export documentation demand. |
| Strategic Partnership | Alliances with document management vendors reduce legacy middleware integration friction. |
| Product Launch | Speech-to-speech convergence products target untapped real-time multilingual video conferencing demand. |
Study Parameters
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and integration specialists anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including SEC filings from hyperscaler cloud providers, FDA software-as-a-medical-device guidance documents, EU AI Act regulatory texts, and ISO 17100 certification records. Bottom-up segment sizing was triangulated with top-down market envelope analysis.
Sensitivity analysis tested forecast robustness across alternative GPU pricing trajectories and regulatory enforcement intensity scenarios. The analytical framework modeled deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern as core segmentation dimensions. CAGRs were derived from fitted growth curves against historical adoption inflection points, with clinical trial documentation volume and e-commerce cross-border listing growth serving as key demand-side inputs.
Decision-makers should treat outputs as directional under assumptions of continued transformer architecture dominance and stable EU AI Act enforcement timelines; material deviation would warrant model refresh. Revision becomes warranted when cloud GPU pricing volatility crosses thresholds that compress enterprise SaaS margins below sustainable levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Shift Planning Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Global Remote Desktop Management Market
Software & Services
Global Inspection Management Software Market
Software & Services
Global Testing Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Personalisation Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global Award Management Software Market
Software & Services
Patent Management Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Global OKR Software Market
Software & Services
Fitness App Market
Software & Services
Automotive Hypervisor Market
Software & Services
Service Scheduling Software Market