
 Custom Packaging Boxes Market | 2026-2036
Custom Packaging Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Packaging Boxes Market Outlook
Digital print-to-cut workflow integration is narrowing the gap between short-run customization and mass-production economics in box manufacturing. Fantastapack leverages web-to-print infrastructure to capture direct-to-brand orders with minimal sales friction. Green Bay Packaging anchors its position through captive pulp and paper supply, insulating margin pools from fiber volatility. Packlane differentiates via real-time 3D design interfaces that collapse proofing cycles from days to hours.
Custom packaging boxes are fabricated structures engineered from paperboard, corrugated fiberboard, or rigid substrates, typically scored, folded, and glued to specific dimensional tolerances for product containment, protection, and brand communication. Folding cartons dominate volume throughput due to flat-ship efficiency and high-speed auto-fill compatibility, while rigid boxes command premium positioning in cosmetics and luxury gifting where unboxing experience drives repurchase intent. Corrugated formats are capturing the fastest growth trajectory within e-commerce fulfillment, particularly among electronics and food and beverage end users where dimensional optimization reduces last-mile shipping penalties.
The EPA regulates corrugated medium emissions under Clean Air Act standards, while the EU Packaging and Packaging Waste Directive mandates extended producer responsibility schemes that reshape material selection across export-bound production. FDA compliance for food-contact paperboard coatings adds a compliance layer that filters out smaller converters lacking analytical testing capacity. Stakeholders must monitor how state-level recycled-content mandates in California and Washington propagate through national supply chains, as these rules will determine which material platforms and geographic production footprints retain structural cost advantage.
Market Dynamics
Digital print-to-cut workflow integration is collapsing minimum order quantities and compressing proofing cycles, fundamentally restructuring how brands source packaging and how converters configure capacity.
Growth Catalysts
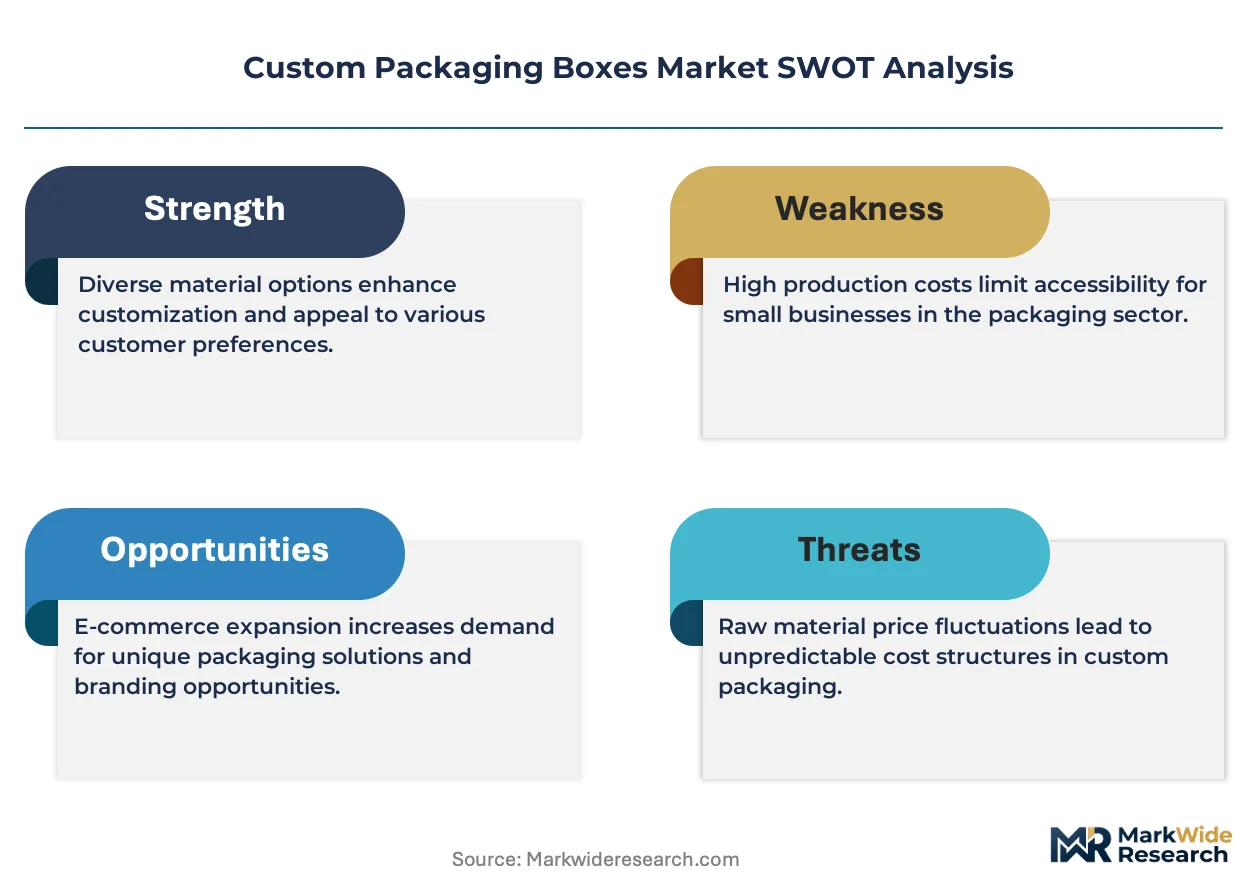
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are forcing brand owners to redesign boxes for recyclability, creating surge demand for fiber-based alternatives and certified compostable substrates.
- E-commerce fulfillment networks:Electronics and food and beverage shippers are adopting dimensional-optimized corrugated formats to minimize last-mile shipping penalties and damage rates.
- Water-based barrier coatings:Food-contact paperboard converters are replacing polyethylene linings with aqueous coatings to meet FDA compliance while maintaining heat-seal performance.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing with Chinese import policy shifts, squeezing margin pools for non-integrated converters lacking captive pulp supply.
- China manufacturing concentration:Export-bound production clusters around Shanghai and Guangdong create single-point vulnerability for brands sourcing from North American and European markets.
- Digital press throughput ceilings:Inkjet web widths and drying energy requirements limit run-length economics, blocking full displacement of flexo for mid-volume work.
Strategic Opportunities
- India domestic brand formation:Local direct-to-consumer labels in cosmetics and specialty foods are awakening to unboxing experience as a repurchase driver, opening short-run rigid box demand.
- California recycled-content mandates:Senate Bill 54 implementation is creating first-mover advantage for converters with verified post-consumer fiber supply chains and mass-balance certification.
- 3D configurator + ERP integration:Real-time design-to-production platforms are collapsing the traditional distributor layer, enabling direct-to-brand capture with minimal sales friction.
Industry Challenges
- Prepress automation talent scarcity:Converters struggle to hire operators who can simultaneously manage color management, die-line optimization, and web-to-print API maintenance.
- Food-contact analytical testing backlog:FDA compliance for novel barrier coatings requires third-party migration studies with 12-16 week turnaround, delaying new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Packaging Boxes Market |
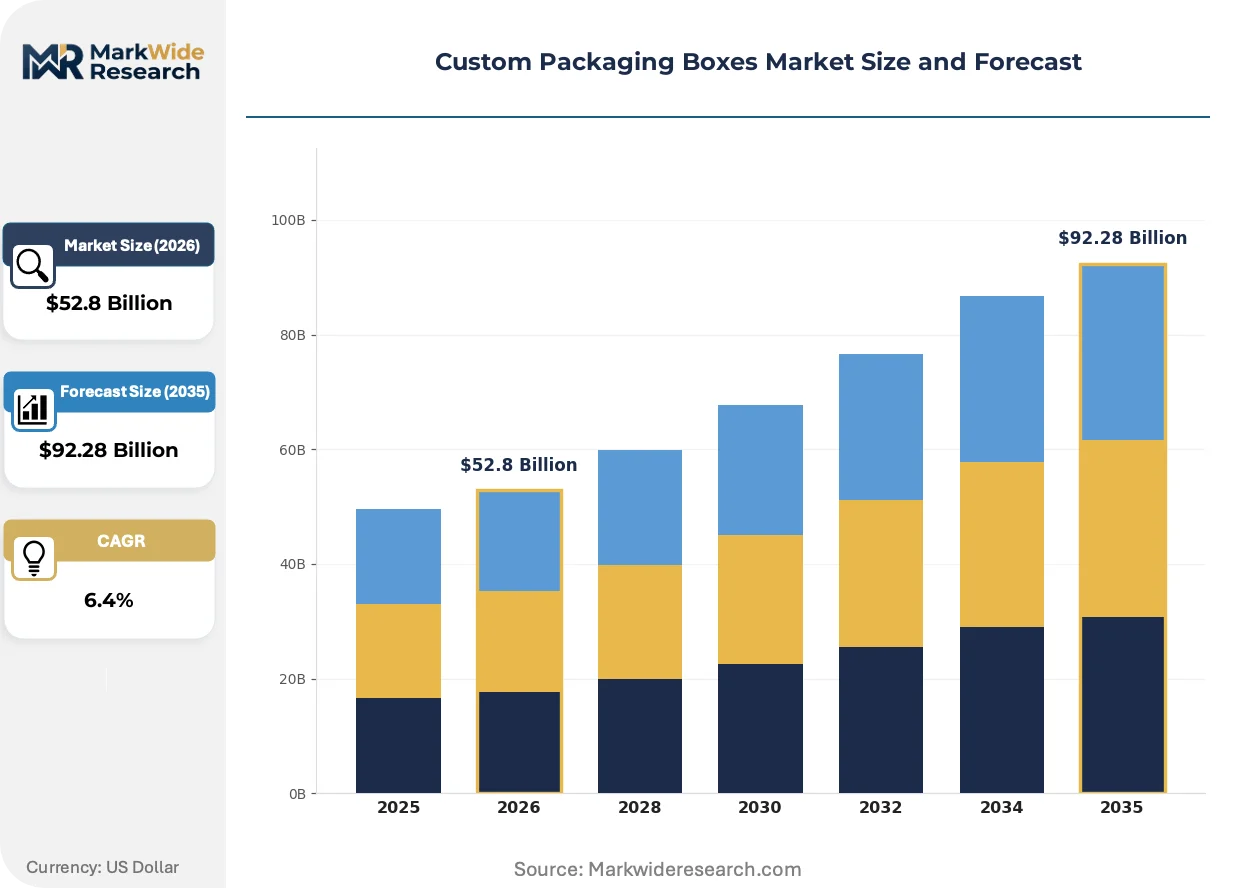
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxes, Rigid Boxes, Corrugated Boxes, Tuck Top Boxes Material: Cardboard, Kraft Paper, Plastic, Metal Size: Small, Medium, Large, Custom Sizes End User: Retail, Food & Beverage, Electronics, Pharmaceuticals |
| Companies Covered | Fantastapack, Instant Custom Boxes, Refine Packaging, The Custom Boxes, OXO Packaging, PakFactory, Impack, Green Bay Packaging, Packlane, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Packaging Boxes Market Strategic Shifts
Active reshaping in this market centers on the convergence of digital production tools with sustainability verification systems, compressing both physical and trust-based transaction costs simultaneously.
Fiber-based barrier technologies are hybridizing conventional paperboard with bio-derived moisture and grease resistance. Food and beverage brands in the ready-meal and frozen dessert segments are piloting these substrates at 10,000-50,000 unit runs. The technology is hybridizing what were previously separate supply chains for fiber and plastic packaging, enabling single-stream recovery without performance sacrifice.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from export-bound folding cartons. European converters are reformulating coatings and redesigning specifications to maintain oil resistance. Food service and fast-casual dining packaging bound for EU markets is experiencing the most acute reformulation pressure, with some brands accelerating migration to molded fiber alternatives.
Direct brand engagement through self-service design platforms is displacing traditional broker-mediated procurement in the sub-10,000 unit segment. Mid-market cosmetics and specialty food companies are building packaging specifications internally using browser-based 3D visualization tools. This pattern is most visible in North America and Western Europe, where digital-native brand managers prioritize speed over established supplier relationships.
Custom Packaging Boxes Market Segmentation
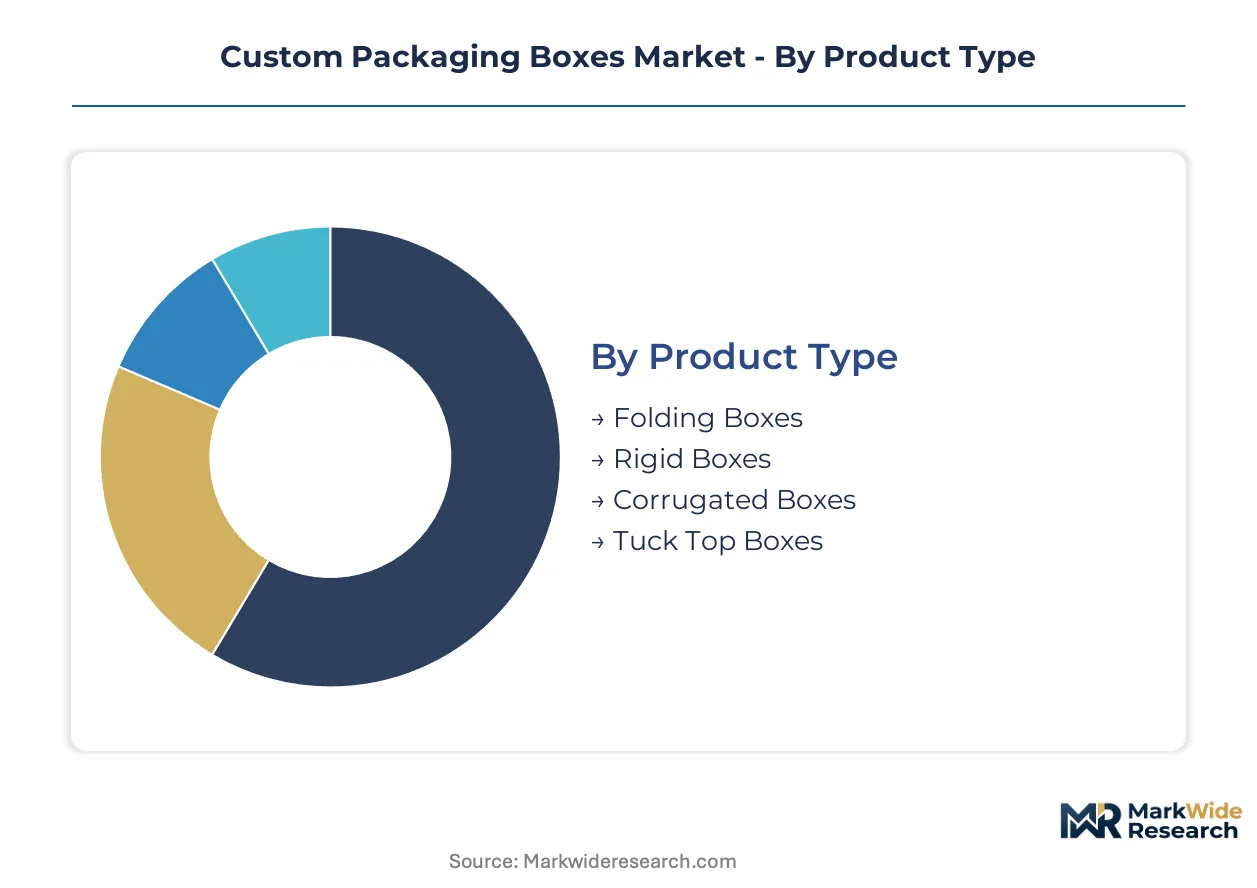
Segmentation in custom packaging boxes reveals how substrate selection, dimensional requirements, and end-use specifications create distinct margin pools and capability requirements across converter operations. Understanding these boundaries helps suppliers align capital deployment with demand concentration.
Product Type:
The use-case spectrum spans flat-ship efficiency for high-volume fulfillment through premium structural integrity for luxury unboxing experiences.
- Folding Boxes:Engineered from paperboard with pre-scored creases and tuck or glue closures, these formats ship flat and run on high-speed auto-fill lines. Demand concentrates in mass-market cosmetics and over-the-counter pharmaceuticals where line speed economics dominate supplier selection.
- Corrugated Boxes:Fluted medium sandwiched between linerboard faces provides stack strength and cushioning for dimensional-optimized e-commerce fulfillment. Electronics and food and beverage shippers in China and the United States are adopting these formats fastest to minimize last-mile shipping penalties and damage rates.
- Rigid Boxes:Thick paperboard wrapped around solid chipboard or greyboard cores delivers premium heft and unboxing ceremony. Luxury gifting and high-end cosmetics brands specify these for repurchase intent.
- Tuck Top Boxes:Self-locking lid configurations eliminate tape or glue for assembly speed in subscription box and sample kit applications. Direct-to-consumer brands favor these for warehouse labor efficiency.
The dominant share belongs to Folding Boxes, while Corrugated Boxes is closing the gap fastest.
Material:
Cost tier alignment separates commodity converters from certified sustainable suppliers in procurement decisions.
- Cardboard:Recycled-content paperboard and virgin kraft liners form the volume backbone, with FDA-compliant coatings required for food-contact applications. California and Washington recycled-content mandates are reshaping fiber sourcing verification requirements.
- Kraft Paper:Unbleached long-fiber stock provides tear resistance and natural aesthetic for organic food and artisan retail positioning. European demand under EU Packaging and Packaging Waste Regulation favors this substrate for single-stream recyclability.
- Plastic:PET, PP, and bio-derived films persist in moisture-critical and transparent-window applications despite fiber substitution pressure. REACH restrictions on additives are forcing reformulation for export-bound production.
- Metal:Tinplate and aluminum configurations serve premium spirits, confections, and collectible packaging where permanence signals value. Limited volume but high margin concentration.
Cardboard commands the volume base, though Kraft Paper is climbing the fastest as EPR schemes tighten.
Size:
Volume throughput and equipment utilization rates vary dramatically across dimensional bands.
- Small:Jewelry, cosmetics samples, and electronics accessories fit sub-100 cubic inch formats. These maximize sheet yield and minimize shipping cube.
- Medium:Standard apparel, footwear, and home goods dimensions represent the most competitive quoting environment with the thinnest margin pools.
- Large:Appliance, furniture, and bulk food formats require specialized corrugators and often regional production to control freight costs.
- Custom Sizes:Dimensional optimization for specific product footprints reduces void fill and shipping penalties. E-commerce fulfillment networks are standardizing these specifications.
Medium sizes retain the largest share, yet Custom Sizes is gaining share fastest as dimensional pricing spreads.
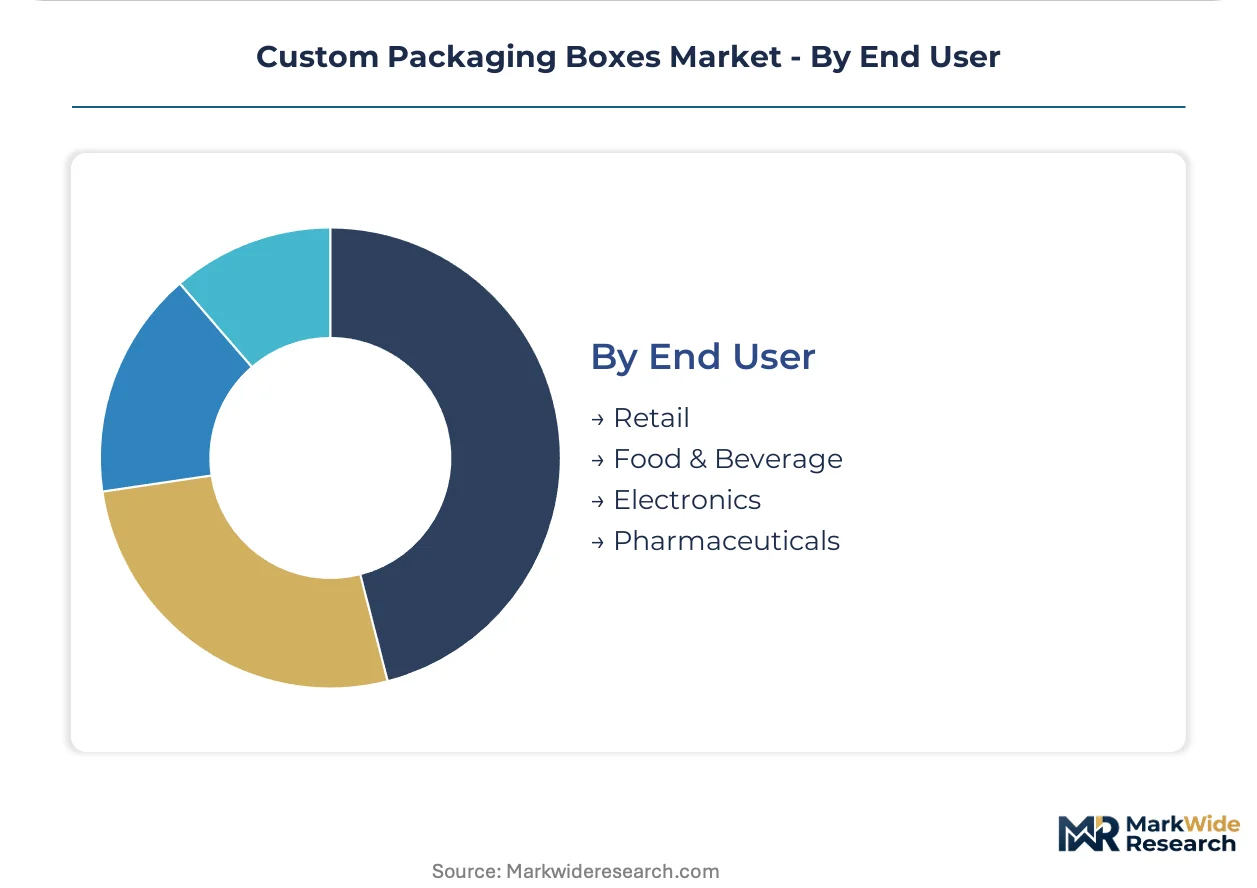
End User:
Application-specific compliance layers and unboxing expectation gaps create distinct supplier qualification barriers.
- Retail:Point-of-purchase displays and shelf-ready packaging demand high-graphic reproduction and rapid replenishment cycles. Mass merchant compliance programs filter supplier pools.
- Food & Beverage:FDA migration testing and barrier performance against moisture, grease, and oxygen define specification rigidity. Ready-meal and frozen dessert segments are piloting fiber-based barrier substrates at commercial scale.
- Electronics:ESD protection, drop testing, and anti-theft features layer onto dimensional optimization for parcel network compatibility. Smartphone and laptop unboxing experience drives rigid box specifications for premium tiers.
- Pharmaceuticals:Child-resistant closures, tamper evidence, and serialization for track-and-trace create the highest compliance burden. FDA validation requirements extend qualification timelines.
Retail holds the established position, while Food & Beverage is expanding most quickly as barrier coatings advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brand procurement managers in cosmetics, electronics, and specialty foods concentrate demand in manufacturing clusters with digital print infrastructure and fiber supply security. Regulatory pressure on recyclability is reshaping supplier qualification criteria across major economies.
United States
E-commerce fulfillment networks and direct-to-consumer subscription brands drive corrugated format adoption. EPA Clean Air Act standards govern emissions from medium production facilities. Manufacturing concentrates in Wisconsin and the Pacific Northwest, where integrated pulp-to-box operations serve national distribution.
China
Export-oriented manufacturing clusters supply North American and European brands with cost-optimized folding cartons and rigid boxes. MIIT dual carbon goals push converters toward renewable energy and fiber certification. Production gravity sits in Guangdong and Zhejiang provinces, where digital print capacity expanded fastest.
Germany
Precision engineering and luxury automotive unboxing specifications sustain rigid box demand. EU Packaging and Packaging Waste Directive extended producer responsibility schemes force redesign for single-stream recovery. The Baden-Württemberg and North Rhine-Westphalia corridors host specialized converters with FSC chain-of-custody certification.
India
Domestic direct-to-consumer brand formation in cosmetics and specialty foods awakens short-run rigid box procurement. BIS standards for food-contact paperboard filter supplier pools. Maharashtra and Gujarat manufacturing clusters add digital print lines to capture premium positioning demand from Mumbai and Delhi brand headquarters.
Brazil
Organic food retail expansion and artisan beverage branding drive kraft paper substrate preference. ANVISA food-contact compliance requirements extend qualification timelines for imported coatings. São Paulo state converters invest in aqueous barrier coating capacity to serve domestic ready-meal brands.
Custom Packaging Boxes Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service models. The vendor base segments between web-to-print platforms, integrated fiber producers, and regional job shops. Three archetypes dominate: captive-supply integrated mills, digital-native direct-to-brand platforms, and compliance-specialized food-contact converters. Competitive moves center on ERP integration for order-to-delivery compression and backward integration into pulp supply.
Among North American integrated producers, Green Bay Packaging anchors the captive-supply archetype with in-house pulp and paper production. Digital-native platforms include Fantastapack, which occupies a position in web-to-print infrastructure for direct brand capture, and Packlane, which exemplifies the 3D configurator interface tier collapsing proofing cycles. These three represent distinct strategic postures on automation depth and customer acquisition economics.
| Leading Market Players |
|---|
| Fantastapack |
| Instant Custom Boxes |
| Refine Packaging |
| The Custom Boxes |
| OXO Packaging |
| PakFactory |
| Impack |
| Green Bay Packaging |
| Packlane |
| Others |
Value Chain & Pricing Dynamics
Chinese OCC fiber concentration and integrated mill dominance in Guangdong and Zhejiang provinces compress margin pools for non-captive converters serving North American and European brand procurement. Cost-plus contracts with Old Corrugated Container indexation force smaller job shops to absorb feedstock volatility while premium rigid box specialists capture brand premiums through unboxing experience differentiation.
Pricing Analysis
Cost-plus contracts with OCC indexation dominate long-term agreements between integrated producers and mass-market retail brands. Pricing stratifies across premium rigid box, standard folding carton, and economy corrugated tiers based on fiber certification grade and customization depth. Cost compression in the economy tier intensifies because Chinese import policy shifts create feedstock price spikes that non-integrated converters cannot pass through. Mass-market cosmetics and over-the-counter pharmaceutical buyers exhibit highest price sensitivity, while luxury gifting brands prioritize unboxing ceremony over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn and Luxshare subsidiaries for electronics packaging, plus anonymous white-label converters for cosmetics and food service applications. Raw material flows draw from Canadian pulp mills, Brazilian eucalyptus plantations, and domestic OCC recovery networks. Single-source vulnerability concentrates in Shanghai and Guangdong export clusters where MIIT dual carbon enforcement could disrupt capacity. Distribution runs through brand-direct web-to-print platforms for sub-10,000 unit orders and traditional distributor networks for high-volume retail replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against molded fiber and reusable packaging systems that EU extended producer responsibility schemes actively promote. Incumbents must harden their position before regulatory acceleration tips procurement preferences.
For Market Incumbents: Pre-empt displacement by molded fiber alternatives through accelerated aqueous barrier coating certification for food-contact applications. Secure FSC chain-of-custody verification ahead of California Senate Bill 54 enforcement timelines. Captive pulp supply anchors margin pools against OCC volatility that squeezes non-integrated competitors.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat manufacturing corridors offer underpenetrated short-run rigid box demand from domestic direct-to-consumer cosmetics brands awakening to unboxing economics. Target specialty food subscription boxes with 3D configurator interfaces that collapse proofing cycles from days to hours. Lead with real-time ERP integration rather than price competition against established distributors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital print platforms lacking backward fiber integration. Five-to-ten year viability hinges on converting SaaS-style customer acquisition into captive supply economics. Monitor MIIT renewable energy enforcement intensity in Guangdong as signal for Chinese export cost structure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Green Bay Packaging's captive fiber production insulates margins from OCC volatility that disrupts competitors. |
| 3D Configurator Platform Deployment | Packlane's real-time design interface collapses proofing cycles and eliminates traditional distributor layers. |
| Aqueous Barrier Coating Certification | FDA-compliant food-contact coatings unlock ready-meal and frozen dessert segments migrating from polyethylene linings. |
| ERP Integration for Direct Brand Capture | Fantastapack's web-to-print infrastructure enables subscription box brands to bypass broker-mediated procurement. |
| FSC Chain-of-Custody Investment | Baden-Württemberg converters leverage certification to meet EU Packaging and Packaging Waste Directive single-stream recovery mandates. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers at cosmetics and electronics brands, prepress automation specialists at folding carton converters, and sustainability compliance officers at food-contact paperboard suppliers; plus secondary validation through EPA Clean Air Act enforcement records, EU Packaging and Packaging Waste Directive implementation guidance, FDA food-contact coating migration study databases, and customs trade flows for OCC fiber imports. Bottom-up unit economics from converter operations triangulated against top-down brand procurement spend patterns.
Forecast inputs considered substrate substitution elasticities, e-commerce fulfillment network expansion trajectories, and regulatory compliance cost pass-through capacity across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, end-use application, and regional manufacturing cluster. CAGRs were derived from volume-weighted growth rates applied to each segment's baseline and projected penetration curves. Digital press throughput ceilings and aqueous coating adoption S-curves shaped medium-term trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by molded fiber specialists or reusable packaging platforms would shift outcomes beyond modeled ranges. Quarterly review of MIIT dual carbon enforcement intensity, California recycled-content mandate implementation pace, and FDA food-contact coating approval backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Confectionery Packaging Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Pillow Boxes Market
Specialty Packaging
Europe Confectionery Packaging Market
Specialty Packaging
Europe Child Resistant Packaging Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Custom Inserts Market
Specialty Packaging
Specialty Labels Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Europe Luxury Packaging Market
Specialty Packaging
Specialty Uncoated Paper Label Market
Specialty Packaging
Specialty Lidding Films Market