
 Global Sensormatic Labels Market | 2026-2036
Global Sensormatic Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sensormatic Labels Market Intelligence
REACH compliance is broadening the cost-of-entry calculus for sensormatic label suppliers serving European retail accounts. Checkpoint Systems leverages its vertical integration into inlay manufacturing to sustain margin control across RFID and EAS product lines. Avery Dennison Corporation anchors its position through deep R&D intensity in sustainable adhesive formulations that meet evolving substrate regulations.
Sensormatic labels are pressure-sensitive or heat-activated tags incorporating radio frequency, acoustic magnetic, or near-field communication elements, typically operating at 8.2 MHz or 58 kHz for EAS detection and 860–960 MHz for UHF RFID backscatter. Their primary commercial purpose is to enable automated item-level identification, deter theft, and stream inventory telemetry across retail and logistics environments. RFID labels occupy the fastest-expanding margin pool as omnichannel fulfillment demands real-time shelf visibility, while EAS labels retain dominance in loss prevention deployments at mass merchant formats. Barcode labels remain mature across warehousing applications where cost sensitivity overrides connected-tag requirements.
The EU Green Deal and REACH frameworks in Europe, alongside FCC equipment authorization rules in the United States, collectively elevate material traceability and electromagnetic compatibility standards that filter market access. Japan's METI circular economy guidelines and China's GB standards for electronic product environmental assessment add compliance layers for suppliers with Asia-Pacific manufacturing footprints. Stakeholders must monitor regulatory divergence on substrate recyclability and frequency allocation as these forces reshape supplier qualification criteria faster than product lifecycles turn.
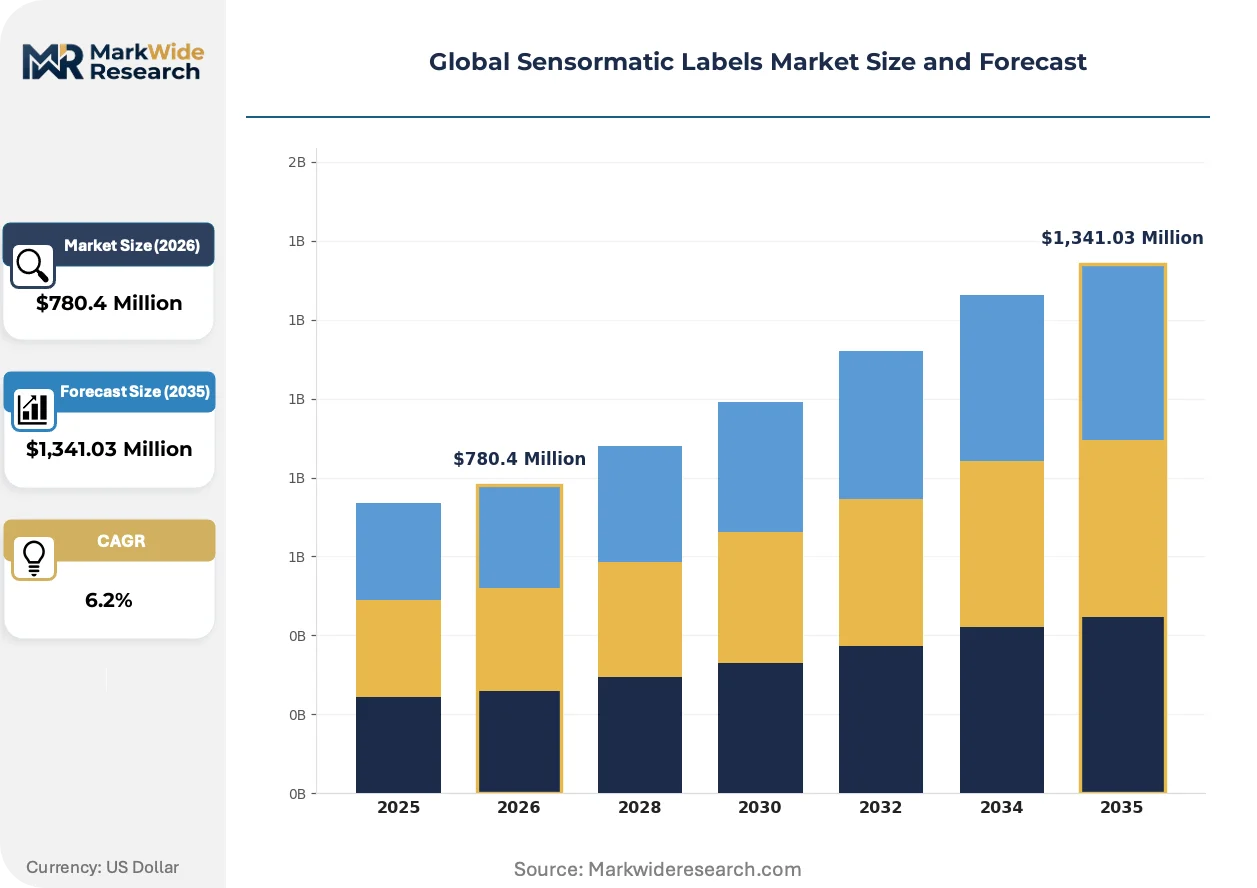
Market Dynamics
RFID-enabled sensormatic labels are compressing EAS dominance as omnichannel retail mandates real-time shelf visibility and automated replenishment across fulfillment networks.
Growth Catalysts
- EU Green Deal substrate mandates:REACH compliance requirements for recyclable adhesives and paper-based inlays are accelerating supplier qualification cycles for European retail accounts.
- Mass merchant loss prevention:Acoustic magnetic EAS labels retain deployment priority at big-box formats where high-throughput deactivation gates deter organized retail crime.
- China smart retail infrastructure:GB standards for electronic product environmental assessment are anchoring domestic RFID label demand through state-backed omnichannel pilot programs.
Market Restraints
- Copper and silver ink volatility:Conductive antenna printing relies on precious metal supply chains concentrated in Chilean copper and Chinese silver processing.
- UHF frequency fragmentation:Divergent 860–960 MHz allocation across national regulators forces multi-SKU antenna designs that inflate inventory carrying costs.
- Barcode cost floor:Legacy linear symbology retains warehouse dominance where item-level connected-tag premiums exceed labor arbitrage savings.
Strategic Opportunities
- India organized retail expansion:FDI liberalization in multi-brand retail is creating first-mover advantage for RFID-enabled inventory visibility platforms.
- Blockchain-anchored provenance:Immutable ledger integration with NFC-enabled sensormatic labels enables luxury authentication and gray-market diversion tracking.
- Japan METI circular economy guidelines:Extended producer responsibility frameworks are mandating take-back infrastructure that favors reusable transponder architectures.
Industry Challenges
- RF engineer scarcity:Antenna design optimization for detuning resistance requires electromagnetic simulation expertise concentrated in semiconductor and telecom labor pools.
- ISO/IEC 18000-63 certification timelines:Interoperability testing for UHF RFID backscatter protocols extends product launch cycles by 8–14 months.
- Legacy WMS integration friction:ERP systems at mid-market retailers lack native RFID middleware, forcing custom API development for item-level telemetry ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sensormatic Labels Market |
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,341.03 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Labels, EAS Labels, Barcode Labels, NFC Labels, Magnetic Labels Application: Inventory Management, Loss Prevention, Asset Tracking, Supply Chain Optimization, Brand Protection End User Industry: Retail Chains, Warehousing, Logistics Providers, Distribution Centers, Specialty Stores Distribution Channel: Direct Sales, Online Retailers, Wholesale Distributors, System Integrators, Resellers |
| Companies Covered | Johnson Controls, Checkpoint Systems, Avery Dennison Corporation, Zebra Technologies Corporation, CCL Industries Inc, Sato Holdings Corporation, ALL-TAG Corporation, Honeywell International Inc, Custom Security Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sensormatic Labels Market Strategic Shifts & Innovations
Passive UHF RFID sensormatic labels are overtaking acoustic magnetic EAS as the default architecture for inventory intelligence, driven by cloud-native retail operating systems and automated fulfillment robotics.
Chipless RFID encoding through printable graphene antennas is overtaking silicon-based inlays in cost-sensitive apparel applications. Fast-fashion retailers in Turkey and Bangladesh are piloting all-printed transponders that eliminate semiconductor die attach costs. This shift is overtaking traditional RFID economics by collapsing unit costs toward barcode parity while retaining wireless readability.
REACH substance restrictions on halogenated flame retardants are tightening electromagnetic compatibility compliance pathways for European-bound sensormatic labels. ECHA substance of very high concern listings now cover specific epoxy formulations common in RFID strap attach processes. German automotive aftermarket retailers are responding by demanding full material disclosure documentation from Asian contract manufacturers.
Buyers are consolidating sensormatic label procurement under unified source-to-pay platforms that bundle RFID inlays, EAS tags, and thermal transfer media. Third-party logistics providers operating US East Coast distribution corridors are displacing direct manufacturer relationships with category-managed vendor pools. This concentration is most visible among grocery chains implementing standardized loss-prevention architectures across banner portfolios.
Global Sensormatic Labels Market Segmentation
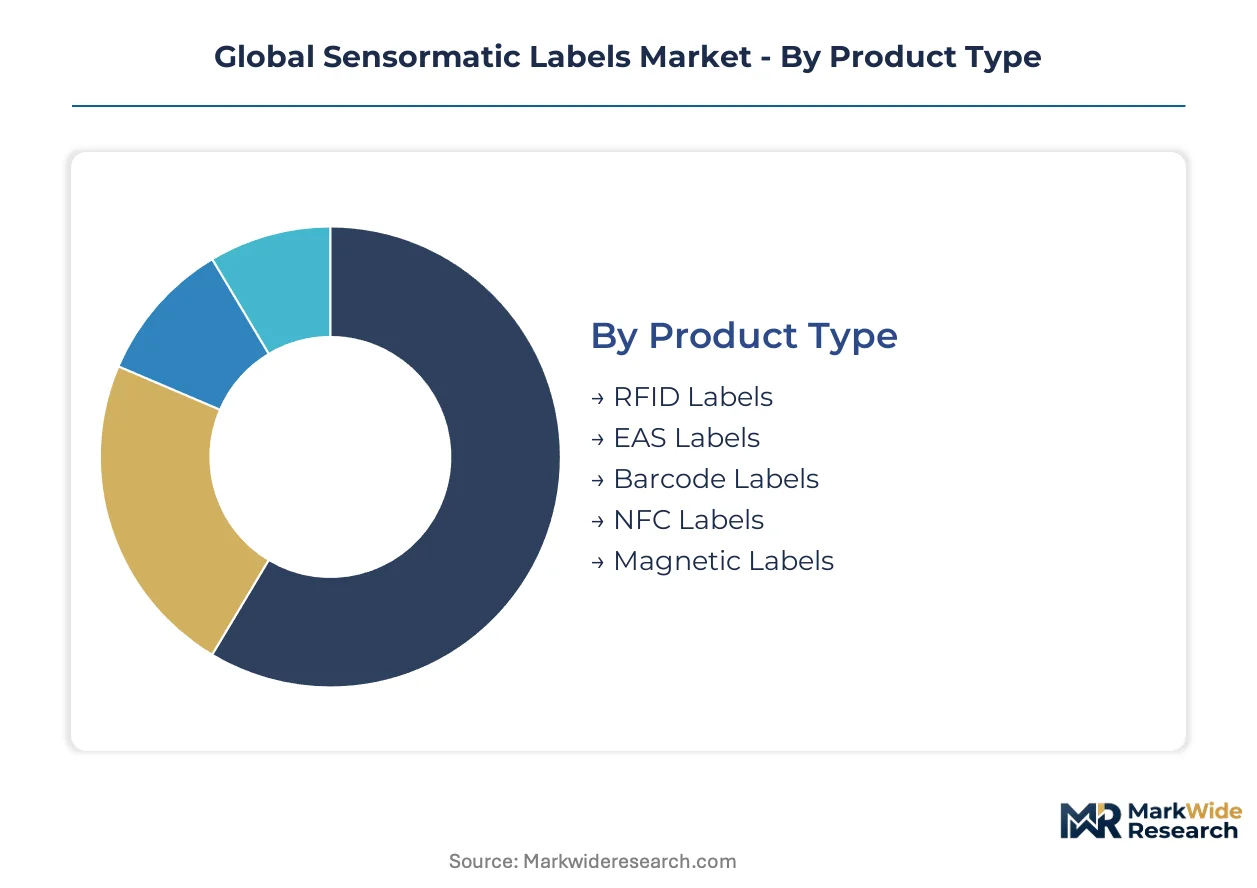
Sensormatic label procurement splits sharply between high-volume commodity tiers and precision-engineered premium categories. Material composition, frequency specification, and integration complexity drive margin dispersion across product architectures.
Product Type:
RFID labels command premium positioning against mature barcode alternatives, while NFC variants carve emerging authentication niches.
- RFID Labels:UHF backscatter tags operating at 860–960 MHz incorporate etched aluminum or copper antennas on PET substrates. Demand concentrates in United States omnichannel grocery networks where automated fulfillment robotics requires real-time shelf telemetry.
- EAS Labels:Acoustic magnetic and radio frequency variants at 58 kHz and 8.2 MHz respectively embed amorphous metal strips or ferrite cores within pressure-sensitive laminates. German mass merchant formats sustain deployment priority for organized retail crime deterrence at high-throughput checkout gates.
- Barcode Labels:Linear symbology and 2D matrix codes on thermal transfer or direct thermal substrates serve cost-sensitive warehouse applications.
- NFC Labels:Near-field communication tags at 13.56 MHz enable smartphone-tap authentication for luxury goods.
- Magnetic Labels:Strip-based magnetic encoding retains legacy presence in library and document management systems.
Today's leader: EAS Labels. Tomorrow's challenger: RFID Labels.
Application:
Use-case maturity varies from ubiquitous inventory visibility to nascent blockchain-anchored provenance tracking.
- Inventory Management:Item-level RFID tagging enables automated cycle counting and shelf replenishment alerts. China's state-backed smart retail pilot programs in Shanghai and Shenzhen anchor deployment velocity for cloud-native inventory platforms.
- Loss Prevention:EAS gate-based detection at store exits remains the dominant shrinkage control mechanism. United States big-box retailers sustain capital allocation for acoustic magnetic systems despite RFID encroachment.
- Asset Tracking:Returnable transport item tagging for pallets and totes extends label durability requirements.
- Supply Chain Optimization:Cross-dock visibility through RFID portal reads reduces dwell time in logistics corridors.
- Brand Protection:NFC-enabled authentication combats gray-market diversion in cosmetics and pharmaceuticals.
Inventory Management captures current investment flows. Brand Protection is climbing the fastest as authentication premiums expand.
End User Industry:
Customer concentration tilts toward retail chains with warehousing and logistics providers trailing in connected-tag adoption.
- Retail Chains:Multi-banner grocery and apparel operators deploy mixed EAS-RFID architectures across store portfolios. India's FDI-liberalized multi-brand retail sector creates first-mover opportunity for integrated loss-prevention and inventory visibility platforms.
- Warehousing:Third-party logistics operators in United States East Coast distribution corridors consolidate label procurement under category-managed vendor pools.
- Logistics Providers:Parcel and freight carriers pilot RFID for package-level tracking in last-mile networks.
- Distribution Centers:Automated sortation systems drive demand for machine-readable label consistency.
- Specialty Stores:High-value electronics and luxury boutiques prioritize discrete EAS tag formats.
Retail Chains dominate current procurement volumes. Warehousing is gaining share fastest as 3PL consolidation accelerates.
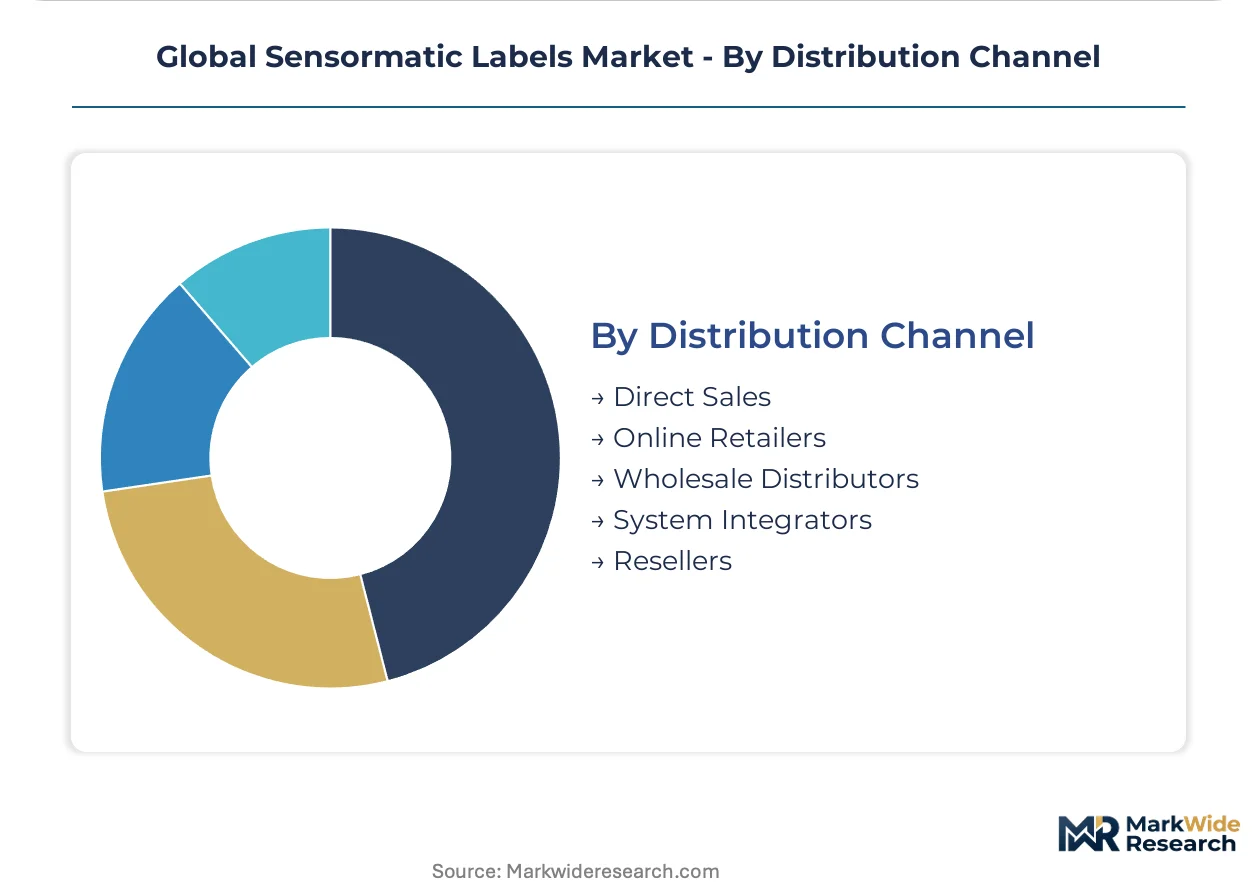
Distribution Channel:
Channel structure reflects the technical complexity gap between standardized commodity labels and integrated system deployments.
- Direct Sales:Manufacturer-direct relationships serve enterprise retail accounts requiring customized inlay-antenna tuning for specific merchandise categories. REACH compliance documentation and FCC equipment authorization support necessitate technical sales engineering.
- System Integrators:Value-added resellers bundle sensormatic labels with middleware, gate hardware, and ERP connector development. Japan's METI circular economy guidelines favor integrators offering take-back infrastructure for reusable transponder architectures.
- Online Retailers:E-commerce platforms serve small-format retailers with standardized EAS and barcode label SKUs.
- Wholesale Distributors:Broad-line industrial distributors stock thermal transfer media and generic EAS tags.
- Resellers:Regional security equipment dealers provide localized installation and maintenance services.
Direct Sales anchors premium transactions. System Integrators show the steepest expansion trajectory as middleware complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RFID antenna design talent clusters in Shenzhen, Munich, and Boston anchor regional capability formation. European REACH compliance engineers and Chinese GB standards specialists concentrate in distinct regulatory knowledge pools. Japanese METI circular economy consultants form a specialized workforce in Tokyo and Osaka.
United States
Omnichannel grocery networks in the Midwest and Southeast drive UHF RFID label demand for automated fulfillment robotics. FCC equipment authorization rules mandate electromagnetic compatibility testing for 860–960 MHz backscatter devices. The Chicago distribution corridor anchors third-party logistics consolidation of sensormatic label procurement under category-managed vendor pools.
Germany
Mass merchant formats in North Rhine-Westphalia sustain acoustic magnetic EAS deployment for organized retail crime deterrence. ECHA substance of very high concern listings now cover specific epoxy formulations in RFID strap attach processes. Stuttgart automotive aftermarket retailers demand full material disclosure documentation from Asian contract manufacturers.
China
State-backed smart retail pilot programs in Shanghai and Shenzhen anchor cloud-native inventory platform deployment velocity. GB standards for electronic product environmental assessment mandate substrate traceability for domestic RFID label production. The Yangtze River Delta concentrates inlay manufacturing capacity serving both domestic consumption and export markets.
India
FDI liberalization in multi-brand retail creates first-mover opportunity for integrated loss-prevention platforms in Maharashtra and Karnataka. BIS certification requirements for electronic products filter market access for imported sensormatic label components. Mumbai and Bangalore retail clusters pilot mixed EAS-RFID architectures across expanding store portfolios.
Japan
METI circular economy guidelines mandate extended producer responsibility frameworks favoring reusable transponder architectures. JIS standards for electromagnetic compatibility add compliance layers for UHF RFID backscatter protocols. The Kansai industrial corridor concentrates system integrators offering take-back infrastructure for reusable label formats.
Global Sensormatic Labels Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with captive RFID inlay production. Checkpoint Systems exemplifies backward integration into antenna manufacturing, while Avery Dennison Corporation anchors premium positioning through adhesive formulation R&D. Zebra Technologies and Honeywell International occupy hardware-software integration archetypes. Strategic moves concentrate on middleware platform acquisitions and sustainable substrate partnerships.
Within the diversified conglomerate tier, Johnson Controls and Honeywell International represent industrial-scale players with security technology heritage. Checkpoint Systems and Avery Dennison Corporation exemplify specialists with upstream control over inlay manufacturing. Zebra Technologies anchors the hardware-software integration vector. Sato Holdings Corporation occupies a position among Asia-Pacific headquartered label converters. CCL Industries exemplifies the packaging-specialist archetype expanding into sensormatic applications.
| Leading Market Players |
|---|
| Johnson Controls |
| Checkpoint Systems |
| Avery Dennison Corporation |
| Zebra Technologies Corporation |
| CCL Industries Inc |
| Sato Holdings Corporation |
| ALL-TAG Corporation |
| Honeywell International Inc |
| Custom Security Industries Inc |
| Others |
Cost & Logistics Intelligence
RFID antenna design engineers concentrated in Shenzhen, Munich, and Boston anchor labor-cost differentials that widen pricing-tier spreads between premium UHF inlays and commodity EAS labels. REACH compliance documentation requirements and FCC equipment authorization testing add fixed-cost layers that suppliers recover through volume-scaled contracts or premium positioning.
Pricing Analysis
Bundled hardware-software-service contracts dominate enterprise retail accounts, while unbundled per-unit transactional pricing serves mid-market buyers lacking integration budgets. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 18000-63 certified UHF RFID inlays from uncertified alternatives and legacy barcode thermal media. Pricing pressure stems from copper and silver ink volatility in conductive antenna printing. Mass merchant procurement teams exhibit highest price sensitivity; luxury brand protection buyers accept premium NFC authentication premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese silver processing and Chilean copper concentrate for conductive antenna inks. Inlay manufacturing concentrates in China, Germany, and the United States, drawing from PET substrate suppliers in Taiwan and South Korea and amorphous metal strip producers in Japan. Supply chain risk centers on UHF frequency fragmentation forcing multi-SKU antenna designs. Distribution runs through direct manufacturer relationships for enterprise accounts and category-managed vendor pools for third-party logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sensormatic Labels Market functions as a stable compounder anchored by omnichannel retail infrastructure deployment that sustains recurring RFID label demand across store refurbishment cycles.
For Market Incumbents: To counter chipless RFID graphene antenna pilots in Turkey and Bangladesh, deepen backward integration into sustainable adhesive formulation R&D and expand captive inlay capacity in Yangtze River Delta manufacturing clusters. Prioritize REACH-compliant substrate partnerships to defend European retail account access against regulatory disqualification.
For New Entrants and Emerging Players: System integrators offering ERP middleware and take-back infrastructure represent the most accessible channel partners. Target India's FDI-liberalized multi-brand retail sector in Maharashtra and Karnataka with mixed EAS-RFID architecture bundles. Lead with cloud-native inventory visibility platforms that bypass legacy WMS integration friction.
For Investors and Strategic Acquirers: Industrial conglomerates with security technology heritage are the most active acquirer in this space. Five-to-ten-year viability rests on middleware platform consolidation and sustainable substrate IP. Target antenna design boutiques with electromagnetic simulation expertise. Monitor GB standards evolution in China as inflection indicator for domestic production preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Platform Acquisition | ERP connector development capabilities anchor system integrator valuations as WMS integration friction rises. |
| Sustainable Substrate Partnership | ECHA substance restrictions on halogenated flame retardants favor adhesive suppliers with REACH-compliant formulation IP. |
| Antenna Design Boutique Purchase | RF engineer scarcity in semiconductor and telecom labor pools elevates electromagnetic simulation expertise premiums. |
| Take-Back Infrastructure Buildout | METI circular economy guidelines in Japan mandate extended producer responsibility for reusable transponder architectures. |
| GB Standards Certification Investment | State-backed smart retail pilots in Shanghai and Shenzhen filter market access through domestic environmental assessment compliance. |
Research Approach
Bottom-up retail chain and logistics provider modeling reconciled against top-down inlay manufacturing capacity tracking forms the analytical core. Primary interviews with RFID program directors at omnichannel grocery networks, EAS loss prevention managers at mass merchant formats, procurement leads at third-party logistics operators, and antenna design engineers at inlay manufacturers combined with secondary validation against FCC equipment authorization filings, ECHA substance restriction updates, GB standards documentation, and customs trade data for PET substrates and conductive inks.
Historical trendline analysis of label deployment density per retail square meter and RFID gate installation trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, application use-case, end-user industry vertical, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year volume estimates, with specific inputs from omnichannel fulfillment robotics adoption rates and organized retail crime incidence reporting.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UHF frequency allocation harmonization, precious metal supply disruptions, and REACH substance restriction expansions. Forecasts reflect documented assumptions about retail capital expenditure cycles and smart infrastructure subsidy programs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Global Pressure Labels Market
Labels
Global Cryogenic Label Market
Labels
Coated Wet Glue Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Hang Tags Market
Labels
Foam Labels Market
Labels
Wet Glue Labels Market
Labels
BOPP Labels Market
Labels
Repositionable Labels Market
Labels
Wash Off Labels Market
Labels
Domed Labels Market
Labels
Polyester Labels Market
Labels
ESD Protective Signage Labels Market
Labels
Tags Market
Labels
Laser Printable Wristbands Market
Labels
Fiber Optic Labels Market