
 Extrusion Press Market | 2026-2036
Extrusion Press Market Size, Share, and Industry Trends Forecast 2026-2036
Extrusion Press Market Foresight
Multi-source procurement for critical press components is broadening as OEMs reduce dependency on single foundries. SMS group GmbH leverages its captive metallurgy expertise to control billet quality from melt to finished press. Yizumi Precision Machinery Co., Ltd. anchors its position through aggressive automation integration in Guangdong facilities. Danieli competes via specialized steel-frame designs for high-cycle aluminum extrusion lines.
An extrusion press is a heavy-duty forming machine that applies continuous compressive force through a ram to push heated or room-temperature billet through a shaped die, typically generating pressures from 1,000 to 12,000 metric tons depending on material and profile complexity. Its primary purpose is producing constant cross-section profiles—aluminum window frames, copper busbars, polymer tubing—for downstream industrial and construction use. Twin-screw configurations command premium pricing in polymer compounding where mixing precision determines output quality. Metal extrusion applications absorb the largest installed base, though food processing lines represent the fastest upgrade cycle as hygienic design standards tighten. Direct extrusion technology dominates volume shipments, but indirect extrusion is gaining traction among specialty alloy producers seeking reduced friction losses.
The EPA enforces emissions thresholds for heat-treatment furnaces integrated with U.S. extrusion lines, while REACH compliance in Europe restricts certain lubricant chemistries used in cold extrusion processes. China's MIIT mandates energy-efficiency labeling under revised GB standards, pressuring domestic press builders toward servo-hydraulic retrofits. Stakeholders must weigh capital allocation between greenfield capacity in Southeast Asian industrial zones and modernization of legacy European press fleets.
Market Dynamics
Servo-hydraulic retrofits are compressing energy intensity curves across installed press fleets, forcing capital allocation trade-offs between modernization and greenfield expansion in East Asian manufacturing clusters.
Growth Catalysts
- Automotive lightweighting mandates:Aluminum chassis programs at German and Japanese OEM plants are pulling high-tonnage press capacity into dedicated supply agreements. Tier-1 extruders in the Chubu region around Nagoya are commissioning 8,000+ ton units for structural profiles.
- REACH lubricant restrictions:Cold extrusion lines across EU member states are retrofitting aqueous-based die lubrication systems ahead of ECHA compliance deadlines. This hardware refresh cycle is accelerating replacement demand for legacy hydraulic architectures.
- China's GB energy-efficiency labeling:MIIT mandates under revised national standards are disqualifying conventional hydraulic presses from state-procurement eligibility. Domestic Jiangsu province fabricators are absorbing servo-electric upgrades to maintain contract access.
Market Restraints
- Specialized alloy billet supply concentration:Aerospace-grade aluminum billet production clusters in the US Gulf Coast and Russian smelter complexes. Geopolitical friction is extending lead times for 7xxx-series feedstock required by high-performance press lines.
- Sub-500 ton press commoditization:Standard polymer and food-grade extrusion equipment faces margin compression from Chinese OEM overcapacity. Differentiation requires vertical integration into downstream die fabrication or automation integration.
- EPA furnace emissions thresholds:Integrated heat-treatment lines at US-based aluminum extrusion plants face scrubber retrofit costs. Smaller operators are deferring press expansion rather than absorbing compliance capex.
Strategic Opportunities
- Southeast Asian industrial zone greenfield capacity:Vietnam's northern provinces and Indonesia's Batang industrial corridor offer tariff-advantaged positioning for export-oriented aluminum profile production. Greenfield press installations can bypass legacy energy infrastructure constraints.
- Twin-screw polymer compounding convergence:Precision mixing requirements in medical-grade tubing and EV battery separator films are opening premium pricing tiers. Technology licensors are bundling process control IP with press hardware.
- Indirect extrusion technology adoption:Specialty copper alloy and titanium producers are piloting reduced-friction architectures for aerospace fastener applications. Equipment suppliers with metallurgy partnerships can capture specification-driven procurement.
Industry Challenges
- Servo-hydraulic control systems integration:Legacy press fleets in European metalworking clusters require synchronized mechanical and electrical retrofitting. Skilled technician availability for closed-loop force control calibration is concentrated at German and Japanese OEM service centers.
- Cross-border die certification timelines:Automotive safety-critical extrusions require PPAP validation cycles spanning 18-24 months. Die design IP protection disputes between press operators and independent toolmakers are extending qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extrusion Press Market |
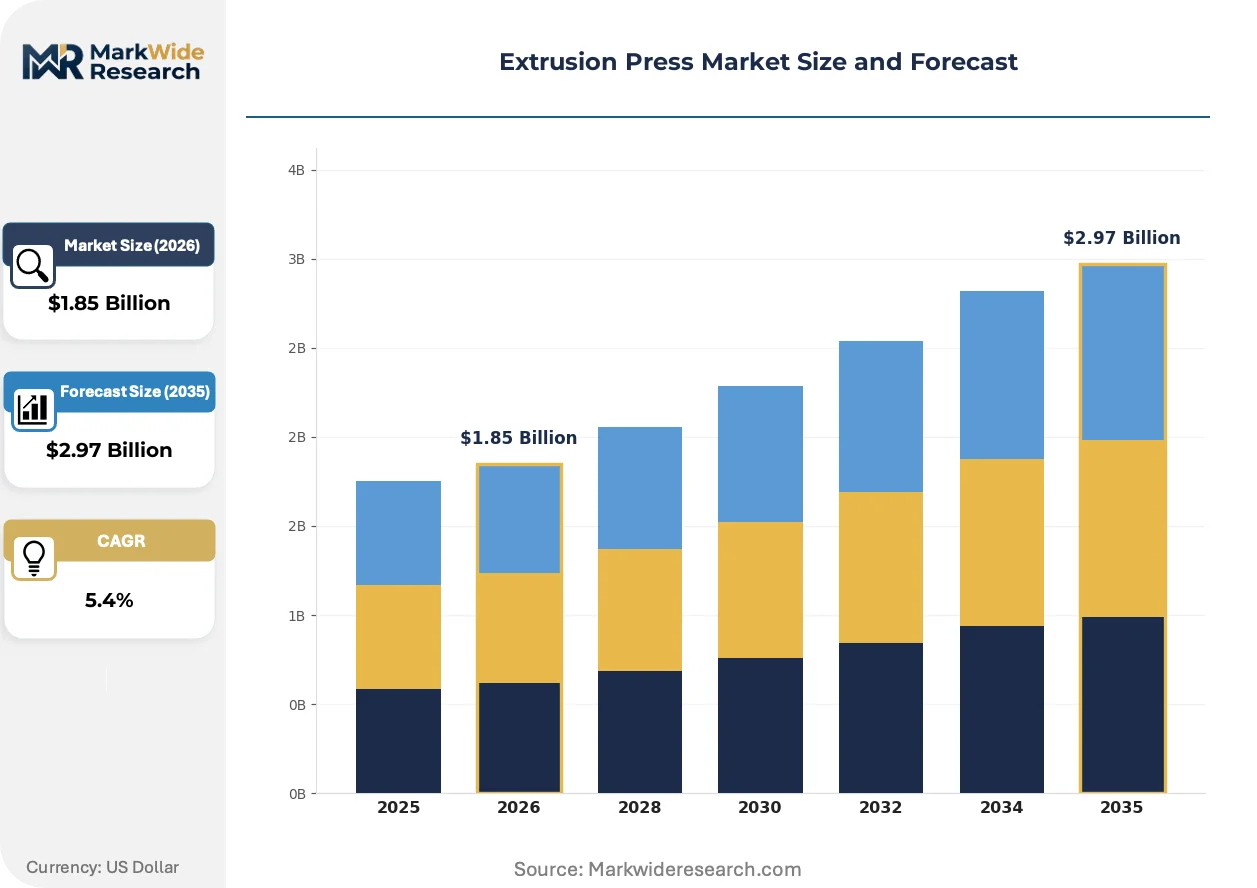
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Screw, Twin-Screw, Multi-Screw, Specialty Application: Plastic Extrusion, Metal Extrusion, Food Processing, Building Materials End User: Manufacturers, Construction Companies, Automotive Plants, Food Producers Technology: Direct Extrusion, Indirect Extrusion, Hot Extrusion, Cold Extrusion |
| Companies Covered | SMS group GmbH, Fives Group, Yizumi Precision Machinery Co., Ltd., FATA Aluminium Systems S.p.A., Sanyu Heavy Industries Co., Ltd., Danieli, UBE Machinery, Tianjin Tianduan Press Co., Ltd., Shibaura Machine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extrusion Press Market Shifts & Advancements
Real-time billet temperature monitoring and predictive ram force algorithms are compressing scrap rates and enabling closed-loop quality certification that downstream automotive OEMs now mandate in supply agreements.
Digital twin architectures for press simulation are integrating finite-element modeling of material flow with live sensor feedback from hydraulic manifold pressure transducers. Tier-1 aluminum extruders in Germany are deploying these systems for first-article qualification of complex hollow profiles. The technology is integrating die design iteration cycles from weeks into days, compressing new product introduction timelines for electric vehicle battery enclosure programs.
China's MIIT energy-efficiency labeling expansion under revised GB standards is disqualifying conventional fixed-displacement hydraulic pumps from state-procurement eligibility. Domestic press builders in Guangdong and Jiangsu provinces are accelerating servo-motor retrofit programs to maintain access to infrastructure stimulus contracts. High-cycle aluminum lines serving building systems are most affected, with compliance costs absorbed through equipment leasing structures rather than outright purchase.
Specification-driven procurement is consolidating buyer power among automotive OEMs and tier-1 aerospace contractors. Extrusion houses are unbundling after-sales service contracts from initial equipment sales, converting maintenance into recurring revenue streams. This behavioral shift is most visible in Japanese and German supply relationships, where predictive maintenance subscriptions now accompany multi-press installation contracts.
Extrusion Press Market Segmentation
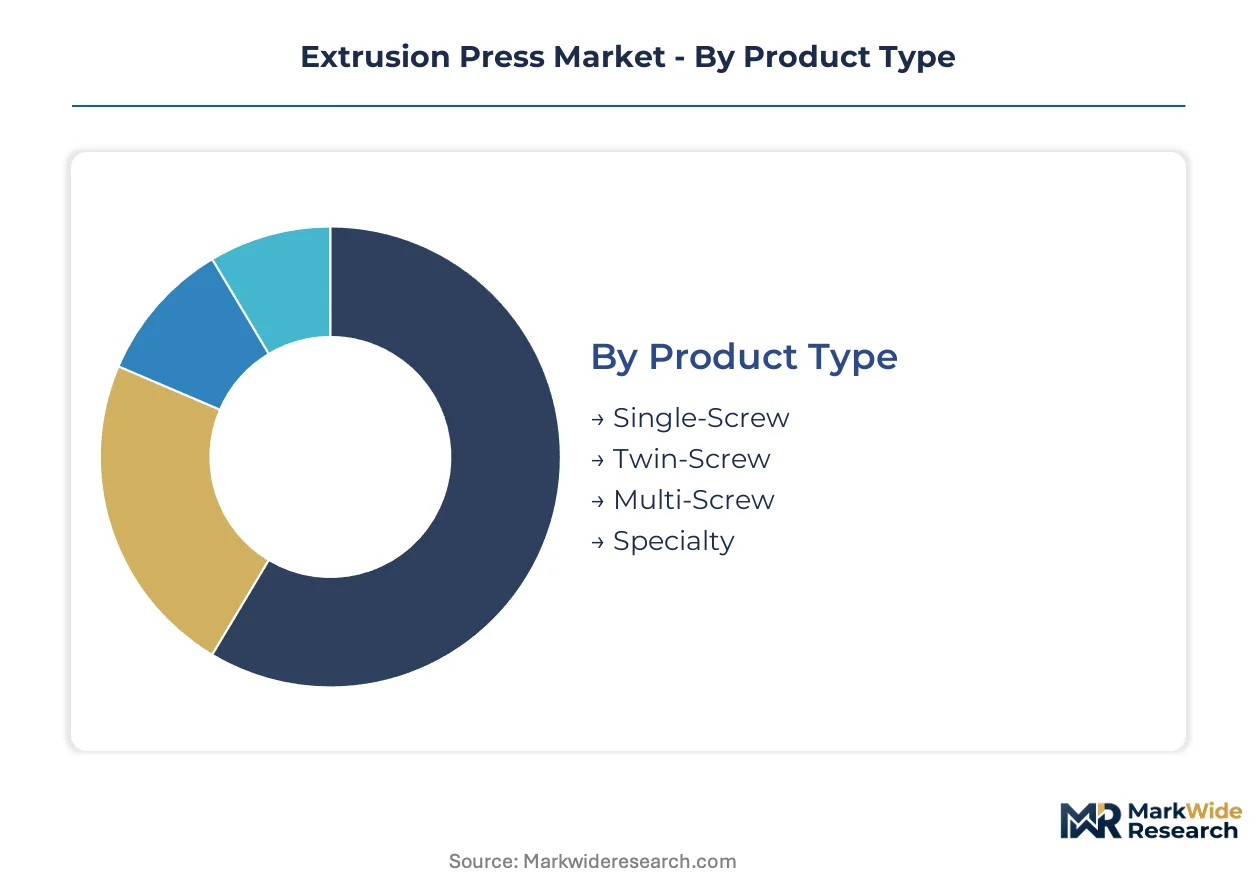
Segmentation in the extrusion press market reflects divergent capital intensity and performance requirements across material classes. Press configuration, thermal regime, and downstream integration depth determine equipment selection and supplier relationships.
Product Type:
Volume shipments concentrate in single-screw architectures, while twin-screw configurations command substantial premiums for precision compounding applications.
- Single-Screw:Dominant architecture for commodity polymer and aluminum profile production, utilizing one rotating screw within a heated barrel. Demand clusters in Jiangsu province building systems manufacturers seeking 1,000-3,000 ton units for standard window and door extrusions. China's MIIT energy-efficiency labeling is accelerating servo-motor retrofits in this segment to maintain state-procurement eligibility.
- Twin-Screw:Intermeshing co-rotating or counter-rotating screws deliver superior mixing and devolatilization for engineering polymers and medical compounds. Medical-grade tubing producers and EV battery separator film lines in Germany's Ruhr industrial cluster specify these systems despite 40-60% capital premiums over single-screw alternatives. REACH lubricant compliance is extending hardware refresh cycles as aqueous die systems replace legacy configurations.
- Multi-Screw:Three or more screws for high-throughput compounding of filled polymers and masterbatches.
- Specialty:Custom configurations including planetary roller extruders for heat-sensitive materials and rubber devulcanization.
Today's leader: Single-Screw. Tomorrow's challenger: Twin-Screw.
Application:
Metal extrusion absorbs the largest installed base by unit count, though food processing commands the most rapid replacement cycle due to hygienic design standard evolution.
- Plastic Extrusion:Thermoplastic profile, film, and pipe production across commodity and engineering resin grades. Automotive underhood ducting and interior trim programs at Japanese OEM plants in the Chubu region are specifying higher-tonnage units with integrated downstream calibration. ECHA restrictions on phthalate plasticizers are reshaping compound formulations and press screw metallurgy requirements.
- Metal Extrusion:Aluminum, copper, and titanium profile forming for structural, electrical, and aerospace applications. German automotive plants are commissioning 8,000+ ton presses for aluminum chassis components under lightweighting mandates. EPA emissions thresholds for integrated heat-treatment furnaces are compressing margins at smaller US-based operators.
- Food Processing:Pasta, cereal, and snack extrusion with sanitary design certifications. This application climbs the fastest as FDA Food Safety Modernization Act requirements and 3-A Sanitary Standards tighten equipment specifications.
- Building Materials:PVC window profiles, aluminum curtain wall systems, and structural framing extrusions.
Metal Extrusion anchors current revenue; Food Processing shows steepest expansion trajectory.
End User:
Automotive plants exercise the most concentrated procurement power through multi-press supply agreements with predictive maintenance bundling.
- Manufacturers:Tier-1 and tier-2 component suppliers across polymer compounding and metal fabrication. These buyers prioritize throughput consistency and die change automation to minimize batch-to-batch variation in just-in-sequence delivery contracts.
- Construction Companies:Vertically integrated building material producers and specialized extrusion job shops serving regional infrastructure projects.
- Automotive Plants:OEM in-house extrusion operations and dedicated tier-1 structural profile suppliers. German and Japanese facilities are pulling high-tonnage capacity into exclusive supply agreements with qualification cycles spanning 18-24 months for safety-critical applications.
- Food Producers:Branded consumer goods companies and contract manufacturers with stringent hygienic design requirements and allergen control protocols.
Automotive Plants set specification standards; Food Producers drive fastest equipment refresh rates.
Technology:
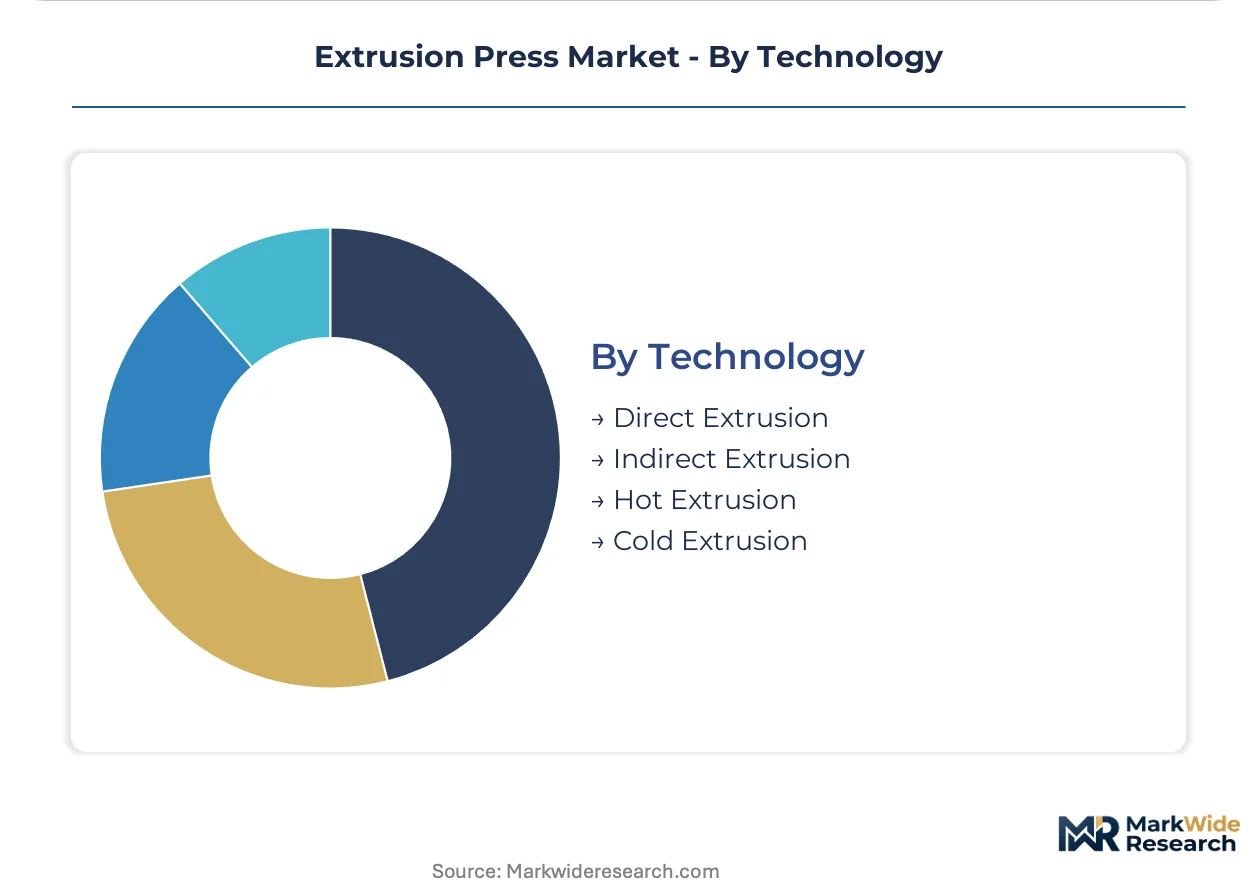
Direct extrusion dominates volume economics, while indirect architectures gain specification-driven adoption among specialty alloy producers.
- Direct Extrusion:Billet contained in stationary container with ram forcing material through die in forward direction. Standard configuration for 90%+ of aluminum building product and polymer profile output, offering simpler die design and lower capital cost per ton of installed capacity.
- Indirect Extrusion:Die mounted on hollow ram moves against stationary billet, reducing friction losses and enabling more uniform grain structure. Aerospace fastener and specialty copper alloy producers in Japan are piloting reduced-friction architectures for titanium and high-strength aluminum grades.
- Hot Extrusion:Billet heated above recrystallization temperature for aluminum, copper, and magnesium alloys requiring substantial deformation.
- Cold Extrusion:Room-temperature forming for steels, titanium, and precious metals with superior surface finish and dimensional precision. REACH lubricant restrictions are forcing aqueous system retrofits across EU cold extrusion lines.
Direct Extrusion holds volume dominance; Indirect Extrusion gains specification-driven share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting extrusion press capacity toward jurisdictions with lower compliance costs or faster permitting timelines. Southeast Asian industrial zones and select North American states are absorbing investment that might otherwise flow to legacy European or Chinese manufacturing clusters.
China
Jiangsu province fabricators dominate standard aluminum building profile output. MIIT energy-efficiency labeling under revised GB standards is disqualifying conventional hydraulic presses from state-procurement contracts. Guangdong facilities are accelerating servo-motor retrofits to maintain infrastructure stimulus eligibility.
Germany
Automotive OEM plants in Bavaria and Baden-Württemberg are commissioning 8,000+ ton presses for aluminum chassis lightweighting programs. REACH compliance deadlines from ECHA are forcing aqueous die lubrication retrofits across cold extrusion lines. The Ruhr industrial cluster anchors precision polymer compounding equipment demand.
United States
EPA emissions thresholds for integrated heat-treatment furnaces are compressing margins at Gulf Coast aluminum extruders. Smaller operators defer press expansion rather than absorb scrubber retrofit costs. Texas and Ohio-based tier-1 suppliers face extended lead times for aerospace-grade 7xxx-series billet feedstock.
Japan
Chubu region manufacturers around Nagoya are pulling high-tonnage capacity into exclusive automotive supply agreements. METI industrial efficiency guidelines are accelerating servo-hydraulic adoption among specialty alloy producers. Indirect extrusion pilots for titanium aerospace fasteners are concentrating in Aichi prefecture engineering clusters.
Vietnam
Northern provinces including Hai Phong and Bac Ninh are attracting greenfield press installations seeking tariff-advantaged export positioning. The country's national industrial development framework offers accelerated permitting for energy-efficient machinery imports. Japanese and Korean extruders are establishing dedicated supply lines for regional automotive assembly plants.
Extrusion Press Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automation integration and aftermarket service bundling as differentiation vectors. The vendor base stratifies across German-Japanese precision specialists, Chinese scale-oriented fabricators, and Italian engineering houses. Three archetypes dominate: metallurgy-integrated builders controlling billet quality from melt to finished press; automation-forward OEMs embedding predictive maintenance platforms; and regional champions capturing domestic infrastructure procurement. Competitive intensity centers on M&A activity for die fabrication capabilities and strategic partnerships with aluminum smelters for captive billet supply.
Among German-based engineering groups, SMS group GmbH exemplifies the metallurgy-integrated archetype through captive control over billet quality streams. Japanese machinery builders including UBE Machinery and Shibaura Machine occupy positions emphasizing precision control systems and long-horizon service relationships. Chinese fabricators Yizumi Precision Machinery Co., Ltd. and Tianjin Tianduan Press Co., Ltd. represent the scale-tier, competing through aggressive automation integration and domestic procurement channel access. Italian engineering house Danieli sits within the specialized-design segment, while French industrial group Fives Group anchors European project-engineering capabilities.
| Leading Market Players |
|---|
| SMS group GmbH |
| Fives Group |
| Yizumi Precision Machinery Co., Ltd. |
| FATA Aluminium Systems S.p.A. |
| Sanyu Heavy Industries Co., Ltd. |
| Danieli |
| UBE Machinery |
| Tianjin Tianduan Press Co., Ltd. |
| Shibaura Machine |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between servo-electric and conventional hydraulic architectures splits the extrusion press market into premium specification tiers and commodity replacement cycles, with MIIT energy-efficiency labeling in China and EPA emissions thresholds in the United States simultaneously reshaping procurement eligibility and supplier pricing power across both equipment categories.
Pricing Analysis
Distributor margins on standard single-screw presses compress as Chinese OEMs sell direct to Jiangsu province fabricators, while premium twin-screw configurations for medical-grade tubing command 40-60% capital premiums through bundled process control IP licensing. Price differentiation hinges on automation integration depth and REACH-compliant aqueous lubrication system certification, with cost compression in sub-500 ton polymer equipment intensifying due to Guangdong overcapacity. Tier-1 automotive extruders in Germany and Japan exhibit lowest price sensitivity through predictive maintenance subscription bundling, whereas Southeast Asian greenfield operators prioritize equipment leasing structures to bypass upfront capex.
Supply Chain Analysis
Freight cost differentials between European component foundries and East Asian assembly hubs favor integrated domestic production in China and Japan for high-tonnage press shipments. Supply concentrates in Germany for precision control systems, China for hydraulic manifold castings, and Japan for servo-motor drives, with aerospace-grade 7xxx-series aluminum billet feedstock drawing from US Gulf Coast and Russian smelter complexes. Single-source vulnerability in specialized alloy supply extends lead times for high-performance press lines. Distribution runs through OEM-direct channels for automotive tier-1 contracts and regional machinery distributors for building systems fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in Vietnam's northern provinces and Indonesia's Batang corridor, where accelerated permitting for energy-efficient machinery imports and tariff-advantaged export positioning offset China's tightening GB compliance costs and Europe's REACH lubricant retrofit requirements.
For Market Incumbents: Deepen captive metallurgy partnerships to secure 7xxx-series billet supply chains against geopolitical friction, and expand servo-hydraulic retrofit service capacity at German and Japanese OEM service centers to capture legacy fleet modernization demand. Threat from Chinese automation-forward OEMs intensifies margin pressure in standard tonnage segments.
For New Entrants and Emerging Players: Capture white-space in Southeast Asian greenfield installations by positioning energy-efficient press configurations that bypass legacy infrastructure constraints, with Vietnam's Hai Phong industrial zone offering the most penetrable entry point through Japanese and Korean extruder supply line relationships. Go-to-market leverage rests on equipment leasing structures rather than outright purchase.
For Investors and Strategic Acquirers: Consolidation pressure builds where die fabrication capabilities remain fragmented among independent toolmakers and cross-border PPAP validation timelines extend 18-24 months for automotive safety-critical extrusions. Long-term viability favors metallurgy-integrated builders with backward integration into billet quality control. Signal to monitor: ECHA enforcement actions on aqueous lubrication system compliance deadlines accelerating hardware refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Hydraulic Retrofit Program | MIIT GB labeling disqualifies conventional pumps from Chinese state contracts. |
| Die Fabrication Capability Acquisition | PPAP validation disputes between operators and toolmakers compress qualification timelines. |
| Southeast Asian Greenfield Capacity | Vietnam's accelerated permitting bypasses legacy European energy infrastructure constraints. |
| Predictive Maintenance Platform Launch | German and Japanese OEMs unbundle service contracts into recurring revenue streams. |
| Captive Billet Supply Partnership | SMS group GmbH controls quality from melt to finished press through metallurgy integration. |
Research Methodology
Coverage spans China, Germany, Japan, the United States, and Vietnam, with primary inputs from each market combining interviews with plant engineers at tier-1 automotive extruders, procurement teams at aluminum building systems manufacturers, aftermarket service heads at OEM facilities, and maintenance directors at polymer compounding operations. Secondary validation draws from MIIT GB standard filings, ECHA REACH compliance databases, EPA emissions enforcement records, SEC 10-K disclosures from listed machinery builders, and customs trade data on press component imports. Bottom-up equipment shipment tallies triangulate against top-down manufacturing capacity estimates across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across product type segmentation by screw architecture, application segmentation by material class, technology segmentation by extrusion method, and end-user segmentation by procurement concentration. CAGRs derive from installed base evolution modeling and replacement cycle acceleration factors, with forecast inputs incorporating automotive lightweighting program commitments and energy-efficiency regulatory phase-in schedules.
Geopolitical friction in aerospace-grade billet supply, ECHA enforcement timing variability, and MIIT labeling expansion scope are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Thermal Film Laminating Machines Market
Packaging Machinery
Corrugated Box Machines Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Side Load Case Packing Machines Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Global Form Fill Seal Machines Market