
 Caffeine Market | 2026-2036
Caffeine Market Size, Share, and Industry Trends Forecast 2026-2036
Caffeine Market Analysis
Synthetic caffeine production is tilting toward biotechnological fermentation methods that reduce petrochemical dependency and lower residual solvent profiles. CSPC Pharmaceutical Group Limited leverages vertical integration from pharmaceutical-grade synthesis to finished ingredient supply, sustaining cost advantages across Asian manufacturing hubs. BASF SE anchors European supply through its specialty chemicals division, while Kerry Group competes on formulation science that extends caffeine into novel delivery matrices for beverage clients.
Caffeine is a trimethylxanthine alkaloid with the molecular formula C₈H₁₀N₄O₂, typically synthesized via the methylation of theobromine or extracted from coffee and tea decaffeination streams, functioning primarily as a central nervous system stimulant in pharmaceutical, food, and cosmetic applications. Powder and beverage product types dominate volume, though energy shots command disproportionate margin pools due to dosage concentration and portability premiums. Ready-to-drink delivery mode growth outpaces instant formats as on-the-go consumption reshapes channel economics across health clubs and cafe segments.
The FDA governs caffeine labeling and GRAS status in food applications, while the EMA and national European regulators enforce pharmacopeial standards for pharmaceutical-grade material, creating a bifurcated compliance landscape that elevates testing costs for cross-border suppliers. China's NMPA and SAMR impose parallel purity and origin documentation requirements that filter smaller traders from direct export channels. Stakeholders must monitor evolving caffeine concentration caps in pre-workout supplements and energy drinks as regulators in multiple jurisdictions reassess acute exposure thresholds for adolescent and sensitive populations.
Market Dynamics
Biotechnological fermentation methods are collapsing synthetic caffeine's petrochemical dependency, redrawing cost structures and residual solvent compliance across pharmaceutical and beverage-grade supply tiers.
Growth Catalysts
- Functional beverage displacement:Energy drink manufacturers are pulling volume from traditional soft drink channels as ready-to-drink formats capture convenience retail shelf space in the United States.
- GRAS pathway expansion:The FDA's food additive framework enables novel delivery matrix approvals, accelerating caffeine integration into gummy and dissolvable strip formats.
- Decaffeination stream recovery:Coffee and tea processing waste streams in Brazil and Vietnam now supply natural caffeine extraction at scale, diversifying raw material origins.
Market Restraints
- Petrochemical feedstock volatility:Methylation reagent costs fluctuate with benzene derivative pricing, squeezing margins for synthetic producers reliant on theobromine pathways.
- Import notification friction:The FDA's New Dietary Ingredient pathway extends clearance timelines for Asian synthetic caffeine shipments, inventory planning extends to six-month horizons.
- Natural caffeine yield ceilings:Decaffeination extraction maxes at 0.3% recovery rates from green coffee, capping output expansion without parallel roasting volume growth.
Strategic Opportunities
- India functional beverage whitespace:FSSAI's 2023 caffeine concentration guidelines opened pre-workout and energy shot categories previously restricted to pharmaceutical channels.
- Biotech-fermentation convergence:Yeast-based theobromine methylation platforms eliminate residual solvent testing burdens entirely, qualifying for organic certification in EU markets.
- Health club direct distribution:Powder and shot formats bypass traditional retail markups through gym vending and subscription models, capturing margin pools previously lost to convenience store distributors.
Industry Challenges
- Pharmacopeial testing capacity:EMA and USP monograph compliance requires HPLC-UV and GC-MS validation protocols that strain smaller analytical service providers.
- Dual-use export licensing:Caffeine's precursor status under the WTO chemical weapons convention triggers end-use certification delays for Middle Eastern and North African buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caffeine Market |
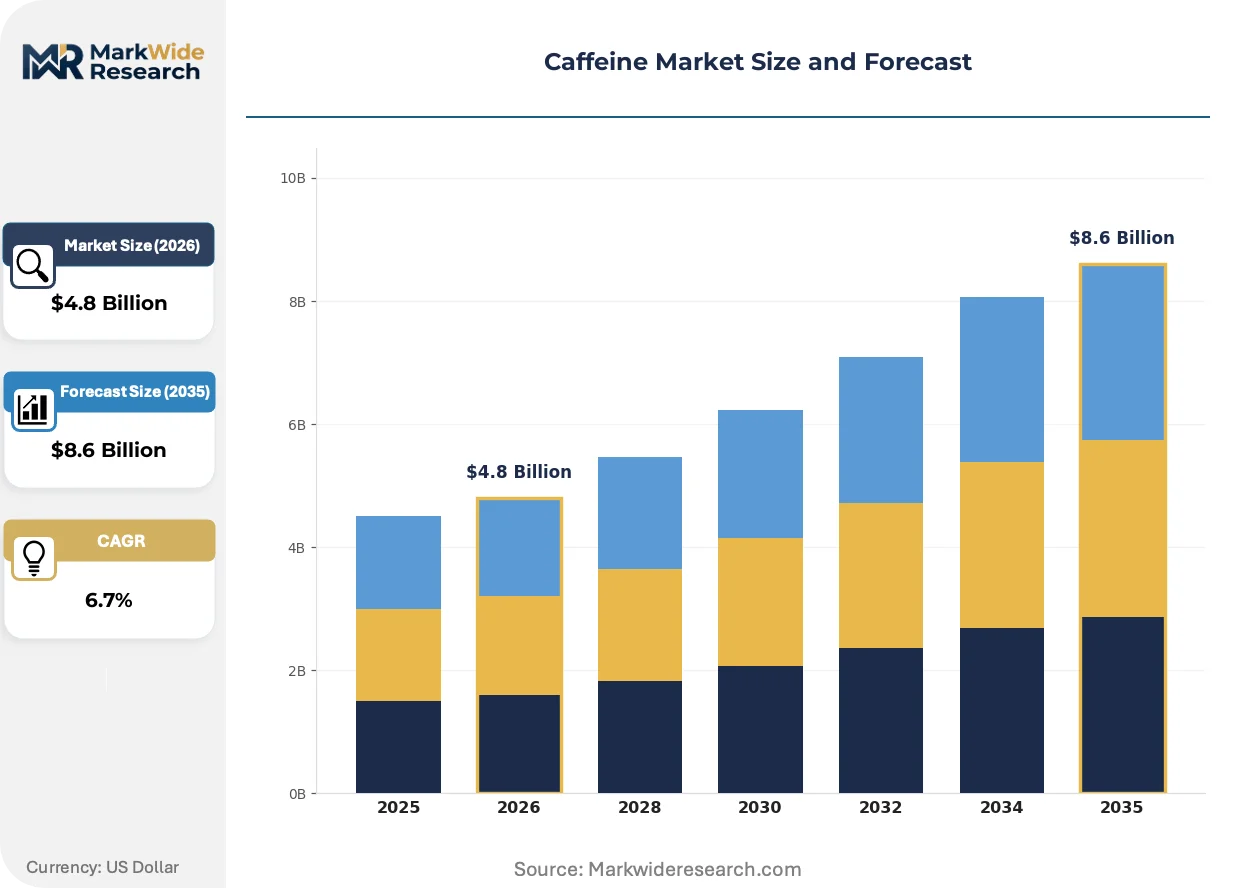
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Beverage, Capsule, Energy Shots Delivery Mode: Instant, Liquid, Granulated, Ready-to-Drink End User: Consumers, Restaurants, Cafes, Health Clubs Packaging Type: Bulk, Sachets, Bottles, Cans |
| Companies Covered | Kudos Chemie Limited, Aarti Pharmalabs Limited, BASF SE, Thermo Fisher Scientific Inc., Merck KGaA, CSPC Pharmaceutical Group Limited, Royal DSM, Kerry Group, Shandong Xinhua Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caffeine Market Emerging Trajectories
Fermentation-derived synthesis, regulatory concentration caps, and channel disintermediation are converging to fragment pricing power and compress legacy supply relationships across the value chain.
Cell-culture caffeine production is collapsing the distinction between natural and synthetic certification categories. Yeast-engineered theobromine methylation delivers USP-grade purity without petrochemical inputs. Beverage formulators in Germany and the Netherlands are qualifying these batches for organic label claims previously unattainable.
REACH's 2024 update to residual solvent thresholds is forcing reformulation investments across European pharmaceutical-grade suppliers. The ECHA classification now treats dichloromethane traces above 50 ppm as substances of very high concern. Contract manufacturers in Switzerland and Belgium are accelerating solvent substitution programs to maintain API export eligibility.
Direct-to-gym subscription models are compressing traditional distributor margins in the United States. Powder and energy shot brands now bypass convenience retail entirely, capturing recurring revenue through fitness app integrations. Los Angeles and Miami health club chains represent the highest-density adoption clusters for this channel shift.
Caffeine Market Segmentation
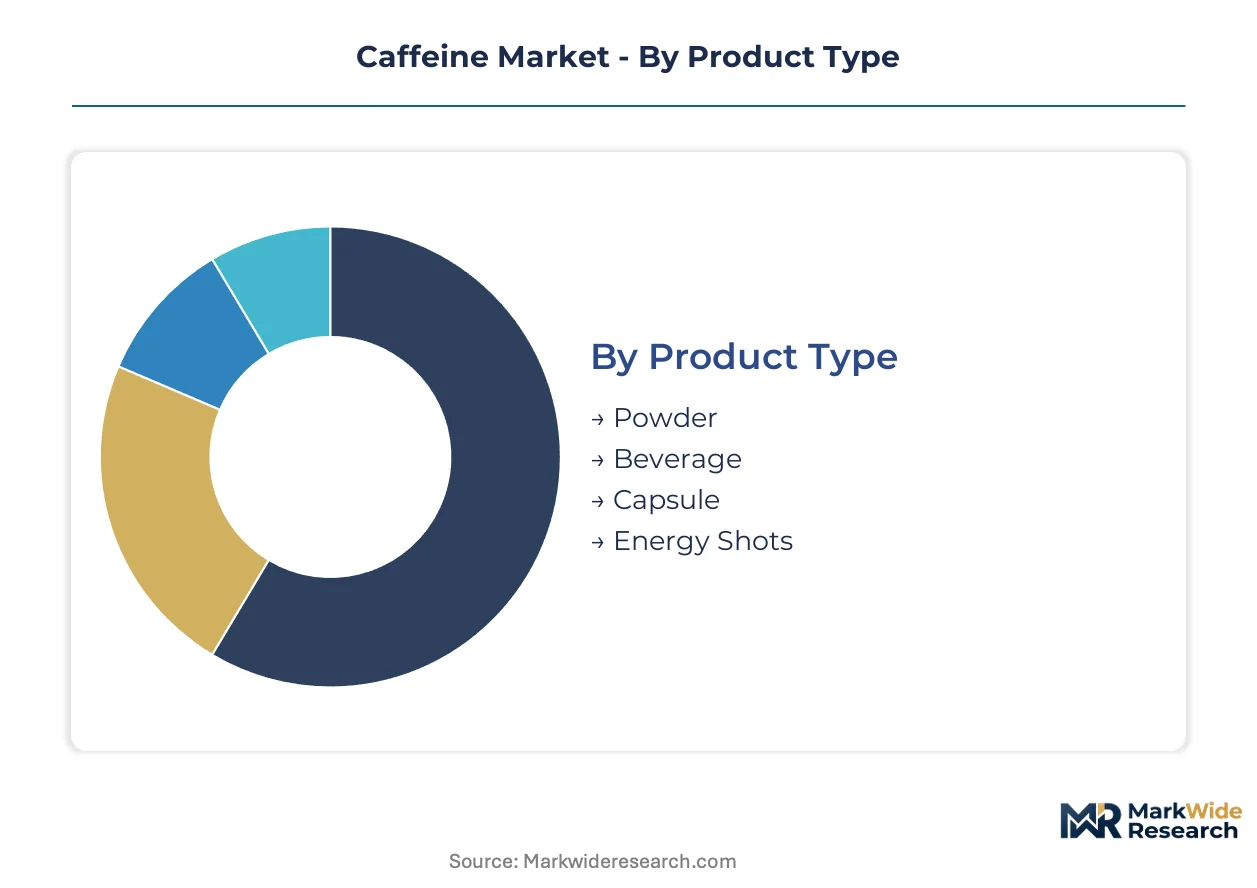
Caffeine product segmentation tracks divergent margin structures across pharmaceutical-grade synthesis and commodity beverage extraction. Delivery mode and packaging choices increasingly determine channel access and regulatory compliance burdens for suppliers.
Product Type:
Cost tier differentiation separates pharmaceutical-grade material from commodity beverage inputs, with purity specifications and residual solvent thresholds driving price spreads.
- Powder:Crystalline anhydrous or monohydrate forms with USP or food-grade certification. Demand concentrates in health clubs and supplement manufacturers where dosage precision commands premium pricing over beverage-grade alternatives.
- Beverage:Pre-formulated caffeine solutions and concentrates for ready-to-drink production. Bottlers in the United States absorb volume as energy drink brands displace traditional soft drink shelf space in convenience retail.
- Capsule:Encapsulated caffeine for nutraceutical and pharmaceutical applications. CDSCO and FDA cGMP compliance elevates testing costs for contract manufacturers serving nootropic and pre-workout supplement brands.
- Energy Shots:High-concentration liquid doses in portable formats. Portability premiums and dosage concentration sustain disproportionate margin pools relative to volume share in gym vending and direct-to-consumer channels.
Powder holds installed capacity. Energy shots are rotating up the share rankings.
Delivery Mode:
Application requirements dictate solubility, stability, and dosing precision across pharmaceutical compounding and mass-market beverage formulation.
- Instant:Spray-dried or freeze-dried soluble powders for hot beverage fortification. Coffee and tea blenders in Brazil and Vietnam leverage decaffeination waste streams for natural caffeine recovery at scale.
- Liquid:Aqueous or propylene glycol solutions for beverage manufacturing. Ready-to-drink brands in Germany and the Netherlands qualify fermentation-derived batches for organic label claims previously unattainable.
- Granulated:Agglomerated particles for controlled-release pharmaceutical tablets. EMA pharmacopeial standards enforce HPLC-UV validation protocols that strain smaller analytical service providers.
- Ready-to-Drink:Finished beverages with integrated caffeine dosing. On-the-go consumption patterns in Los Angeles and Miami health club chains compress traditional distributor margins through subscription and vending bypass.
Instant maintains legacy volume bases. Ready-to-drink is climbing the fastest as convenience retail shelf space reallocates.
End User:
Customer type segmentation reveals divergent procurement patterns between institutional foodservice and direct-to-consumer channels.
- Consumers:Individual purchasers through retail and e-commerce. Subscription models and fitness app integrations capture recurring revenue previously lost to convenience store markups.
- Restaurants:Foodservice operators incorporating caffeine into dessert and beverage menus. Menu engineering teams prioritize stable shelf-life formats that withstand kitchen storage variability.
- Cafes:Specialty coffee chains and independent operators. Decaffeination stream recovery supplies natural caffeine extraction for roasters seeking origin-story differentiation.
- Health Clubs:Gyms and fitness centers deploying vending and direct distribution. Powder and shot formats bypass retail markups entirely in Los Angeles and Miami adoption clusters.
Health clubs are gaining share fastest. Consumers retain absolute volume leadership.
Packaging Type:
Volume scale and handling requirements separate industrial procurement from single-serve convenience formats.
- Bulk:Drum and supersack configurations for pharmaceutical and beverage manufacturers. REACH residual solvent thresholds force reformulation investments across European pharmaceutical-grade suppliers.
- Sachets:Single-serve powder packets for on-the-go consumption. Portability premiums sustain margin capture in travel and workplace channels.
- Bottles:PET and glass containers for liquid concentrates and ready-to-drink products. FDA labeling requirements for caffeine content disclosure shape format selection.
- Cans:Aluminum packaging for carbonated and still energy beverages. Convenience retail channel economics favor shelf-stable formats with extended distribution reach.
Bulk commands industrial procurement volumes. Sachets are expanding most quickly in travel and workplace channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports synthetic caffeine to the United States, Germany, and India, with shipment values concentrated in pharmaceutical-grade and beverage-grade tiers. Trade flows reflect divergent regulatory clearance timelines and residual solvent testing requirements across destination markets.
United States
Energy drink manufacturers drive demand as ready-to-drink formats displace traditional soft drinks in convenience retail. The FDA's New Dietary Ingredient notification pathway extends clearance timelines for Asian synthetic caffeine shipments to six-month horizons. Los Angeles and Miami health club chains anchor direct-to-gym subscription models that bypass traditional distributor markups.
Germany
Beverage formulators qualify fermentation-derived caffeine batches for organic label claims previously unattainable through petrochemical synthesis. REACH's 2024 update to residual solvent thresholds forces reformulation investments across pharmaceutical-grade suppliers. Contract manufacturers in Switzerland and Belgium accelerate solvent substitution programs to maintain API export eligibility.
China
CSPC Pharmaceutical Group Limited leverages vertical integration from pharmaceutical-grade synthesis to finished ingredient supply. The NMPA and SAMR impose parallel purity and origin documentation requirements that filter smaller traders from direct export channels. Shandong Province hosts concentrated synthetic production capacity serving both domestic nutraceutical demand and international beverage clients.
India
FSSAI's 2023 caffeine concentration guidelines opened pre-workout and energy shot categories previously restricted to pharmaceutical channels. Aarti Pharmalabs Limited occupies a position within the API synthesis tier serving both domestic formulation houses and export markets. Maharashtra and Gujarat industrial corridors concentrate decaffeination stream processing for natural caffeine recovery.
Brazil
Coffee and tea processing waste streams supply natural caffeine extraction at scale, diversifying raw material origins beyond Asian synthetic sources. ANVISA enforces labeling thresholds for energy beverages that shape formulation decisions by multinational brands. São Paulo and Minas Gerais roasting clusters generate decaffeination byproduct volumes that feed regional extraction facilities.
Caffeine Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic archetypes: vertically integrated pharmaceutical conglomerates, specialty chemical divisions of diversified industrials, and fermentation-technology specialists. Tiered competitive positioning separates USP-grade synthesis from commodity beverage-grade extraction. Dominant competitive moves include backward integration into raw material supply and technology licensing partnerships that transfer biotechnological production platforms across geographic markets.
Within the pharmaceutical-grade synthesis tier, CSPC Pharmaceutical Group Limited and Aarti Pharmalabs Limited exemplify vertically integrated API producers with captive supply from chemical intermediates through finished caffeine. BASF SE anchors the specialty chemicals division archetype, occupying a position that bridges European regulatory compliance with global beverage client relationships. Kudos Chemie Limited represents the India-based synthesis specialist archetype, sitting within the export-oriented supply tier that serves formulation houses across Middle Eastern and Southeast Asian markets.
| Leading Market Players |
|---|
| Kudos Chemie Limited |
| Aarti Pharmalabs Limited |
| BASF SE |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| CSPC Pharmaceutical Group Limited |
| Royal DSM |
| Kerry Group |
| Shandong Xinhua Pharmaceutical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Shandong Province's concentrated synthetic caffeine capacity in China anchors downstream pricing power for pharmaceutical-grade and beverage-grade tiers, with methylation reagent cost fluctuations from benzene derivative markets transmitting directly into Asian export quotations.
Pricing Analysis
Fermentation-derived caffeine production commands a 15-20% premium over petrochemical-synthetic material in EU organic certification pathways, while traditional theobromine methylation retains cost leadership in commodity beverage-grade supply. Three-tier pricing structure across USP-certified pharmaceutical, food-grade standard, and technical-economy beverage inputs separates quality-grade premiums from volume-scale discounts. Pricing pressure stems from REACH residual solvent compliance investments forcing European contract manufacturers into solvent substitution programs. Energy shot brands exhibit lowest price sensitivity due to portability premiums, while instant powder blenders in Brazil and Vietnam face acute margin compression from decaffeination yield ceilings.
Supply Chain Analysis
Petrochemical feedstock supply from benzene derivative markets and agricultural coffee bean inputs from Brazil and Vietnam constitute the dual upstream anchors for synthetic and natural caffeine production respectively. Manufacturing concentrates in China, India, and Germany, with Shandong Province and Maharashtra industrial corridors hosting API synthesis clusters while Swiss and Belgian contract manufacturers handle pharmaceutical-grade finishing. Single-source vulnerability runs through Chinese synthetic caffeine export channels where FDA New Dietary Ingredient notifications extend clearance timelines. Distribution runs through beverage manufacturer direct procurement for ready-to-drink formats, pharmaceutical CDMOs for encapsulated products, and health club vending bypass for energy shots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by functional beverage displacement of traditional soft drinks, with energy drink manufacturers pulling volume through convenience retail reallocation.
For Market Incumbents: Build regulatory certification moats by securing USP-grade validation and EMA pharmacopeial compliance ahead of REACH residual solvent threshold tightening. CSPC Pharmaceutical Group Limited and BASF SE should accelerate backward integration into fermentation-derived theobromine platforms to eliminate petrochemical dependency and capture organic label premiums in German and Dutch beverage markets. Defensive capacity positioning in India leverages FSSAI guideline openings for pre-workout and energy shot categories previously restricted to pharmaceutical channels. For New Entrants and Emerging Players: India's functional beverage whitespace offers the most penetrable geographic entry point, with Maharashtra and Gujarat industrial corridors providing decaffeination stream access for natural caffeine recovery at scale. Brazil's São Paulo and Minas Gerais roasting clusters present alternative upstream positioning for waste-stream extraction without competing against established Chinese synthetic capacity. Go-to-market execution should target health club direct distribution in Los Angeles and Miami adoption clusters, bypassing convenience retail markups through fitness app-integrated subscription models. For Investors and Strategic Acquirers: Long-term, this sits as a formulation-science consolidation play because caffeine's commodity differentiation is collapsing toward delivery matrix innovation and regulatory compliance capabilities rather than synthesis cost alone. Acquisition targets should prioritize fermentation-technology specialists with yeast-engineered theobromine methylation platforms and existing EU organic certification pathways. The signal to watch is FDA concentration cap revisions for pre-workout supplements and energy drinks, which would trigger reformulation demand spikes and channel reallocation toward compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech-Fermentation Scale-Up | Eliminates residual solvent testing burdens entirely, qualifying for EU organic certification previously unattainable through petrochemical routes. |
| Health Club Direct Distribution | Bypasses convenience retail markups in Los Angeles and Miami adoption clusters through vending and subscription integration. |
| Regulatory Certification Investment | Secures USP-grade and EMA pharmacopeial compliance ahead of REACH dichloromethane threshold enforcement. |
| Backward Integration into Feedstock | Captures benzene derivative cost exposure and secures methylation reagent supply continuity for synthetic production tiers. |
| Decaffeination Stream Recovery Partnerships | Locks in natural caffeine extraction rights from Brazil and Vietnam coffee processing waste at 0.3% yield recovery rates. |
Methodological Framework
Cross-validation between primary interviews with caffeine synthesis plant managers, beverage formulation R&D directors, pharmaceutical procurement leads, and health club chain operators anchors the qualitative findings against secondary validation from FDA GRAS notifications, EMA pharmacopeial submissions, customs trade data, and FSSAI regulatory filings. Bottom-up triangulation across product type, delivery mode, and end-user segmentation dimensions reconciles with top-down market sizing from caffeine import/export value flows and energy drink production volume disclosures.
Calibration against historical caffeine price spreads between synthetic and natural extraction tiers, petrochemical feedstock cost indices, and regulatory compliance investment cycles informs the analytical framework across the projection horizon. Segmentation modeling incorporates grade tier (pharmaceutical vs food vs technical), end-use industry (beverage vs pharmaceutical vs nutraceutical), packaging format (bulk vs sachet vs bottle vs can), and regional production hub (China vs India vs Germany vs Brazil). CAGRs derive from elasticity-adjusted volume projections tied to functional beverage displacement rates and health club channel penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed pharmaceutical conglomerates or breakthrough yeast-engineered production scale-ups would shift outcomes beyond modeled ranges. Cross-checking against ECHA substance of very high concern designations and FDA New Dietary Ingredient clearance velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Roast to Order Coffee Market
Coffee
Coffee Cherry Market
Coffee
Portable Espresso Machines Market
Coffee
Global Automatic Coffee Machines Market
Coffee
North America Specialty Coffee Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Reusable Coffee Cup Market
Coffee
Espresso Powder Market
Coffee
Oceania Coffee Market
Coffee
US Instant Coffee Market
Coffee
Global Portable Coffee Makers Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Chewable Coffee Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
Coffee Concentrate Market
Coffee
Single Origin Coffee Market