
 Ethiopia Coffee Market | 2026-2036
Ethiopia Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Ethiopia Coffee Market Analysis
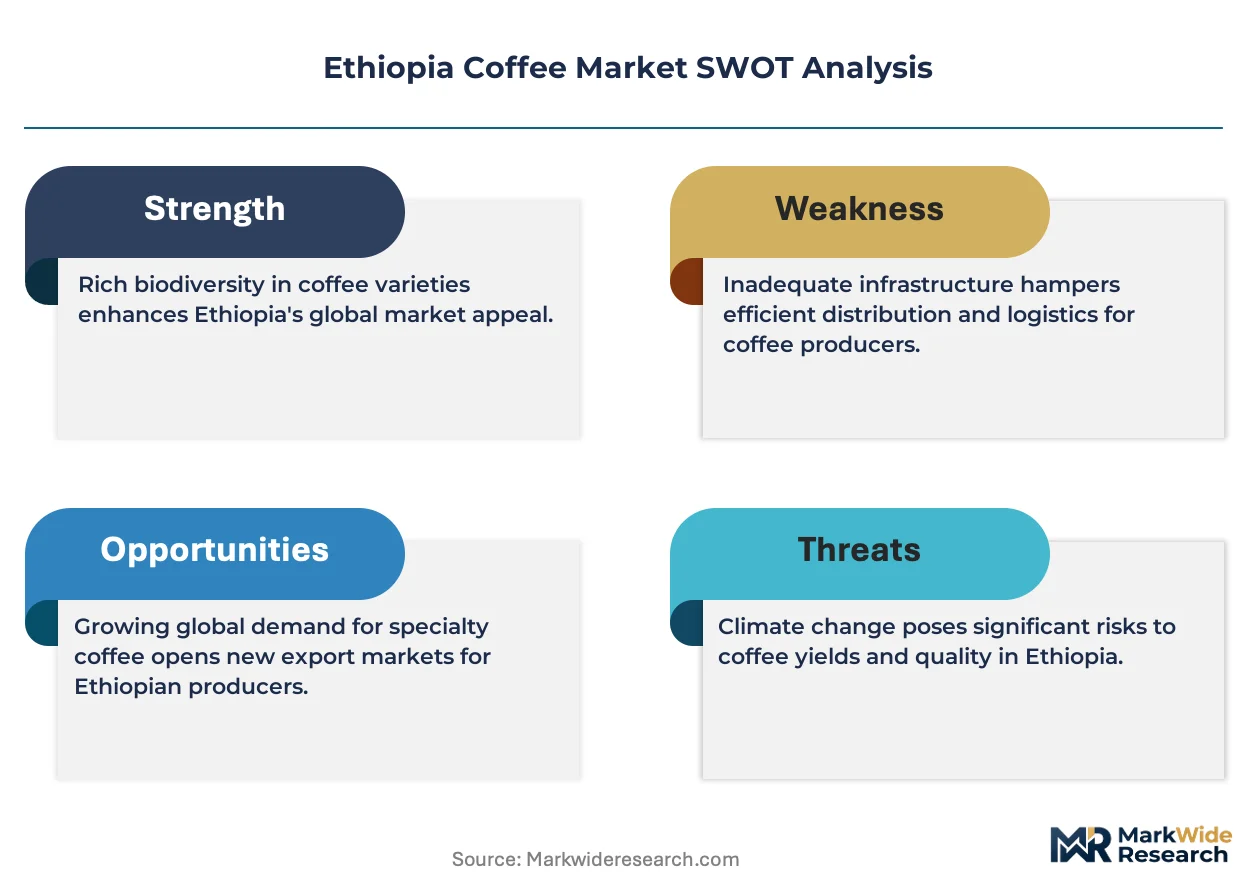
Capital-intensity divergence between integrated washing station operators and smallholder aggregators is rotating competitive dynamics across Ethiopia's coffee value chain. Kerchanshe Trading leverages direct farm partnerships to sustain volume throughput for European export contracts. Yirgacheffe Coffee Farmers Cooperative Union anchors premium positioning through certified heirloom varietal segregation. Moyee Coffee Ethiopia differentiates via in-country roasting and branded retail channels.
Ethiopia coffee comprises Coffea arabica L. specimens grown at elevations between 1,500 and 2,200 meters above sea level, processed through washed or natural drying methods to produce green bean lots graded by defect count and cup score for international trade. Specialty-grade washed Arabica commands the strongest margin pools due to traceability premiums and direct trade relationships with Nordic and Japanese buyers. Natural-processed lots across Yirgacheffe and Sidama zones attract growing demand from North American specialty roasters seeking fruit-forward cup profiles. Instant and commercial-grade segments occupy price-sensitive channels serving domestic households and institutional foodservice accounts.
The Ethiopian Coffee and Tea Authority enforces minimum quality thresholds and export licensing that determine market access for washing stations and cooperative unions. BIS-equivalent national standards and emerging EU Deforestation Regulation compliance requirements shape traceability investments across supplier networks. Stakeholders must monitor evolving specialty buyer certification demands and domestic consumption tax structures to align processing infrastructure with dual-market revenue streams.
Market Dynamics
The Ethiopian Coffee and Tea Authority's revised export licensing framework is concentrating washing station throughput toward certified specialty channels while marginalizing non-compliant aggregators from premium buyer networks.
Growth Catalysts
- EU Deforestation Regulation:Traceability mandates from Brussels are accelerating GPS polygon mapping investments across Sidama and Yirgacheffe highlands, unlocking compliant supply contracts with Nordic importers.
- Third-wave café proliferation:Addis Ababa's urban café density is expanding domestic consumption of single-origin Arabica, creating parallel revenue streams beyond export dependence.
- Heirloom varietal segregation:Cooperative unions are deploying genetic fingerprinting protocols to certify indigenous landrace provenance, commanding traceability premiums from Japanese specialty roasters.
Market Restraints
- Input cost volatility:Fertilizer import dependencies and birr depreciation are compressing smallholder margins below sustainable thresholds in Oromia highlands.
- Supply concentration risk:European specialty buyers dominate export offtake, creating demand-side vulnerability to recession-driven contract cancellations.
- Technical limitation:Inconsistent electricity access across SNNPR washing stations limits controlled fermentation protocols required for consistent 85+ cup scores.
Strategic Opportunities
- Underpenetrated Gulf markets:Dubai and Riyadh specialty café sectors remain underserved by direct Ethiopian export relationships, offering premium positioning whitespace.
- Regulatory tailwind:Ethiopia's Coffee Quality-Trading Standards create tiered grading infrastructure that domestic roasters can leverage for branded retail channel expansion.
- Technology convergence:Blockchain traceability platforms merged with mobile money settlement systems are enabling disintermediated farmer-to-roaster transactions.
Industry Challenges
- Cupping skill scarcity:Qualified Q-grader density remains insufficient to support quality verification demands across expanding washing station networks.
- Capex intensity:Solar-powered drying infrastructure requires upfront investment beyond cooperative union borrowing capacity without development finance intermediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethiopia Coffee Market |
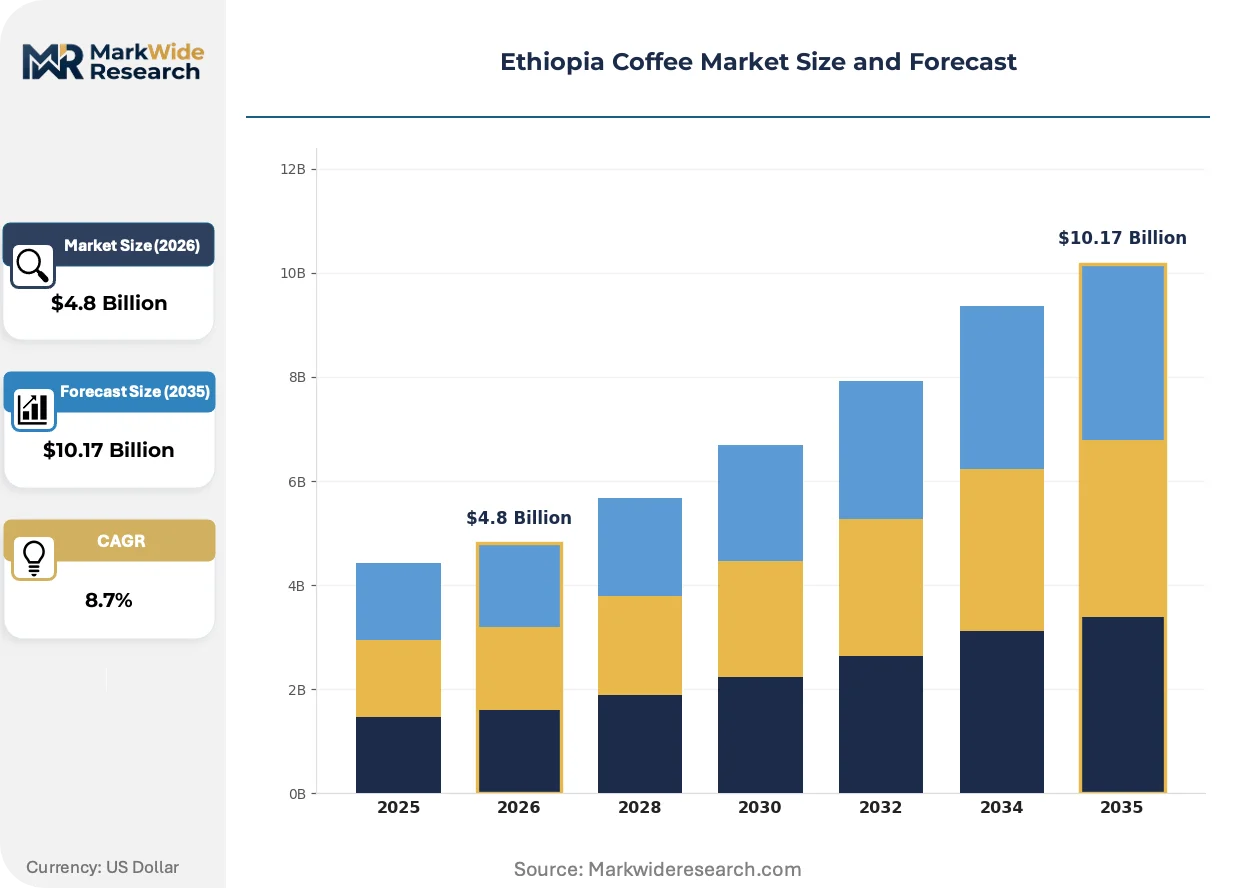
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabica, Robusta, Specialty, Instant Processing Method: Washed, Natural, Honey, Pulped Natural Distribution Channel: Retail, Online, Wholesale, Export Customer Type: Households, Cafés, Restaurants, Hotels |
| Companies Covered | Moyee Coffee Ethiopia, Oromia Coffee Farmers Cooperative Union, Nestlé SA, Tomoca Coffee, Kerchanshe Trading, Hadero Coffee, Belco Coffee, Yirgacheffe Coffee Farmers Cooperative Union, Ya Coffee, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethiopia Coffee Market Emerging Trajectories
Processing technology and regulatory compliance architectures are restructuring competitive advantage across Ethiopia's coffee value chain, separating traceable specialty supply from commodity-grade volume.
Near-infrared spectrometry deployed at washing station intake is bifurcating cherry quality assessment, separating moisture-calibrated lots for specialty channels from standard-grade volume. European export houses are requiring spectroscopic certification as a contract precondition. This instrumentation is compressing price pooling across non-compliant aggregators while concentrating margin capture among capitalized station operators.
Ethiopia's Coffee Quality-Trading Standards enforcement by the Ethiopian Coffee and Tea Authority is mandating defect-count thresholds and origin documentation for export licensing. Washing stations are retrofitting traceability systems to comply with batch-lot segregation requirements. Specialty-grade washed Arabica segments are absorbing compliance costs through direct trade premiums, while natural-processed commodity lots face margin compression from documentation overhead.
Roaster procurement patterns are pivoting from spot-market purchasing toward multi-year forward contracts with named washing stations. North American specialty buyers are displacing traditional European auction intermediaries through direct origin relationships. This channel restructuring is most visible across Yirgacheffe and Guji zones where traceability premiums now exceed traditional export parity by substantial margins.
Ethiopia Coffee Market Segmentation
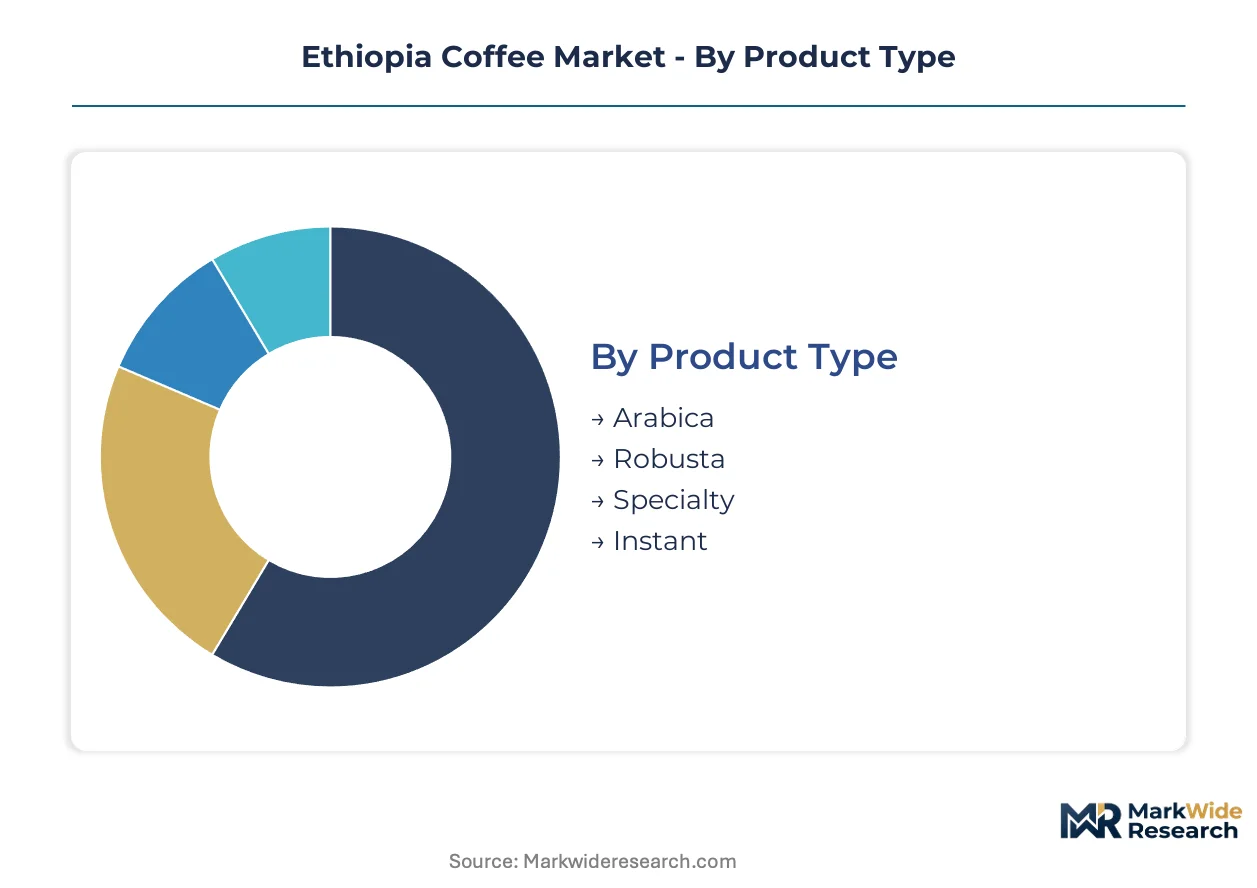
Ethiopia's coffee market segmentation reveals distinct demand architectures across domestic consumption corridors and export-grade supply channels. Understanding these segment boundaries enables stakeholders to align processing investments with revenue pool concentration.
Product Type:
Domestic consumption gravitates toward soluble and commercial-grade segments, while export value concentrates in traceable Arabica lots certified by the Ethiopian Coffee and Tea Authority.
- Arabica:Indigenous heirloom varietals grown at 1,500-2,200 meters elevation constitute the genetic backbone of Ethiopia's export reputation. Addis Ababa's third-wave cafés and Nordic specialty roasters drive demand for single-origin lots with documented provenance.
- Specialty:Segregated lots scoring 80+ on SCA protocols command traceability premiums through direct trade relationships. Yirgacheffe and Sidama zones supply the majority of certified specialty volume to Japanese and North American buyers.
- Robusta:Limited cultivation in lowland margins serves regional blending markets.
- Instant:Soluble coffee production targets price-sensitive domestic households and institutional foodservice accounts in Oromia urban centers.
Arabica commands the established base. The steepest expansion runs through Specialty.
Processing Method:
Cost tier differentiation separates capital-intensive washed protocols from lower-investment natural drying, with margin capture diverging sharply across these technical approaches.
- Washed:Controlled fermentation at centralized washing stations produces consistent cup profiles required for 85+ scoring. European export houses mandate washed processing for premium contract eligibility.
- Natural:Sun-dried whole cherry processing yields fruit-forward flavor matrices prized by North American specialty roasters seeking distinct cup differentiation.
- Honey:Partial mucilage retention creates mid-tier positioning between washed clarity and natural intensity.
- Pulped Natural:Mechanical demucilagination followed by patio drying offers throughput efficiency for volume-oriented stations.
Washed processing anchors the revenue base. The steepest expansion trajectory belongs to Natural.
Distribution Channel:
Customer type concentration shapes channel selection, with household and hospitality segments demanding divergent fulfillment architectures.
- Export:Licensed washing stations and cooperative unions ship green bean lots through Djibouti port to European, Japanese, and North American specialty buyers under Ethiopian Coffee and Tea Authority oversight.
- Wholesale:Roasted coffee distribution serves Addis Ababa's café cluster and regional hospitality procurement in SNNPR state capitals.
- Retail:Branded packaged coffee moves through domestic supermarket chains and airport duty-free concessions.
- Online:Direct-to-consumer platforms remain nascent, constrained by logistics infrastructure outside major urban corridors.
Export channels dominate value capture. Wholesale is climbing fastest as domestic café density expands.
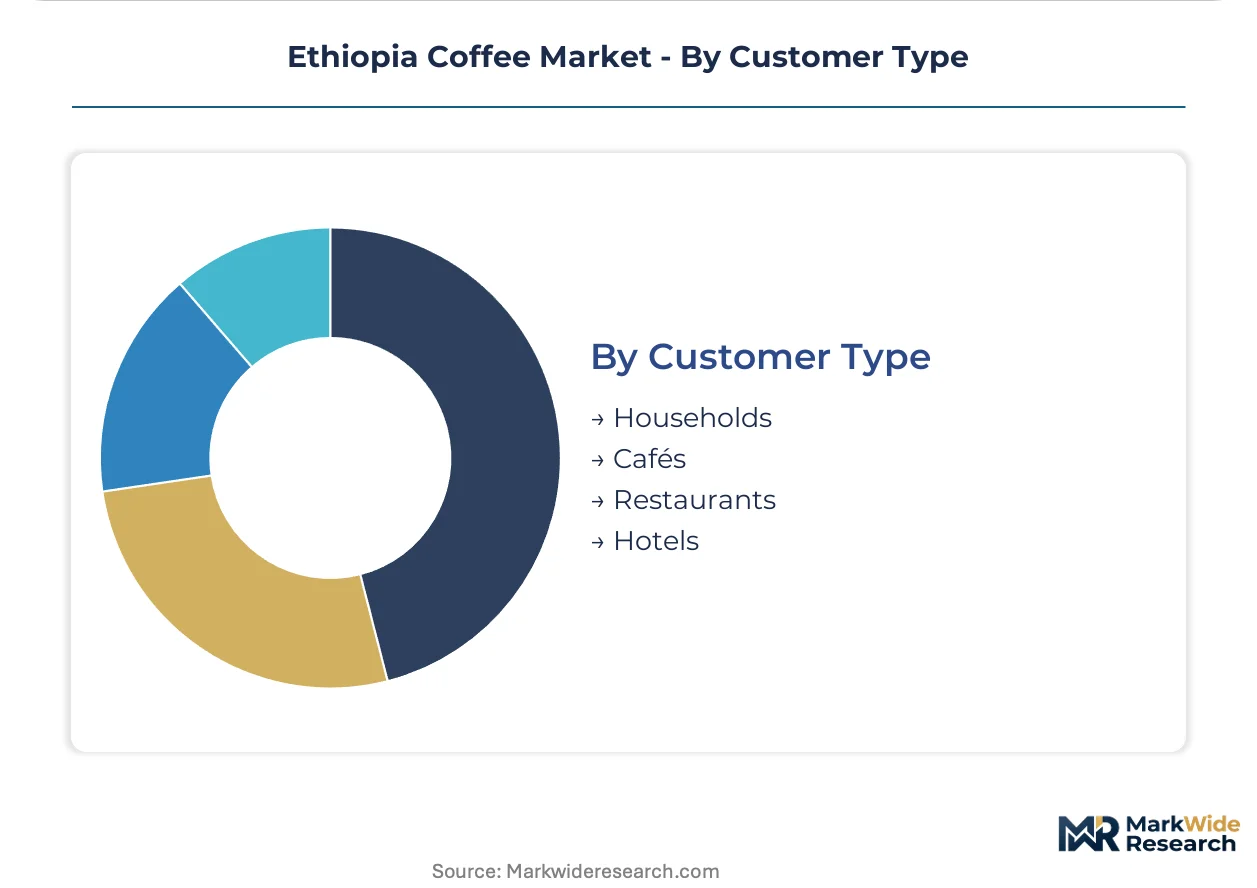
Customer Type:
Application context determines quality thresholds and price sensitivity, with institutional buyers operating on contracted volume schedules distinct from discretionary household purchasing.
- Cafés:Addis Ababa's third-wave coffee culture demands single-origin Arabica with transparent sourcing narratives, creating a premium channel parallel to export markets.
- Hotels:International hospitality chains in the capital require consistent supply of certified specialty grades for in-house roasting programs.
- Households:Urban consumers in Oromia and SNNPR regional states purchase commercial-grade roasted coffee through traditional market channels.
- Restaurants:Foodservice accounts prioritize volume pricing over provenance documentation, sourcing through wholesale aggregators.
Cafés represent the fastest-growing customer segment. Hotels anchor the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export volume concentrates in highland zones while domestic consumption clusters around urban corridors. Regional differentiation follows elevation gradients and processing infrastructure density.
Oromia
Smallholder density drives raw cherry supply to washing stations across Jimma and Limu zones. The Ethiopian Coffee and Tea Authority licenses export operations through regional cooperative unions. Jimma city anchors processing infrastructure for European specialty contracts.
Sidama
Washed Arabica from Yirgacheffe sub-zone commands premium cup scores for Japanese buyers. Traceability mandates under EU Deforestation Regulation accelerate GPS polygon mapping across Bensa and Aleta Wondo districts. Hawassa hosts the largest concentration of certified washing stations.
SNNPR
Guji zone natural-processed lots attract North American roasters seeking fruit-forward profiles. Inconsistent electricity access constrains controlled fermentation protocols in remote washing stations. Dilla and Yirga Chefe serve as collection points for export consolidation.
Addis Ababa
Third-wave café proliferation creates domestic demand for single-origin Arabica with transparent sourcing narratives. Roasting capacity expansion targets airport duty-free and branded retail channels. The capital's consumption growth reduces historical export dependence.
Ethiopia Coffee Market Vendor Landscape
Concentration sits with cooperative unions and integrated trading houses that control washing station throughput and export licensing. The structure separates capitalized operators capable of traceability investments from smallholder aggregators facing margin compression. Strategic archetypes include direct-trade specialists, volume exporters, and domestic retail brands. Competitive moves center on backward integration into farm partnerships and geographic diversification toward Gulf markets.
Among integrated trading houses, Kerchanshe Trading exemplifies volume-oriented export specialization through direct farm partnerships. Cooperative union structures find representation in Yirgacheffe Coffee Farmers Cooperative Union, which anchors premium positioning through certified heirloom varietal segregation. Domestic retail differentiation is occupied by Moyee Coffee Ethiopia, which exemplifies in-country roasting and branded channel development.
| Leading Market Players |
|---|
| Moyee Coffee Ethiopia |
| Oromia Coffee Farmers Cooperative Union |
| Nestlé SA |
| Tomoca Coffee |
| Kerchanshe Trading |
| Hadero Coffee |
| Belco Coffee |
| Yirgacheffe Coffee Farmers Cooperative Union |
| Ya Coffee |
| Others |
Supply Flow & Price Mechanics
The Ethiopian Coffee and Tea Authority's export licensing framework gates both supply qualification and price differentiation simultaneously. Certified washing stations command traceability premiums from Nordic and Japanese buyers while non-compliant aggregators face margin compression from documentation overhead.
Pricing Analysis
Specialty roasters anchor Ethiopia's pricing structure through direct trade relationships with named washing stations. Three-tier pricing stratifies across certified specialty, commercial-grade washed, and commodity natural lots based on defect counts and cup scores. Pricing pressure intensifies in commercial segments due to birr depreciation and fertilizer import cost volatility. Domestic household buyers exhibit highest price sensitivity, while Japanese specialty importers absorb premiums for documented heirloom provenance.
Supply Chain Analysis
Just-in-time cherry delivery dominates upstream collection, while strategic stockpiling of dried parchment secures export contract fulfillment during harvest peaks. Supply concentrates in Ethiopia's Sidama, Yirgacheffe, and Guji highlands, with secondary sourcing from Jimma and Limu zones. Processing draws from imported fermentation equipment, fuel for generators, and jute export bags. Single-source vulnerability runs through Djibouti port congestion. Distribution runs through cooperative unions to European auction houses and direct roaster relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethiopia's coffee market rewards regulatory entrenchment as a defensive moat. The Ethiopian Coffee and Tea Authority's licensing concentration creates switching costs that protect incumbent positions.
For Market Incumbents: Consolidate washing station throughput through backward integration into farm partnerships in Yirgacheffe and Sidama zones. Deepen traceability investments to preempt EU Deforestation Regulation compliance gaps that threaten contract eligibility with European export houses. For New Entrants and Emerging Players: Anchor in underpenetrated Gulf markets where Dubai and Riyadh specialty café sectors lack direct Ethiopian supply relationships. Target domestic roasting capacity in Addis Ababa's expanding third-wave corridor as a parallel revenue stream beyond export dependence. For Investors and Strategic Acquirers: Carve-out targets emerge from cooperative unions seeking development finance intermediation for solar-powered drying infrastructure. Long-term viability hinges on traceability technology convergence with mobile money settlement systems. Watch for blockchain platform adoption crossing threshold density as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Partnerships | Kerchanshe Trading exemplifies volume security through direct smallholder contracts. |
| Traceability Technology Deployment | Near-infrared spectrometry at washing station intake bifurcates specialty from commodity channels. |
| Domestic Roasting Capacity Expansion | Moyee Coffee Ethiopia demonstrates branded retail channel development beyond export parity. |
| EU Deforestation Regulation Compliance | GPS polygon mapping investments unlock certified supply contracts with Nordic importers. |
| Gulf Market Direct Export Relationships | Dubai and Riyadh specialty café sectors remain underserved by Ethiopian origin connections. |
Methodological Framework
The analysis maps specialty-grade Arabica, commercial washed lots, natural-processed segments, and instant coffee channels, each validated through washing station operators, cooperative union managers, export house procurement leads, and Addis Ababa café roasters. Primary fieldwork combined with secondary validation from Ethiopian Coffee and Tea Authority filings, customs export records, and SCA cupping competition databases. Bottom-up cherry volume estimates triangulate against top-down export value aggregation.
Consistency checks validated volume and value outputs against Ethiopian Coffee and Tea Authority production statistics and port throughput data. The analytical framework segments by processing method, quality grade tier, distribution channel, and regional origin cluster across the projection horizon. CAGRs derive from trend extrapolation of certified specialty adoption rates and domestic café density expansion. Forecast inputs incorporate washing station electrification timelines and EU regulatory compliance cost absorption.
Material uncertainties — birr volatility, fertilizer import disruption, and European recession-driven contract cancellation — sit outside the modeled envelope. Forecasts reflect assumptions regarding traceability technology diffusion and cooperative union consolidation trajectories. Revision becomes warranted when EU Deforestation Regulation enforcement stringency crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Asia-Pacific Coffee Franchise Market
Coffee
Coffee Extracts Market
Coffee
US Instant Coffee Market
Coffee
Germany Coffee Market
Coffee
Single Origin Coffee Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Ready to Drink (RTD) Coffee Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Out-Of-Home Coffee Market
Coffee
United States Coffee Pods and Capsules Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Global Automatic Coffee Machines Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
High Protein Coffee Market
Coffee
GCC Instant Coffee Market
Coffee
Stove Top Moka Coffee Pot Market