
 Asia-Pacific Ready to Drink (RTD) Coffee Market | 2026-2036
Asia-Pacific Ready to Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ready to Drink (RTD) Coffee Market Outlook
ISO 22000 certification is redrawing competitive boundaries across the Asia-Pacific RTD coffee landscape, forcing smaller bottlers toward third-party audits or co-manufacturing partnerships. Nestle S.A. leverages its Nescafé production network to dominate ambient distribution in tropical climates. UCC Holdings Co., Ltd. anchors its position through backward integration into coffee bean sourcing across Indonesian highland estates. Suntory Holdings Limited differentiates via proprietary aseptic filling lines that extend shelf life without preservatives.
Ready to Drink (RTD) Coffee comprises brewed coffee extracts preserved through thermal processing, aseptic packaging, or cold filtration, typically formulated at 1.0-2.5% TDS (total dissolved solids) for immediate consumption without preparation equipment. The category serves commuters, office workers, and foodservice channels requiring portable caffeine delivery with consistent flavor profiles. Cold brew segments command margin premiums due to extended steeping cycles and lower acidity positioning, while flavored variants attract younger demographics through seasonal limited editions. Cans dominate packaging type share for vending machine compatibility across Japanese and South Korean transit corridors.
Japan's Ministry of Health, Labour and Welfare (MHLW) food additive standards, South Korea's MFDS labeling requirements for caffeine content, and Australia's FSANZ beverage classification rules collectively shape formulation thresholds and import compliance costs. China's SAMR is tightening scrutiny of "sugar-free" claims, forcing reformulation investments among entrants targeting health-conscious consumers. Stakeholders must monitor evolving refrigerant regulations under Japan's F-Gas framework and Australia's phasedown schedule, as cold-chain infrastructure constraints will determine which brands achieve national distribution versus metro-only presence.
Market Dynamics
Japan's F-Gas Regulation is forcing cold-chain infrastructure reconfiguration across refrigerated distribution networks, compressing margins for ambient-stable format producers while advantaging aseptic filling investments. This regulatory pressure cascades through formulation chemistry, packaging material selection, and route-to-market economics.
Growth Catalysts
- Cold brew steeping protocols:Extended extraction cycles at ambient temperatures reduce acidity profiles that appeal to South Korean working professionals seeking smoother caffeine delivery without dairy additives.
- MFDS caffeine disclosure mandates:South Korea's labeling requirements for milligram content per serving have standardized transparency, reducing consumer hesitation and accelerating trial rates among health-conscious demographics.
- Convenience store shelf expansion:Southeast Asian retail chains are dedicating incremental chilled space to single-serve formats, creating physical availability that converts impulse purchases into habitual consumption.
Market Restraints
- Arabica price volatility:Indonesian highland estate supply concentration exposes margin structures to commodity futures swings that co-manufacturers cannot hedge without balance sheet depth.
- Aseptic line capex thresholds:Proprietary filling technology requires capital commitments that fragment competitive tiers, freezing out regional bottlers lacking access to contract manufacturing networks.
- SAMR sugar-free claim scrutiny:China's tightening enforcement of sweetener disclosure standards has triggered reformulation costs that delay product registration timelines for entrants targeting reduced-calorie positioning.
Strategic Opportunities
- Vietnamese urban corridor penetration:Ho Chi Minh City and Hanoi convenience networks remain underdeveloped for premium chilled formats, offering first-mover shelf positioning before infrastructure saturation.
- Plant-based milk convergence:Oat and almond protein stabilization technologies enable clean-label formulation that captures lactose-intolerant segments without sacrificing mouthfeel consistency.
- Australia FSANZ beverage reclassification:Pending rules on caffeinated drink thresholds may create regulatory arbitrage for sub-80mg formulations that qualify for favorable retail placement.
Industry Challenges
- ISO 22000 audit bandwidth:Third-party certification queues extend 14-18 months across accredited bodies, delaying market entry for bottlers lacking existing quality management infrastructure.
- Refrigerant transition technician scarcity:Japan's F-Gas phasedown has outpaced HVAC technician training pipelines, creating service bottlenecks for cold-chain fleet operators.
- Legacy PET line retrofit complexity:Existing blow-molding assets require mechanical modification to handle nitrogen dosing for shelf-life extension, stranding capital for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ready to Drink (RTD) Coffee Market |
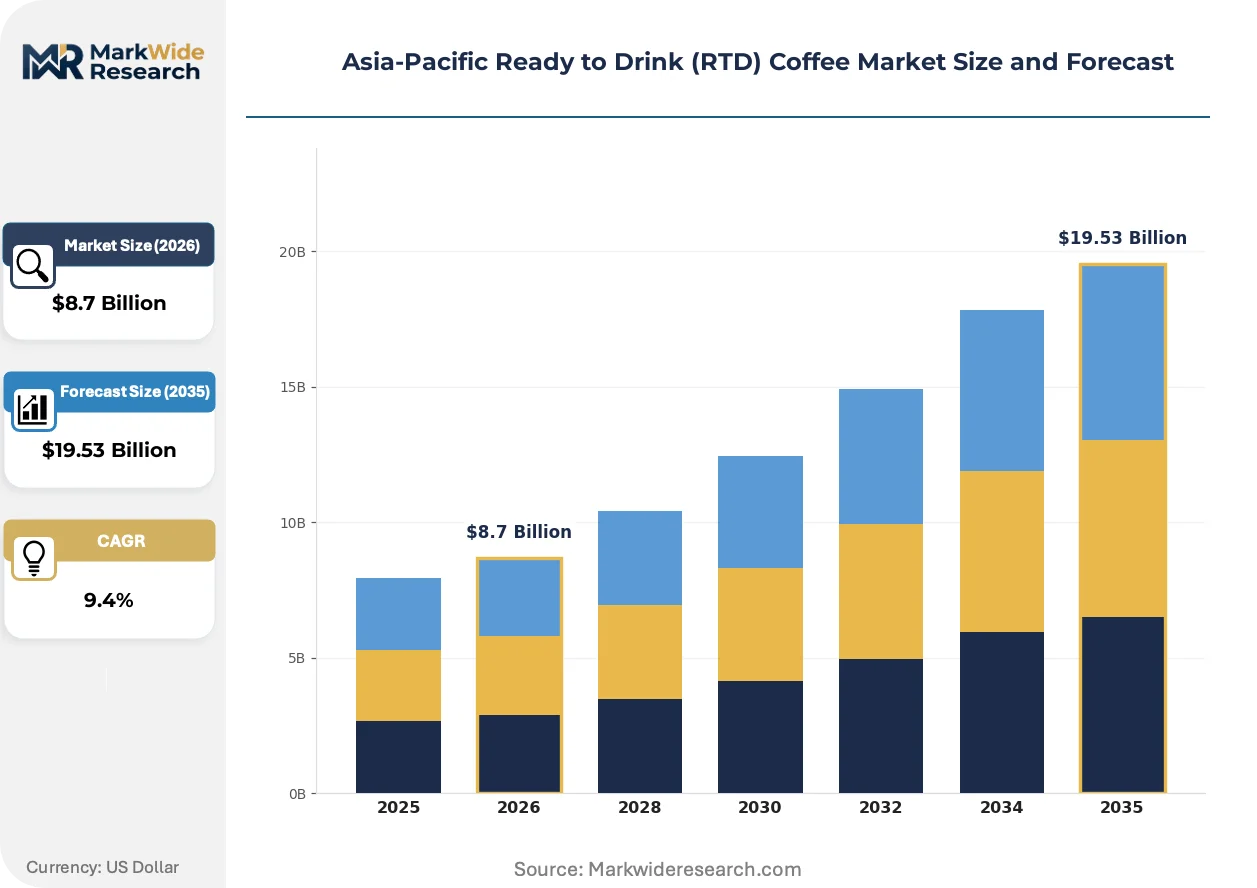
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbonated, Non-Carbonated, Cold Brew, Flavored Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Coffee Shops Packaging Type: Cans, Bottles, Tetra Packs, Pouches Customer Type: Millennials, Working Professionals, Health-Conscious Consumers, Students |
| Companies Covered | The Coca-Cola Company, Keurig Dr Pepper, Inc., Kirin Holdings Company, Limited, Starbucks Corporation, Lotte Chilsung Beverage Co., Ltd., Nestle S.A., UCC Holdings Co., Ltd., Tata Consumer Products, Suntory Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ready to Drink (RTD) Coffee Market Strategic Shifts
Formulation chemistry and thermal processing methods are diverging along stability-versus-freshness axes, with equipment investments locking producers into irreversible technical trajectories. This bifurcation reshapes competitive boundaries more dramatically than brand equity or price positioning.
Aseptic cold-filling technology is bifurcating the competitive landscape between preservative-free premium positioning and ambient-stable mass-market economics. Japanese transit corridor vending operators are prioritizing 180-day shelf-life SKUs that reduce replenishment frequency. The structural consequence compresses regional bottlers without co-manufacturing partnerships into commodity pricing tiers.
Japan's F-Gas Regulation mandates refrigerant phasedown schedules that cascade through refrigerated logistics infrastructure. Cold-chain fleet operators face retrofit deadlines that accelerate consolidation toward vertically integrated distributors with capital reserves. Southeast Asian import-dependent markets bear disproportionate compliance cost burdens relative to domestic production bases.
Working professionals in South Korean metropolitan centers are compressing consumption occasions from sit-down café visits to grab-and-go chilled formats. Convenience store chains are responding with dedicated cold vault sections that displace traditional ambient coffee aisles. This channel rotation is most visible in Seoul's Gangnam and Jongno districts where office density exceeds 15,000 workers per square kilometer.
Asia-Pacific Ready to Drink (RTD) Coffee Market Segmentation
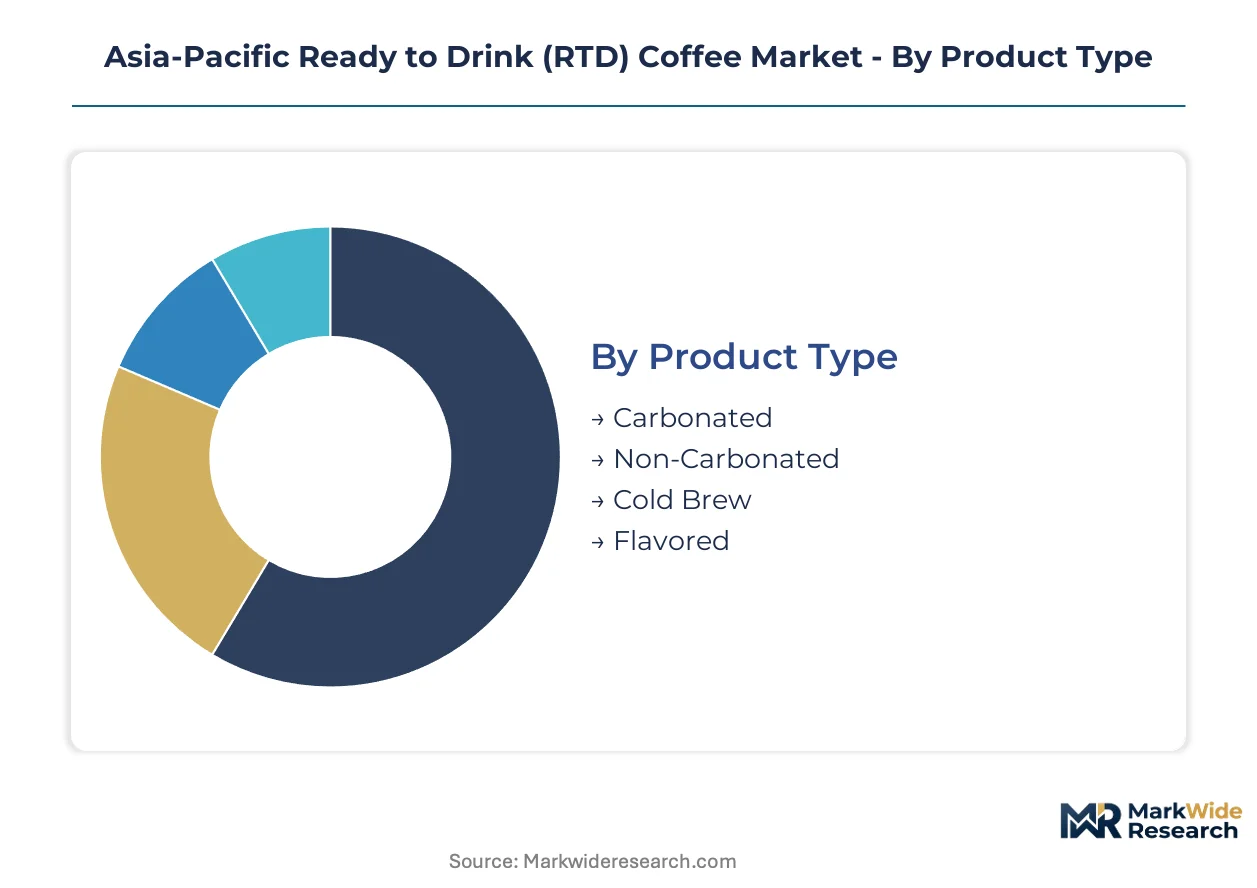
Segmentation in the Asia-Pacific RTD coffee market reveals how consumption occasions, channel access, and demographic targeting create divergent margin structures. Each dimension exposes different vulnerability to substitute beverages and competing caffeine formats.
Product Type:
Substitution pressure from energy drinks and functional teas weighs heaviest on carbonated variants, while cold brew segments defend position through proprietary extraction protocols.
- Carbonated:Nitrogen-infused or CO2-charged formulations replicate soda mouthfeel with caffeine delivery. Demand concentrates in Japanese vending corridors where younger consumers seek alternatives to cola brands, though MFDS caffeine disclosure rules have compressed impulse trial rates in South Korean convenience networks.
- Non-Carbonated:Still formulations at 1.0-2.5% TDS dominate ambient-stable production economics. Working professionals across Seoul's Gangnam district drive habitual purchase patterns for shelf-stable variants that eliminate refrigeration dependency.
- Cold Brew:Extended steeping cycles at ambient temperatures yield lower acidity profiles that command retail premiums.
- Flavored:Seasonal limited editions targeting younger demographics through vanilla, caramel, and regional fruit infusions.
Non-Carbonated anchors the volume base while Cold Brew gains share at the steepest rate.
Distribution Channel:
Channel economics diverge sharply between high-frequency replenishment formats and destination purchase occasions, with cold-chain requirements filtering viable entrants.
- Supermarkets:Multi-pack SKUs and promotional stacking drive household stock-up behavior. Australian chains dedicate end-cap positioning to aseptic-filled formats that satisfy FSANZ beverage classification thresholds.
- Convenience Stores:Single-serve chilled formats dominate impulse capture in Southeast Asian urban corridors. Ho Chi Minh City and Hanoi networks are expanding cold vault capacity ahead of infrastructure saturation.
- Online Retail:Subscription models and bulk discounting attract price-sensitive segments across China's tier-two cities.
- Specialty Coffee Shops:Curated local brand discovery channels with premium positioning.
Convenience Stores capture the highest transaction frequency while Online Retail climbs fastest as SAMR registration timelines delay physical retail entry.
Packaging Type:
Material selection locks producers into irreversible capital commitments, with aseptic line investments fragmenting competitive tiers.
- Cans:Aluminum formats compatible with Japanese and South Korean vending machine standards. Transit corridor operators prioritize 180-day shelf-life nitrogen-dosed variants that reduce replenishment cycles.
- Bottles:PET and rPET formats enable resealability for multi-occasion consumption. Health-Conscious Consumers in Australia's metropolitan centers favor transparent bottles that signal clean-label formulation.
- Tetra Packs:Aseptic carton technology for ambient distribution in tropical climates.
- Pouches:Flexible formats for portion-controlled sampling and travel channels.
Cans anchor volume throughput while Bottles expand most quickly as sustainability credentials reshape procurement priorities.
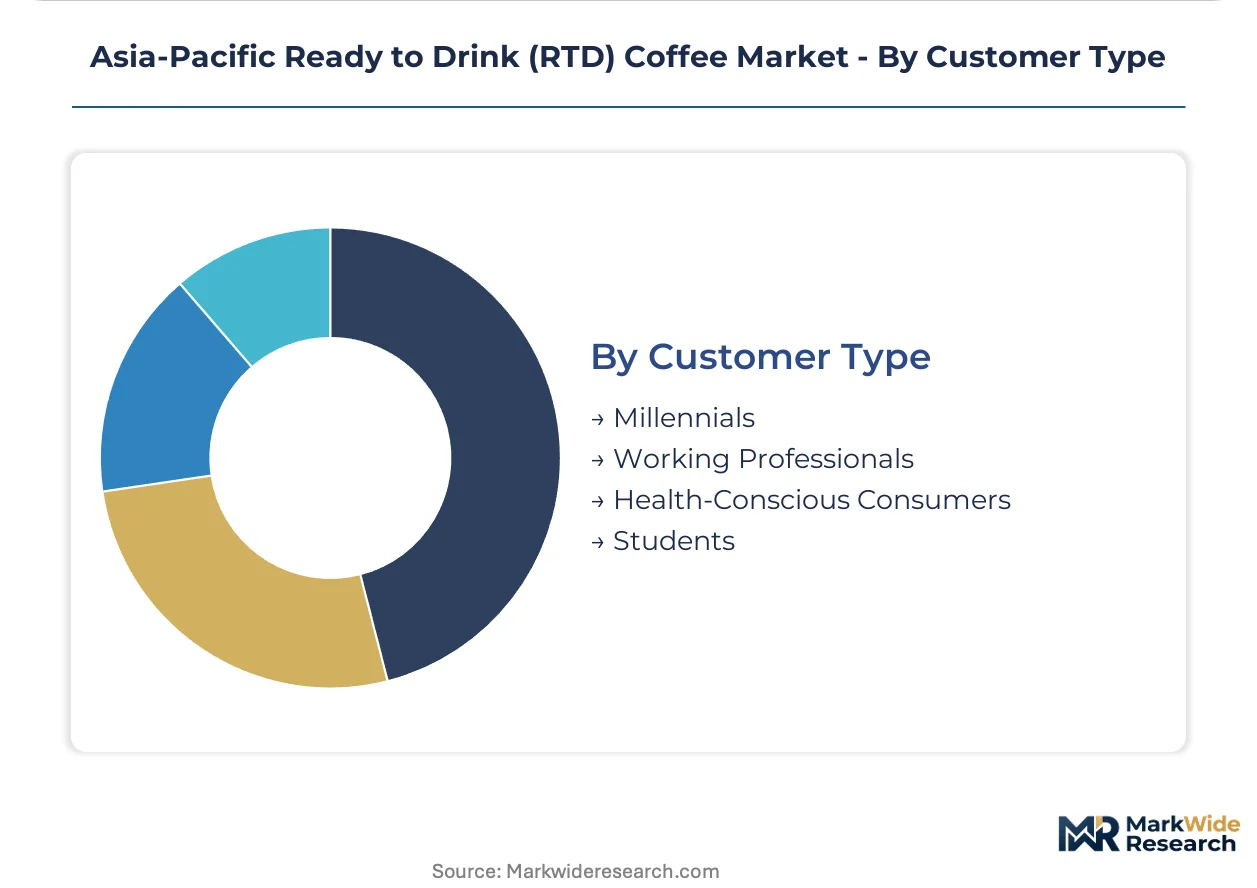
Customer Type:
Demographic targeting determines formulation complexity, with health-positioned segments demanding certification transparency that extends supply lead times.
- Millennials:Flavor experimentation and Instagram-compatible packaging drive trial behavior. Seoul's Jongno district convenience chains rotate seasonal SKUs to sustain engagement.
- Working Professionals:Caffeine efficiency and portability dominate purchase criteria. South Korean office density above 15,000 workers per square kilometer compresses consumption occasions from café visits to grab-and-go formats.
- Health-Conscious Consumers:Sugar-free and plant-based milk variants with ISO 22000 certification requirements.
- Students:Price-sensitive volume seekers in examination-intensive periods.
Working Professionals provide the revenue base while Health-Conscious Consumers show the steepest expansion trajectory as SAMR sugar-free claim scrutiny forces reformulation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's F-Gas Regulation is accelerating cold-chain infrastructure consolidation across the region, compressing margins for refrigerated distribution while advantaging producers with aseptic filling capabilities. South Korea's MFDS caffeine disclosure mandates and China's SAMR sugar-free claim scrutiny are reshaping formulation thresholds and import compliance costs.
Japan
Working professionals in Tokyo's Kanto corridor drive habitual consumption of shelf-stable formats that eliminate refrigeration dependency. METI's refrigerant phasedown schedules under the F-Gas framework are forcing fleet operators toward consolidated distributors with capital reserves for retrofit compliance. Osaka's Kansai industrial zone hosts proprietary aseptic filling investments that extend shelf life without preservatives.
South Korea
Office density exceeding 15,000 workers per square kilometer in Seoul's Gangnam and Jongno districts compresses consumption occasions from café visits to grab-and-go chilled formats. MFDS labeling requirements for milligram caffeine content per serving have standardized transparency, reducing consumer hesitation among health-conscious demographics. Convenience store chains are responding with dedicated cold vault sections that displace traditional ambient coffee aisles.
China
SAMR's tightening scrutiny of "sugar-free" claims is triggering reformulation investments that delay product registration timelines for entrants targeting reduced-calorie positioning. The regulator's enforcement of sweetener disclosure standards has forced portfolio adjustments among brands seeking health-conscious urban consumers. Shanghai and Beijing metro networks remain focal points for premium chilled format trials ahead of national distribution scaling.
Australia
FSANZ beverage classification rules are shaping formulation thresholds for caffeinated drink retail placement, with pending rules on sub-80mg formulations creating potential regulatory arbitrage opportunities. Health-conscious consumers in Sydney and Melbourne metropolitan centers favor transparent bottle formats that signal clean-label positioning. Supermarket chains dedicate end-cap positioning to aseptic-filled formats that satisfy classification thresholds.
Vietnam
Ho Chi Minh City and Hanoi convenience networks remain underdeveloped for premium chilled formats, offering first-mover shelf positioning before infrastructure saturation. Urban corridor penetration lags regional peers due to cold-chain constraints, though ambient-stable formats gain traction through traditional trade channels. Local bottlers face ISO 22000 certification queues extending 14-18 months across accredited bodies.
Asia-Pacific Ready to Drink (RTD) Coffee Market Competitive Environment
Player mix skews toward multinational beverage conglomerates with diversified coffee portfolios and established distribution networks. The competitive structure concentrates around three strategic archetypes: diversified conglomerates leveraging cross-category scale, coffee-specialized producers with backward integration into bean sourcing, and contract manufacturing specialists serving private-label demand. Dominant competitive moves include co-manufacturing partnerships to bypass aseptic line capex thresholds and geographic licensing arrangements to navigate SAMR registration timelines.
Within the diversified conglomerate tier, Nestle S.A. and The Coca-Cola Company exemplify scale-driven positioning across ambient and chilled formats. Suntory Holdings Limited occupies a specialist position through proprietary filling technology investments. These three anchors demonstrate how capital reserves and technical capabilities fragment competitive tiers, freezing out regional bottlers lacking access to contract manufacturing networks or backward integration into coffee bean supply.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Keurig Dr Pepper, Inc. |
| Kirin Holdings Company, Limited |
| Starbucks Corporation |
| Lotte Chilsung Beverage Co., Ltd. |
| Nestle S.A. |
| UCC Holdings Co., Ltd. |
| Tata Consumer Products |
| Suntory Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Aseptic filling equipment replacing legacy PET nitrogen-dosing lines simultaneously redraws supply geography toward Japanese and South Korean manufacturing clusters and compresses margin economics for mid-scale bottlers lacking co-manufacturing access.
Pricing Analysis
Certification level creates the primary spread between premium and mass-market tiers, with ISO 22000-accredited producers commanding shelf-space premiums in Australian supermarkets while uncertified regional bottlers compete on transactional spot pricing. Cold brew extraction protocols and proprietary steeping cycles add second-layer differentiation. Pricing pressure stems from Arabica futures volatility exposing margin structures at the commodity end. Students and price-sensitive volume seekers show highest elasticity, while working professionals in Seoul's dense office corridors demonstrate lowest price sensitivity for convenience-positioned formats.
Supply Chain Analysis
Inventory lead times for aseptic filling equipment extend 14-18 months through accredited certification bodies, forcing entrants toward contract manufacturing partnerships. Coffee bean supply concentrates in Indonesian highland estates, Vietnamese robusta corridors, and Brazilian arabica regions. Raw material dependencies span green coffee futures, aluminum can sheet, and aseptic carton laminate. Single-source vulnerability runs through Japanese cold-chain fleet operators facing F-Gas retrofit deadlines. Distribution feeds from vertically integrated conglomerates through convenience store cold vaults and vending machine networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary aseptic filling capability represents the binding constraint separating viable national distribution from metro-limited presence, with technician training pipelines and certification audit queues creating asymmetric access for capital-reserved players.
For Market Incumbents: Consolidate cold-chain fleet capacity ahead of Japan's F-Gas phasedown deadlines, capturing stranded regional operators unable to fund refrigerant retrofits. Deepen backward integration into Indonesian highland bean sourcing to hedge Arabica futures exposure. Lock in co-manufacturing partnerships with mid-scale bottlers facing ISO 22000 certification delays, converting potential competitors into captive supply channels. For New Entrants and Emerging Players: White-space in Vietnamese urban corridor chilled format penetration offers first-mover shelf positioning before Ho Chi Minh City and Hanoi convenience networks reach infrastructure saturation. Plant-based milk stabilization technologies for lactose-intolerant segments remain underdeveloped by legacy dairy-dependent portfolios. Pursue direct-to-convenience-store distribution bypassing supermarket slotting fee barriers that favor conglomerate scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed contract manufacturing specialists possessing installed aseptic line capacity but lacking brand equity. Five-to-ten-year viability hinges on regulatory arbitrage across Australia's pending FSANZ beverage reclassification and China's SAMR sugar-free claim enforcement trajectory. Monitor refrigerant technician training pipeline expansion as inflection signal for cold-chain consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Line Capacity Expansion | Extends shelf-life positioning without preservatives, satisfying Japan's MHLW additive standards. |
| Backward Integration into Bean Sourcing | Captures Indonesian highland estate supply, hedging Arabica futures volatility exposure. |
| Cold-Chain Fleet Retrofit Compliance | Meets Japan's F-Gas phasedown schedules, consolidating distribution toward capital-reserved operators. |
| Plant-Based Milk Formulation Partnership | Unlocks lactose-intolerant segments through oat and almond protein stabilization technologies. |
| ISO 22000 Certification Investment | Enables premium retail placement in Australian supermarkets and South Korean convenience chains. |
Study Parameters
Cross-validation between trade customs data and retail audit filings anchors the qualitative findings, combining primary interviews with RTD coffee brand managers, convenience store category buyers, cold-chain logistics operators, and aseptic equipment procurement leads with secondary validation through MFDS registration databases, SAMR product filing records, FSANZ beverage classification rulings, and SEC 10-K disclosures from diversified beverage conglomerates. Bottom-up volume triangulation across packaging format SKUs reconciles with top-down category value estimates.
Sensitivity analysis tests forecast robustness across alternative regulatory enforcement scenarios and commodity price trajectories. The analytical framework segments by product type, distribution channel, packaging format, and customer demographic across the projection horizon. CAGRs derive from trend extrapolation adjusted for saturation effects and substitution dynamics. Key inputs include convenience store cold vault expansion rates, F-Gas retrofit compliance timelines, and ISO 22000 certification queue lengths.
Underlying assumptions cover regulatory enforcement continuity, cold-chain infrastructure investment pacing, and commodity futures stability, with deviation risk concentrated in China's SAMR sugar-free claim adjudication and Japan's refrigerant technician training pipeline expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Vietnam Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Europe Coffee Pods and Capsules Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Decoction Maker Market
Coffee
Bioactive Proteins in Coffee Market
Coffee
Single Origin Coffee Market
Coffee
Single-Serve Coffee Containers Market
Coffee
Saudi Arabia Coffee Roaster Market
Coffee
Australia Coffee Market
Coffee
Encapsulated Caffeine Market
Coffee
Dairy-Free RTD Coffee Products Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Green Coffee Market
Coffee
Organic Coffee Market
Coffee
India Coffee Roaster Market