
 Tea and Coffee Bags Market | 2026-2036
Tea and Coffee Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Tea and Coffee Bags Market Intelligence
The proliferation of independent coffee roasters and specialty tea brands is realigning purchasing patterns away from large-scale contracts. This fragmentation creates opportunities for flexible packaging suppliers. Amcor leverages its global manufacturing footprint to serve multinational beverage companies, while Huhtamaki specializes in solutions for both large and small-batch producers. Berry Global competes on material science, offering advanced films and nonwovens for premium applications.
Tea and coffee bags are single-use, porous pouches containing pre-portioned dried tea leaves or ground coffee for infusion in hot water. These products are typically constructed from filter papers, woven fabrics like silken nylon, or polylactic acid (PLA) mesh, all designed for optimal flavor extraction and particle retention. Biodegradable bags represent the fastest-growing product type, gaining share over traditional filter papers. Within distribution channels, online retail and specialty stores show higher growth compared to mature supermarket segments.
Food contact material regulations from bodies like the US FDA and the European EFSA dictate permissible polymers, adhesives, and printing inks. Standards for compostability and biodegradability, such as those aligned with ISO norms or national rules from India's FSSAI, govern market access for sustainable products. Vendor selection will increasingly hinge on a supplier's ability to document material traceability and compliance with evolving circular economy mandates.
Market Dynamics
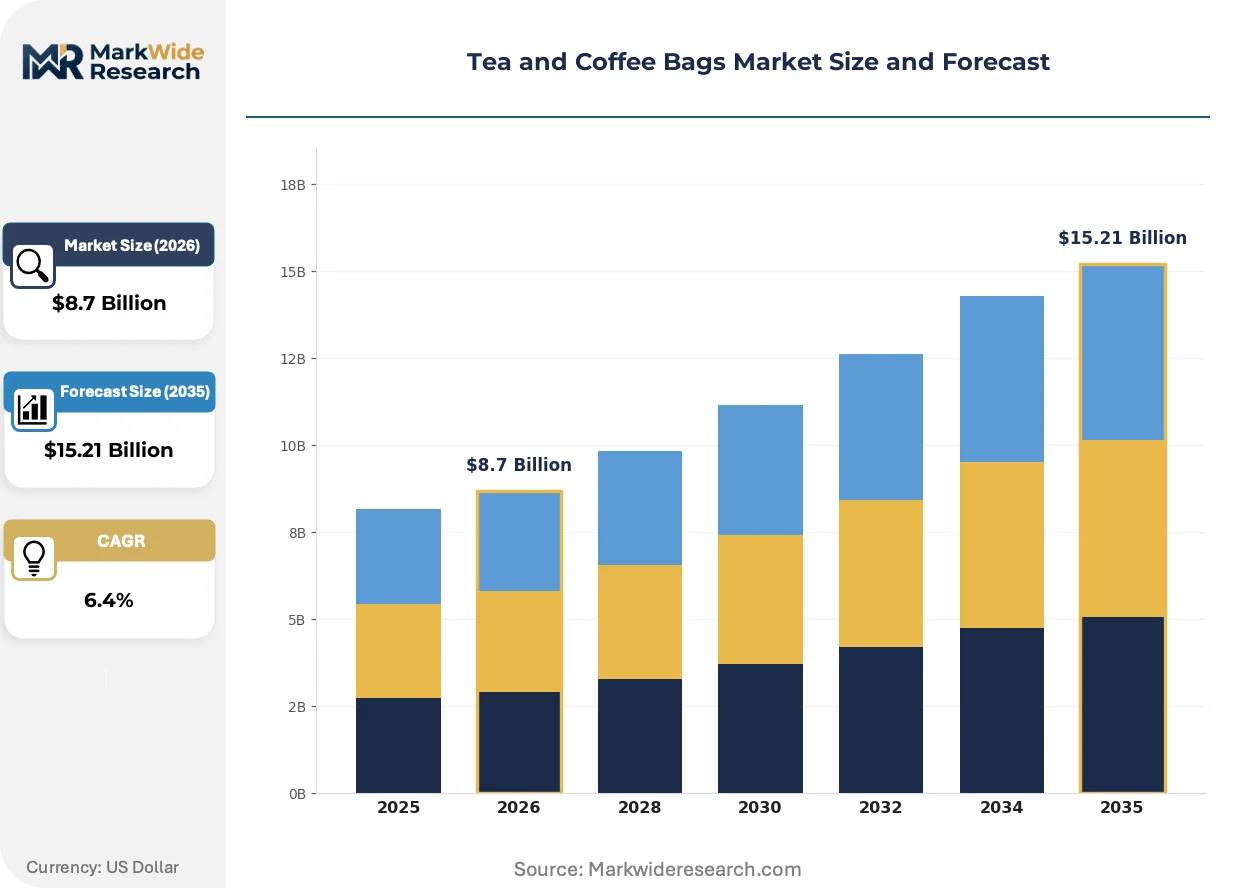
The central dynamic shaping the market is the tension between the premiumization of single-serve beverages and the intensifying regulatory pressure for sustainable, circular packaging. This forces material innovation toward solutions that deliver superior flavor extraction while meeting stringent compostability and food-contact standards.
Growth Catalysts
- Sustainable Material Mandates:Regulatory frameworks like the EU Green Deal are compelling brands to adopt biodegradable and compostable materials, creating a direct catalyst for filter papers and PLA mesh certified for industrial or home composting.
- Specialty Beverage Culture:The expansion of independent coffee roasters and premium tea purveyors in urban centers across the United States, Germany, and Japan is increasing the need for sophisticated single-serve packaging that signals quality.
- Performance of Advanced Materials:Innovations in woven and nonwoven fabrics, such as silken nylon and PLA, offer enhanced infusion characteristics and particle retention, which supports the higher price points of specialty products.
Market Restraints
- Input Cost Volatility:The price of polylactic acid (PLA) resins, a primary input for biodegradable bags, is subject to fluctuations based on feedstock availability and biopolymer production capacity, creating margin uncertainty for converters.
- Technical Performance Gaps:Certain biodegradable materials can exhibit lower heat-sealing consistency and oxygen barrier properties compared to conventional non-compostable plastics, posing risks to product shelf life and manufacturing efficiency.
- Fragmented Compostability Standards:Disparities between national regulations, such as those from India's FSSAI, and regional standards like those in the EU create compliance hurdles for brands seeking to launch a single sustainable product globally.
Strategic Opportunities
- Cold Brew Applications:Developing larger-format, durable porous pouches specifically designed for the cold brew coffee and tea market represents a significant opportunity, as this segment requires different material properties than hot infusion products.
- Emerging Market Premiumization:Targeting the growing middle-class consumer base in Southeast Asian and Latin American countries with premium, sustainably packaged tea and coffee products offers a new growth frontier beyond mature markets.
- Circular Economy Alignment:Proactively designing packaging for compliance with future circular economy mandates, including those related to recycled content or material traceability, can create a distinct competitive advantage with large beverage brands.
Industry Challenges
- Regulatory Compliance Documentation:Maintaining comprehensive traceability and documentation for all food contact materials, including polymers, adhesives, and inks, to satisfy evolving requirements from the US FDA and European EFSA is a significant operational burden.
- Supply Chain Reconfiguration:Shifting sourcing from established, large-scale suppliers of traditional filter paper to a more fragmented and specialized base of certified compostable material vendors requires significant investment in qualification and logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea and Coffee Bags Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silken Bags, Filter Papers, Cloth Bags, Biodegradable Bags Flavor: Herbal, Green Tea, Espresso, Flavored Coffee Packaging Type: Boxed, Loose Packs, Sachets, Pouches Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafés |
| Companies Covered | Printpack, CarePac, Amcor, Boyue Printing, PBFY Packaging, Berry Global, Huhtamaki, MTPak, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea and Coffee Bags Market Strategic Shifts & Innovations
Material science advancements are converging with consumer ethical demands, reshaping the market. The primary focus is on developing packaging that delivers a premium sensory experience for tea and coffee while providing a verifiable, environmentally responsible end-of-life pathway, moving beyond mere functionality.
Polylactic acid (PLA) mesh, a bioplastic derived from plant-based resources, offers a transparent, pyramid-shaped structure that enables superior water flow and infusion. Specialty tea brands and premium single-origin coffee producers are adopting PLA for its high-end aesthetic and certified compostability. This material innovation is absorbing market share from conventional petroleum-based nylon and bleached paper filter bags, especially within the premium retail and food service channels.
European Union directives under the Green Deal framework are establishing strict targets for packaging waste reduction and recyclability. These regulations compel manufacturers to reconsider material choices, favoring mono-materials and certified compostable bioplastics over complex, multi-layer structures. The biodegradable product segment is most directly impacted, as suppliers must now provide rigorous, third-party-verified data aligned with ISO norms to substantiate environmental claims in the European market.
Purchasing behavior is fragmenting away from large, centralized contracts toward more flexible, small-batch procurement. The proliferation of independent coffee roasters and artisanal tea blenders creates demand for suppliers who can offer lower minimum order quantities and customized packaging solutions. This trend is disrupting the established distribution model dominated by high-volume orders and is most visible in the competitive metropolitan markets of North America and Western Europe.
Tea and Coffee Bags Market Segmentation
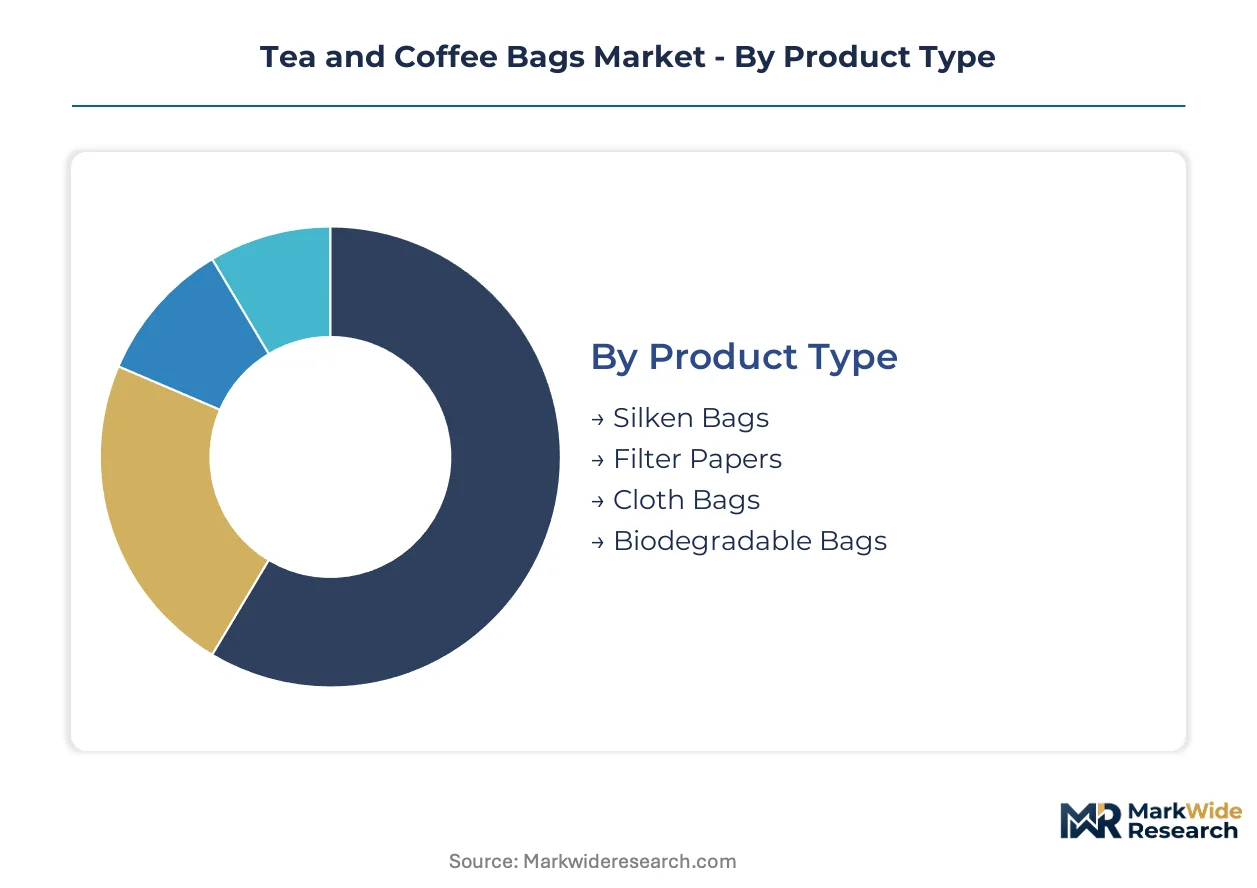
The Tea and Coffee Bags Market is granularly segmented, reflecting the diverse material innovations and evolving consumer preferences driving its expansion. Understanding these distinct segments allows for precise market positioning and strategic resource allocation across product development and distribution.
Product Type:
The market for tea and coffee bags exhibits a varied degree of material integration, ranging from basic standalone filter media to advanced embedded solutions.
- Silken Bags:These premium bags, often made from nylon or PLA mesh, provide superior aesthetic appeal and optimal infusion characteristics for specialty teas and coffees. Demand in urban centers across Germany and Japan favors these high-end options for their visual and performance attributes.
- Filter Papers:Constructed from cellulose fibers, these traditional, cost-effective bags are widely used for both tea and coffee, offering reliable particle retention. Large-scale commercial operations and mainstream supermarket brands in the United States continue to rely on filter papers for their established supply chains.
- Cloth Bags:Typically reusable or compostable, these bags are often made from cotton or muslin, appealing to environmentally conscious consumers seeking plastic-free alternatives. Independent tea blenders and zero-waste retailers are increasingly offering cloth bags for bulk tea purchases.
- Biodegradable Bags:Composed of materials like PLA or plant-based fibers, these bags are designed to break down naturally, aligning with circular economy mandates. Regulatory frameworks in the European Union are compelling brands to adopt these materials, driving their market share growth.
Volume placements concentrate in Filter Papers; the faster expansion belongs to Biodegradable Bags.
Flavor:
Consumer preferences delineate distinct flavor profiles, catering to diverse palate segments across the globe.
- Herbal:These bags contain infusions made from herbs, spices, or other plant materials, offering caffeine-free alternatives with various health benefits. Demand for herbal options is consistent across wellness-focused demographics in North America.
- Green Tea:Characterized by minimal oxidation, green tea bags deliver a fresh, often grassy flavor profile, rich in antioxidants. Asian markets, particularly Japan, demonstrate strong, sustained demand for green tea products.
- Espresso:Specifically formulated for intense, concentrated coffee brewing, espresso bags cater to consumers seeking strong flavor and convenience. Specialty coffee shops in Germany and the United States are driving demand for premium espresso pods and bags.
- Flavored Coffee:These bags contain ground coffee infused with various artificial or natural flavors, such as vanilla, hazelnut, or caramel. Younger consumer segments in Western markets show a preference for flavored coffee varieties.
While traditional Herbal and Green Tea varieties maintain consistent demand, Espresso and Flavored Coffee are experiencing accelerated uptake.
Packaging Type:
Packaging formats demonstrate varying volume capacities, from individual servings to bulk options for institutional use.
- Boxed:This traditional packaging method involves multiple tea or coffee bags enclosed within a cardboard box, providing protection and brand visibility. Supermarkets globally stock a wide array of boxed tea and coffee bags for household consumption.
- Loose Packs:These refer to bags sold without individual outer packaging, often in larger quantities, appealing to cost-conscious consumers or bulk purchasers. Foodservice providers in the United States frequently procure loose packs for high-volume operations.
- Sachets:Individual, sealed packets containing a single tea or coffee bag, sachets offer maximum convenience and freshness, particularly for on-the-go consumption. Hotel chains and travel-oriented retailers utilize sachets for their portability.
- Pouches:Flexible, resealable bags that often contain multiple tea or coffee bags, pouches provide extended shelf life and reduced material usage compared to rigid packaging. Specialty tea brands are adopting resealable pouches for their premium loose-leaf tea bags.
Boxed formats dominate traditional retail volume, but flexible Pouches are gaining traction for convenience and single-serve applications.
Distribution Channel:
Different distribution channels reflect varying levels of market maturity and consumer access.
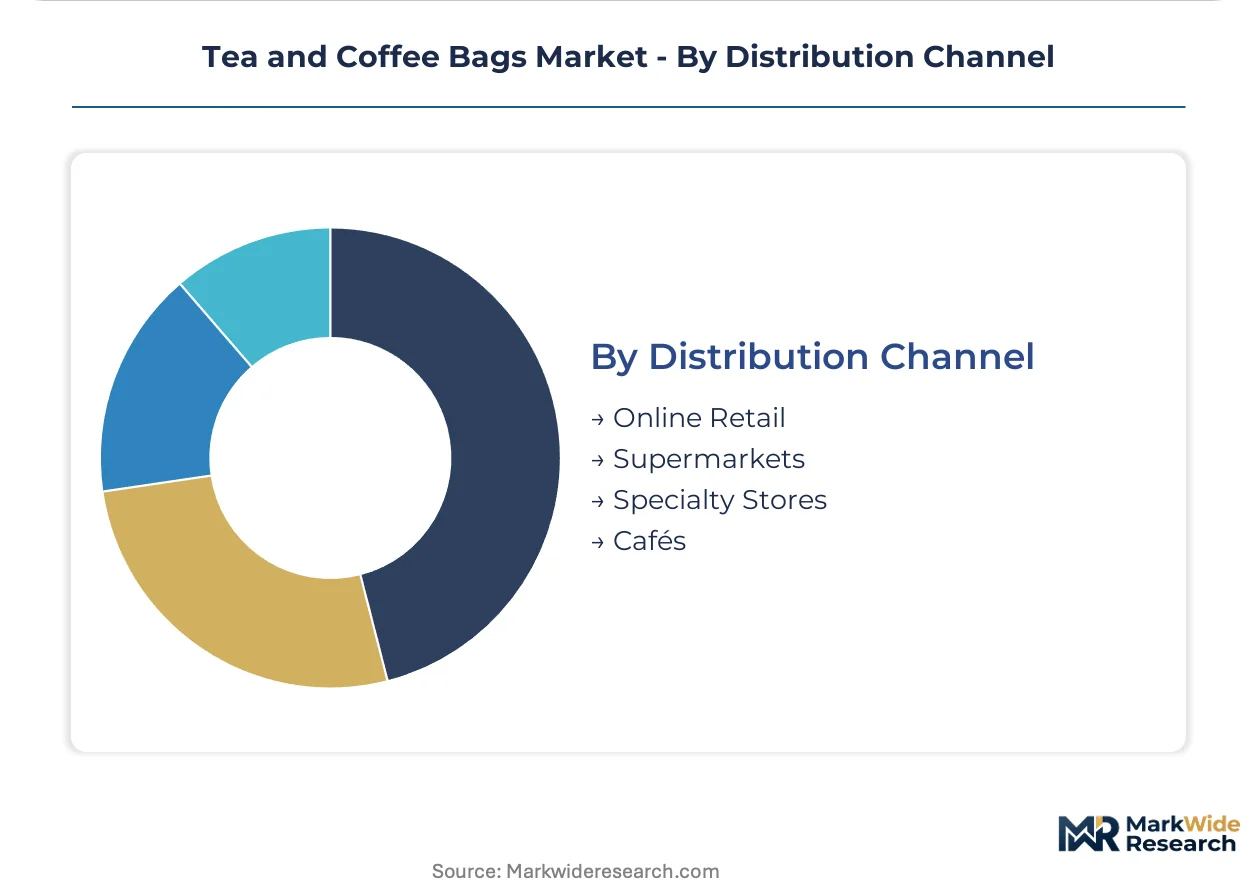
- Online Retail:E-commerce platforms facilitate direct-to-consumer sales and provide extensive product variety, reaching a broad customer base. Growth in this channel is significant across all major markets, driven by convenience and niche product availability.
- Supermarkets:Large retail chains offer a wide selection of mainstream tea and coffee bag brands, serving as a primary purchasing point for most consumers. This mature channel accounts for substantial volume sales globally.
- Specialty Stores:These outlets focus on premium, artisanal, or niche tea and coffee products, often providing a curated shopping experience. Independent coffee roasters and tea purveyors leverage specialty stores to reach discerning customers in metropolitan areas.
- Cafés:Food service establishments that prepare and serve beverages directly to consumers, cafés represent a significant point of consumption for single-serve tea and coffee bags. Expansion of premium coffee culture in Germany and the United States boosts this channel.
Supermarkets maintain broad consumer reach, but Online Retail and Specialty Stores are expanding rapidly, especially for premium offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its significant agricultural base, influences the availability of plant-based feedstocks for biodegradable tea and coffee bags. This market sees substantial demand from its thriving specialty coffee culture. European Union regulations further shape material innovation.
United States
The United States experiences high demand for premium single-serve tea and coffee bags due to its extensive specialty coffee culture. US FDA regulations dictate permissible polymers and inks for food contact materials. Major metropolitan areas like New York City drive innovation in customized packaging solutions.
Germany
Germany's robust premium coffee culture fuels demand for sophisticated single-serve packaging. The EU Green Deal mandates accelerated adoption of biodegradable and compostable materials. Urban centers such as Berlin see significant growth in specialty stores offering high-end tea bags.
Japan
Japan's discerning consumers seek premium tea and coffee bags, particularly silken and green tea varieties. METI influences the development of sustainable packaging standards for market access. The Tokyo metropolitan area is a hub for high-end aesthetic packaging innovations.
India
India's expanding middle-class consumer base shows increasing interest in premium, sustainably packaged tea products. FSSAI standards govern compostability and material traceability for market entry. Cities like Mumbai are emerging as key markets for new tea bag formats.
France
France exhibits strong demand for specialty tea and coffee bags, emphasizing aesthetic appeal and sustainable attributes. European Union directives, including the Green Deal, compel manufacturers to adopt mono-materials. Paris, a major European capital, drives trends in eco-conscious packaging design.
Tea and Coffee Bags Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue flexible packaging solutions and sustainable material innovations. The market structure reflects a mix of large-scale multinational suppliers and specialized providers for niche segments. Companies differentiate through material science expertise and global manufacturing footprints. Competitive moves focus on achieving regulatory compliance and expanding into biodegradable product lines.
At the scale-driven end, Amcor leverages its extensive global manufacturing footprint to serve multinational beverage companies. Huhtamaki, a Finland-based packaging solutions provider, occupies a position catering to both large and small-batch producers. Berry Global Group, Inc., an Indiana-based plastics manufacturer, exemplifies a focus on material science, offering advanced films and nonwovens for premium applications. These companies represent different strategic approaches within the tea and coffee bags market, addressing diverse client needs across the value chain.
| Leading Market Players |
|---|
| Printpack |
| CarePac |
| Amcor |
| Boyue Printing |
| PBFY Packaging |
| Berry Global |
| Huhtamaki |
| MTPak |
| Sealed Air |
| Others |
Cost & Logistics Intelligence
Independent coffee roasters and specialty tea brands drive a transactional pricing model for packaging, often featuring tiered volume discounts. This model reflects their varied procurement scales and customization needs.
Pricing Analysis
Volume-driven segments like traditional filter papers operate on tighter margins, while premium biodegradable bags command higher price points. The dominant pricing structure is a hybrid of contract-based long-term agreements for large-scale buyers and transactional models for smaller, specialized orders. Price differentiation stems from certified compostability standards and advanced material properties like PLA mesh. Pricing pressure stems from input cost volatility for bioplastics. Supermarkets exhibit high price sensitivity, whereas specialty stores prioritize quality and sustainability.
Supply Chain Analysis
Regional distribution centers facilitate the movement of packaging materials from concentrated production hubs to beverage brands. Supply concentration for advanced materials centers on countries like China and Germany for manufacturing, and the United States for feedstock availability. The supply chain draws from key inputs such as PLA resins and specialized cellulose fibers. A structural risk involves commodity price volatility for bioplastic feedstocks. Distribution runs through both direct-to-manufacturer channels and specialized packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tea and coffee bags market navigates a technology-transition phase, with plant-based PLA mesh displacing conventional petroleum-based nylon and bleached paper. This shift aligns with consumer demand for verifiable environmental responsibility.
For Market Incumbents: Anchor existing large-scale contracts with multinational beverage companies by accelerating investment in certified compostable material research and development. Leverage global manufacturing footprints to achieve ISO norm compliance across diverse regulatory landscapes, mitigating the threat of evolving EU Green Deal mandates. Pursue strategic partnerships with biopolymer suppliers to secure feedstock for biodegradable product lines.
For New Entrants and Emerging Players: Begin with targeting niche, high-growth segments such as cold brew applications, which require distinct material properties for durability and larger formats. The most penetrable segment includes independent coffee roasters and specialty tea brands seeking customized, sustainable packaging solutions. Offer flexible minimum order quantities and advanced material options like PLA mesh for premium aesthetic appeal.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value creation in sustainable packaging solutions. Acquisition targets should focus on specialized material science companies possessing patented bioplastic technologies or advanced converting capabilities for certified compostable products. The signal to watch for accelerated market consolidation is the harmonization of global compostability standards, reducing compliance hurdles.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic R&D Investment | Accelerates development of next-generation compostable materials aligned with EU Green Deal mandates. |
| Global Certification Attainment | Ensures market access and substantiates environmental claims under diverse regulatory frameworks like FSSAI. |
| Cold Brew Pouch Development | Captures premium demand in a high-growth beverage segment requiring specialized durable packaging properties. |
| Small-Batch Customization Services | Addresses fragmented procurement patterns from independent coffee roasters and specialty tea brands. |
| Emerging Market Expansion | Taps into growing middle-class consumer bases in Southeast Asia and Latin America for premium products. |
Research Approach
Document review covered US FDA filings, European EFSA reports, ISO norms, and India's FSSAI guidelines, complemented by interviews with packaging engineers and brand managers. Industry stakeholders included procurement leads from specialty tea brands and sustainability officers at large beverage companies. This approach combined primary insights with secondary validation, utilizing both bottom-up and top-down triangulation for data accuracy.
Volume and value outputs were generated through a quantitative model, integrating historical trends and future growth drivers across the analysis window. Segmentation dimensions modeled included product type, flavor, packaging format, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from a synthesis of market dynamics and competitive landscape analysis. Key forecast inputs included PLA resin pricing trends and regulatory adoption timelines.
Underlying measurement precision varies by segment; established filter paper and supermarket distribution carry tighter precision than emerging biodegradable materials. Forecasts reflect assumptions regarding input cost volatility for PLA resins and the eventual harmonization of compostability standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Concentrate Market
Coffee
Cold Brew Coffee Market
Coffee
Asia Pacific Coffee Market
Coffee
Europe Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Crystal Market
Coffee
GCC Instant Coffee Market
Coffee
Coffee Roaster Machine Market
Coffee
Office Coffee Service (OCS) Market
Coffee
Roast to Order Coffee Market
Coffee
Coffee Grinder Market
Coffee
North America Instant Coffee Market
Coffee
Decaf Coffee Market
Coffee
Coffee Pods and Capsules Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Adaptogen Coffee Market