
 Australia Coffee and Tea Capsules Market | 2026-2036
Australia Coffee and Tea Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Coffee and Tea Capsules Market Intelligence
The capital-intensity divergence between multinational roasters and local boutique packagers is unwinding competitive dynamics across the category. Nestle Australia Ltd leverages its vertically integrated Nespresso-compatible supply chain to dominate pod distribution in premium retail. Vittoria Food & Beverage anchors its position through proprietary aluminum-sealing technology that extends shelf stability for supermarket channels. Lavazza Australia Pty Limited competes via specialized office-catering contracts that sustain recurring B2B volumes.
Coffee and tea capsules are single-serve, hermetically sealed portions of ground roast coffee or leaf tea, typically weighing 5–7 grams and engineered for extraction at 9-bar pressure in compatible brewing systems. The primary commercial purpose is delivering consistent beverage quality with minimal preparation time across household, workplace, and hospitality settings. Coffee capsules lead product-type value generation due to entrenched espresso culture, while bio-based material alternatives represent the fastest-growing structural segment as APCO targets pressure converters away from conventional plastic. Aluminum occupies the premium margin pool through perceived recyclability and barrier performance, though composite formats now dominate total unit volumes.
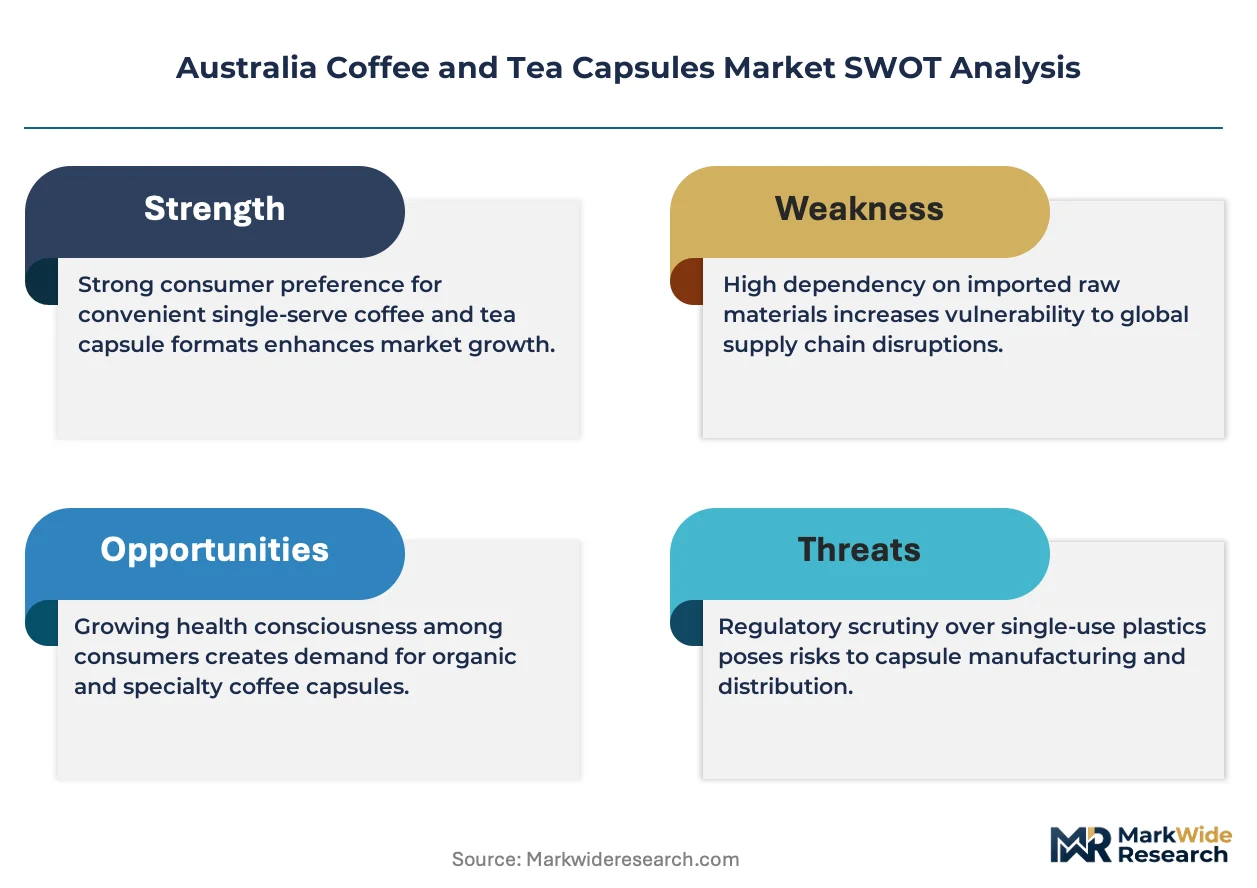
FSANZ food-contact material standards, the ACCC's mandatory recycling label requirements, and state-level container deposit schemes collectively shape capsule design specifications and market access conditions across Australia. TGA-adjacent caffeine-content disclosure rules for decaffeinated variants further constrain formulation and labeling practices. Stakeholders must monitor whether emerging state-based single-use plastic bans in Queensland and Western Australia will accelerate material conversion timelines or fragment compliance obligations across jurisdictions.
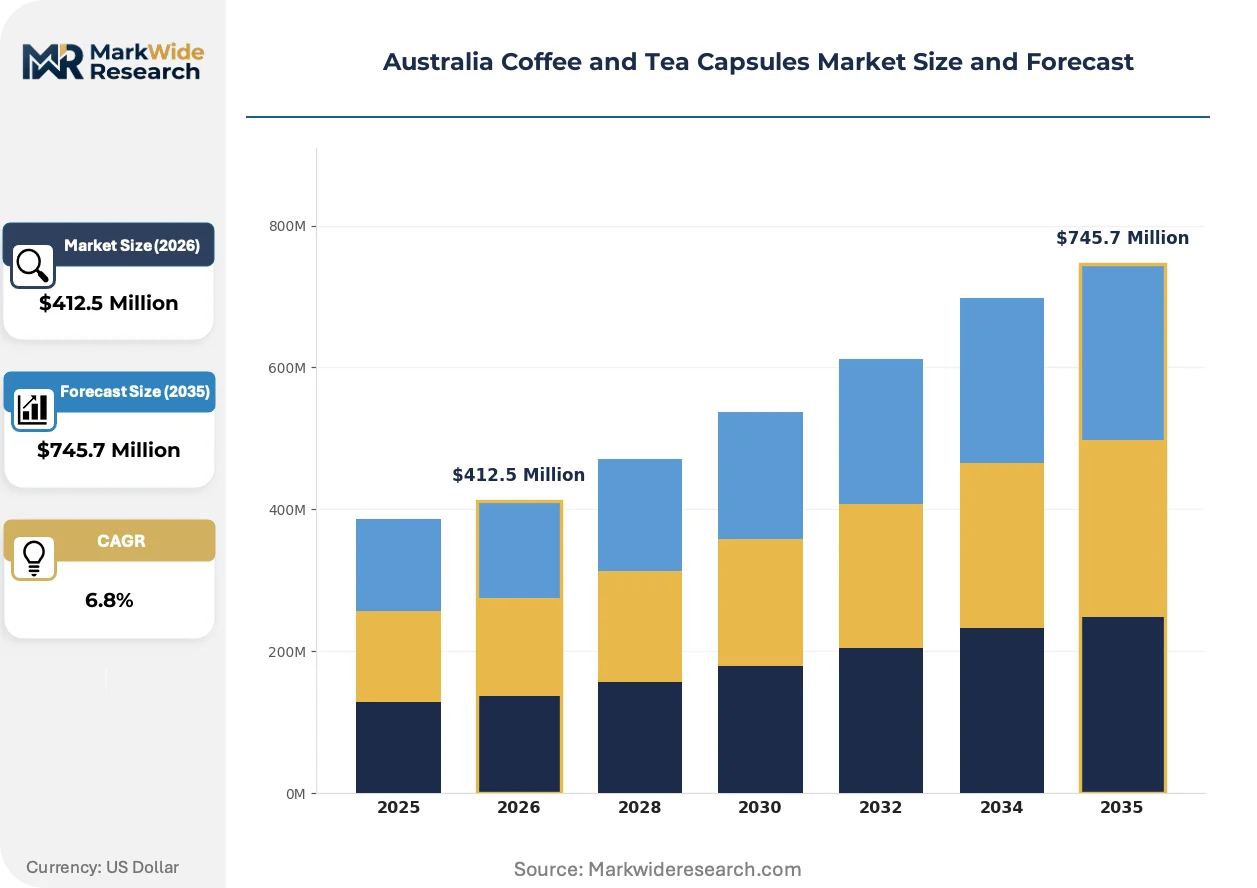
Market Dynamics
Material conversion timelines under Australia's National Plastics Plan are compressing converter margins while reshaping procurement specifications across hospitality and retail channels. The APCO 2025 packaging targets are forcing rapid aluminum-to-compostable transitions that favor converters with captive biopolymer supply.
Growth Catalysts
- Specialty hospitality demand:Premium hotels and independent cafés in Melbourne and Sydney are mandating certified-compostable pods for procurement contracts, creating volume anchors for domestic converters.
- APCO recycling mandates:The Australian Packaging Covenant Organisation's 2025 targets require 70% of packaging to be recyclable or compostable, accelerating material R&D investment.
- Home espresso penetration:Households in New South Wales and Victoria are adopting pod systems at rates outpacing traditional ground coffee, sustaining replacement-cycle revenue.
Market Restraints
- Aluminum price volatility:Global aluminum ingot fluctuations compress margin stability for converters locked into long-term hospitality supply contracts.
- Biopolymer supply concentration:Limited domestic PLA and PHA production capacity creates import dependency on Southeast Asian resin suppliers.
- FSANZ food-contact compliance:Extended certification timelines for novel compostable materials delay product launches by 12–18 months versus conventional formats.
Strategic Opportunities
- Queensland and Western Australia expansion:State-level single-use plastic bans in these markets create first-mover advantages for compliant pod suppliers before enforcement spreads.
- Office-catering channel integration:Corporate procurement platforms are consolidating beverage supply contracts, enabling direct B2B relationships bypassing retail intermediaries.
- Composting infrastructure alignment:Partnerships with municipal organic waste processors in South Australia and Victoria can secure end-of-life certification premiums.
Industry Challenges
- Material science talent scarcity:Formulation chemists with biopolymer barrier-property expertise command premium wages that strain mid-tier converter budgets.
- Legacy equipment retooling:Existing thermoforming and sealing lines require capital-intensive modification to handle compostable web materials at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Coffee and Tea Capsules Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffee Capsules, Tea Capsules, Herbal Infusion Capsules, Decaffeinated Capsules Material: Plastic, Aluminum, Bio-based, Composite End User: Household, Office, Hospitality, Retail Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Vending Machines |
| Companies Covered | Vittoria Food & Beverage, Mad Coffee Capsules Pty Ltd, Nestle Australia Ltd, Carlini Coffee Company, Grinders Coffee, Lavazza Australia Pty Limited, Illy Australia, Tetley (Tata Global Beverages Australia Pty Limited), Jacobs Douwe Egberts Professional Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Coffee and Tea Capsules Market Strategic Shifts & Innovations
Compostable barrier technologies are overtaking aluminum in unit volume while extraction-system compatibility constraints reshape pod geometry standards. The convergence of material science and waste-stream logistics is redefining what "premium" signifies in capsule positioning.
Plant-based multilayer films with oxygen-barrier coatings are supplanting conventional aluminum laminates in mid-tier retail SKUs. Supermarket private-label buyers in Victoria and New South Wales are specifying these formats for 2025–2026 resets. This transition is compressing aluminum's share of volume while expanding the addressable market for converters with biopolymer extrusion capabilities.
FSANZ is tightening food-contact notification requirements for novel compostable substrates, extending pre-market review timelines. The regulator's draft guidance on migration testing for bio-based materials is forcing converters to front-load validation expenditure. Small-scale domestic suppliers are responding by pooling testing costs through industry associations rather than absorbing individual compliance burdens.
Subscription-based replenishment models are displacing supermarket impulse purchases among metropolitan households. Melbourne and Sydney consumers are locking into 90-day auto-delivery contracts with direct-to-origin roasters, bypassing traditional retail shelf competition. This shift is most visible in decaffeinated and single-origin segments where provenance storytelling supports premium pricing outside conventional channels.
Australia Coffee and Tea Capsules Market Segmentation
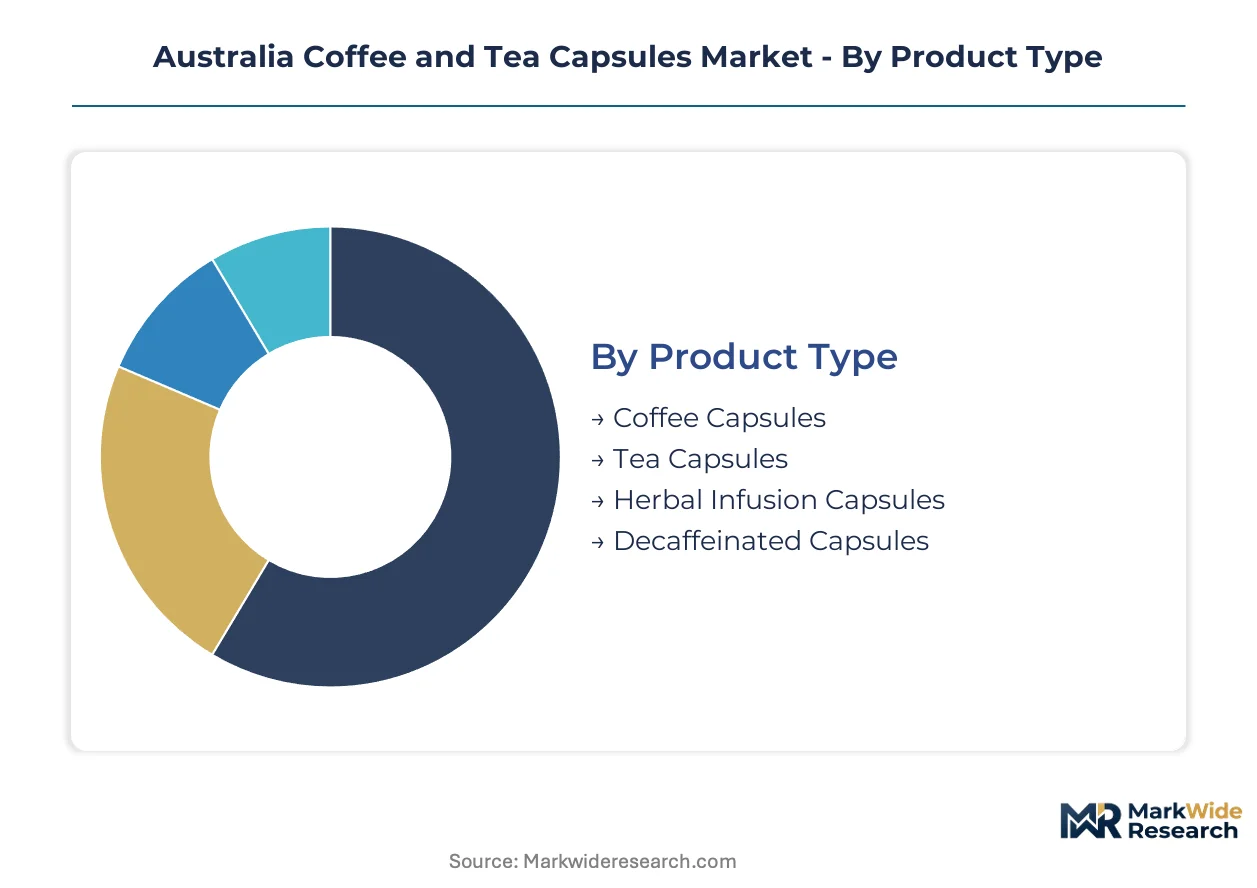
Segmentation in Australia's coffee and tea capsules market reveals how material regulations, channel consolidation, and hospitality procurement standards are fragmenting volume across incompatible technical specifications. Each dimension carries distinct margin profiles and compliance burdens that reshape converter investment priorities.
Product Type:
Premium extraction systems in Melbourne and Sydney households concentrate margin pools in formats compatible with 9-bar pressure standards and provenance storytelling.
- Coffee Capsules:Ground roast coffee sealed in hermetically engineered portions for espresso extraction. New South Wales and Victoria households sustain replacement-cycle revenue through entrenched café culture adoption in metropolitan suburbs.
- Tea Capsules:Leaf tea portions optimized for lower-pressure brewing parameters. Procurement contracts from premium hotel chains in Sydney and Melbourne are mandating certified-compostable formats, anchoring volume for domestic converters with biopolymer capabilities.
- Herbal Infusion Capsules:Caffeine-free botanical formulations targeting wellness-positioned retail shelves in Queensland and Western Australia.
- Decaffeinated Capsules:TGA-adjacent caffeine-content disclosure requirements constrain labeling and formulation practices for this segment.
Coffee Capsules holds installed capacity. Tea Capsules is rotating up the share rankings.
Material:
Converter procurement specifications now pivot on APCO 2025 compliance timelines rather than barrier performance alone.
- Plastic:Conventional petroleum-based polymers facing accelerated phase-out under state-level single-use bans. Queensland and Western Australia enforcement timelines are compressing remaining commercial viability for this legacy format.
- Aluminum:Perceived recyclability and oxygen barrier performance sustain premium positioning. Global ingot price volatility strains margin stability for converters locked into long-term hospitality supply contracts across New South Wales and Victoria.
- Bio-based:PLA and PHA formulations gaining fastest share expansion. Limited domestic resin production creates import dependency on Southeast Asian suppliers, constraining scale-up velocity for mid-tier converters.
- Composite:Multilayer structures dominating total unit volumes through cost-optimized barrier performance. Supermarket private-label buyers in Victoria are specifying these formats for upcoming range resets.
Aluminum holds installed capacity. Bio-based is rotating up the share rankings.
End User:
Channel-specific extraction equipment and procurement consolidation patterns determine volume concentration across this dimension.
- Household:Pod system adoption in New South Wales and Victoria outpaces traditional ground coffee consumption. Subscription-based auto-delivery contracts are displacing supermarket impulse purchases among metropolitan consumers.
- Office:Corporate procurement platforms consolidating beverage supply contracts enable direct B2B relationships bypassing retail intermediaries. Melbourne and Sydney central business districts anchor recurring volume.
- Hospitality:Premium hotels and independent cafés mandating certified-compostable pods for procurement contracts.
- Retail:Shelf-space competition intensifying as private-label buyers specify material transitions ahead of regulatory deadlines.
Household holds installed capacity. Office is rotating up the share rankings.
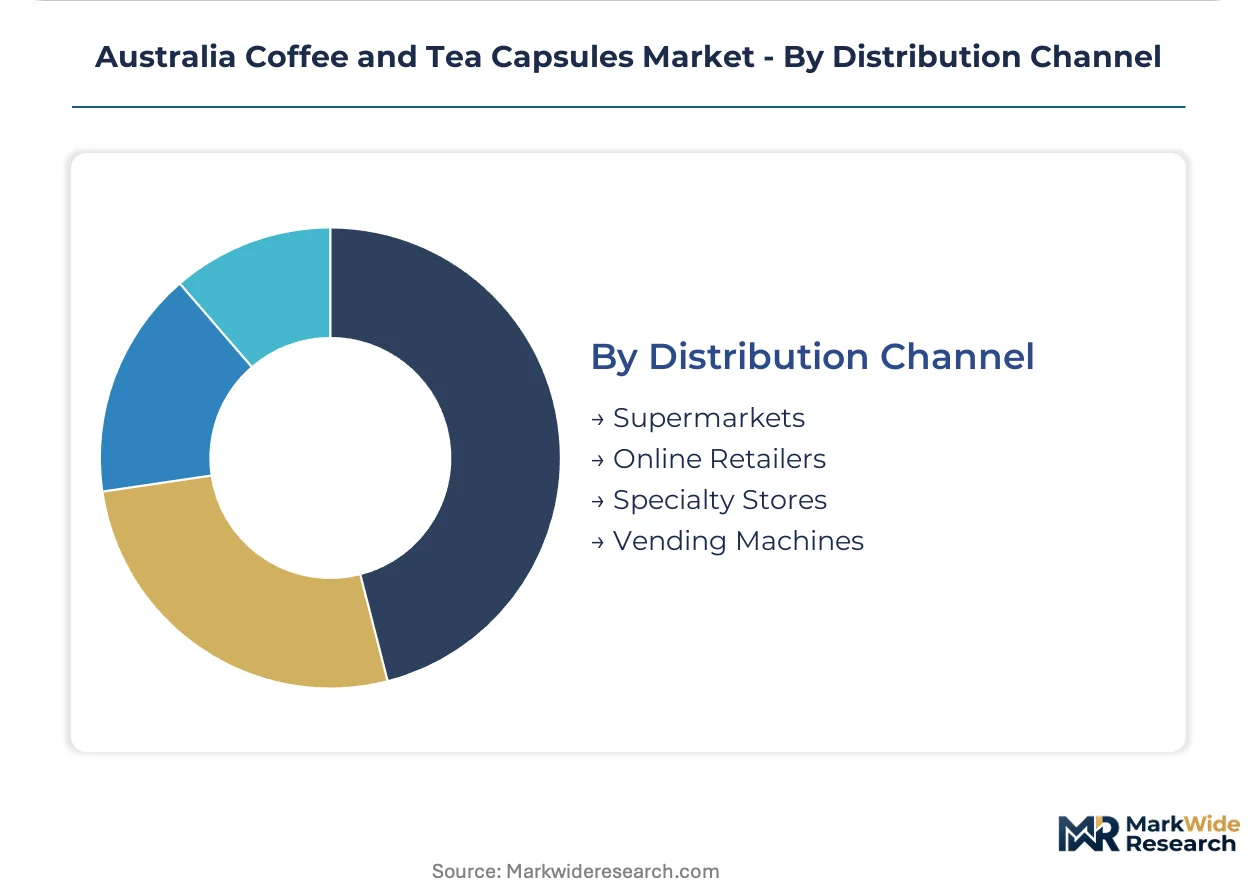
Distribution Channel:
Channel selection now correlates with material certification requirements and end-user technical sophistication.
- Supermarkets:Private-label specification power is driving compostable material transitions. Victoria and New South Wales retail resets are compressing aluminum's shelf presence.
- Online Retailers:Direct-to-origin roasters leveraging provenance storytelling for premium pricing outside conventional retail. Auto-delivery subscriptions concentrate in decaffeinated and single-origin segments.
- Specialty Stores:Curated equipment and capsule compatibility guidance for enthusiast consumers.
- Vending Machines:Workplace and hospitality automated dispensing requiring extended shelf-stability formats.
Supermarkets holds installed capacity. Online Retailers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power through Sydney's hospitality procurement concentration, while Victoria's manufacturing density enables cost-competitive compostable pod production. This asymmetry shapes converter investment allocation across Australia's eastern seaboard.
New South Wales
Sydney's premium hotel chains and independent cafés are mandating certified-compostable pods for procurement contracts. The state's container deposit scheme and APCO compliance timelines accelerate material transitions for hospitality suppliers. Parramatta and North Sydney industrial zones concentrate converter facilities serving metropolitan foodservice channels.
Victoria
Melbourne's entrenched specialty coffee culture sustains household pod system adoption rates outpacing traditional ground coffee. FSANZ food-contact material standards constrain novel compostable substrate certification timelines for local converters. Port Melbourne and Dandenong manufacturing corridors anchor biopolymer extrusion capacity for supermarket private-label supply.
Queensland
State-level single-use plastic bans create first-mover advantages for compliant pod suppliers before enforcement spreads nationally. Brisbane's corporate procurement platforms consolidate beverage supply contracts for office-catering channels. Gold Coast hospitality venues drive demand for aluminum-format premium capsules despite material transition pressures.
Western Australia
Perth's geographic isolation intensifies supply chain costs for biopolymer resin imports from Southeast Asian suppliers. The state's impending single-use plastic restrictions compress remaining commercial viability for conventional petroleum-based pod formats. Fremantle port infrastructure constrains scale-up velocity for mid-tier converters seeking compostable material transitions.
South Australia
Municipal organic waste processing partnerships in Adelaide secure end-of-life certification premiums for compliant pod suppliers. The state's advanced container deposit scheme infrastructure supports aluminum capsule recovery rates exceeding national averages. Barossa Valley tourism corridors generate seasonal hospitality demand for single-origin capsule formats.
Australia Coffee and Tea Capsules Market Key Industry Players
Concentration sits with multinational roasters leveraging vertically integrated supply chains against local boutique packagers dependent on third-party conversion capacity. Three archetypes define competitive positioning: global beverage conglomerates with captive distribution networks, domestic roasters with proprietary sealing technologies, and private-label converters serving supermarket channel specifications. Dominant competitive moves include aluminum-to-compostable material transitions and direct-to-origin subscription model deployment bypassing retail intermediaries.
Among Australia-based operators, Vittoria Food & Beverage and Mad Coffee Capsules Pty Ltd exemplify domestic roaster archetypes with proprietary technology positions, while Nestle Australia Ltd represents multinational supply chain concentration. These three entities anchor the competitive structure through divergent channel strategies: Vittoria occupies supermarket shelf stability through aluminum-sealing expertise, Mad Coffee Capsules sits within specialty hospitality procurement, and Nestle leverages Nespresso-compatible distribution scale. Lavazza Australia Pty Limited and Illy Australia occupy premium-tier import positions, with Jacobs Douwe Egberts Professional Australia representing office-catering channel consolidation. The remaining field—Carlini Coffee Company, Grinders Coffee, and Tetley—fragment across private-label and niche wellness segments.
| Leading Market Players |
|---|
| Vittoria Food & Beverage |
| Mad Coffee Capsules Pty Ltd |
| Nestle Australia Ltd |
| Carlini Coffee Company |
| Grinders Coffee |
| Lavazza Australia Pty Limited |
| Illy Australia |
| Tetley (Tata Global Beverages Australia Pty Limited) |
| Jacobs Douwe Egberts Professional Australia |
| Others |
Cost & Logistics Intelligence
Long-term hospitality procurement contracts lock in aluminum supply access while obscuring compostable material cost visibility for converters navigating APCO compliance timelines. These agreements tether margin stability to global ingot price floors, even as biopolymer alternatives reset procurement specifications across New South Wales and Victoria.
Pricing Analysis
Customization-premium spreads separate certified-compostable pod pricing from standard aluminum formats across hospitality procurement channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by material certification grade and extraction-system compatibility. Cost compression in mid-tier retail SKUs is intensifying because supermarket private-label buyers are front-loading compostable specifications ahead of regulatory deadlines. Corporate office-catering platforms exhibit lowest price sensitivity due to bundled beverage service contracts, while independent cafés in Melbourne and Sydney face acute margin pressure from dual-format inventory requirements.
Supply Chain Analysis
Thailand and Malaysia anchor biopolymer resin production for Australian converters seeking APCO-compliant material transitions. Domestic pod manufacturing draws from Southeast Asian PLA and PHA feedstocks, specialty-grade coffee roasting inputs from New South Wales and Victoria, and precision thermoforming equipment from Germany and Italy. Single-source vulnerability concentrates in biopolymer import channels through Fremantle and Port Melbourne. Distribution runs through supermarket retail intermediaries, direct-to-origin subscription platforms, and consolidated corporate procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's coffee and tea capsules market is cycling through a material-transition recovery phase as APCO 2025 targets force aluminum-to-compostable conversion investment. This cyclical driver compresses converter margins while creating first-mover premiums for compliant suppliers.
For Market Incumbents: Shield installed base relationships by securing captive biopolymer supply agreements before Southeast Asian resin capacity tightens further. Nestle Australia Ltd and Vittoria Food & Beverage should prioritize backward integration into compostable web extrusion to defend against margin erosion from aluminum price volatility and emerging local boutique packagers with direct municipal composting partnerships. For New Entrants and Emerging Players: Differentiate on end-of-life certification alignment by targeting Queensland and Western Australia markets ahead of single-use plastic enforcement waves. White-space concentration sits with office-catering channel integration through corporate procurement platforms in Brisbane and Perth, where consolidated beverage contracts bypass entrenched retail shelf competition. For Investors and Strategic Acquirers: Domestic converters with proven FSANZ food-contact certification timelines and existing biopolymer extrusion lines represent the most defensible acquisition archetype. Long-term viability hinges on material science talent retention and municipal organic waste processor partnerships securing end-of-life premiums. Watch for inflection when South Australia and Victoria composting infrastructure expansion accelerates certified-compostable volume thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Material Transition | APCO 2025 compliance timelines force aluminum-to-biopolymer conversion investment across converter facilities. |
| Direct-to-Origin Subscription Launch | Melbourne and Sydney households bypass retail intermediaries through auto-delivery contracts with provenance storytelling. |
| Corporate Procurement Platform Integration | Office-catering channel consolidation enables B2B relationships anchoring recurring volume in central business districts. |
| Municipal Composting Partnership | South Australia and Victoria organic waste processors secure end-of-life certification premiums for compliant suppliers. |
| Biopolymer Extrusion Capacity Addition | Port Melbourne and Dandenong manufacturing corridors expand captive supply reducing Southeast Asian resin dependency. |
Research Approach
A standing panel of converter operations managers, hospitality procurement directors, supermarket category buyers, and FSANZ regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from APCO packaging target disclosures, state-level container deposit scheme reports, customs import data for biopolymer resins, and ACCC recycling label compliance filings. Bottom-up volume modeling triangulated against top-down expenditure estimates from hospitality and corporate foodservice channels.
Consistency checks validated segment-level outputs against external benchmarks including retail audit data from Victoria and New South Wales supermarket resets, office-catering contract disclosure patterns, and municipal organic waste processing capacity announcements. The analytical framework modeled product type, material format, end-user channel, and distribution pathway dimensions across the projection horizon. CAGRs were derived from replacement-cycle velocity in household pod system adoption and procurement contract renewal rates in hospitality and corporate segments.
Decision-makers should treat outputs as directional under assumptions of APCO target enforcement continuity and biopolymer resin import channel stability; material deviation in state-level plastic ban timelines or Southeast Asian supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in FSANZ food-contact notification requirements and composting infrastructure commissioning announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Coffee Bags Market
Coffee
Ethiopia Coffee Market
Coffee
Global Professional Coffee Machine Market
Coffee
South Korea Coffee and Tea Capsules Market
Coffee
Philippines Coffee and Tea Capsules Market
Coffee
Butter Coffee Market
Coffee
Tea and Coffee Bags Market
Coffee
South Korea Coffee Roaster Market
Coffee
Cold Brew Coffee Pots Market
Coffee
Breakroom Refreshment and Coffee Services Market
Coffee
Freeze Dried Coffee Market
Coffee
Cafix Market
Coffee
Organic Coffee Market
Coffee
Ready to Drink (RTD) Tea and Coffee Market
Coffee
Coffee Concentrate Market
Coffee
Coffee Syrup Market