
 Saudi Arabia Coffee Roaster Market | 2026-2036
Saudi Arabia Coffee Roaster Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Coffee Roaster Market Insights
SFDA's updated food safety guidelines for coffee processing equipment is decoupling informal roasting operations from licensed commercial supply chains. Probat leverages its German engineering heritage to anchor premium installations across Riyadh's specialty coffee district. Saudi Coffee Company sustains vertical integration from green bean import through retail roasting, controlling origin narratives for domestic consumers. Genio Roasters competes on automated profiling systems that reduce operator training burdens for mid-scale café chains.
A coffee roaster is a thermal processing machine that applies controlled heat between 180°C and 240°C to green coffee beans, initiating Maillard reactions and caramelization to develop flavor compounds, aroma oils, and bean color for commercial brewing or retail sale. Espresso roasters dominate Saudi Arabia's café segment due to darker roast profiles preferred in traditional Arabic coffee preparations and Italian-style beverage menus. Fluid bed technology is gaining share among new entrants seeking faster batch turnaround and cleaner exhaust profiles compared to conventional drum systems. Small-scale capacity units lead unit shipments as home roasting and micro-roastery concepts proliferate in Jeddah's Al-Andalus district and Riyadh's Diriyah Gate development.
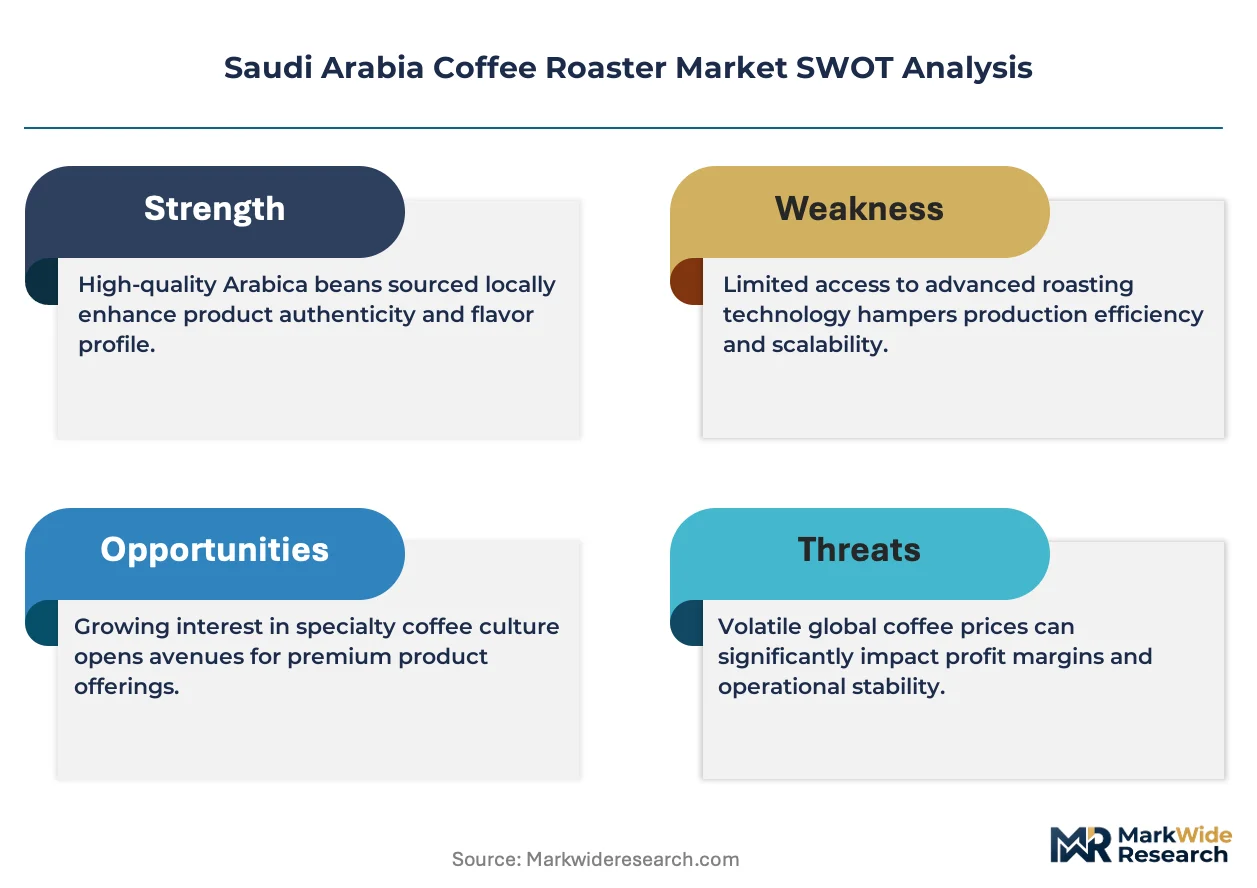
SFDA equipment certification requirements, SASO energy efficiency labeling for commercial appliances, and GSO harmonized standards for Gulf food machinery collectively elevate compliance costs for imported roasters while creating preference windows for pre-certified European and Turkish suppliers. The General Authority for Food Security's domestic coffee cultivation initiatives in Jazan Province will eventually reshape raw material sourcing patterns for roaster operators. Stakeholders should monitor SFDA's anticipated transition from voluntary to mandatory HACCP documentation for roasting facilities.
Market Dynamics
SFDA's mandatory equipment certification protocols are compressing informal roasting operations into licensed commercial supply chains, forcing capital migration toward pre-certified European and Turkish suppliers.
Growth Catalysts
- Third-wave café proliferation:Specialty coffee concepts across Riyadh's Al-Malqa district and Jeddah's Al-Andalus corridor are installing in-house roasting capacity to control origin narratives and reduce green bean inventory cycles.
- SFDA certification mandates:Tightening food safety documentation requirements for thermal processing equipment are disqualifying uncertified imports and creating procurement preference windows for compliant suppliers.
- Jazan cultivation initiatives:The General Authority for Food Security's domestic arabica planting programs will eventually shorten raw material transit distances for Central Region roaster operators.
Market Restraints
- Import dependency for certified equipment:German and Turkish manufacturers control premium drum roaster supply, exposing buyers to euro-denominated pricing volatility and extended lead times.
- Energy efficiency compliance costs:SASO labeling requirements for commercial appliances add 12-18% to total cost of ownership for roasting installations above 30kg batch capacity.
- Green bean price volatility:Brazilian and Colombian arabica futures fluctuations compress roasting margins for operators lacking long-term origin contracts.
Strategic Opportunities
- Fluid bed technology penetration:Air-roasting systems offering faster batch turnaround and cleaner exhaust profiles are capturing share among new entrants in Jeddah's emerging micro-roastery cluster.
- HACCP documentation services:Anticipated SFDA transition from voluntary to mandatory facility certification creates adjacent revenue streams for compliance consultancies and equipment vendors.
- Home roasting segment:Small-capacity electric roasters are proliferating in Riyadh's Diriyah Gate development as consumer experimentation with single-origin preparation expands.
Industry Challenges
- Roastmaster talent scarcity:Proficiency in automated profiling software and Maillard reaction management exceeds current vocational training output from Saudi technical institutes.
- Legacy equipment retrofit complexity:Drum roaster fleets imported before 2020 face costly control system upgrades to meet SFDA's revised thermal monitoring specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Coffee Roaster Market |
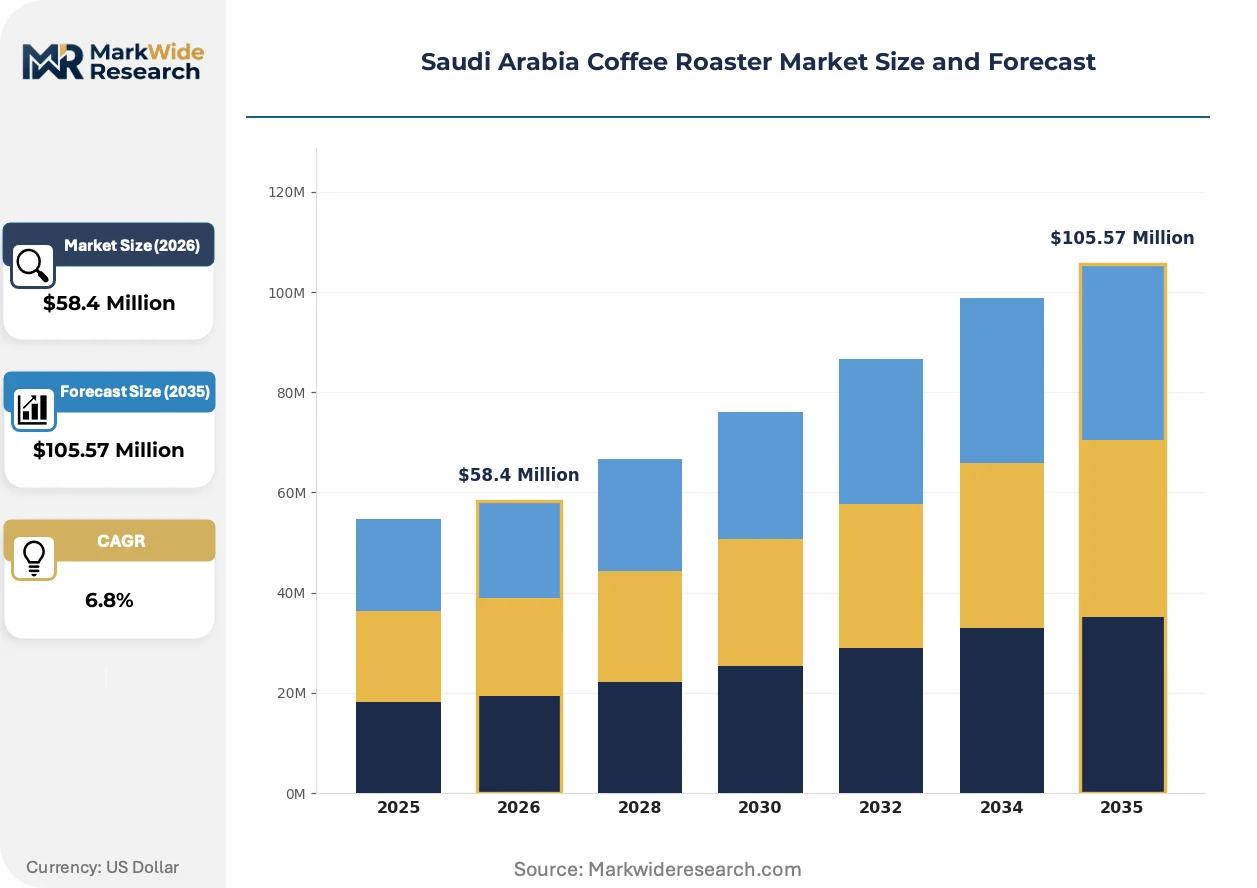
| Market Size in 2026 | $58.4 Million |
| Market Size in 2035 | $105.57 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip, Espresso, Air Roaster, Cold Brew Technology: Convection, Conduction, Hybrid, Fluid Bed End User: Cafés, Restaurants, Home Users, Retailers Capacity: Small Scale, Medium Scale, Large Scale, Industrial |
| Companies Covered | Toper, Diedrich Roasters, Black Knight Company, Probat, Genio Roasters, Saudi Coffee Company, Giesen Coffee Roasters, Scolari Engineering, Atyab Al-Karam International Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Coffee Roaster Market Trends and Innovations
Automation and regulatory digitization are compressing operator skill requirements while fragmenting procurement channels across café chains and independent roasting operations.
Automated roast profiling software is automating temperature curve management and first-crack detection that previously demanded experienced roastmaster intervention. Mid-scale café chains across Riyadh are adopting these systems to reduce training burdens and standardize output across multiple locations. The technology is automating quality consistency while enabling centralized production oversight from headquarters facilities.
SFDA's phased implementation of digital equipment registration and HACCP documentation portals is shifting compliance verification from paper-based audits to real-time data submission. Roasting facilities must now maintain continuous temperature logs and batch traceability records accessible to inspectors. Central Region operators with enterprise resource planning integration are adapting faster than standalone cafés lacking IT infrastructure.
Café chains are unbundling after-sales service contracts from equipment procurement, selecting third-party maintenance providers based on response time guarantees rather than manufacturer affiliation. Independent roasting consultants in Jeddah are displacing OEM service networks for drum refurbishment and burner calibration. This pattern is most visible among second-wave operators with mature equipment fleets seeking cost containment.
Saudi Arabia Coffee Roaster Market Segmentation
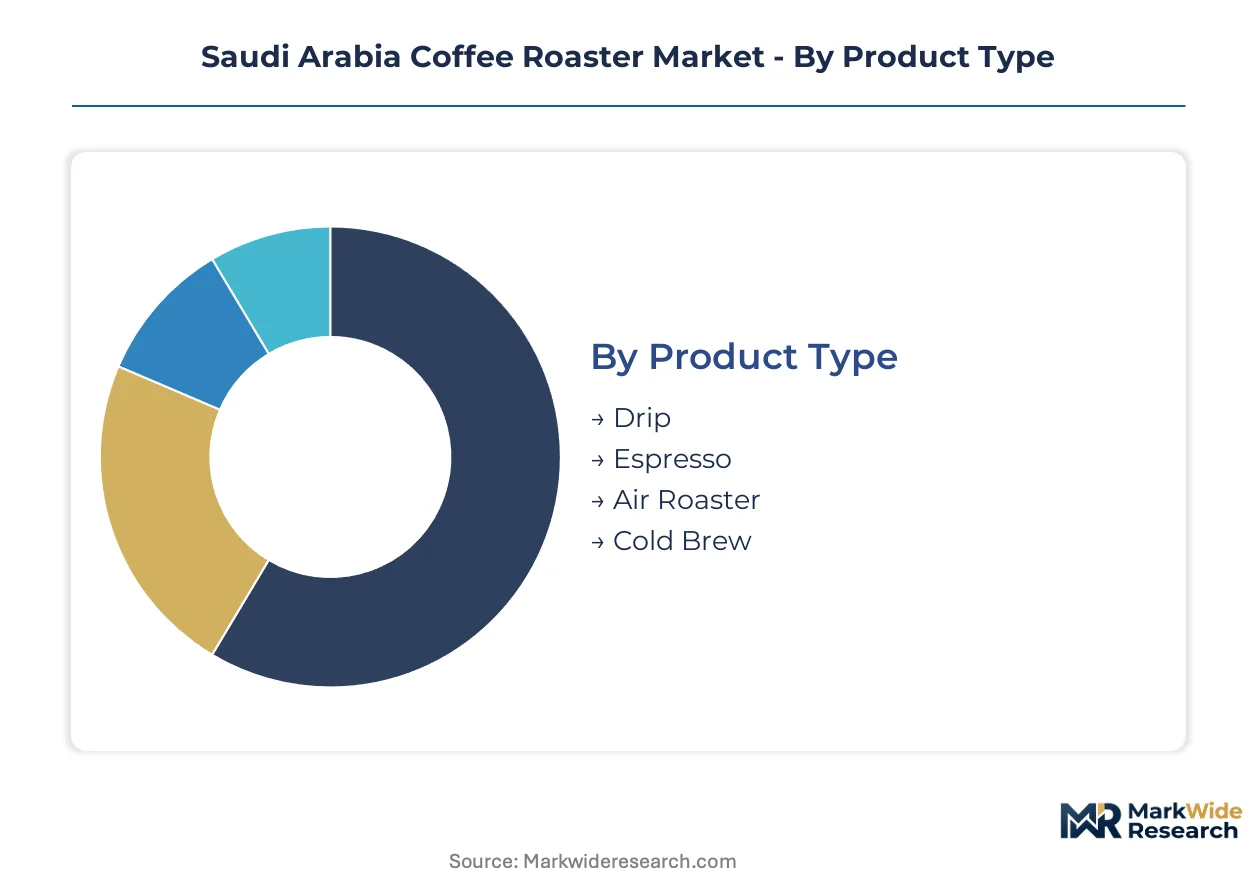
Coffee roaster procurement in Saudi Arabia fragments across four dimensions that determine equipment specifications, certification requirements, and total cost of ownership. Understanding these segment boundaries clarifies why Riyadh's specialty cafés and Jeddah's micro-roasteries source from entirely different supplier tiers despite operating in the same national market.
Product Type:
Customization intensity varies sharply across this category, from standardized mass-market units to origin-specific profiling systems.
- Espresso:Thermal processing systems optimized for darker roast profiles between 220°C and 240°C, developing the caramelized compounds preferred in traditional Arabic coffee preparations and Italian-style beverage menus. Demand concentrates in Riyadh's Al-Malqa district specialty cafés, where in-house roasting controls origin narratives and compresses green bean inventory cycles.
- Drip:Equipment calibrated for medium roast profiles emphasizing acidity clarity and origin character, typically deployed by third-wave operators seeking lighter extraction bases. Jeddah's Al-Andalus corridor cafés favor these systems for single-origin pour-over programs targeting expatriate and affluent local demographics.
- Air Roaster:Fluid bed technology utilizing convective heat transfer for faster batch turnaround and cleaner exhaust profiles, gaining traction among new entrants prioritizing operational simplicity.
- Cold Brew:Specialized low-temperature roasting profiles reducing acidity for extended steeping applications, niche but expanding in Jeddah's coastal hospitality sector.
Most installed capacity flows through Espresso. Expansion is steepest in Air Roaster as fluid bed technology penetrates micro-roastery clusters.
Technology:
Heat transfer mechanism selection directly determines SFDA compliance pathway, energy efficiency rating, and operator skill requirements.
- Drum (Conduction):Traditional rotating steel cylinders transferring heat through direct bean-to-metal contact, offering precise Maillard reaction control but requiring experienced roastmaster oversight. Central Region operators with legacy fleets face costly control system upgrades to meet SFDA's revised thermal monitoring specifications.
- Fluid Bed (Convection):Hot air suspension systems achieving faster roast development through convective heat transfer, reducing operator training burdens and enabling cleaner exhaust profiles that simplify environmental permitting.
- Convection:Hot air circulation configurations distinct from fluid bed designs, common in smaller batch equipment serving home roasting segments.
- Hybrid:Combined conduction-convection systems attempting to balance flavor development control with operational efficiency, positioned between premium drum and entry-level fluid bed price tiers.
Drum systems retain the largest installed base. Fluid Bed technology is gaining share fastest among new market entrants.
End User:
Customer type dictates batch size requirements, after-sales service expectations, and financing structure preferences.
- Cafés:In-house roasting installations across Riyadh's specialty coffee district and Jeddah's emerging micro-roastery clusters, driven by third-wave culture demands for origin narrative control and reduced green bean inventory cycles.
- Home Users:Small-capacity electric roasters proliferating in Riyadh's Diriyah Gate development as consumer experimentation with single-origin preparation expands.
- Restaurants:Front-of-house roasting displays prioritizing theater and aroma marketing over production volume, common in upscale hotel food and beverage operations.
- Retailers:Supermarket and specialty food store installations offering grab-and-go freshly roasted packages, typically sourcing through Saudi Coffee Company's vertical integration network.
Cafés command the dominant share of new equipment shipments. Home Users represent the steepest expansion trajectory as residential roasting experimentation spreads.
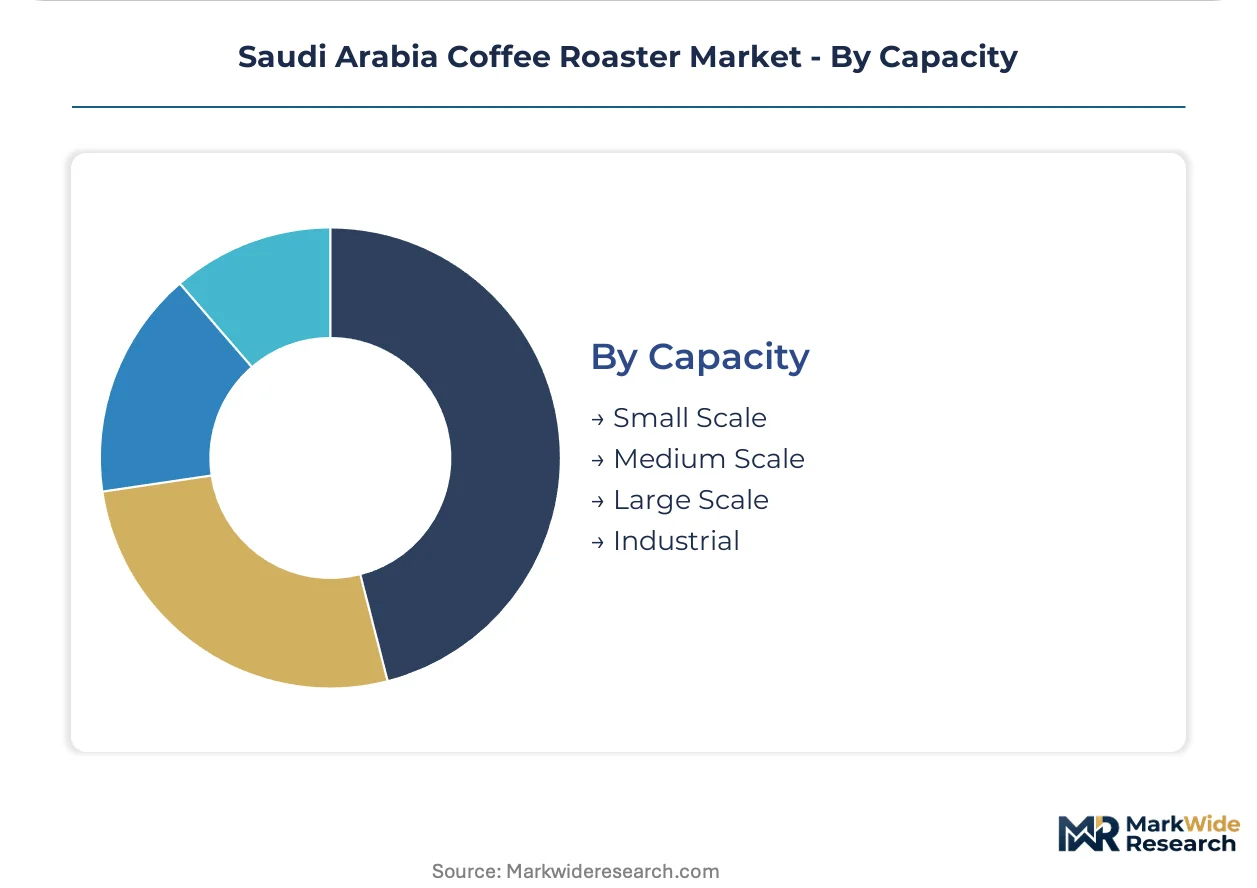
Capacity:
Scale tier determines SASO energy efficiency labeling applicability, SFDA inspection frequency, and import tariff classification.
- Small Scale:Batch capacities below 5kg serving home roasting enthusiasts and micro-roastery proof-of-concept operations, proliferating in Jeddah's Al-Andalus district and Riyadh's Diriyah Gate development.
- Medium Scale:5kg to 30kg batch configurations dominating independent café chains across Riyadh's Al-Malqa corridor, where operators balance production flexibility with capital constraints.
- Large Scale:30kg to 120kg systems triggering SASO energy efficiency compliance costs adding 12-18% to total cost of ownership, concentrated among established roasting houses supplying wholesale accounts.
- Industrial:Continuous roasting configurations exceeding 120kg batch equivalent, limited to Saudi Coffee Company's integrated facilities and multinational processor installations.
Small Scale units lead absolute shipment volumes. Medium Scale installations are climbing the fastest as café chains standardize multi-location roasting programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roastmaster talent concentrates in Riyadh's Al-Malqa district, where vocational training institutes partner with specialty café chains to develop thermal processing expertise. This workforce hub anchors the Central Region's dominance in certified commercial roasting operations.
Central Region
Third-wave café proliferation in Riyadh's Al-Malqa district and Diriyah Gate development drives demand for medium-scale drum and fluid bed installations. SFDA's mandatory equipment certification protocols compress informal operations into licensed supply chains, elevating procurement standards. The capital's specialty coffee corridor hosts the densest concentration of in-house roasting capacity nationwide.
Western Region
Jeddah's Al-Andalus corridor and coastal hospitality sector favor drip roasting systems for single-origin pour-over programs targeting affluent demographics. SASO energy efficiency labeling adds compliance costs for large-scale installations above 30kg batch capacity. Micro-roastery clusters in Jeddah's emerging districts are adopting air-roasting technology for faster batch turnaround.
Eastern Province
Industrial-scale roasting for wholesale distribution concentrates in Dammam and Khobar's logistics corridors serving Bahrain and Qatar export markets. The General Authority for Food Security monitors domestic cultivation trials that will eventually reshape raw material sourcing patterns. Established roasting houses here operate the largest drum roaster fleets in the kingdom.
NEOM Northwest
Experimental hospitality concepts in the giga-project zone are piloting automated profiling systems with centralized production oversight. Regulatory frameworks remain under development as the zone attracts greenfield investment in food processing infrastructure. Early installations prioritize theater-oriented front-of-house roasting displays over production volume.
Jazan Province
Domestic arabica cultivation initiatives led by the General Authority for Food Security will eventually shorten raw material transit distances for Central Region operators. Current roasting infrastructure remains minimal as cultivation scales toward commercial viability. The province's mountainous terrain supports high-altitude coffee planting trials.
Saudi Arabia Coffee Roaster Market Competitive Landscape
Capital-heavy German and Turkish manufacturers compete with asset-light automated profiling specialists for procurement decisions across Saudi café chains. The vendor base splits between premium drum roaster suppliers with decades of engineering heritage and emerging fluid bed technology providers targeting operational simplicity. Three archetypes dominate: heritage European fabricators, automation-focused mid-scale specialists, and vertically integrated domestic operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure SFDA pre-certification status.
Among heritage European fabricators, Probat GmbH and Giesen Coffee Roasters exemplify premium-tier positioning anchored by German and Dutch engineering credentials. Toper occupies a position within the Turkish manufacturing cluster that competes on certified commercial installations. Within the automation-focused tier, Genio Roasters represents mid-scale specialists competing on reduced operator training burdens. Saudi Coffee Company anchors the domestic integrated archetype, controlling supply chains from green bean import through retail roasting. These named entities collectively illustrate how procurement preferences are fragmenting across certification compliance, automation intensity, and vertical integration strategies.
| Leading Market Players |
|---|
| Toper |
| Diedrich Roasters |
| Black Knight Company |
| Probat |
| Genio Roasters |
| Saudi Coffee Company |
| Giesen Coffee Roasters |
| Scolari Engineering |
| Atyab Al-Karam International Company |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed vertical integration by Saudi Coffee Company compresses pricing power for independent roaster operators while elevating procurement discipline across Riyadh's specialty café corridor. This ownership pattern feeds into supply chain decisions that favor pre-certified European equipment over uncertified Turkish alternatives despite euro-denominated cost exposure.
Pricing Analysis
The bundled-versus-unbundled service split distinguishes German heritage suppliers commanding premium installation packages from Turkish manufacturers competing on stripped equipment-only transactions. Three-tier pricing structure across premium drum systems, mid-market fluid bed units, and economy convection configurations reflects SFDA certification grade and after-sales bundling intensity. Pricing pressure stems from SASO energy efficiency labeling adding compliance costs above 30kg batch capacity. Small-scale home roasting segments exhibit highest price sensitivity, while Central Region café chains absorb premiums for automation and origin narrative control.
Supply Chain Analysis
Roastmaster talent scarcity in German and Dutch manufacturing geographies extends lead times for Probat and Giesen installations serving Saudi Arabia's premium tier. Supply concentrates in Turkey for certified mid-market drum systems, Germany for precision-engineered legacy platforms, and South Korea for automated control components. Component dependencies span steel fabrication for drum assemblies, burner systems from Italian suppliers, and profiling software modules. Single-source vulnerability runs through euro-denominated pricing volatility for Central Region operators. Distribution runs through Jeddah's industrial corridor for Western Region micro-roasteries and Riyadh's Al-Malqa logistics hub for Central Region café chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's coffee roaster market functions as a geographic-arbitrage play where Jeddah's coastal positioning offers lower logistics costs for European equipment imports versus Riyadh's inland premium for immediate technical support access.
For Market Incumbents: To counter fluid bed technology displacement of drum system share among new entrants, heritage European fabricators should deepen captive supply of automated profiling software and expand certification consultancy services ahead of SFDA's mandatory HACCP transition. Capacity addition in Turkey's manufacturing cluster reduces euro exposure while maintaining CE-marked quality credentials for Saudi buyers. For New Entrants and Emerging Players: Launch via third-party maintenance unbundling to capture after-sales revenue from mature drum fleets requiring SFDA thermal monitoring upgrades. White-space targets concentrate in Jeddah's Al-Andalus micro-roastery cluster and Diriyah Gate home roasting segments where operational simplicity preferences favor fluid bed technology. Direct-to-café technical training partnerships reduce roastmaster talent scarcity barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale automation specialists lacking SFDA pre-certification status but possessing transferable profiling software IP. Long-term viability hinges on regulatory compliance moats deepening across the analysis window. Acquisition target archetypes include Turkish manufacturers with certified commercial installations and fluid bed technology providers with scalable control platforms. Monitor SFDA's transition timeline from voluntary to mandatory HACCP documentation as inflection indicator for compliance service demand.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Establishes procurement preference windows ahead of mandatory HACCP transition for roasting facilities. |
| Fluid Bed Technology Partnership | Captures share among Jeddah micro-roasteries prioritizing faster batch turnaround and cleaner exhaust profiles. |
| Roastmaster Training Academy | Addresses talent scarcity constraining Central Region café chain expansion and quality consistency. |
| Backward Integration into Green Bean Sourcing | Mirrors Saudi Coffee Company's origin narrative control as Jazan cultivation scales toward commercial viability. |
| Automated Profiling Software Licensing | Reduces operator training burdens for mid-scale Riyadh café chains standardizing multi-location programs. |
Research Methodology
Multiple input streams — structured interviews with roasting equipment procurement managers, secondary validation through SFDA regulatory filings and SASO energy efficiency databases, and trade flow analysis from German and Turkish customs records — were reconciled to construct market estimates. Primary engagement spanned café chain operations directors, aftermarket service technicians in Jeddah's Al-Andalus corridor, and plant engineers at Saudi Coffee Company's integrated facilities. Secondary sources included GSO harmonized standards documentation, commercial appliance import tariff schedules, and technical specifications from CE-marked equipment registries. Bottom-up unit shipment tallies by capacity tier were cross-checked against top-down market value estimates derived from average selling price analysis.
Data-stream reconciliation applied across the projection horizon weighted near-term regulatory compliance costs more heavily than long-term cultivation-driven sourcing shifts. Segmentation dimensions modeled encompassed product type, heat transfer technology, end-user category, and batch capacity tier alongside regional adoption patterns distinguishing Riyadh's third-wave culture from Jeddah's coastal hospitality orientation. CAGRs emerged from logistic growth curve fitting anchored to verified base-year installation data and forward-looking capacity expansion announcements. Industry-specific forecast inputs incorporated SFDA inspection frequency schedules and Jazan Province arabica yield projections from General Authority for Food Security trial data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated SFDA enforcement timelines or sustained euro appreciation against the Saudi riyal. Material deviation in green bean futures volatility or domestic cultivation commercialization schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
RTD Coffee Market
Coffee
Mushroom Coffee Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Green Coffee Market
Coffee
Asia-Pacific Espresso Coffee Market
Coffee
Cold Brew Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Coffee Crystal Market
Coffee
Coffee Capsules Market
Coffee
Encapsulated Caffeine Market
Coffee
Coffee Bags Market
Coffee
Japan Coffee and Tea Capsules Market
Coffee
North America Coffee Market
Coffee
Bioactive Compounds in Coffee Market
Coffee
India Coffee Roaster Market
Coffee
Smart Coffee Maker Market