
 Global Frozen Drink Machines Market | 2026-2036
Global Frozen Drink Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Frozen Drink Machines Market Analysis
Convenience stores is redrawing demand patterns in frozen drink equipment as 24-hour retail formats expand self-serve beverage lanes. Taylor Company dominates commercial-grade soft serve and frozen drink installations through its captive distribution network. Elmeco specializes in granita systems for European café channels where equipment footprint constraints shape purchasing decisions. Bunn-O-Matic Corporation leverages its coffee equipment relationships to cross-sell frozen beverage platforms into convenience store chains.
Frozen drink machines are electromechanical systems combining refrigeration compressors, auger or barrel freezing mechanisms, and dispensing interfaces to produce textured frozen beverages at temperatures between 20°F and 28°F. These units employ either glycol-cooled or air-cooled refrigeration circuits with stainless steel freezing cylinders rated for continuous duty cycles in commercial environments. Slushy machines lead volume sales due to their deployment across convenience store chains, while granita machines command premium positioning in European café and bar segments where beverage customization drives replacement cycles. Soft serve machines concentrate margin pools in dessert applications, though ice blenders are gaining traction in smoothie-focused quick-service formats.
The US FDA Food Code and NSF International sanitation standards govern equipment design for commercial food contact surfaces, while the EU F-Gas Regulation restricts refrigerant types used in new freezing equipment deployed across Europe. China's SAMR enforces GB standards for electrical safety and energy efficiency in imported commercial refrigeration equipment. Stakeholders must monitor refrigerant phase-down schedules and regional energy labeling requirements when configuring product portfolios for multi-territory deployment.
Market Dynamics
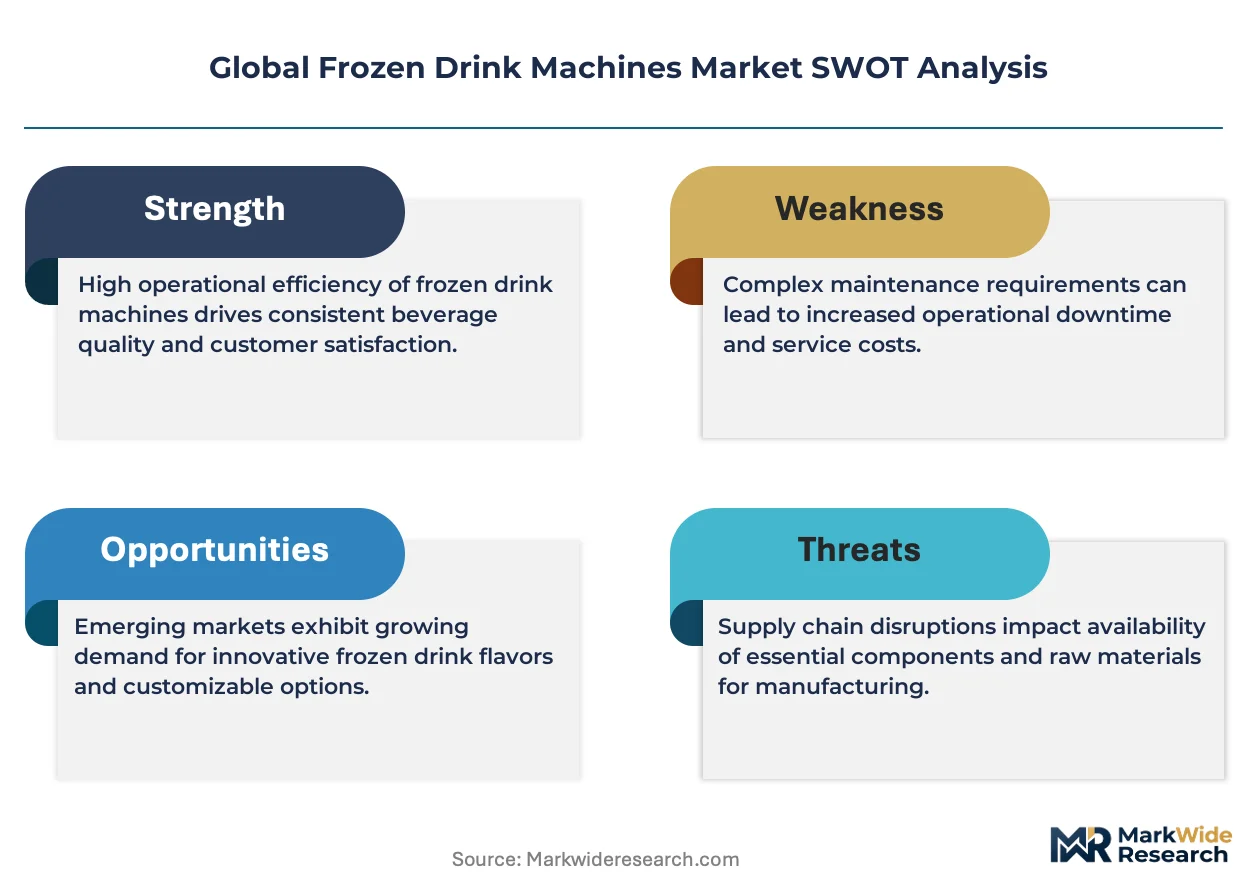
The US FDA's updated Food Code provisions on equipment sanitation are forcing redesigns of dispensing systems across commercial installations, compressing product development cycles and reshaping supplier qualification requirements for frozen drink machine manufacturers.
Growth Catalysts
- Convenience store expansion:24-hour retail formats are accelerating self-serve beverage lane deployments, creating pull for compact, high-throughput frozen drink equipment in the United States and Brazil.
- EU F-Gas Regulation phase-down:Refrigerant transition mandates are stimulating replacement demand as operators retire legacy equipment ahead of compliance deadlines across European café channels.
- Granita format premiumization:Beverage customization trends in European bars are shortening replacement cycles for programmable freezing systems with precision temperature control.
Market Restraints
- Stainless steel input volatility:Freezing cylinder fabrication depends on food-grade stainless steel pricing, exposing manufacturers to commodity swings without long-term hedge coverage.
- Compressor supply concentration:Refrigeration compressor production clusters in East Asian manufacturing hubs, creating single-source vulnerability for air-cooled and glycol-cooled system assemblers.
- NSF International certification friction:Commercial food contact surface standards impose 12-18 month validation timelines that delay product launches and lock out unqualified entrants.
Strategic Opportunities
- Japan's signature format development:Specialty frozen beverage concepts in Japanese convenience retail remain underpenetrated by Western equipment suppliers, creating first-mover positioning for localized product portfolios.
- Ice blender convergence:Smoothie-focused quick-service formats are driving hybrid equipment demand that combines frozen drink freezing with high-shear blending in single-footprint units.
- Cross-channel coffee equipment relationships:Leveraging existing beverage equipment installed bases enables frozen platform penetration into convenience store chains without dedicated cold-beverage procurement teams.
Industry Challenges
- Refrigeration technician scarcity:Commercial compressor servicing requires EPA Section 608 certification in the United States, constraining field service network expansion and extending mean-time-to-repair.
- Legacy glycol system integration:Retrofitting air-cooled equipment into existing bar and café infrastructure demands plumbing reconfiguration that complicates sales cycles and raises total installation cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Frozen Drink Machines Market |
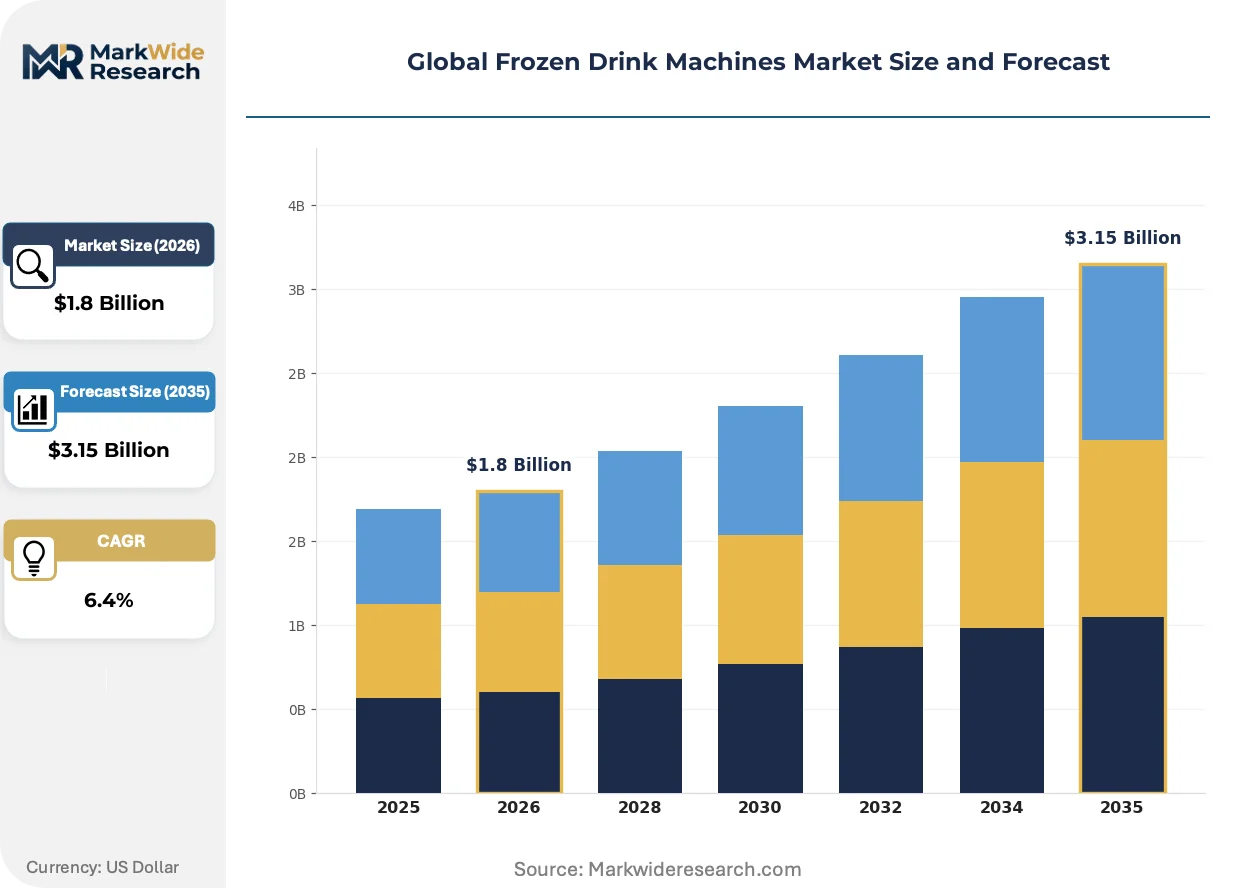
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
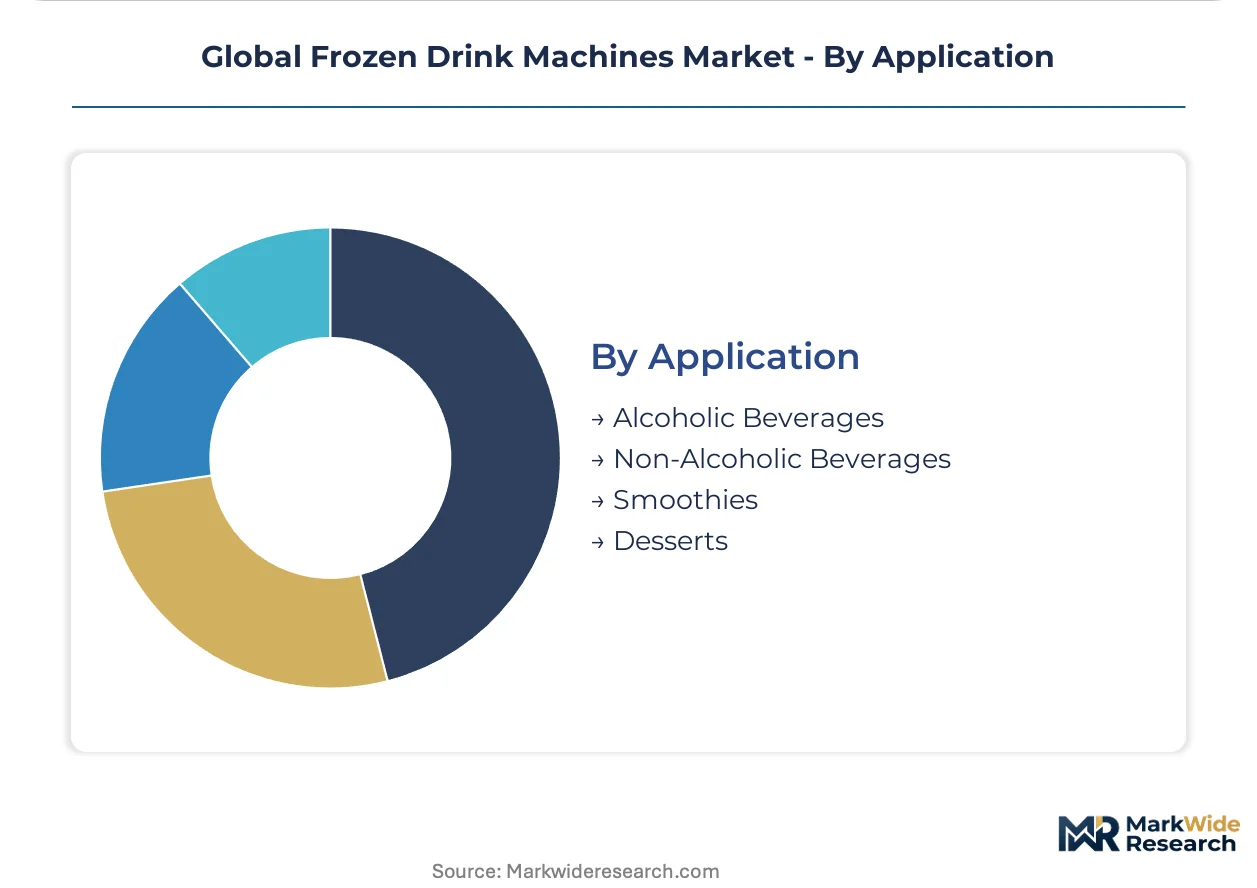
| Segmentation | Product Type: Granita Machines, Slushy Machines, Ice Blenders, Soft Serve Machines End User: Restaurants, Bars, Cafés, Convenience Stores Technology: Refrigeration, Blending, Freezing, Dispensing Application: Alcoholic Beverages, Non-Alcoholic Beverages, Smoothies, Desserts |
| Companies Covered | Taylor Company, Bunn-O-Matic Corporation, Carpigiani Group, Donper America, Electro Freeze, Elmeco, Grindmaster-Cecilware, Jet-Ice, Stoelting Foodservice Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Frozen Drink Machines Market Emerging Trajectories
Equipment footprint reduction and refrigerant chemistry transitions are converging to reshape frozen drink machine architecture, while channel-specific format development is fragmenting previously standardized product categories.
Countertop granita systems with single-barrel configurations are miniaturizing. European café operators with sub-500 square meter footprints are adopting these units at twice the rate of full-size alternatives. This compression is enabling equipment placement in airport kiosks and hotel lobby concessions previously excluded by spatial constraints.
REACH chemical restrictions and the EU F-Gas Regulation are jointly prohibiting hydrofluorocarbon refrigerants in new freezing equipment deployed across Europe. Manufacturers are reformulating cooling circuits around hydrocarbon and CO2 alternatives. Premium granita installations in Germany and France are absorbing the engineering cost premium fastest, while value-tier slushy deployments lag due to price sensitivity.
Convenience store chains are unbundling after-sales service from equipment procurement. Tier-one retailers now negotiate separate maintenance contracts with third-party refrigeration service networks, displacing manufacturer-captive service as the default. This bifurcation is most visible in the United States, where 7-Eleven and Circle K parent entities have established preferred service provider panels independent of original equipment suppliers.
Global Frozen Drink Machines Market Segmentation
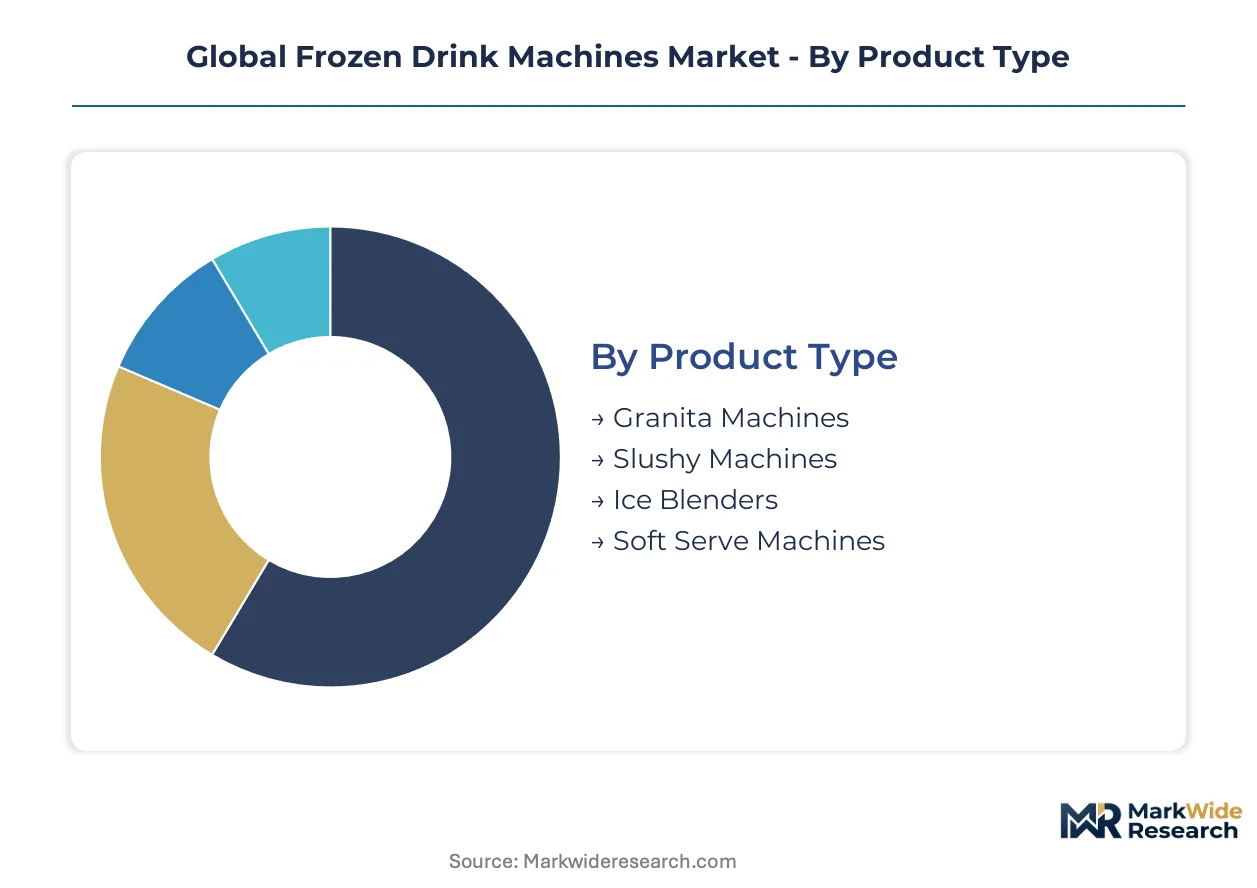
Frozen drink equipment segments diverge sharply by margin profile and technical complexity, with refrigeration-intensive categories commanding premium pricing against simpler blending formats. Channel-specific requirements fragment demand across convenience retail, hospitality, and foodservice verticals with incompatible throughput specifications.
Product Type:
Margin pools concentrate in precision-controlled freezing systems where temperature stability differentiates commercial-grade from entry-tier equipment.
- Granita Machines:These units employ auger-driven freezing cylinders with glycol-cooled circuits to produce crystalline, semi-frozen textures at precise viscosity points. European café operators in France and Italy drive replacement demand for programmable models with multi-recipe memory banks, absorbing 20-30% price premiums for NSF-certified sanitary designs.
- Slushy Machines:Barrel-style freezing systems dominate convenience store deployments across the United States and Brazil, where 24-hour retail formats demand continuous-duty compressors rated for 100,000+ cycle lifespans. Self-serve lane expansions at 7-Eleven and Circle K parent entities are pulling compact twin-barrel configurations that maximize throughput per linear foot of counter space.
- Ice Blenders:High-shear blade systems with frozen drink integration are gaining traction in smoothie-focused quick-service formats.
- Soft Serve Machines:Dessert-focused freezing systems with overrun control concentrate margin pools in frozen yogurt and ice cream applications.
The dominant share belongs to Slushy Machines, while Granita Machines are closing the gap fastest through European premiumization.
End User:
Volume concentration tracks retail format expansion, with 24-hour convenience channels outpacing traditional hospitality in unit deployment velocity.
- Restaurants:Full-service dining operators deploy frozen drink equipment primarily for dessert and beverage program differentiation, favoring under-counter configurations that preserve front-of-house aesthetics. Chains with 50+ unit footprints negotiate fleet pricing through equipment finance programs.
- Bars:Cocktail-focused establishments in Japan and Spain are driving demand for precision granita systems that enable frozen margarita and daiquiri consistency across high-turnover service windows.
- Cafés:European independent operators with sub-500 square meter footprints are adopting single-barrel countertop granita units at twice the rate of full-size alternatives.
- Convenience Stores:Self-serve beverage lanes at 7-Eleven, Circle K, and OXXO locations across the United States, Brazil, and Mexico are accelerating deployments of compact high-throughput equipment with cashless payment integration.
Convenience Stores capture the largest installed base, though Bars are expanding frozen beverage programs most aggressively.
Technology:
Supply-side specialization fragments along thermal management versus mechanical processing boundaries, with refrigeration commanding the deepest technical moats.
- Refrigeration:Compressor-based cooling circuits—glycol-cooled for precision applications, air-cooled for cost-sensitive deployments—constitute the highest-value subsystem, with stainless steel freezing cylinder fabrication requiring food-grade metallurgy certification. EU F-Gas Regulation phase-downs are forcing refrigerant chemistry transitions to hydrocarbon and CO2 alternatives.
- Blending:High-shear blade systems with variable speed control enable texture modulation for smoothie and frozen coffee applications, converging with freezing functions in hybrid equipment formats.
- Freezing:Auger and barrel mechanisms transform liquid bases into textured frozen states, with auger designs preferred for granita crystalline structure and barrel systems dominant in slushy applications.
- Dispensing:Sanitary valve and tap configurations are undergoing redesign to comply with FDA Food Code updated provisions on equipment sanitation, compressing product development cycles.
Refrigeration technology anchors the value stack, while Dispensing systems are seeing the most rapid architectural change.
Application:
Format development creates channel-specific equipment requirements that resist standardization, with alcoholic beverage applications demanding regulatory-compliant sanitary designs.
- Alcoholic Beverages:Frozen cocktail production requires equipment with alcohol-tolerant seals and accelerated freezing algorithms to handle ethanol's depression of freezing points. Japanese bars and Spanish hospitality venues are developing signature frozen sake and sangria formats that drive specialized equipment procurement.
- Non-Alcoholic Beverages:Carbonated slushy systems dominate convenience store deployments, with flavor syrup integration and post-mix carbonation requiring dedicated dispensing architecture.
- Smoothies:Health-focused quick-service formats are pulling hybrid equipment that combines frozen fruit processing with high-shear blending in single-footprint units.
- Desserts:Soft serve and frozen yogurt applications concentrate in dedicated dessert chains and restaurant dessert programs, with overrun control and swirl pattern capabilities differentiating premium from economy tiers.
Non-Alcoholic Beverages hold the broadest installed base, though Smoothies are climbing the fastest as quick-service health positioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy exports precision granita systems to France and Spain, while the United States ships high-volume slushy machines to Brazil and Mexico. Trade corridors concentrate refrigeration-intensive equipment from manufacturing clusters in Lombardy and Michigan toward convenience retail expansion zones.
United States
7-Eleven and Circle K parent entities are accelerating self-serve beverage lane deployments across 24-hour formats. The FDA's updated Food Code provisions on equipment sanitation are compressing product development cycles for dispensing system redesigns. Equipment manufacturing clusters in Michigan and Ohio supply compressed refrigeration systems for domestic convenience store chains.
Brazil
OXXO and local convenience store operators are expanding frozen beverage programs faster than traditional foodservice channels. ANVISA enforces sanitary standards for commercial food contact surfaces that align with NSF International certification requirements. São Paulo-based equipment distributors are retrofitting air-cooled systems into existing retail infrastructure.
Japan
Specialty frozen beverage concepts in convenience retail remain underpenetrated by Western equipment suppliers. METI oversees energy efficiency labeling requirements for commercial refrigeration equipment under Top Runner standards. Tokyo and Osaka metropolitan areas are developing signature frozen sake formats that demand precision temperature control systems.
Germany
The EU F-Gas Regulation phase-down is stimulating replacement demand as café operators retire legacy equipment ahead of compliance deadlines. ECHA administers REACH chemical restrictions that jointly prohibit hydrofluorocarbon refrigerants in new freezing equipment. Bavarian equipment fabricators are reformulating cooling circuits around hydrocarbon and CO2 alternatives for granita installations.
France
Beverage customization trends in Parisian bars are shortening replacement cycles for programmable freezing systems. The EU F-Gas Regulation mandates refrigerant transitions that premium granita installations are absorbing fastest. Lyon and Marseille hospitality clusters are driving procurement of precision-controlled granita systems with multi-recipe memory banks.
Global Frozen Drink Machines Market Vendor Landscape
Player mix skews toward diversified foodservice equipment conglomerates with captive distribution networks. Market structure concentrates around three to four integrated manufacturers controlling commercial-grade installation channels. Strategic archetypes include refrigeration-centric specialists, beverage equipment diversifiers, and dessert-focused freezing system providers. Competitive moves center on cross-selling frozen platforms into existing coffee equipment relationships and geographic expansion through localized product portfolios.
Among Italian specialists, Carpigiani Group and Elmeco occupy positions within the precision granita tier, leveraging European café channel expertise to command premium positioning. Taylor Company anchors the high-volume commercial segment through integrated soft serve and frozen drink installations. Bunn-O-Matic Corporation exemplifies the beverage equipment diversifier archetype, leveraging existing relationships to cross-sell frozen platforms into convenience store chains without dedicated cold-beverage procurement teams.
| Leading Market Players |
|---|
| Taylor Company |
| Bunn-O-Matic Corporation |
| Carpigiani Group |
| Donper America |
| Electro Freeze |
| Elmeco |
| Grindmaster-Cecilware |
| Jet-Ice |
| Stoelting Foodservice Equipment |
| Others |
Supply Flow & Price Mechanics
NSF International certification timelines gate both supplier qualification and price differentiation simultaneously, compressing development cycles for unqualified entrants while enabling certified manufacturers to command 20-30% premiums on sanitary-design equipment. This regulatory filter concentrates pricing power among established players with validated freezing cylinder fabrication capabilities.
Pricing Analysis
Next-generation hydrocarbon and CO2 refrigerant systems carry 15-25% cost premiums over legacy hydrofluorocarbon equipment, while prior-generation glycol-cooled units trade at discounts in secondary markets. Three-tier pricing structure across premium programmable granita systems, standard slushy barrel configurations, and economy ice blender formats separates NSF-certified sanitary designs from basic commercial-grade alternatives. Pricing pressure stems from stainless steel input volatility and compressor supply concentration, squeezing margins on mid-tier equipment. Convenience store chains exhibit highest price sensitivity due to volume procurement and unbundled service contracts, while European café operators absorb premiums for precision temperature control.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes are elevating inbound logistics costs for refrigeration compressor shipments from East Asian manufacturing hubs. Production clusters in China, South Korea, and Japan anchor compressor supply for air-cooled and glycol-cooled system assemblers, while food-grade stainless steel for freezing cylinder fabrication draws from specialized metallurgy suppliers in Germany and the United States. Single-source vulnerability in compressor procurement creates structural risk for equipment manufacturers without dual-qualified supplier bases. Distribution runs through captive dealer networks for commercial-grade installations and third-party refrigeration service panels for convenience store chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as EU F-Gas Regulation compliance deadlines force replacement demand across European café and bar channels.
For Market Incumbents: Secure refrigerant transition leadership by accelerating hydrocarbon and CO2 cooling circuit certification ahead of 2025-2030 phase-down milestones. Lock in long-term stainless steel supply agreements with metallurgy-certified foundries to hedge commodity volatility. Defend against emerging Asian equipment entrants by deepening captive service network density in convenience store channels where third-party maintenance contracts are displacing manufacturer-provided support. For New Entrants and Emerging Players: Anchor in Japan's underpenetrated convenience retail segment, where specialty frozen sake and signature beverage concepts lack Western equipment supplier coverage. Target single-barrel countertop granita configurations for European independent cafés with sub-500 square meter footprints, a segment adopting compact units at twice the rate of full-size alternatives. Pursue white-label manufacturing partnerships with established coffee equipment distributors to bypass direct cold-beverage procurement team access barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerant-transitioning equipment sub-segments as engineering costs for hydrocarbon and CO2 alternative systems compress returns on legacy product lines. Five-to-ten year viability favors manufacturers with backward integration into compressor sourcing or freezing cylinder fabrication. Target acquisition candidates with established NSF certification portfolios and installed base density in convenience store chains. Monitor EU F-Gas Regulation enforcement acceleration as the key inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Chemistry Transition | EU F-Gas Regulation mandates hydrocarbon and CO2 alternatives, absorbing engineering premiums fastest in German and French granita installations. |
| Equipment Footprint Miniaturization | Single-barrel countertop configurations unlock airport kiosks and hotel lobby concessions previously excluded by spatial constraints. |
| After-Sales Service Unbundling | Tier-one retailers like 7-Eleven and Circle K now negotiate separate maintenance contracts, displacing manufacturer-captive service as default. |
| Cashless Payment Integration | Self-serve beverage lane deployments at OXXO and convenience chains require dispensing architecture compatible with digital transaction systems. |
| Cross-Channel Coffee Equipment Leverage | Bunn-O-Matic's existing relationships enable frozen platform penetration into chains without dedicated cold-beverage procurement teams. |
Methodological Framework
Desk research of trade publications, customs records, and NSF International certification databases preceded structured interviews with equipment manufacturing executives, convenience store procurement directors, refrigeration service network operators, and European café chain operators. Primary fieldwork across the United States, Brazil, Germany, France, and Japan validated secondary findings on refrigerant transition timelines and channel-specific format preferences. Bottom-up unit deployment estimates triangulated against top-down market value reconstructions from equipment finance program disclosures.
Variance decomposition across product type, end-user channel, cooling technology, and geographic regulatory cluster shaped the analytical framework. Modeled segmentation tracked granita, slushy, ice blender, and soft serve equipment categories against convenience store, bar, café, and restaurant deployment patterns. CAGRs derived from replacement cycle analysis, format expansion rates, and regulatory compliance deadline impacts. Refrigerant phase-down schedules and stainless steel price indices served as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued EU F-Gas Regulation enforcement, stable convenience store format expansion, and no catastrophic compressor supply disruptions; material deviation would warrant model refresh. Forecasts reflect base-case assumptions on certification timeline friction and commodity input volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Scroll Chiller Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Global QSR Food Service Equipment Market
Food Service Equipment
Electric Commercial Deep Fryers Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Europe Commercial Dishwashers Market
Food Service Equipment
UK Countertop Ice Makers Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
France Smokeless Indoor Grills Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Specialty Commercial Deep Fryers Market