
 United Kingdom Ready-To-Drink (RTD) Coffee Market | 2026-2036
United Kingdom Ready-To-Drink (RTD) Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Ready-To-Drink (RTD) Coffee Market Analytics
BRC Food Safety Certification is rotating as the baseline qualification for shelf placement in British grocery retail, filtering which suppliers gain nationwide listings. Starbucks Corporation leverages its licensed manufacturing partnerships to secure premium chiller space in Tesco and Sainsbury's. Nestlé S.A. anchors volume through Nescafé-branded RTD lines distributed via broad retail networks. The Coca-Cola Company competes through its Costa Coffee acquisition, extending coffee shop credibility into grab-and-go formats.
United Kingdom Ready-To-Drink Coffee comprises chilled or ambient single-serve beverages containing brewed coffee extract, typically preserved through pasteurization or high-pressure processing, with milk proteins, sweeteners, and stabilizers adjusted for shelf stability and sensory replication of fresh preparation. Cold Brew segments lead margin pools due to extended steeping cycles and perceived craft credentials justifying price premiums above Latte formulations. Online Retailers represent the fastest-growing distribution channel as British consumers shift replenishment toward subscription models and rapid delivery platforms. Supermarkets retain volume dominance but face share erosion from Convenience Stores expanding chiller capacity in transport hubs and city centers.
The Food Standards Agency monitors caffeine content declarations while the Competition and Markets Authority scrutinizes shelf slotting fees that disadvantage emerging entrants. Plastic Packaging Tax regulations from HM Revenue and Customs push manufacturers toward rPET or aluminum can formats, altering cost structures and supplier qualifications. Stakeholders must weigh whether to prioritize reformulation investments for sugar reduction targets or channel expansion into direct-to-consumer platforms before regulatory thresholds tighten further.
Market Dynamics
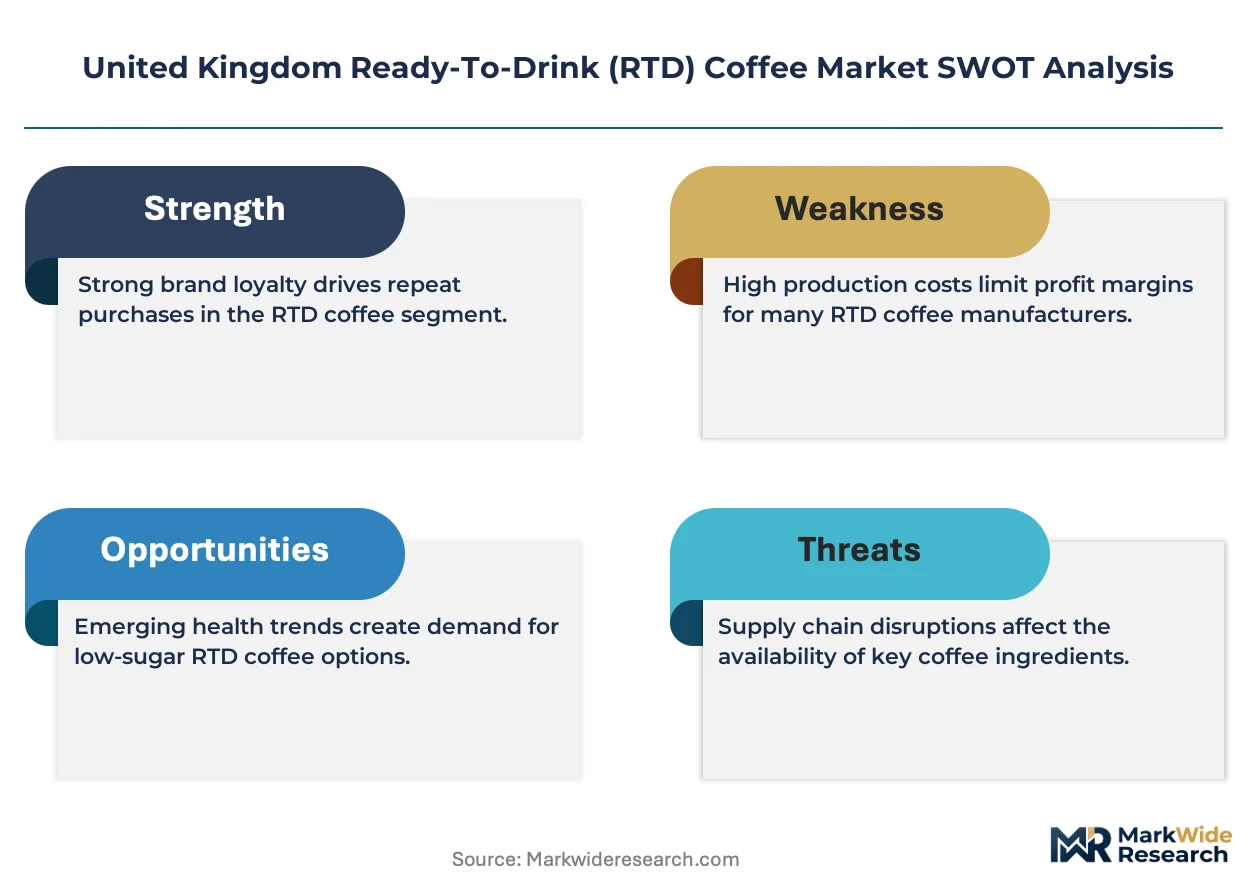
The United Kingdom RTD Coffee Market pivots on the Food Standards Agency's tightening caffeine labeling mandates and HM Revenue and Customs' Plastic Packaging Tax, which together force simultaneous reformulation and packaging reinvestment across British manufacturing footprints.
Growth Catalysts
- Commuter Channel Expansion:Convenience Stores in London transport hubs are installing dedicated chiller banks for grab-and-go coffee, capturing impulse purchases from rail and Underground passengers.
- Sugar Reduction Targets:The UK government's reformulation incentives push manufacturers toward naturally sweetened cold brew formulations that satisfy clean-label preferences without artificial substitutes.
- High-Pressure Processing:Cold pasteurization technology extends ambient shelf life while preserving volatile aromatic compounds that differentiate premium RTD lines from retort-stable commodity offerings.
Market Restraints
- Arabica Price Volatility:London ICE futures contract swings for washed arabica directly compress gross margins on latte-formulation SKUs that carry higher milk solids ratios.
- Rigid Packaging Conversion Costs:Shifting from virgin PET to rPET or aluminum cans requires capital outlays that filter smaller regional bottlers from Tesco and Sainsbury's supplier pools.
- Competition and Markets Authority Scrutiny:Shelf slotting fee investigations create listing uncertainty for emerging entrants negotiating nationwide distribution with British grocery multiples.
Strategic Opportunities
- Subscription Replenishment Models:Online Retailers in Greater Manchester and Birmingham are capturing recurring revenue through direct-to-consumer cold brew concentrate deliveries.
- Extended Steeping Cold Brew:Twenty-four-hour ambient extraction methods command price premiums in premium chiller placements at Waitrose and Marks & Spencer food halls.
- Deposit Return Scheme Alignment:Scotland's forthcoming beverage container deposit framework creates first-mover advantage for aluminum can formats ahead of England and Wales implementation.
Industry Challenges
- BRC Food Safety Certification Timelines:Version 9 audit requirements demand documented allergen control plans that delay new supplier onboarding by four to six months.
- Refrigerated Last-Mile Infrastructure:Cold chain integrity failures in summer peak periods generate write-offs for ambient-stocked convenience operators lacking chiller redundancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Ready-To-Drink (RTD) Coffee Market |
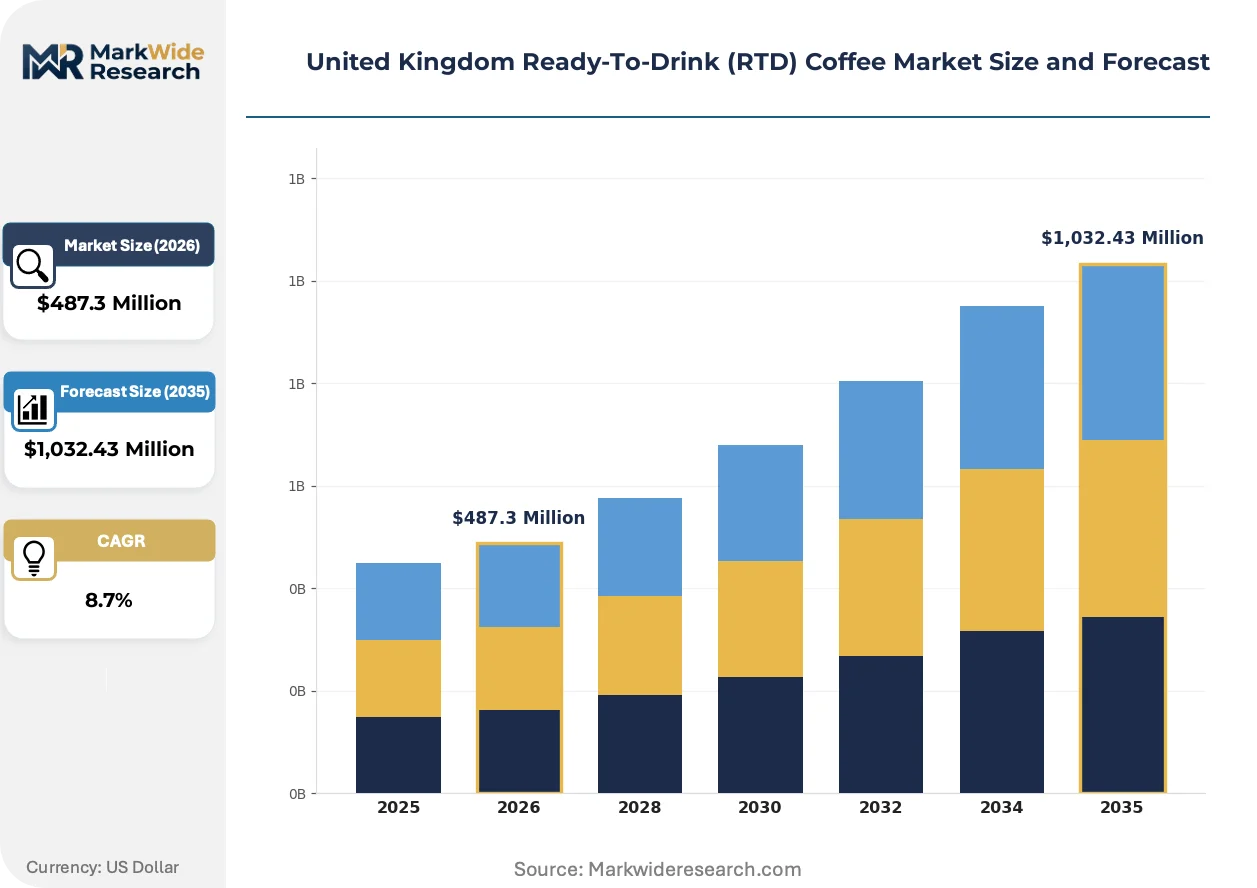
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Brew, Espresso, Latte, Mocha Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Cafes Price Tier: Premium, Mid-range, Economy, Value Consumer Age Group: 18-24, 25-34, 35-44, 45+ |
| Companies Covered | Starbucks Corporation, The Coca-Cola Company, Nestlé S.A., Luigi Lavazza S.p.A., Carlsberg Group, Emmi AG, Danone S.A., Illycaffè S.p.A., Suntory Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Ready-To-Drink (RTD) Coffee Market Evolving Landscape
Reformulation chemistry and packaging substrate selection dominate British RTD Coffee innovation cycles as manufacturers balance sensory fidelity against regulatory compliance deadlines.
Nitrogen dosing technology is supplanting traditional carbonation in cold brew formats, creating cascading visual cues and creamy mouthfeel without dairy solids. Manchester-based coffee roasters and London café chains are adopting nitrogen lines for draft-style RTD cans at pace. This shift is compressing the addressable market for conventional still cold brew while expanding premium price bands.
The Plastic Packaging Tax from HM Revenue and Customs mandates minimum thirty percent recycled content in plastic vessels, forcing converters toward rPET sourcing agreements or aluminum migration. British grocery multiples are delisting virgin PET SKUs that fail compliance thresholds ahead of enforcement dates. Chilled RTD Coffee in aluminum cans is capturing shelf space fastest in Sainsbury's Local and Tesco Express formats.
Urban millennials in London and Manchester are consolidating replenishment through rapid delivery platforms rather than weekly supermarket shops. Gorillas, Getir, and Zapp dark-store networks are displacing traditional convenience store foot traffic for impulse coffee purchases. This channel rotation is most pronounced in Zone 1-2 London postcodes where fifteen-minute delivery promises match commuter break schedules.
United Kingdom Ready-To-Drink (RTD) Coffee Market Segmentation
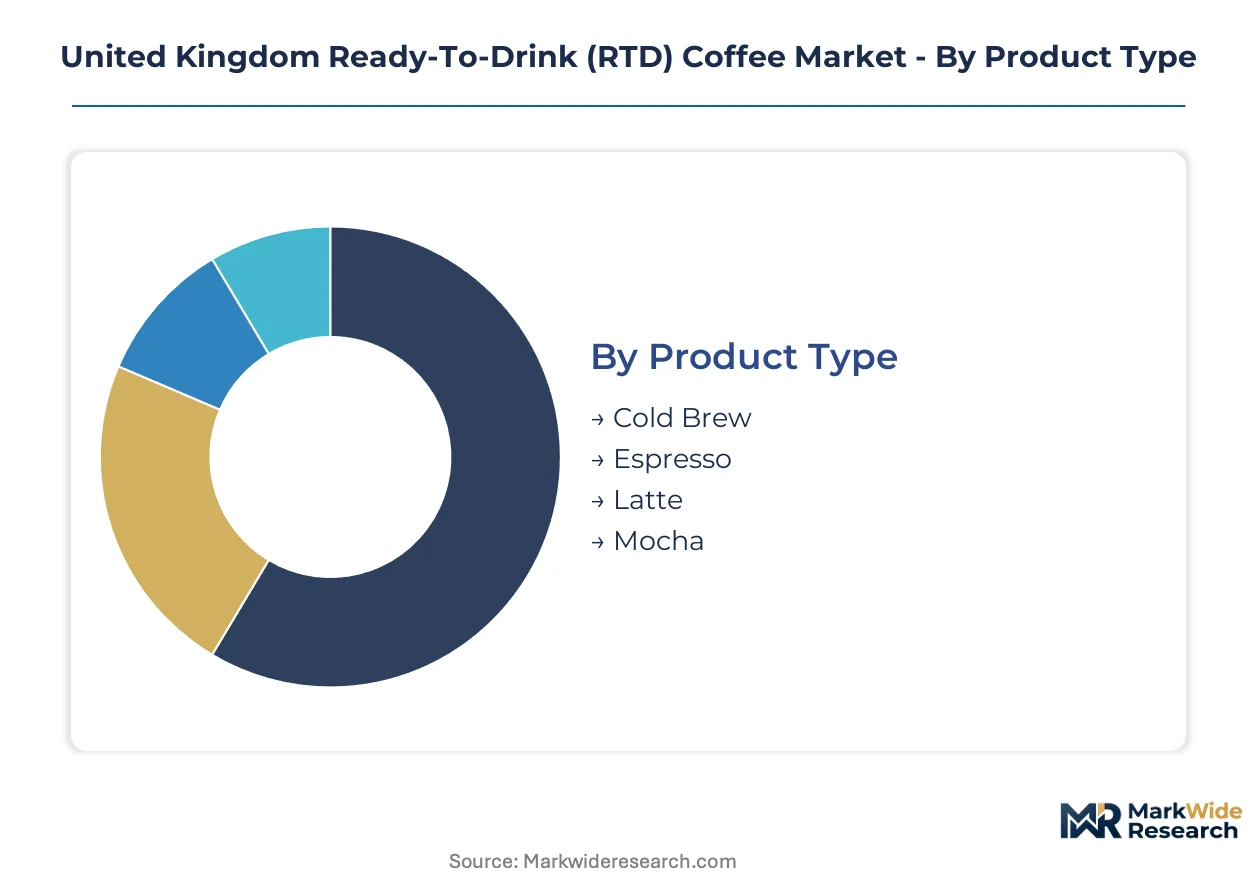
RTD Coffee manufacturers in the United Kingdom calibrate portfolio depth across four intersecting dimensions. Cold brew extraction methods and chiller placement economics create divergent margin profiles within product categories, while age-cohort targeting determines formulation sweetness and caffeine positioning.
Product Type:
Premium margin pools concentrate in extended-steep cold brew lines where twenty-four-hour ambient extraction justifies shelf price premiums above dairy-based formulations.
- Cold Brew:Extended ambient steeping cycles extract volatile aromatic compounds without thermal degradation. Manchester roasters and London café chains are adopting nitrogen dosing systems for draft-style cans that command placement in Waitrose and Marks & Spencer premium chillers.
- Latte:Milk protein stabilization and retort pasteurization dominate this high-volume segment. Arabica price volatility from London ICE futures directly compresses gross margins on SKUs carrying higher milk solids ratios.
- Espresso:Concentrated coffee extract formulations target intensity-seeking consumers. Birmingham convenience stores are expanding chiller banks for single-serve espresso cans in transport hub locations.
- Mocha:Cocoa-coffee blends appeal to transitional consumers entering the category. Reformulation pressures from Food Standards Agency sugar reduction targets are forcing cocoa supplier switches.
Latte holds installed capacity. Cold Brew is rotating up the share rankings.
Distribution Channel:
Volume concentration sits with grocery multiples, yet capital efficiency is climbing fastest in rapid-delivery dark stores that bypass traditional wholesale markups.
- Supermarkets:Tesco and Sainsbury's control nationwide chiller placement through BRC Food Safety Certification gatekeeping. Shelf slotting fee investigations by the Competition and Markets Authority are creating listing uncertainty for emerging entrants negotiating nationwide distribution.
- Online Retailers:Subscription replenishment models through Gorillas, Getir, and Zapp dark-store networks are displacing traditional convenience foot traffic. Zone 1-2 London postcodes show the steepest expansion trajectory where fifteen-minute delivery promises match commuter break schedules.
- Convenience Stores:Transport hub locations in London and Manchester are installing dedicated chiller banks for grab-and-go impulse purchases. Refrigerated last-mile infrastructure gaps in summer peak periods generate write-offs for operators lacking chiller redundancy.
- Cafes:Costa Coffee and licensed Starbucks locations extend coffee shop credibility into branded RTD grab-and-go formats. On-premise consumption licensing creates channel conflict with retail-bound product lines.
Supermarkets hold installed capacity. Online Retailers are gaining share fastest.
Price Tier:
Cost tier stratification aligns with packaging substrate compliance costs, where rPET and aluminum conversion investments filter regional bottlers from premium placement eligibility.
- Premium:Extended steep cold brew and nitrogen-dosed formats with minimum thirty percent recycled content packaging. HM Revenue and Customs Plastic Packaging Tax mandates are delisting virgin PET SKUs that fail compliance thresholds.
- Mid-range:Standard pasteurized latte and mocha lines in hybrid retail-convenience distribution. This tier absorbs the highest volume of sugar reformulation investment to meet government reduction targets.
- Economy:Retort-stable commodity offerings with simplified stabilizer systems. Margin compression from arabica futures volatility is forcing SKU rationalization in this tier.
- Value:Private-label lines for Aldi and Lidl price-positioning. BRC Food Safety Certification Version 9 audit requirements demand documented allergen control plans that delay new supplier onboarding.
Premium holds installed capacity. Mid-range is rotating up the share rankings.
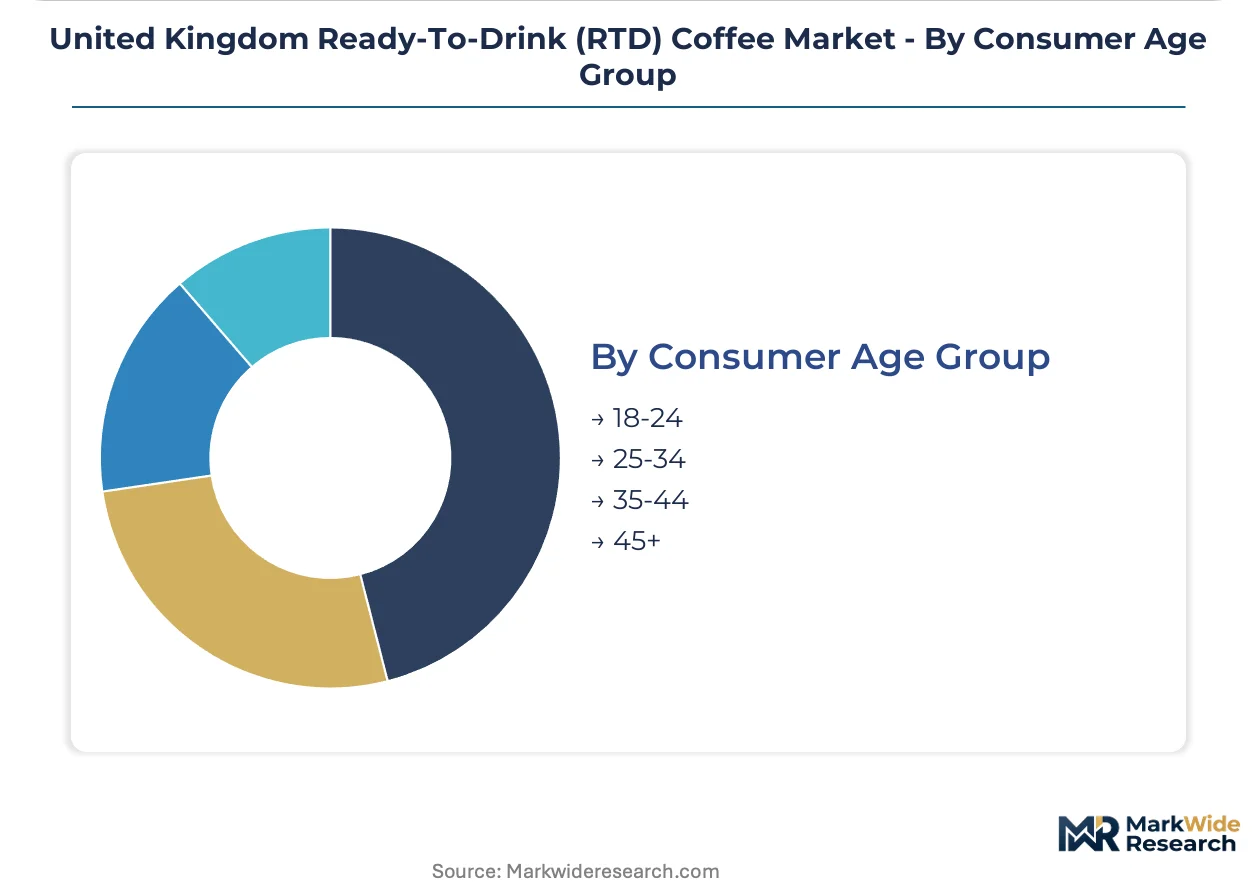
Consumer Age Group:
Cohort targeting intensity peaks among urban millennials whose replenishment patterns through rapid delivery platforms are reshaping channel economics.
- 25-34:Core urban millennial segment consolidating purchases through subscription and rapid delivery. Clean-label preferences drive naturally sweetened cold brew adoption without artificial substitutes.
- 18-24:Entry-level consumers responding to visual nitrogen cascade cues and social media positioning. Price sensitivity limits penetration to promotional cycles and value-tier SKUs.
- 35-44:Established routine purchasers with weekly supermarket replenishment habits. This cohort shows highest loyalty to traditional latte and mocha formulations.
- 45+:Caffeine-conscious segment influencing Food Standards Agency labeling mandate tightening. Decaffeinated and half-caff line extensions target this demographic.
35-44 holds installed capacity. 25-34 is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HM Revenue and Customs' Plastic Packaging Tax is redistributing manufacturing investment toward Scotland and England's industrial corridors as suppliers race to meet recycled-content thresholds ahead of enforcement deadlines.
London and Southeast
Zone 1-2 postcodes drive the fastest channel shift toward Gorillas, Getir, and Zapp dark-store networks where fifteen-minute delivery promises match commuter break schedules. The Food Standards Agency's caffeine labeling mandates hit formulation labs in Slough and Reading first. Nitrogen-dosed cold brew canning lines cluster along the M4 corridor serving Waitrose and Marks & Spencer premium chiller placements.
Midlands
Birmingham convenience stores are expanding chiller banks for single-serve espresso cans in New Street Station and Bullring transport hubs. Competition and Markets Authority scrutiny of shelf slotting fees creates listing uncertainty for emerging entrants negotiating with West Midlands grocery multiples. Coventry and Leicester host contract manufacturing facilities serving private-label Aldi and Lidl lines.
North England
Manchester roasters are adopting nitrogen dosing systems for draft-style RTD cans targeting urban millennial replenishment patterns. BRC Food Safety Certification Version 9 audit requirements delay new supplier onboarding by four to six months across Yorkshire and Lancashire manufacturing footprints. Leeds and Bradford cold brew concentrate subscription models capture recurring revenue through direct-to-consumer platforms.
Scotland
Scotland's forthcoming beverage container deposit framework creates first-mover advantage for aluminum can formats ahead of England and Wales implementation. Glasgow and Edinburgh transport hubs are installing dedicated chiller banks for grab-and-go impulse purchases. Scottish bottlers are converting virgin PET lines to rPET sourcing agreements to meet HM Revenue and Customs compliance thresholds.
Wales
South Wales manufacturing corridors face refrigerated last-mile infrastructure gaps during summer peak periods that generate write-offs for ambient-stocked convenience operators. Cardiff convenience stores are expanding chiller capacity in central transport nodes. Welsh suppliers are prioritizing reformulation investments for Food Standards Agency sugar reduction targets over channel expansion into direct-to-consumer platforms.
United Kingdom Ready-To-Drink (RTD) Coffee Market Competitive Landscape
Player mix skews toward multinational beverage conglomerates with licensed coffee shop partnerships and Swiss-German dairy-coffee hybrid specialists. Three structural tiers have crystallized: coffee shop brand licensors commanding premium chiller space, packaged goods multinationals anchoring volume through broad retail networks, and regional dairy processors extending into functional coffee lines. Dominant competitive moves include strategic licensing agreements with café chains and packaging substrate conversion investments to satisfy Plastic Packaging Tax thresholds.
Within the multinational beverage tier, Starbucks Corporation and The Coca-Cola Company exemplify divergent entry strategies—one leveraging coffee shop credibility into retail-bound formats, the other extending soft drink distribution muscle into grab-and-go coffee. Nestlé S.A. anchors the packaged goods vector through Nescafé-branded lines. Among European specialists, Luigi Lavazza S.p.A. and Illycaffè S.p.A. occupy positions emphasizing Italian espresso heritage in premium shelf placements.
| Leading Market Players |
|---|
| Starbucks Corporation |
| The Coca-Cola Company |
| Nestlé S.A. |
| Luigi Lavazza S.p.A. |
| Carlsberg Group |
| Emmi AG |
| Danone S.A. |
| Illycaffè S.p.A. |
| Suntory Holdings Limited |
| Others |
Value Network & Pricing Analysis
Chilled distribution capacity utilization across British grocery multiples creates scale thresholds that filter regional bottlers from premium shelf access while anchoring price floors for compliant formats. HM Revenue and Customs' Plastic Packaging Tax mandates thirty percent recycled content minimums, forcing capital-intensive substrate conversions that concentrate supply among multinationals with rPET sourcing agreements or aluminum can migration capabilities.
Pricing Analysis
Certification level creates the primary spread, with BRC Food Safety Certification Version 9 compliance separating premium chiller placements at Waitrose and Marks & Spencer from economy-tier ambient listings. Three-tier pricing structure across premium, standard, and economy levels reflects packaging substrate compliance costs and extraction method complexity. Cost compression in economy-tier retort-stable lines is intensifying because arabica futures volatility from London ICE contracts squeezes milk solids-heavy latte formulations. Price-sensitive entry-level consumers aged 18-24 limit penetration to promotional cycles, while premium cold brew commands inelastic demand from urban millennials.
Supply Chain Analysis
Brazil and Vietnam anchor green coffee bean supply, with washed arabica futures pricing through London ICE directly feeding British formulation cost structures. High-pressure processing equipment and nitrogen dosing systems draw from German and Italian engineering specialists. Single-source vulnerability sits with rPET flake supply concentrated among European recyclers. Distribution runs through Tesco and Sainsbury's nationwide chiller networks, with rapid-delivery dark stores displacing wholesale markups in Zone 1-2 London postcodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment models represent a service-attach opportunity expanding faster than hardware, with recurring cold brew concentrate deliveries capturing lifetime value beyond single-transaction retail economics.
For Market Incumbents: Secure BRC Food Safety Certification Version 9 audit completion ahead of supplier pool consolidation, defending premium chiller placement against emerging entrants facing four-to-six-month onboarding delays. Anchor aluminum can format capacity in Scotland to capture first-mover advantage under the forthcoming beverage container deposit framework, locking out competitors awaiting England and Wales implementation timelines. For New Entrants and Emerging Players: Anchor in Leeds and Bradford cold brew concentrate subscription models, exploiting direct-to-consumer platform economics that bypass Tesco and Sainsbury's slotting fee investigations. Target transport hub convenience stores in Birmingham New Street Station and Manchester Piccadilly, where chiller bank expansion captures impulse commuter purchases with lower listing barriers than nationwide grocery multiples. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among roasters with nitrogen-dosed canning lines and established rapid-delivery partnerships, offering visibility through subscription retention metrics rather than promotional cycle dependency. Acquisition target archetype: Manchester-based specialty roasters with extended steep extraction capabilities and clean-label formulation credentials. Watch Scotland's deposit scheme implementation velocity as inflection indicator for aluminum format adoption rates across Britain.| Strategic Initiative | Industry Significance |
|---|---|
| Nitrogen Dosing Technology Adoption | Draft-style cold brew cans command Waitrose and Marks & Spencer premium placement. |
| Aluminum Can Format Migration | Scotland's deposit scheme creates first-mover positioning ahead of England implementation. |
| Subscription Platform Integration | Gorillas and Getir dark-store networks displace traditional convenience foot traffic. |
| BRC Version 9 Certification Investment | Documented allergen control plans filter supplier pools for Tesco and Sainsbury's. |
| Sugar Reformulation Chemistry | Food Standards Agency targets force natural sweetener adoption without artificial substitutes. |
Research Methodology
Operator-level perspectives from category buyers at Tesco and Sainsbury's, supply planners at chilled distribution networks, and regulatory affairs leads navigating Food Standards Agency mandates anchored the qualitative base. Secondary validation drew from HM Revenue and Customs Plastic Packaging Tax guidance documents, Competition and Markets Authority shelf slotting fee investigation records, and London ICE futures contract data. Bottom-up SKU-level volume builds triangulated against top-down grocery multiple chiller placement audits.
Sensitivity analysis tested arabica price volatility bands and regulatory compliance timeline scenarios across the analysis window. Segmentation dimensions modeled include product type, distribution channel, price tier, and consumer age cohort, with regional regulatory clusters capturing Scotland's deposit scheme divergence. CAGRs derived from historical trajectory fitting against announced capacity investments and channel shift elasticity parameters.
Material uncertainties — arabica futures contract swings, BRC audit backlog delays, and rapid-delivery platform consolidation outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and consumer channel migration stickiness. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
South America Coffee Market
Coffee
Coffee Crystal Market
Coffee
Green Coffee Extract Market
Coffee
Latin America Coffee Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Stove Top Moka Coffee Pot Market
Coffee
Coffee Premixes Market
Coffee
Take Out Coffee Market
Coffee
Middle East and Africa Coffee Market
Coffee
Roast to Order Coffee Market
Coffee
Espresso Coffee Market
Coffee
North America Ready-To-Drink (RTD) Coffee Market
Coffee
Coffee Brewers Market
Coffee
Cold Brew Coffee Market
Coffee
Decaffeinated Coffee Market
Coffee
RTD Coffee Market