
 GCC Instant Coffee Market | 2026-2036
GCC Instant Coffee Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Instant Coffee Market Intelligence
Saudi Food and Drug Authority labeling requirements for nutritional disclosure and halal certification is broadening the cost-of-entry calculus for instant coffee importers targeting the Kingdom. Nestle S.A. leverages its Nescafé manufacturing footprint and deep retail penetration across Gulf Cooperation Council hypermarkets to sustain volume leadership. Jacobs Douwe Egberts anchors its regional position through licensed production arrangements and concentrated B2B supply to Saudi Arabian institutional foodservice operators. Starbucks Corporation differentiates via licensed retail presence and branded soluble product lines distributed through regional grocery channels.
Instant coffee comprises brewed coffee extract that undergoes spray-drying or freeze-drying to reduce moisture below five percent, yielding a shelf-stable soluble powder or granule that reconstitutes in hot water for immediate consumption. The freeze-drying process preserves volatile aromatic compounds better than spray-drying, commanding price premiums in Gulf markets where sensory quality expectations rise among affluent consumers. Powdered formats dominate household pantry stock-keeping units across GCC retail shelves, while liquid single-serve sachets capture faster growth in office breakroom and hotel in-room applications where portion control and preparation convenience matter. Online retailers now represent the fastest-expanding distribution channel, though supermarkets still control the largest margin pool through slotting fees and promotional calendar access.
Gulf Standards Organization food safety standards, Saudi Food and Drug Authority import registration protocols, and UAE Ministry of Climate Change and Environment halal verification requirements collectively shape product formulation, packaging disclosure, and customs clearance timelines for market participants. Compliance with these overlapping regimes demands dedicated regulatory affairs capacity, particularly for European and Asian exporters unfamiliar with Gulf-specific labeling and certification workflows. Stakeholders must monitor evolving national nutrition labeling mandates and potential harmonization gaps between individual GCC member state requirements as the region advances toward deeper economic integration.
Market Dynamics
Hospitality procurement teams across Saudi Arabia and the UAE are expanding instant coffee placement in hotel minibars and in-room service menus, reshaping volume distribution toward premium single-serve formats. This demand rotation from retail pantry stock to commercial hospitality channels is compressing traditional supermarket dominance while elevating sensory quality thresholds.
Growth Catalysts
- Gulf Standards Organization harmonization:CODEX Alimentarius alignment is elevating import compliance thresholds, filtering out lower-tier suppliers and creating shelf space for premium soluble coffee brands with dedicated regulatory capacity.
- Freeze-drying technology adoption:Preservation of volatile aromatic compounds commands price premiums in Dubai and Abu Dhabi corridors where affluent consumers demand sensory parity with fresh-brewed alternatives.
- Hospitality channel expansion:Hotel operators in Riyadh and Jeddah are retrofitting in-room service menus with premium instant options, driving volume shifts toward liquid single-serve sachets.
Market Restraints
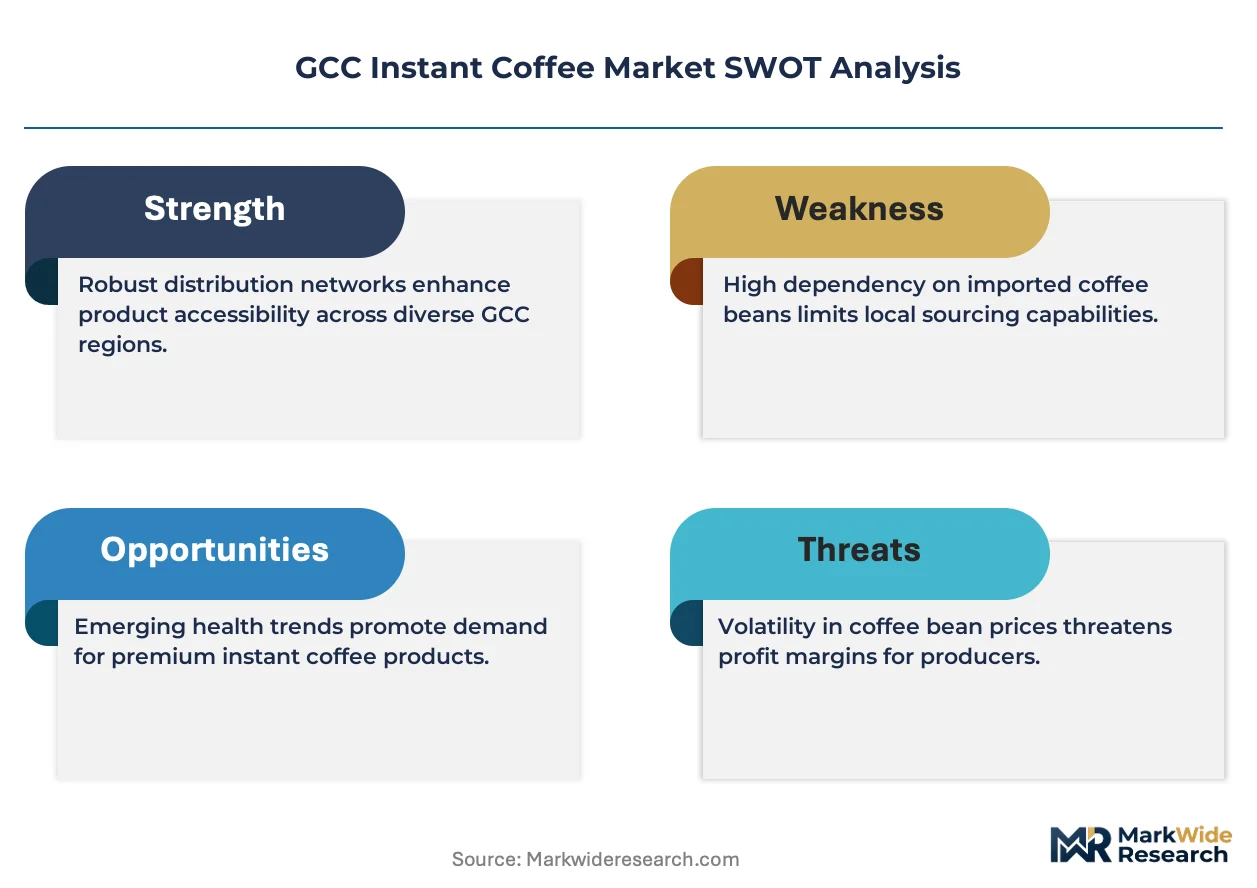
- Robusta arabica price volatility:Raw coffee bean cost fluctuations squeeze margin structures for spray-dried mass-market producers dependent on commodity input markets.
- Regulatory friction:Overlapping Saudi Food and Drug Authority labeling mandates and UAE Ministry of Climate Change and Environment halal verification create extended customs clearance timelines for European and Asian exporters.
- Fresh-brewed substitution threat:Third-wave coffee shop proliferation in Doha and Manama captures younger consumers seeking experiential consumption over convenience-oriented soluble formats.
Strategic Opportunities
- Kuwait and Bahrain underpenetration:These smaller GCC markets show lower premium instant coffee saturation, offering first-mover positioning for freeze-dried specialists with hospitality relationships.
- E-commerce channel innovation:Online retailers represent the fastest-expanding distribution vector, bypassing supermarket slotting fee barriers that protect incumbent volume leaders.
- Saudi halal certification tailwind:SFDA nutritional disclosure mandates create competitive moats for brands with pre-established compliance infrastructure, disadvantaging late entrants.
Industry Challenges
- Regulatory affairs talent scarcity:Dedicated compliance capacity for Gulf-specific labeling workflows remains concentrated among established players, constraining new market entry speed.
- Freeze-drying capex intensity:Capital requirements for aroma-preservation equipment limit production scale-up for mid-tier brands competing on sensory quality.
- Legacy spray-drying asset stranding:Incumbent producers face reconfiguration costs as hospitality demand tilts toward freeze-dried premium formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Instant Coffee Market |
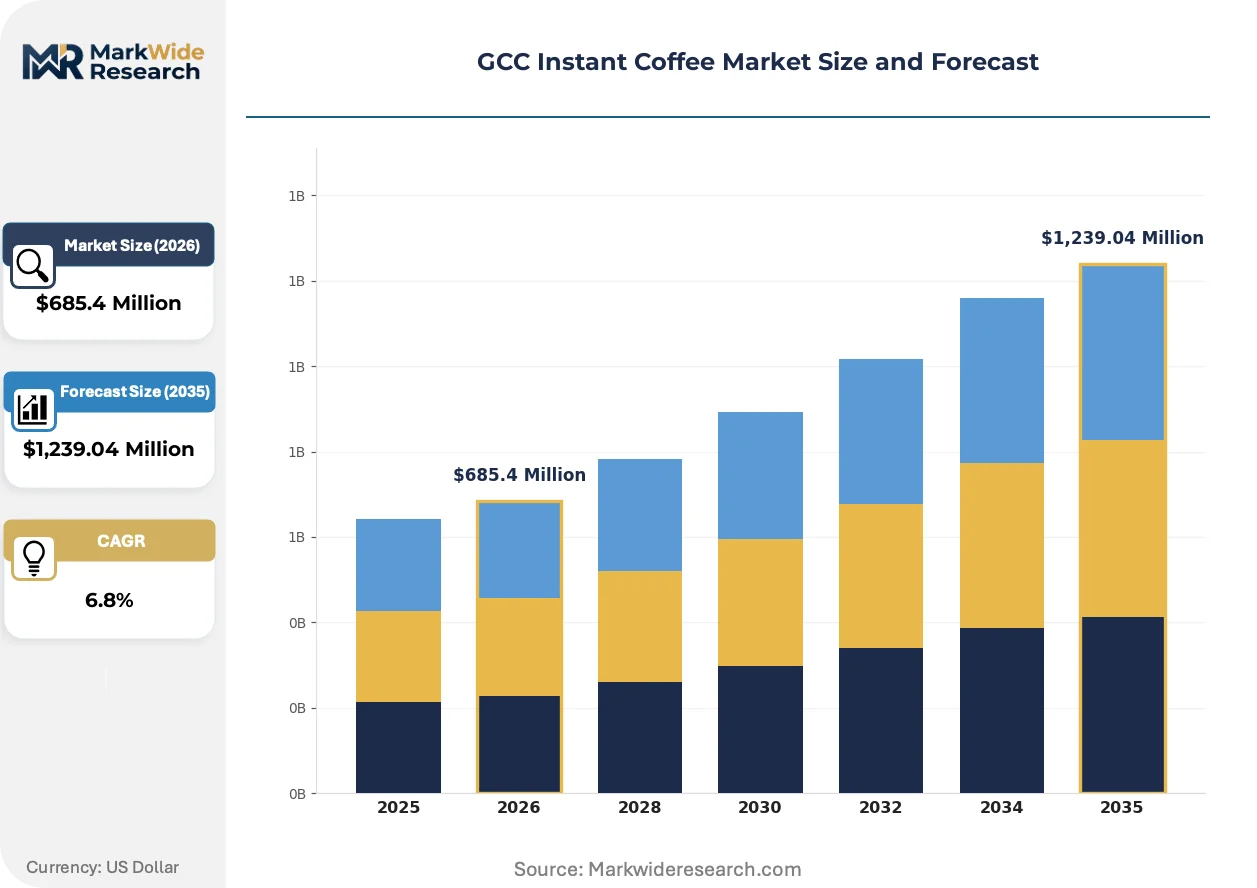
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Granulated, Liquid, Sachets Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops End User: Households, Offices, Cafes, Hotels Flavor Profile: Classic, Mocha, Vanilla, Caramel |
| Companies Covered | Nestle S.A., Jacobs Douwe Egberts, Starbucks Corporation, The Kraft Heinz Company, Strauss Group Ltd., Luigi Lavazza S.P.A., Tata Consumer Products Limited, Tchibo Coffee International Ltd., Unilever PLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Instant Coffee Market Strategic Shifts & Innovations
Product formulation and distribution models across the GCC are converging around convenience premiumization and digital channel expansion. Three developments are compressing traditional competitive positions.
Freeze-drying equipment is decentralizing production geography for soluble coffee manufacturers. Regional licensed producers in Jeddah and Dubai are adopting aroma-preservation technology previously concentrated in European export hubs. This capability diffusion is shortening supply chains and enabling faster formulation iteration for local taste preferences.
SFDA labeling requirements for nutritional disclosure and halal certification are tightening formulation transparency standards. Brands must reformulate packaging disclosure and substantiate supply chain provenance to maintain import registration validity. Saudi Arabian retail and hospitality procurement teams are now screening suppliers on pre-existing compliance infrastructure.
Hotel operators are unbundling in-room beverage service from traditional minibar suppliers. Procurement teams in Abu Dhabi and Riyadh are sourcing premium instant coffee directly from specialty roasters with soluble product lines, bypassing legacy hospitality distributors. This disintermediation elevates brand visibility while compressing margin pools for intermediate traders.
GCC Instant Coffee Market Segmentation
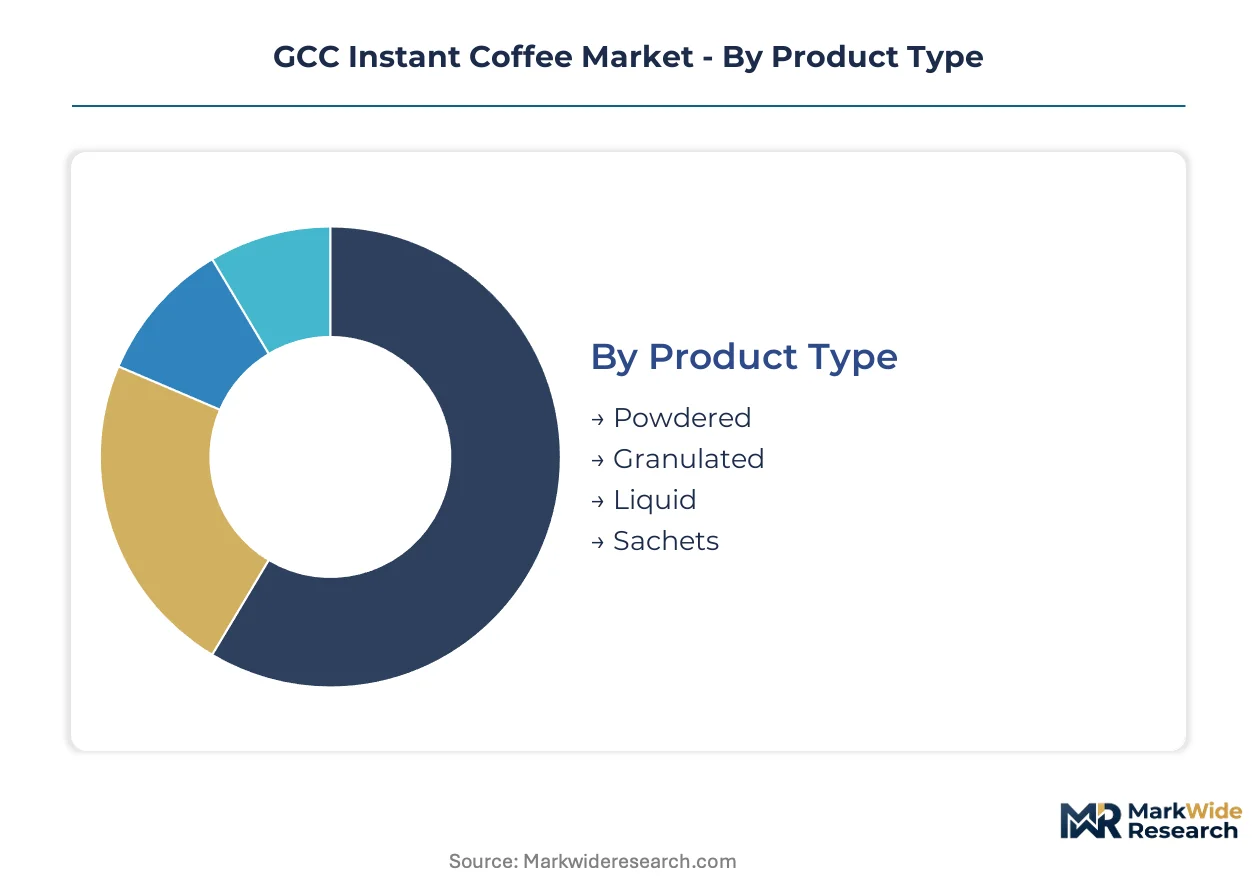
GCC instant coffee procurement patterns diverge sharply between standalone household consumption and embedded hospitality service applications. Manufacturers must configure formulation, packaging, and pricing architectures separately for pantry stock versus in-room and office breakroom deployment.
Product Type:
Powdered formats function as standalone pantry staples requiring consumer preparation equipment, while liquid sachets embed directly into hospitality service systems without additional inputs.
- Powdered:Spray-dried or freeze-dried soluble particles packaged in glass jars or flexible pouches. Saudi Arabian households stock these formats for daily consumption, though growth is decelerating as single-serve alternatives penetrate.
- Liquid:Pre-dissolved coffee concentrate in portion-controlled sachets or capsules. Dubai hotel operators specify these for in-room minibars where preparation speed and zero equipment requirements override unit cost considerations.
- Granulated:Agglomerated particles offering faster dissolution than standard powder. UAE office breakrooms favor this format for vending machine compatibility.
- Sachets:Individual portion packets containing flavored or unflavored soluble coffee. Bahraini convenience stores stock these for on-the-go consumption.
Powdered formats lead volumes today; liquid sachets are gaining share fastest.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with slotting fee structures and inventory velocity requirements creating divergent profitability profiles.
- Supermarkets:Hypermarket chains across Riyadh and Jeddah command the largest revenue pool through promotional calendar dominance and shelf space allocation power. Nestlé and JDE sustain volume leadership here via trade marketing investment.
- Online Retailers:E-commerce platforms bypass traditional slotting barriers, enabling direct-to-consumer subscription models and specialty freeze-dried introductions. Noon and Amazon.ae are expanding grocery delivery infrastructure.
- Convenience Stores:High-frequency, low-basket formats serving commuter corridors and fuel station locations. These outlets prioritize sachet and single-serve packaging.
- Specialty Shops:Curated retail environments emphasizing premium origin claims and sensory differentiation. Dubai Mall and Abu Dhabi Galleria host these formats.
Supermarkets dominate revenue today; online retailers are climbing the fastest.
End User:
User context shapes sensory quality thresholds and price elasticity, with hospitality procurement teams applying stricter performance specifications than household purchasers.
- Hotels:Procurement teams in Riyadh and Abu Dhabi specify freeze-dried formats for in-room service menus. Minibar placement demands premium packaging and consistent aroma delivery.
- Households:Pantry stock rotation drives volume for standard powdered formats. Saudi families prioritize value positioning and large-format packaging.
- Offices:Corporate breakroom managers balance cost control with employee satisfaction. UAE free zone companies show willingness to upgrade from spray-dried to freeze-dried.
- Cafes:Limited-service coffee shops use soluble products for back-of-house efficiency. Kuwaiti café chains are testing premium instant for speed-of-service advantages.
Households anchor volume today; hotels show the steepest expansion trajectory.
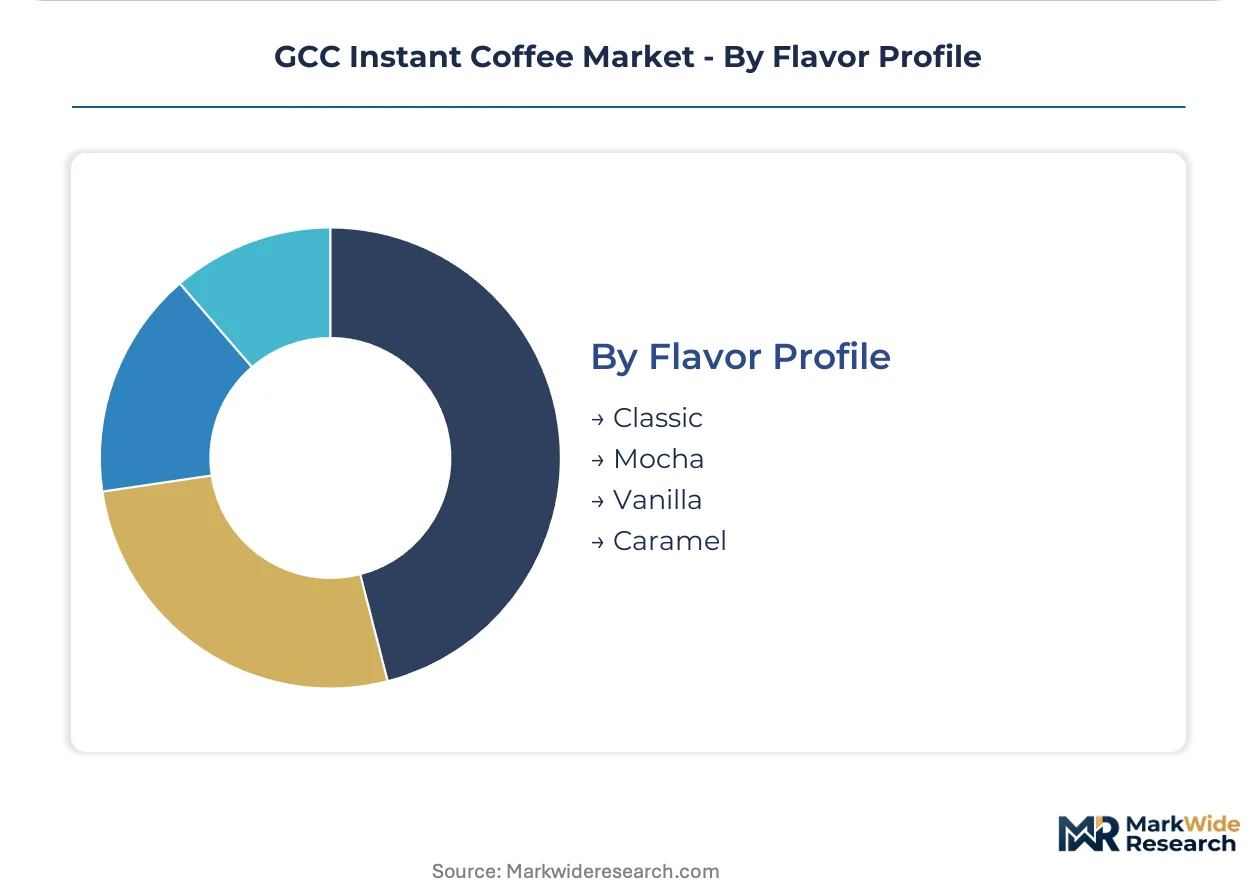
Flavor Profile:
Flavor diversification creates tiered pricing architectures and occasion-based segmentation within soluble coffee portfolios.
- Classic:Unflavored coffee delivering traditional roast and aroma profiles. This format commands the largest volume base across GCC retail.
- Mocha:Chocolate-coffee hybrid formulations. Younger consumers in Doha and Manama show disproportionate preference.
- Vanilla:Sweetened flavor variants targeting afternoon consumption occasions. Saudi female consumers drive this segment.
- Caramel:Dessert-inspired profiles for treat-replacement positioning. Seasonal promotional activity concentrates here.
Classic profiles dominate volume today; mocha variants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement specialists and foodservice distribution talent concentrate in Riyadh, Dubai, and Jeddah, anchoring regional demand formation for premium soluble coffee formats.
Saudi Arabia
Saudi Food and Drug Authority labeling mandates for nutritional disclosure and halal certification are elevating compliance costs for importers. The Kingdom's import registration protocols now require dedicated regulatory affairs capacity. Riyadh hotel operators are retrofitting in-room service menus with freeze-dried premium options, compressing traditional pantry-format dominance.
United Arab Emirates
Expatriate professionals and tourism operators in Dubai and Abu Dhabi corridors drive premium single-serve format adoption. UAE Ministry of Climate Change and Environment halal verification requirements overlap with SFDA protocols, creating dual compliance burdens for European exporters. Dubai Mall specialty retail environments now host curated instant coffee brands emphasizing origin claims.
Kuwait
Lower premium instant coffee saturation creates first-mover positioning opportunities for freeze-dried specialists. The country's national food safety regulator maintains import standards aligned with Gulf Standards Organization harmonization. Kuwait City café chains are testing premium instant formats for speed-of-service advantages over traditional espresso preparation.
Qatar
Third-wave coffee shop proliferation in Doha captures younger consumers seeking experiential consumption, threatening soluble format growth. The national standards body enforces CODEX Alimentarius-aligned food safety protocols for imported coffee products. Doha hospitality procurement teams specify liquid single-serve sachets for luxury hotel minibars.
Bahrain
Convenience store networks across Manama prioritize sachet and single-serve packaging for commuter corridor traffic. The country's import regulatory framework follows GCC-wide harmonization trends. Manama office breakrooms show emerging preference for granulated formats compatible with vending machine infrastructure.
GCC Instant Coffee Market Key Industry Players
The competitive structure tilts toward multinational FMCG conglomerates with deep retail penetration and dedicated Gulf regulatory capacity. Volume leadership concentrates among Swiss and Dutch-domiciled foodservice specialists with licensed production arrangements in Jeddah and Dubai. Two strategic archetypes dominate: established soluble coffee manufacturers leveraging manufacturing footprint and trade marketing investment; and specialty roasters expanding into branded soluble lines through hospitality channel partnerships. Competitive moves center on portfolio diversification toward freeze-dried premium tiers and backward integration into regional licensed production.
Among Swiss-domiciled conglomerates, Nestle S.A. exemplifies the manufacturing-footprint archetype through its Nescafé brand presence across GCC hypermarkets. Jacobs Douwe Egberts anchors the licensed-production vector with concentrated B2B supply relationships to Saudi Arabian institutional foodservice operators. Starbucks Corporation occupies a position bridging retail licensing and branded soluble distribution through regional grocery channels.
| Leading Market Players |
|---|
| Nestle S.A. |
| Jacobs Douwe Egberts |
| Starbucks Corporation |
| The Kraft Heinz Company |
| Strauss Group Ltd. |
| Luigi Lavazza S.P.A. |
| Tata Consumer Products Limited |
| Tchibo Coffee International Ltd. |
| Unilever PLC |
| Others |
Cost & Logistics Intelligence
Backward integration into regional licensed production anchors supply positioning and pricing power for multinational soluble coffee manufacturers serving Gulf markets. Nestlé and Jacobs Douwe Egberts operate captive facilities in Jeddah and Dubai that bypass import duty layers and compress landed cost structures against European-sourced competitors.
Pricing Analysis
Bundled hospitality procurement contracts versus unbundled direct sourcing splits the pricing architecture across GCC instant coffee markets. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy private-label levels segments buyer willingness-to-pay. Price differentiation rests on halal certification tier and sensory quality grade. Cost compression in spray-dried mass-market tiers is intensifying because Robusta arabica bean volatility squeezes margin structures. Household purchasers in Saudi Arabia show highest price sensitivity; Dubai hotel procurement teams demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Riyadh operate hub-and-spoke patterns that consolidate inventory before last-mile deployment to hospitality and retail endpoints. Manufacturing concentrates in Switzerland, the Netherlands, and Saudi Arabia for licensed production. Raw material flows draw from Vietnamese Robusta, Brazilian Arabica, and Indonesian bean origins. Single-source vulnerability in freeze-drying equipment supply constrains premium format scale-up. Distribution runs through hypermarket chains controlling promotional calendar access and slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC instant coffee markets function as a geographic-arbitrage play where regulatory compliance infrastructure in Saudi Arabia commands premium pricing against lower-threshold Bahraini and Kuwaiti entry points.
For Market Incumbents: Deepen captive production capacity in Jeddah and Dubai to defend against freeze-dried specialists entering via hospitality channel disintermediation. Expand SFDA pre-registration holdings to create compliance moats as nutritional disclosure mandates tighten. Prioritize aroma-preservation R&D investments that sustain sensory parity premiums against third-wave coffee shop substitution threats. For New Entrants and Emerging Players: Hospitality procurement specialists represent the most accessible entry vector for freeze-dried specialists lacking hypermarket slotting fee resources. Target Kuwait and Bahrain for first-mover positioning in underpenetrated premium segments. Deploy direct-to-hotel sales models that bypass legacy hospitality distributors and capture minibar specification authority. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier freeze-dried specialists because hospitality channel fragmentation across Riyadh, Dubai, and Jeddah prevents single-brand dominance. Monitor SFDA enforcement intensity as the inflection signal determining whether compliance infrastructure becomes acquisition currency or stranded cost.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Technology Licensing | Aroma-preservation capabilities command price premiums in Dubai and Abu Dhabi corridors. |
| Halal Certification Pre-Registration | SFDA compliance infrastructure creates competitive moats against late European entrants. |
| Hospitality Channel Direct Sourcing | Hotel procurement disintermediation elevates brand visibility while compressing trader margins. |
| E-Commerce Subscription Launch | Noon and Amazon.ae grocery delivery infrastructure bypasses supermarket slotting barriers. |
| Regional Licensed Production Expansion | Jeddah and Dubai facilities reduce import duty exposure and customs clearance timelines. |
Research Approach
Direct dialogue with hospitality procurement managers, foodservice distribution executives, regulatory affairs specialists, and retail category buyers grounded qualitative insights in operational reality. Secondary validation drew from Gulf Standards Organization technical standards, Saudi Food and Drug Authority import registration protocols, UAE Ministry of Climate Change and Environment halal verification guidelines, and customs trade records. Bottom-up channel volume estimates and top-down macroeconomic indicators underwent iterative reconciliation.
Segmented outputs across product type, distribution channel, end user, and flavor profile dimensions populated the analytical framework over the projection horizon. CAGRs emerged from trend extrapolation against historical velocity patterns and structural shift assumptions. Forecast inputs incorporated hospitality placement expansion rates, freeze-drying adoption curves, and regulatory harmonization progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SFDA enforcement intensity, Robusta arabica price volatility, and third-wave coffee shop penetration rates. Outputs reflect documented assumptions around regulatory stability and channel mix evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coffee
Mushroom Coffee Market
Coffee
South America Coffee Market
Coffee
South America Ready-To-Drink (RTD) Coffee Market
Coffee
Singapore Coffee Roaster Market
Coffee
Oceania Coffee Market
Coffee
Coffee Syrup Market
Coffee
Cold Brew Coffee Makers Market
Coffee
Australia Coffee and Tea Capsules Market
Coffee
Coffee Roaster Machine Market
Coffee
North America Specialty Coffee Market
Coffee
Sparkling Coffee Market
Coffee
Smart Coffee Maker Market
Coffee
Global Coffee Market
Coffee
Coffee Premixes Market
Coffee
APAC Ready-To-Drink Coffee Market
Coffee
Global Coffee Shop Market