
 Ethylhexyl Cocoate Market | 2026-2036
Ethylhexyl Cocoate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylhexyl Cocoate Market Foresight
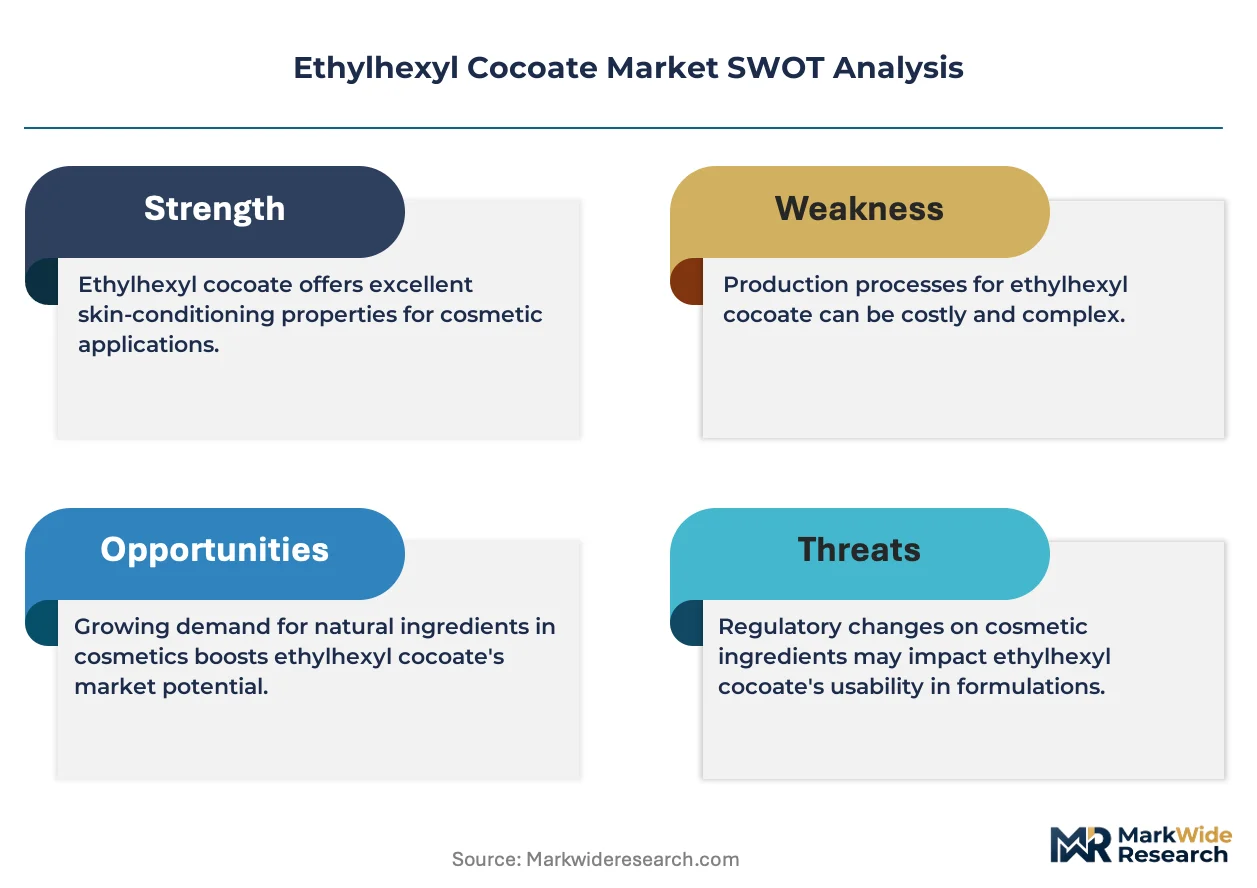
Mineral oil is broadening its displacement by plant-derived esters in cosmetic emulsion bases, and ethylhexyl cocoate sits at the center of this substitution wave. BASF leverages its integrated oleochemicals platform to secure feedstock continuity across European manufacturing sites. Croda anchors its position through high-purity ester specialization for premium skincare brands. Evonik Industries competes via advanced catalysis technology that tightens color specifications and oxidative stability.
Ethylhexyl cocoate is a fatty acid ester synthesized from coconut oil-derived lauric acid and 2-ethylhexanol, yielding a low-viscosity liquid with a cloud point below 10°C and excellent spreadability on skin. Its primary commercial purpose is to function as an emollient, solvent, and co-emulsifier in cosmetic and personal care formulations where silicone-free texture is desired. The emulsifiers segment dominates current volume as formulators replace traditional ethoxylated compounds with milder ester-based alternatives. Cosmetics and personal care applications command the strongest margin pools due to clean-label positioning and certification requirements, while pharmaceutical-grade specifications represent the fastest-growing demand tier as compendial monographs expand.
REACH registration through ECHA mandates full substance dossiers for cosmetic-grade esters imported into Europe, directly raising compliance costs for non-EU suppliers. FDA oversight through cosmetic ingredient safety guidelines shapes product liability exposure for brands marketing in the United States. ISO 16128 natural origin standards increasingly determine formulation eligibility for certified clean beauty claims across multiple jurisdictions. Stakeholders must monitor evolving pharmaceutical monograph adoption rates and regional bio-based content thresholds to align capacity investments with the next wave of specification-driven demand.
Market Dynamics
Clean-label cosmetic formulation is compressing demand timelines for ester suppliers, as brands accelerate silicone replacement programs and tighten purity specifications ahead of regulatory deadlines.
Growth Catalysts
- REACH purity mandates:ECHA's tightening thresholds for cosmetic-grade esters are forcing formulators to upgrade ingredient specifications, directly expanding the addressable market for high-purity ethylhexyl cocoate.
- Silicone-free texture demand:Premium skincare brands are eliminating cyclomethicones and dimethicones from emulsion bases, creating immediate formulation slots for plant-derived esters with comparable spreadability.
- Oleochemical platform consolidation:Integrated coconut oil processors in Southeast Asia are securing lauric acid supply chains, reducing feedstock volatility for ester manufacturers serving European cosmetic houses.
Market Restraints
- Coconut oil price volatility:Weather-driven supply disruptions in Indonesia and the Philippines create input cost instability that compresses margin predictability for ester producers.
- Technical color specification limits:Current catalytic hydrogenation processes struggle to consistently achieve APHA color values below 20, blocking access to ultra-premium cosmetic segments.
- Pharmaceutical monograph lag:Incomplete USP and EP compendial coverage for ethylhexyl cocoate delays regulatory approval timelines for topical drug formulations.
Strategic Opportunities
- Pharmaceutical compounding expansion:Compounding pharmacies and topical drug manufacturers are seeking GRAS-status esters for dermatological delivery systems, opening a compliance-light entry path.
- ISO 16128 certification acceleration:Natural origin standard adoption across clean beauty retailers is creating tiered pricing power for certified ester grades.
- Biotechnology convergence:Enzymatic esterification processes are reducing energy intensity and enabling carbon footprint claims that resonate with sustainability-focused procurement teams.
Industry Challenges
- Analytical method standardization:Inconsistent oxidative stability test protocols between cosmetic and pharmaceutical buyers force suppliers to maintain dual qualification pathways.
- Specialized catalysis talent scarcity:Experienced process chemists capable of optimizing selective hydrogenation for color and odor control command premium compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylhexyl Cocoate Market |
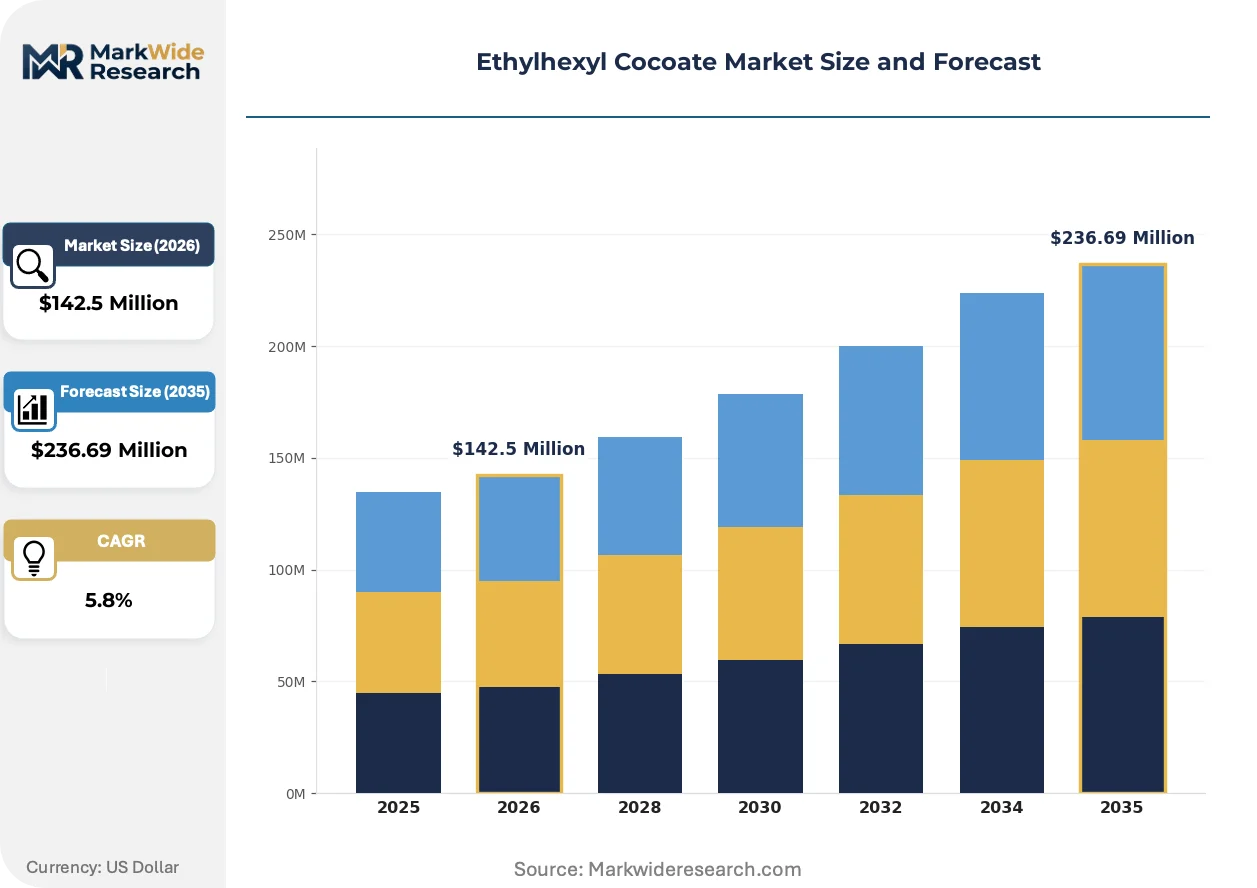
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Solvents, Plasticizers, Coatings Application: Cosmetics, Personal Care, Pharmaceuticals, Food Additives End User: Manufacturers, Distributors, Retailers, Consumers Form: Liquid, Gel, Powder, Granulate |
| Companies Covered | BASF, Croda, Berg+Schmidt, Brenntag Nederland BV, Oleon, Evonik Industries, Acme-Hardesty, Clariant, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylhexyl Cocoate Market Shifts & Advancements
Enzymatic process technology is rewriting cost structures for medium-chain ester production, while regulatory alignment between cosmetic and pharmaceutical grades is collapsing traditional specification boundaries.
Bio-based 2-ethylhexanol derived from sugarcane ethanol is converging with traditional petrochemical routes, enabling mass balance certification for fully renewable ethylhexyl cocoate. Clean beauty brands in France and Germany are mandating bio-based content verification through radiocarbon analysis. This feedstock diversification is compressing the price premium between conventional and renewable grades.
ECHA's 2023 updated guidance on substance identity for UVCB esters is forcing suppliers to tighten analytical characterization protocols. The regulation requires detailed fatty acid distribution reporting for coconut-derived feedstocks. Small and mid-sized ester manufacturers are outsourcing dossier preparation to specialized regulatory consultancies.
Direct procurement relationships between cosmetic brand technical teams and ester manufacturers are displacing traditional distributor channels for specification-critical ingredients. Formulation chemists at premium skincare houses now conduct supplier audits focused on catalytic process transparency. This channel compression is most visible in the German and Italian markets where clean-label positioning commands retail price premiums.
Ethylhexyl Cocoate Market Segmentation
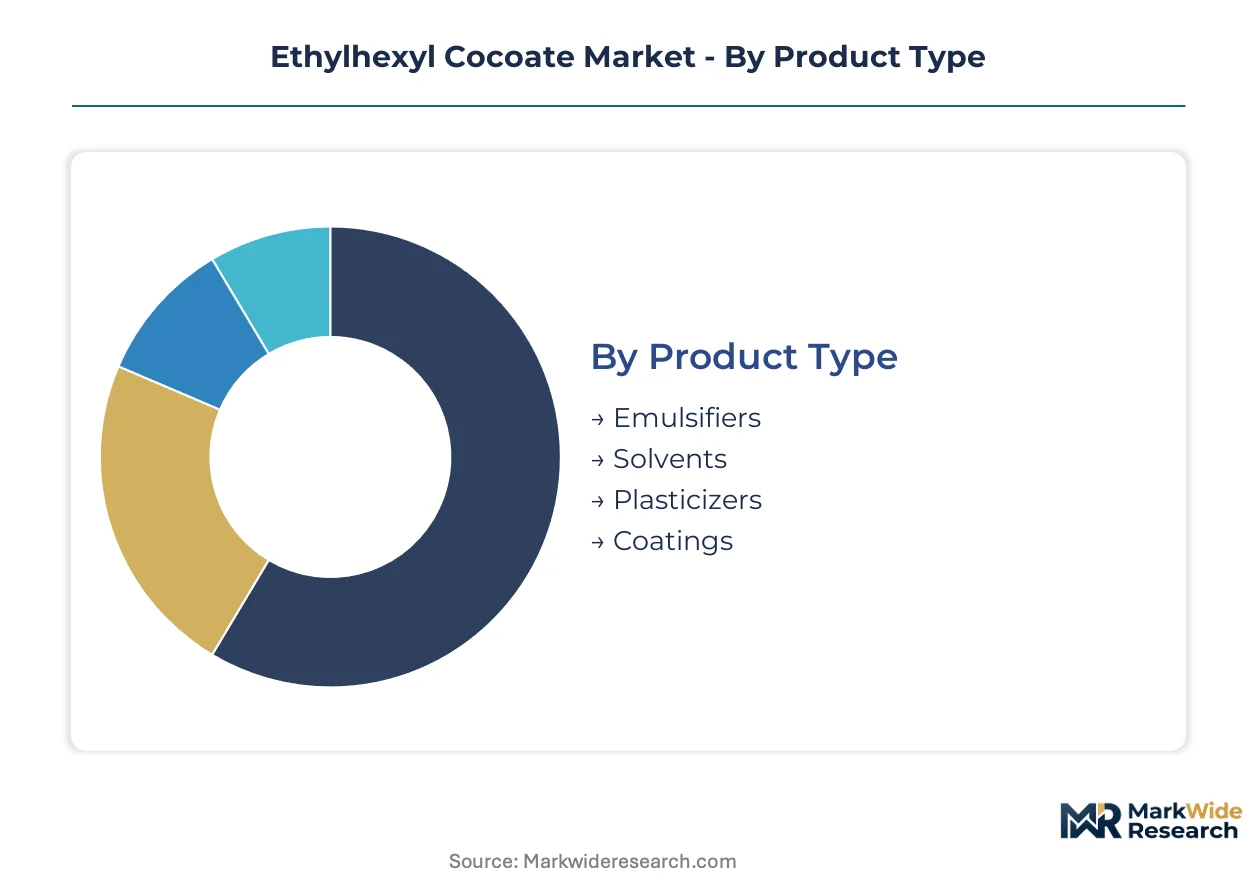
Segmentation reveals how specification tiers and channel structures fragment the ethylhexyl cocoate opportunity set. Understanding these divisions exposes where margin pools concentrate and where compliance burdens shift across buyer types.
Product Type:
Supply concentration in lauric acid processing favors integrated producers of high-purity ester grades, compressing competitive space for standalone compounders.
- Emulsifiers:Alkoxylated ester variants function as primary surfactants in O/W emulsion systems, replacing ethoxylated alcohols in clean-label skincare. Demand clusters with German and French formulators pursuing silicone-free textures for prestige facial creams.
- Solvents:Low-viscosity liquid grades dissolve lipophilic actives in anhydrous serums and cleansing oils. REACH purity mandates are forcing specification upgrades across mid-tier cosmetic houses, expanding addressable volume for APHA sub-20 grades.
- Plasticizers:Flexible polymer applications leverage ethylhexyl cocoate as a phthalate alternative in biodegradable film coatings.
- Coatings:Surface treatment grades provide gloss and water resistance in decorative cosmetic applications.
Today's leader: Emulsifiers. Tomorrow's challenger: Solvents.
Application:
Cost tier stratification separates pharmaceutical qualification pathways from cosmetic-grade volume plays, with certification premiums widening the pricing spread.
- Cosmetics:Facial skincare and color cosmetics deploy ethylhexyl cocoate as a dimethicone replacement in premium texture systems. ISO 16128 certification requirements from German clean beauty retailers are tiering supplier access by bio-based content verification.
- Personal Care:Hair conditioners and body lotions utilize the ester's spreadability for rinse-off and leave-on formulations. Italian formulators are accelerating silicone replacement timelines ahead of regulatory deadlines.
- Pharmaceuticals:Topical drug delivery systems seek compendial-grade esters for dermatological actives. Incomplete USP and EP monograph coverage delays regulatory approvals, constraining near-term volume.
- Food Additives:Limited food-contact applications exploit the ester's lubricity in processing aids.
Cosmetics commands current margin pools; pharmaceuticals climbs fastest on compendial expansion.
End User:
Customer type determines specification intensity, with direct technical relationships displacing distributor channels for critical grades.
- Manufacturers:Cosmetic compounders and pharmaceutical processors purchase bulk esters for in-house formulation. BASF and Croda serve this tier through integrated oleochemical platforms with catalytic process transparency.
- Distributors:Regional chemical traders handle standard-grade volumes for mid-tier personal care brands. REACH dossier complexity is consolidating this channel toward specialized regulatory consultancies.
- Retailers:Clean beauty retailers in France mandate bio-based verification through radiocarbon analysis, compressing supply base to certified producers.
- Consumers:Minimal direct exposure exists; end-product positioning drives upstream specification pressure.
Manufacturers anchor volume commitment; retailers reshape specification floors fastest.
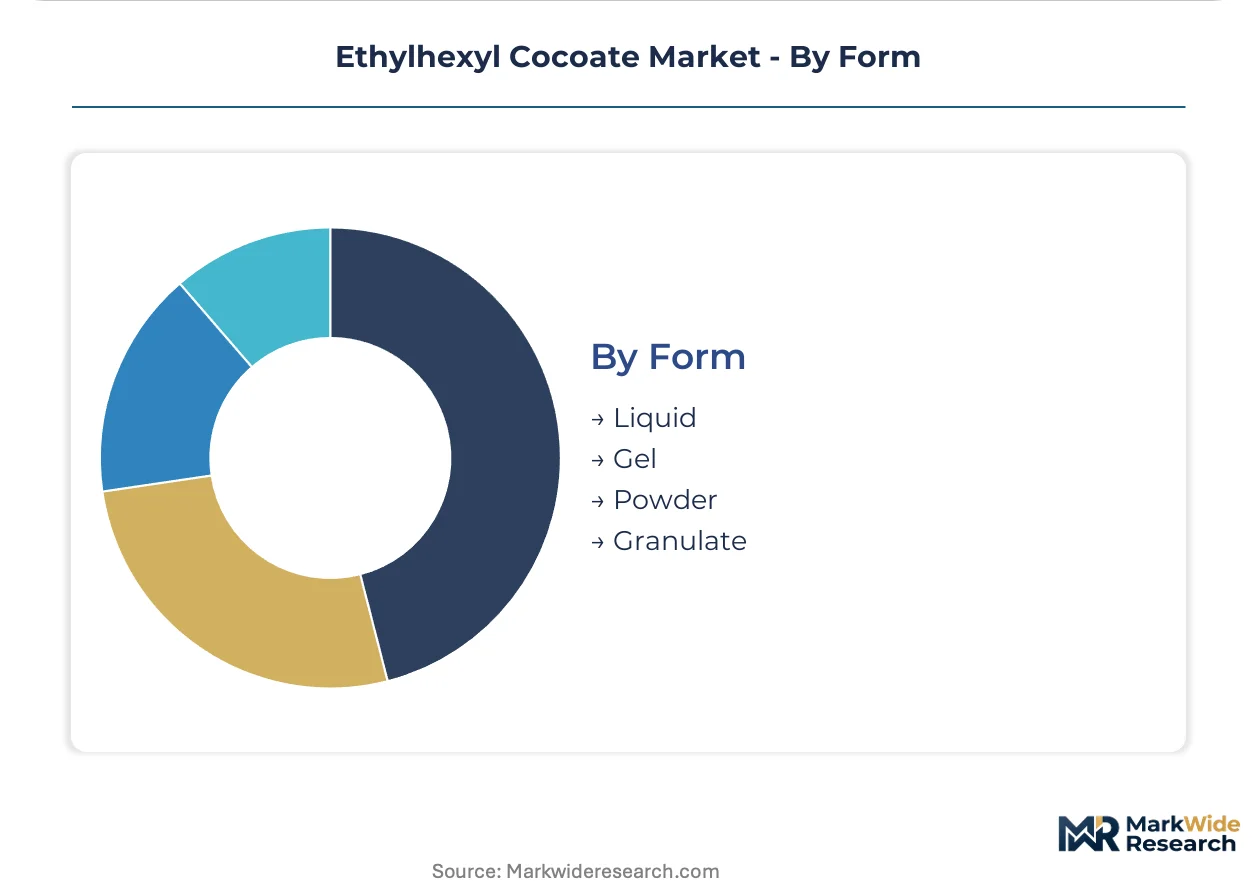
Form:
Physical state governs handling infrastructure and formulation compatibility, with liquid dominance reflecting process economics.
- Liquid:Standard low-viscosity grades suit pumpable emulsion manufacturing and cold-process formulation. Cloud points below 10°C ensure year-round pumpability in European climate conditions.
- Gel:Thickened variants enable controlled release in anhydrous stick formulations.
- Powder:Spray-dried grades serve solid dosage and dry blend applications.
- Granulate:Free-flowing particulates facilitate metered dosing in industrial compounding.
Liquid holds process integration advantages; gel gains share in solid format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr chemical corridor hosts the densest concentration of cosmetic-grade ester formulation activity, with technical teams from premium skincare houses conducting direct supplier audits for REACH-compliant ethylhexyl cocoate grades.
Germany
Clean beauty retailers in Berlin and Hamburg mandate ISO 16128 certification with radiocarbon verification, compressing supplier bases to certified ester producers. ECHA's 2023 UVCB guidance forces detailed fatty acid distribution reporting. BASF's Ludwigshafen oleochemical platform anchors integrated lauric acid-to-ester production for domestic cosmetic compounders.
France
Paris-based luxury skincare brands accelerate silicone replacement timelines ahead of 2025 regulatory deadlines, creating immediate slots for plant-derived emollients. ANSM cosmetic safety guidelines align with REACH purity thresholds. The Île-de-France formulation cluster drives specification intensity for APHA sub-20 color grades in prestige facial creams.
Italy
Milanese personal care manufacturers expand ethylhexyl cocoate use in hair conditioners and body lotions for rinse-off applications. The national cosmetic association pushes voluntary bio-based content labeling ahead of EU harmonization. Lombardy-based compounders negotiate direct technical relationships with ester producers, bypassing traditional distribution channels.
United States
FDA cosmetic ingredient safety guidelines shape product liability exposure for brands marketing silicone-free emulsions. California's clean beauty legislation drives bio-based verification requirements that mirror European standards. New Jersey and Illinois formulation houses qualify suppliers through dual cosmetic-pharmaceutical pathways pending USP monograph expansion.
Indonesia
Integrated coconut oil processors in Sulawesi and Sumatra secure lauric acid supply chains for export to European ester manufacturers. The national palm and coconut derivatives association coordinates feedstock traceability protocols. Weather-driven supply disruptions in key growing regions create input cost volatility that compresses margin predictability for downstream producers.
Ethylhexyl Cocoate Market Competitive Landscape
Global majors compete with regional champions across integrated oleochemical platforms versus specialized ester purification capabilities. The market structure concentrates around three to four vertically integrated producers controlling lauric acid feedstock and catalytic hydrogenation technology, while mid-sized compounders occupy specification niches. Strategic archetypes span integrated petrochemical-oleochemical hybrids, pure-play high-purity ester specialists, and regional distribution-anchored compounders. Capacity expansion in Southeast Asian lauric acid processing and selective hydrogenation technology licensing represent the dominant competitive moves.
Within the integrated platform tier, BASF and Croda exemplify archetypes that combine captive coconut oil processing with advanced catalytic capabilities. Evonik Industries occupies a position emphasizing process technology for color and oxidative stability control. These three anchors demonstrate how feedstock security and specification intensity separate premium-grade suppliers from commodity ester compounders in procurement decisions by German and French cosmetic houses.
| Leading Market Players |
|---|
| BASF |
| Croda |
| Berg+Schmidt |
| Brenntag Nederland BV |
| Oleon |
| Evonik Industries |
| Acme-Hardesty |
| Clariant |
| Stepan Company |
| Others |
Supply & Pricing Matrix
Specialized catalysis chemists concentrated in Germany's Rhine-Ruhr corridor command compensation premiums that widen pricing spreads between premium cosmetic-grade and standard industrial esters. Labor-cost differentials between European specification specialists and Southeast Asian compounders feed directly into tiered pricing structures that separate REACH-certified grades from commodity alternatives.
Pricing Analysis
Coconut oil price volatility passes through to finished ester quotations on a lagged basis, compressing margin predictability for non-integrated producers. Pricing stratifies across premium, standard, and economy tiers based on APHA color specifications and ISO 16128 certification status. Cost compression in mid-tier cosmetic grades is intensifying because Indonesian feedstock disruptions coincide with REACH dossier complexity. Contract manufacturers exhibit highest price sensitivity; prestige skincare houses prioritize specification compliance over unit economics.
Supply Chain Analysis
REACH registration and ECHA substance-identity requirements gate supplier access to European cosmetic compounders, forcing dossier investments that smaller producers cannot absorb. Feedstock concentration in Indonesia and the Philippines combines with hydrogenation capacity in Germany and the Netherlands. The chain rests on lauric acid from coconut oil, 2-ethylhexanol from petrochemical or bio-based routes, and specialized hydrogenation catalysts. Weather-driven supply disruptions in Southeast Asia create commodity price volatility that ripples through quarterly contract negotiations. Distribution runs through direct technical relationships with German and French formulators, displacing traditional chemical traders for specification-critical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European regulatory stringency creates premium pricing pools that Southeast Asian feedstock access can capture. The spread between REACH compliance costs and lauric acid procurement economics defines viable competitive positioning.
For Market Incumbents: Deepen catalytic process transparency to defend against emerging enzymatic esterification specialists. Secure captive lauric acid supply through backward integration into Indonesian coconut processing or long-term offtake agreements with Sulawesi-based cooperatives. Expand selective hydrogenation capacity to consistently achieve APHA sub-20 color specifications that unlock ultra-premium cosmetic segments. For New Entrants and Emerging Players: REACH's 2023 UVCB guidance opens a window for regulatory consultancies to bundle dossier preparation with ester supply, lowering barriers for mid-tier compounders. Target pharmaceutical compounding pharmacies seeking GRAS-status esters ahead of USP monograph expansion. Enter through enzymatic process technology that enables carbon footprint claims resonating with French clean beauty procurement teams. For Investors and Strategic Acquirers: Integrated oleochemical platforms are the most active acquirer in this space, consolidating hydrogenation expertise and feedstock security. The five-to-ten-year viability window favors targets with dual cosmetic-pharmaceutical qualification pathways and existing ECHA registration. Watch USP and EP compendial adoption rates for ethylhexyl cocoate as the signal indicating when pharmaceutical volume inflection accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive lauric acid supply from Indonesian coconut processors insulates margin predictability against weather-driven disruptions. |
| Enzymatic Process Technology Licensing | Carbon footprint reduction claims unlock procurement preference from German clean beauty retailers mandating bio-based verification. |
| Dual Pharmaceutical-Cosmetic Qualification | USP and EP monograph preparation positions suppliers for dermatological delivery system expansion as regulatory coverage completes. |
| Direct Technical Relationship Cultivation | Milanese and Parisian formulation teams now audit catalytic transparency, bypassing distributor channels for critical grades. |
| Specialized Regulatory Consultancy Acquisition | ECHA dossier complexity consolidates supplier bases toward bundled compliance-and-supply offerings for mid-tier compounders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic formulation chemists, pharmaceutical compounding pharmacists, oleochemical plant managers, and ECHA regulatory consultants with secondary validation. Customs trade data, REACH registration filings, SEC disclosures from listed chemical producers, and ISO certification databases anchored supply-side estimates. Bottom-up volume triangulation across emulsifier, solvent, and pharmaceutical-grade segments converged with top-down market sizing.
Comparable-period anchoring linked projection assumptions to historical demand patterns across silicone replacement cycles and prior REACH regulatory phases. The modeling period incorporated grade tier, end-use industry, regional production hub, and certification status as segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves and input-cost pass-through coefficients, with coconut oil price volatility and hydrogenation capacity utilization as specific forecast inputs.
Revisions become necessary when ECHA guidance updates, USP monograph expansions, or Indonesian weather disruptions materially alter supply-demand balances. Forecasts reflect documented assumptions about regulatory timeline adherence and feedstock traceability protocol adoption. A model refresh is warranted upon material change in pharmaceutical compendial coverage or bio-based 2-ethylhexanol cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Squalane Market
Oleochemicals
Ethylene Bis Stearamide Market
Oleochemicals
Lipid Rich Powder Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Butyl Stearate Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market