
 Asia-Pacific Green Sic Market | 2026-2036
Asia-Pacific Green Sic Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Green Sic Market Analytics
Silicon carbide wafers is broadening the addressable market for high-voltage power modules as gallium nitride faces thermal ceiling constraints above 650V. Shin-Etsu Chemical Co., Ltd. leverages its polysilicon heritage to secure precursor supply chains across Japan and Taiwan. Futong Industry Co. Limited anchors Chinese domestic demand through long-term foundry partnerships in Hefei and Xi'an. Fiven ASA differentiates via Norwegian-sourced petroleum coke feedstock that reduces boron contamination in 6-inch substrates.
Green silicon carbide consists of alpha-phase SiC crystals synthesized through the Acheson process at temperatures exceeding 2,200°C, yielding purity grades above 99% with hexagonal polytype structures optimized for abrasive and refractory applications. The material serves primarily as a precision abrasive for hard ceramics and as a thermal management substrate in power electronics where silicon reaches intrinsic limits. Powders and wafers currently capture the deepest margin pools, with wafer segments tightening supply as 200mm qualification timelines extend. Chemical Vapor Deposition technology leads capital deployment among fabrication methods, while Physical Vapor Deposition competes for niche optoelectronic applications requiring minimal defect densities.
China's MIIT sets national GB standards for SiC substrate dimensional tolerances, while Japan's METI coordinates public-private consortia on next-generation wafer inspection protocols. India's BIS has begun aligning domestic testing norms with IEC semiconductor substrate specifications to ease import substitution. Stakeholders must track which geography secures operational 8-inch wafer capacity first, as this threshold determines cost parity with silicon IGBTs in mass-market EV inverters.
Market Dynamics
The Asia-Pacific Green SiC market pivots on China's dual carbon mandate, which redirects state capital toward domestic wafer production and compresses import dependency timelines. This structural force reshapes capacity allocation across the Yangtze River Delta and accelerates 200mm substrate qualification races.
Growth Catalysts
- MIIT substrate standards:China's GB dimensional tolerance rules for 6-inch and 8-inch wafers create predictable qualification pathways, reducing foundry integration friction for power module manufacturers in Hefei and Xi'an.
- EV powertrain thermal ceilings:Gallium nitrate faces intrinsic limits above 650V, forcing inverter designers toward Green SiC MOSFETs in 800V architectures deployed by Japanese and Korean automakers.
- India's PLI scheme:Production-linked incentives for semiconductor fabrication attract Green SiC precursor investments toward Gujarat and Karnataka, diversifying supply origins beyond Chinese coastal clusters.
Market Restraints
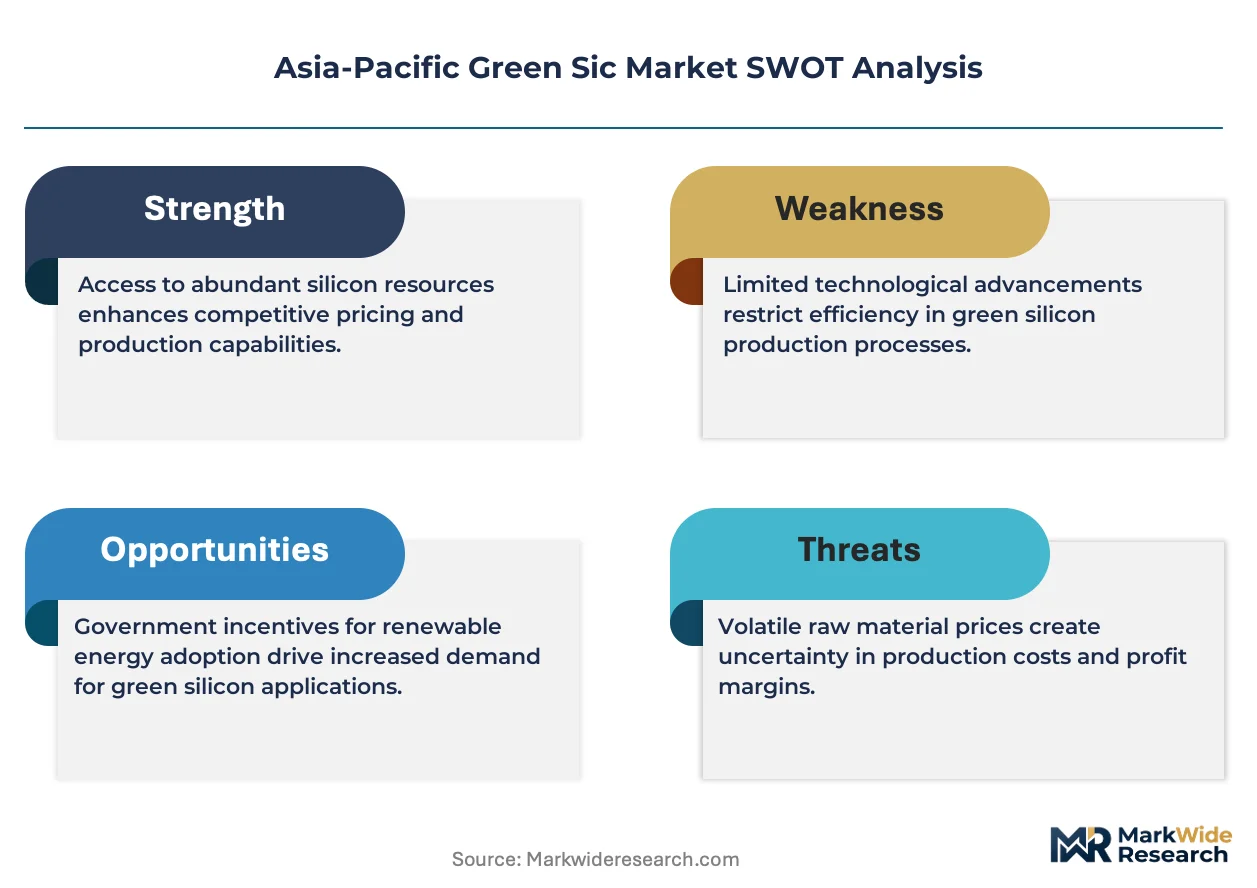
- Petroleum coke purity volatility:Norwegian-sourced low-boron feedstock commands premium multiples, constraining 6-inch substrate yields for second-tier Chinese producers dependent on domestic coke supplies.
- Acheson furnace energy intensity:Synthesis temperatures exceeding 2,200°C require captive power arrangements that exclude smaller entrants from cost-competitive alpha-phase crystal production.
- Physical Vapor Deposition niche lock:Minimal defect density requirements for optoelectronic applications limit PVD scalability, forcing capital concentration into Chemical Vapor Deposition lines with longer depreciation cycles.
Strategic Opportunities
- Indonesia's nickel-smelter power surplus:Excess geothermal and captive coal generation in Sulawesi and Halmahera enables energy-cost arbitrage for Acheson process operators seeking alternative production bases outside China.
- 8-inch wafer cost parity threshold:First-mover qualification of 200mm substrates unlocks silicon IGBT displacement in mass-market EV inverters, with METI-funded consortia in Japan accelerating inspection protocol development.
- BIS-IEC alignment:India's harmonization of domestic testing norms with international semiconductor substrate specifications streamlines import substitution for foundry customers in Bangalore and Hyderabad.
Industry Challenges
- Polytype control expertise scarcity:Hexagonal 4H and 6H crystal structure optimization requires materials scientists with decade-long Acheson process experience, a talent pool concentrated among retired Japanese furnace operators.
- 200mm qualification timeline compression:Foundry customers demand 18-month substrate validation cycles that outpace standard 36-month defect density characterization protocols, forcing premature yield commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Green Sic Market |
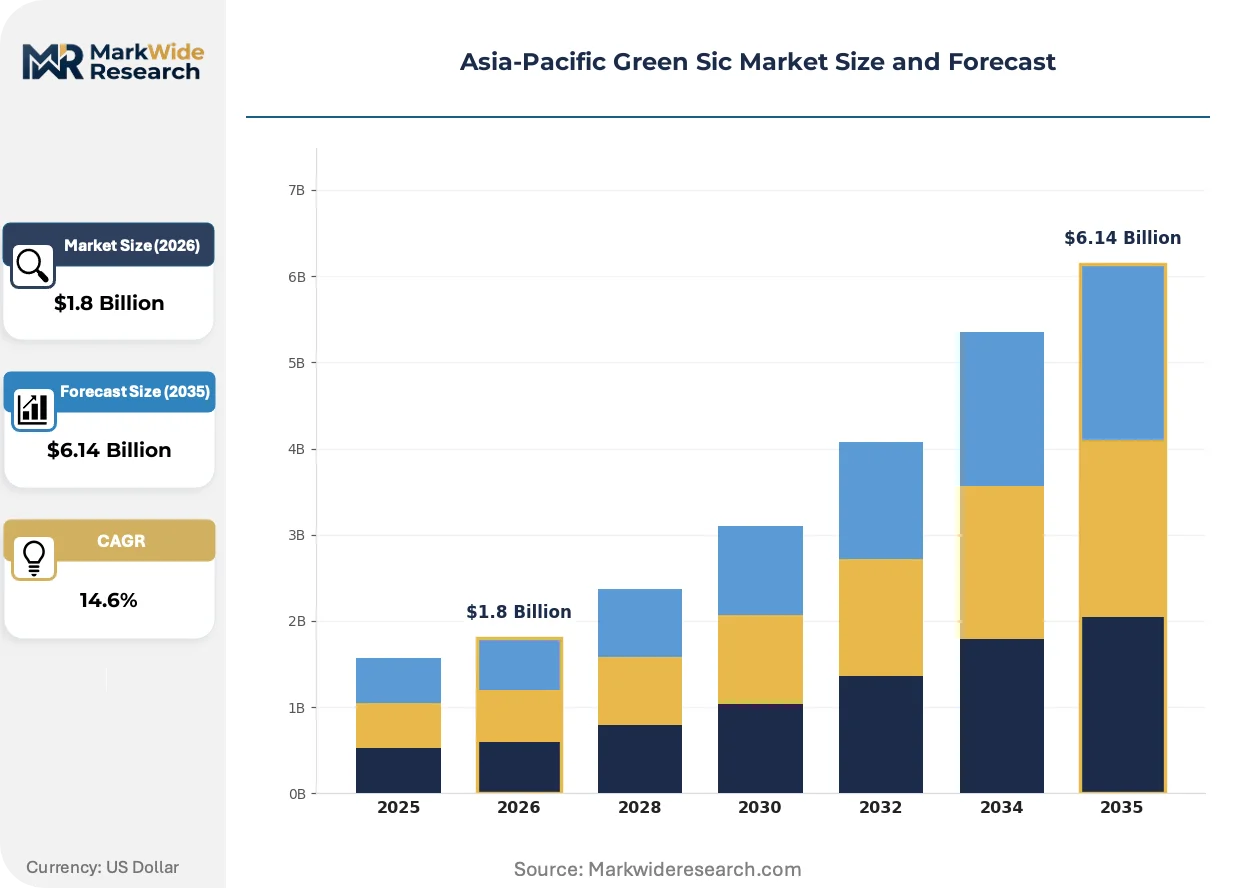
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Powders, Granules, Wafers End User: Aerospace, Electronics, Automotive Components, Renewable Energy Application: Semiconductors, Solar Cells, Power Electronics, LED Lighting Technology: Sintering, Chemical Vapor Deposition, Liquid Phase Sintering, Physical Vapor Deposition |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Futong Industry Co. Limited, Washington Mills, General Abrasivi Srl, CHOKO CO., LTD., Fiven ASA, Zibo Jinjiyuan Abrasives Co. Ltd., Snam Abrasives Pvt. Ltd., Henan Qingjiang Industrial Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Green Sic Market Evolving Landscape
Chemical Vapor Deposition technology is consolidating fabrication investment as thermal management requirements intensify across electric vehicle and renewable energy applications. Process convergence and substrate scaling dominate capital allocation decisions.
Advanced CVD reactor designs is unifying temperature uniformity control across 150mm and 200mm growth chambers. Tier-one foundries in Japan and Taiwan are retrofitting lines at 24-month intervals. This unifying platform approach compresses equipment vendor margins while accelerating polytype consistency for power electronics customers.
METI's next-generation wafer inspection protocols mandate automated defect mapping for substrates destined for automotive qualification. Japanese consortia coordinate public-private funding to deploy X-ray topography systems at volume. Power module manufacturers in Nagoya and Hiroshima now require METI-compliant certification for inverter supply contracts, shifting procurement screening criteria.
Consolidated procurement through Yangtze River Delta foundry clusters concentrates Green SiC wafer purchasing among three dominant power semiconductor IDMs. Long-term supply agreements with 36-month price locks displace spot-market transactions. This concentration is most visible in Hefei, where provincial industrial guidance directs foundry customers toward domestic substrate qualification programs.
Asia-Pacific Green Sic Market Segmentation
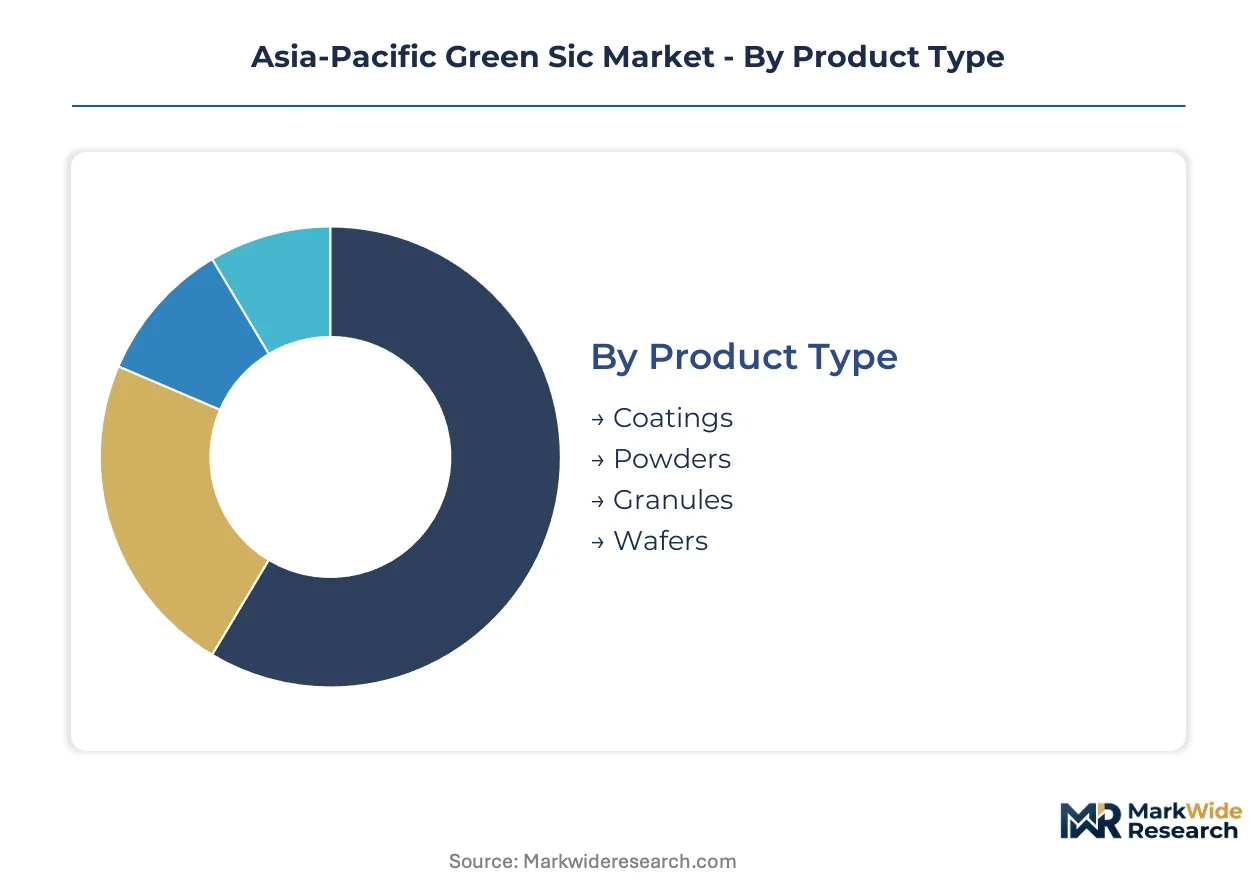
Green silicon carbide markets fragment across material form, end-use thermal requirements, fabrication technology, and voltage class specifications. Each segmentation axis carries distinct margin profiles and qualification barriers that shape procurement decisions across China's foundry corridor and Japan's automotive supply base.
Product Type:
Customization intensity spans from commoditized bulk powders to wafer-grade substrates requiring dimensional tolerances measured in microns.
- Wafers:Single-crystal substrates sliced from boules grown via modified Lely or CVD processes, with surface roughness specifications below 0.5nm RMS for epitaxial-ready grades. Demand concentrates in Hefei and Xi'an foundry clusters where MIIT substrate standards compress qualification timelines for 6-inch and 8-inch formats. Supply tightens as 200mm diameter qualification extends beyond standard depreciation cycles.
- Powders:Alpha-phase SiC particulates graded by grit size distribution and purity thresholds above 99%, serving precision abrasive and ceramic matrix composite feedstock applications. Japanese automotive suppliers in Nagoya and Hiroshima anchor consumption for brake pad and clutch friction material formulations.
- Granules:Sized agglomerates optimized for blast media and refractory gunning applications, with hardness retention above Mohs 9.0 driving specification in Korean shipyard maintenance contracts.
- Coatings:Thin-film depositions of beta-phase or amorphous SiC for corrosion protection and wear resistance, applied via plasma spray or chemical vapor infiltration to turbine components in India's aerospace maintenance facilities.
Leading the category by volume: Powders. Expanding most quickly: Wafers.
End User:
Cost tier stratification separates qualification-intensive automotive and aerospace segments from price-sensitive renewable energy procurement.
- Automotive Components:Traction inverter modules and onboard charger subassemblies requiring 800V architecture compatibility and AEC-Q101 qualification. Korean and Japanese OEMs in Ulsan and Toyota City specify Green SiC MOSFETs for next-generation EV platforms.
- Electronics:Power supply units, RF amplifiers, and thermal management substrates where gallium nitrate thermal ceilings above 650V force material substitution. Taiwan's ODM clusters in Taoyuan drive spot demand for 6-inch wafer formats.
- Renewable Energy:Solar inverter power stages and wind turbine converter modules, with procurement decisions dominated by levelized cost of energy calculations that delay Green SiC adoption until 8-inch wafer cost parity.
- Aerospace:Satcom amplifiers, radar T/R modules, and propulsion system thermal protection, with minimal defect density requirements restricting supply to PVD-processed substrates from METI-certified Japanese vendors.
Highest margin capture: Automotive Components. Steepest volume climb: Electronics.
Application:
Technology maturity separates established LED and solar applications from emerging power electronics deployments.
- Power Electronics:High-voltage switching devices, rectifiers, and inverters where silicon IGBT displacement depends on substrate cost reduction. China's dual carbon mandate accelerates domestic wafer qualification for grid-tied storage inverters.
- Semiconductors:Discrete devices and integrated power stages requiring epitaxial layer thickness uniformity within 3% across 150mm diameters. Japanese consortia under METI coordination advance automated defect mapping protocols.
- Solar Cells:P-type and n-type SiC substrates for multi-junction photovoltaic cells in concentrated solar power installations, with demand anchored in Gujarat and Rajasthan under India's PLI scheme for renewable manufacturing.
- LED Lighting:Substrates for ultraviolet and high-power white LED epitaxy, a maturing segment where sapphire substrate cost advantages constrain Green SiC penetration except in military and sterilization applications.
Deepest supply concentration: Power Electronics. Fastest specification evolution: Semiconductors.
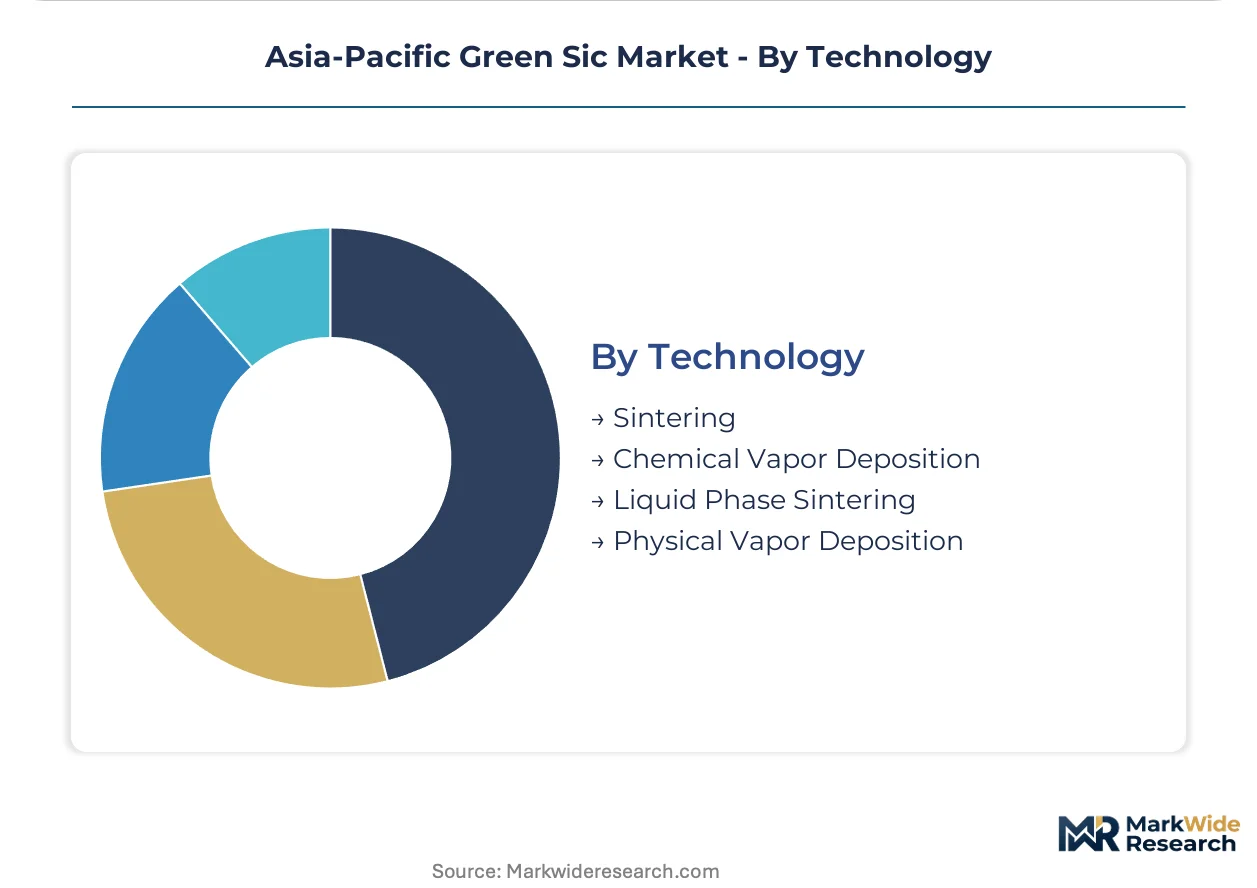
Technology:
Capital intensity and yield scalability differentiate fabrication methods for volume production versus specialty applications.
- Chemical Vapor Deposition:Halide- or silane-based precursor decomposition at 1,400-1,600°C producing 4H-SiC epilayers with controlled doping profiles. Tier-one foundries in Japan and Taiwan consolidate investment in unified 150mm/200mm reactor platforms.
- Physical Vapor Deposition:Sublimation-based growth from polycrystalline sources yielding minimal defect densities for optoelectronic and radiation-hardened applications. Niche scalability limits deployment to METI-funded consortia and aerospace-qualified suppliers.
- Sintering:Solid-state densification of SiC powders with oxide or nitride sintering aids for structural ceramic components, dominating refractory and armor tile production in China's Shandong industrial belt.
- Liquid Phase Sintering:Rare-earth oxide flux-assisted densification achieving full density at reduced temperatures, employed for complex-shaped ceramic components in Japanese precision tooling markets.
Widest capital deployment: Chemical Vapor Deposition. Narrowest supplier base: Physical Vapor Deposition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate foundry demand through provincial industrial guidance directing substrate qualification programs. State capital flows toward 200mm wafer capacity under China's dual carbon mandate, compressing import dependency timelines across the region.
China
MIIT substrate standards create predictable qualification pathways for 6-inch and 8-inch wafers, reducing foundry integration friction for power module manufacturers. The dual carbon goals redirect capital toward domestic Green SiC wafer production. Hefei and Xi'an anchor long-term supply agreements with 36-month price locks that displace spot-market transactions.
Japan
Automotive OEMs in Toyota City and Nagoya specify Green SiC MOSFETs for 800V EV architectures, driving AEC-Q101 qualification requirements. METI coordinates public-private consortia on next-generation wafer inspection protocols with automated defect mapping mandates. Shin-Etsu Chemical leverages polysilicon heritage to secure precursor supply chains across domestic and Taiwanese markets.
India
The PLI scheme for semiconductors attracts Green SiC precursor investments toward Gujarat and Karnataka, diversifying supply origins beyond Chinese coastal clusters. BIS alignment with IEC semiconductor substrate specifications streamlines import substitution for foundry customers. Bangalore and Hyderabad concentrate procurement decisions for power electronics customers under harmonized testing norms.
South Korea
Korean automakers in Ulsan deploy Green SiC traction inverters for next-generation EV platforms, anchoring regional demand for high-voltage power modules. Domestic industrial policy supports materials localization for automotive semiconductor supply chains. Daegu-Gyeongbuk clusters coordinate with Japanese METI protocols to accelerate substrate qualification timelines.
Indonesia
Excess geothermal and captive coal generation in Sulawesi and Halmahera enables energy-cost arbitrage for Acheson process operators. Nickel-smelter power surplus attracts alternative production bases outside China for alpha-phase crystal synthesis. Provincial energy pricing undercuts Yangtze River Delta captive power arrangements for furnace-intensive operations.
Asia-Pacific Green Sic Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tier-one foundries consolidating procurement through long-term supply agreements while spot markets serve abrasive and refractory applications. The vendor base organizes around three strategic archetypes: polysilicon heritage players controlling precursor supply, foundry-integrated domestic producers securing provincial guidance benefits, and petroleum coke specialists differentiating on feedstock purity. Competitive moves concentrate on capacity expansion in 200mm substrate formats and backward integration into Acheson furnace operations to secure energy cost positions.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. represents the polysilicon heritage archetype with established precursor supply chain control. Chinese domestic producers exemplify the foundry-integrated model, with Futong Industry Co. Limited occupying a position tied to Hefei and Xi'an industrial corridor partnerships. Norwegian-sourced feedstock specialists anchor the petroleum coke differentiation vector, with Fiven ASA sitting within the low-boron contamination tier for 6-inch substrate supply.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Futong Industry Co. Limited |
| Washington Mills |
| General Abrasivi Srl |
| CHOKO CO., LTD. |
| Fiven ASA |
| Zibo Jinjiyuan Abrasives Co. Ltd. |
| Snam Abrasives Pvt. Ltd. |
| Henan Qingjiang Industrial Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Petroleum coke feedstock purity grades cascade through substrate pricing tiers, with Norwegian low-boron material commanding premium multiples over domestic Chinese supplies before reaching Hefei foundry procurement desks. Acheson furnace energy intensity in the Yangtze River Delta anchors cost structures, compressing margins for operators lacking captive power arrangements while Indonesian nickel-smelter surplus electricity enables competitive positioning for alternative production bases.
Pricing Analysis
Short lead-time premiums dominate wafer procurement, with 18-month qualification cycles forcing foundry customers toward long-term offtake contracts carrying 36-month price locks. Three-tier pricing structure across AEC-Q101 automotive certification, industrial-grade, and abrasive feedstock separates premium capture from commodity erosion. Pricing pressure stems from 200mm substrate yield compression as defect density characterization outpaces depreciation timelines. Automotive power module manufacturers exhibit lowest price sensitivity, while renewable energy inverter procurement delays adoption until cost parity with silicon IGBTs.
Supply Chain Analysis
Regional distribution centers in Nagoya and Taoyuan coordinate hub-and-spoke patterns for epitaxial-ready wafer delivery to tier-one foundries. Supply concentrates in China, Japan, and Taiwan, with alpha-phase crystal synthesis drawing from petroleum coke, high-purity silica, and graphite electrode inputs. Single-source vulnerability in Norwegian feedstock creates qualification bottlenecks for 6-inch substrate producers. Distribution runs through Yangtze River Delta foundry clusters under provincial industrial guidance directing domestic qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green SiC MOSFETs displace silicon IGBTs in 800V EV architectures, compressing technology-transition timelines across automotive power electronics procurement.
For Market Incumbents: To counter Indonesian energy-cost arbitrage from nickel-smelter power surplus, secure backward integration into Acheson furnace operations with captive geothermal or coal generation in Sulawesi-equivalent cost positions. Prioritize METI-compliant automated defect mapping certification to maintain procurement screening advantages in Nagoya and Hiroshima inverter supply contracts. For New Entrants and Emerging Players: Begin with abrasive-grade powder supply to Japanese automotive friction material formulators in Nagoya, where polysilicon heritage incumbents underinvest in commoditized segments. Target India's Gujarat precursor investments under PLI scheme alignment, leveraging BIS-IEC harmonization to streamline foundry customer qualification in Bangalore. For Investors and Strategic Acquirers: First operational 8-inch wafer qualification announcement is the leading indicator that cost parity thresholds for silicon IGBT displacement have been crossed. Position acquisition screening around polysilicon heritage players with established precursor supply chain control and CVD reactor platform consolidation capability. Watch METI-funded consortia inspection protocol deployment as signal of automotive certification barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acheson Furnace Operations | Captive power arrangements in Indonesia undercut Yangtze River Delta energy costs for alpha-phase synthesis. |
| 200mm Wafer Qualification Acceleration | First-mover 8-inch substrate certification unlocks mass-market EV inverter procurement from Toyota City OEMs. |
| METI Inspection Protocol Certification | Automated defect mapping mandates from Japanese consortia shift power module procurement screening criteria. |
| Long-term Foundry Supply Agreements | 36-month price locks with Hefei and Xi'an clusters displace spot-market transactions for tier-one IDMs. |
| PLI Scheme Precursor Investment | India's Gujarat and Karnataka incentives diversify supply origins beyond Chinese coastal clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CVD reactor equipment vendors, Acheson furnace operators, foundry procurement managers, and automotive power module qualification engineers. MIIT substrate standards documentation, METI consortium disclosure filings, and BIS testing norm alignment records provided regulatory validation. Bottom-up wafer capacity buildout tracking and top-down EV powertrain content-per-vehicle estimates were triangulated against precursor import volumes.
Reconciliation of production capacity announcements, equipment vendor order backlogs, and foundry customer qualification timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, voltage class architecture, fabrication technology, and end-use thermal requirement tier. CAGRs were derived from supply-demand gap analysis incorporating 200mm substrate yield learning curves and automotive platform electrification roadmaps from Korean and Japanese OEMs.
Underlying measurement precision varies by segment; wafer-grade substrates carry tighter precision than abrasive powders due to qualification timeline visibility. Forecasts reflect documented assumptions regarding 8-inch cost parity thresholds and dual carbon mandate capital allocation continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Halloysite Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Lab Grown Diamonds Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Asia-Pacific Reflective Tape Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Polyimide Foam Market