
 Asia-Pacific Colloidal Silica Market | 2026-2036
Asia-Pacific Colloidal Silica Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Colloidal Silica Market Outlook
Japanese colloidal silica production is shifting toward higher-purity grades for advanced node semiconductor manufacturing. Nissan Chemical Corporation leverages its proprietary ion-exchange technology to dominate electronics-grade supply across East Asia. FUSO CHEMICAL Co., Ltd. anchors regional alkali-stabilized output through integrated sodium silicate operations in Osaka. Evonik Industries AG competes via surface-modified product lines tailored to precision coating applications.
Colloidal silica comprises nanoscale amorphous silicon dioxide particles dispersed in aqueous or organic media, typically manufactured through sodium silicate ion-exchange or sol-gel processes yielding particle sizes from 5 to 150 nanometers. The material functions primarily as a polishing abrasive, binder, and rheology modifier across precision industrial applications. Alkali-stabilized formulations retain the largest volume share due to their cost efficiency in construction and textile processing, while surface-modified grades command premium positioning in electronics CMP slurries where particle uniformity directly determines wafer yield. Aqueous dispersions show the fastest trajectory as water-based formulations displace solvent systems under environmental compliance pressure.
Japan's METI enforces nanomaterial handling protocols under the Chemical Substances Control Law, while China's SAMR administers GB standards for industrial silica purity classifications. South Korea's MFDS regulates pharmaceutical-grade colloidal silica through biocompatibility testing mandates that restrict import access for uncertified suppliers. Buyers must track evolving registration requirements across these three jurisdictions to secure uninterrupted supply for semiconductor and pharmaceutical end uses.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are driving colloidal silica consumption through aggressive capacity expansion for chemical mechanical planarization slurries, while China's GB standards and Japan's METI circular economy roadmap simultaneously tighten purity specifications and reshape supplier qualification requirements.
Growth Catalysts
- Advanced node semiconductor manufacturing:Taiwan and South Korean foundries are consuming higher-purity colloidal silica grades as they migrate to 3nm and 2nm process nodes, pulling demand from legacy construction applications.
- China's dual carbon goals:The country's MEE enforcement of water-based formulation mandates is accelerating displacement of solvent-based silica dispersions in coatings and adhesives.
- Japan's METI circular economy roadmap:This framework incentivizes closed-loop silica recovery from semiconductor polishing waste, creating certified recycled feedstock streams for industrial applications.
Market Restraints
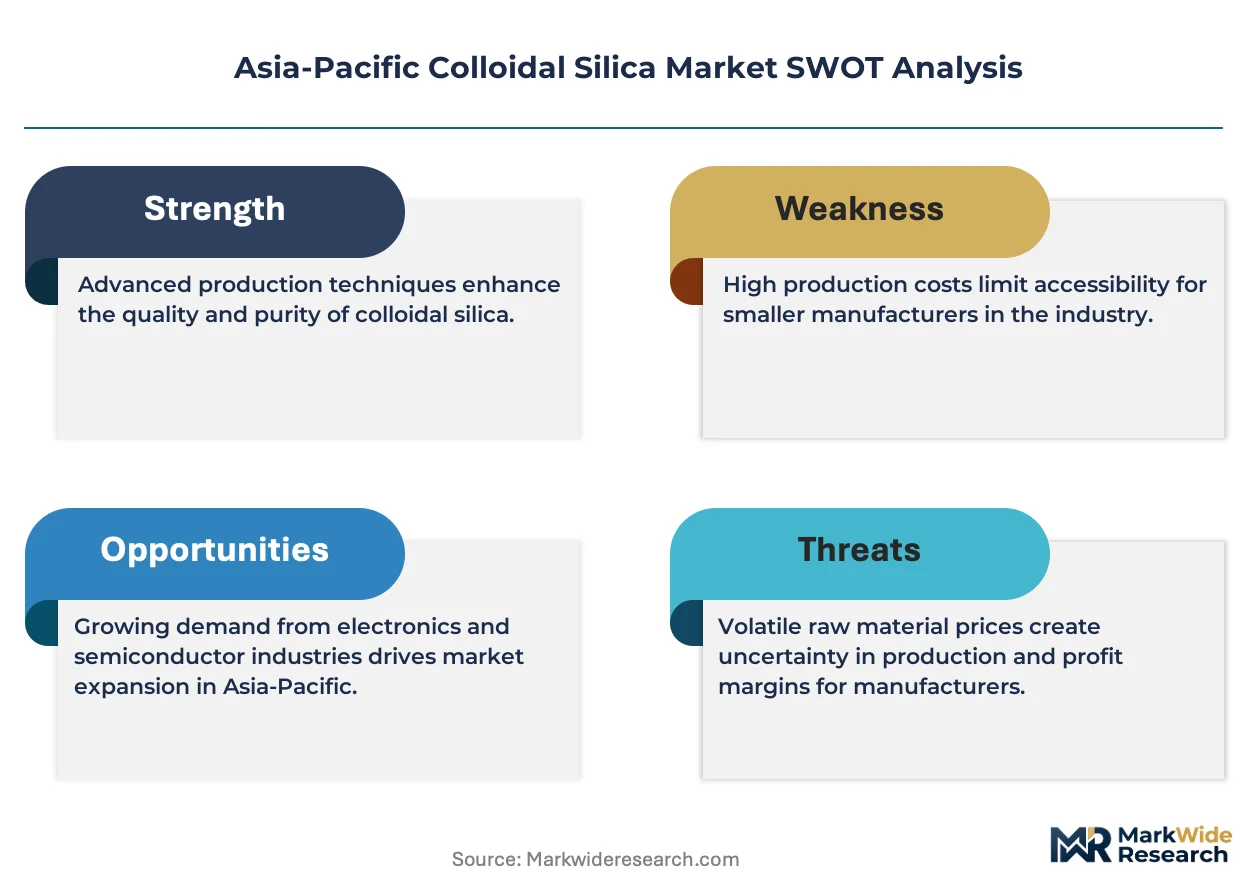
- Sodium silicate input volatility:Alkali-stabilized colloidal silica production depends on sodium silicate pricing, which fluctuates with energy costs and soda ash supply constraints in China.
- Supply concentration in Osaka-Kobe corridor:Japanese integrated sodium silicate-to-colloidal silica operations control critical electronics-grade capacity, creating geographic single-point vulnerability.
- Particle size distribution limitations:Conventional ion-exchange processes struggle to achieve the sub-30nm monodispersity required for next-generation CMP slurries without costly sol-gel retrofitting.
Strategic Opportunities
- India's electronics manufacturing clusters:The country's PLI scheme for semiconductor and display manufacturing is attracting colloidal silica suppliers to establish local blending operations in Gujarat and Tamil Nadu.
- Surface-modified silica for battery applications:Silica nanoparticles functionalized with conductive coatings are emerging as rheology modifiers in lithium-ion electrode slurries for electric vehicle cell production.
- China's GB/T nanomaterial standards:New certification pathways for industrial silica purity classifications are creating first-mover advantages for suppliers achieving GB-compliant production ahead of mandatory enforcement.
Industry Challenges
- Cleanroom-grade logistics infrastructure:Electronics-grade colloidal silica requires ISO Class 5-7 handling through final delivery, demanding specialized tanker fleets that few regional carriers maintain.
- Cross-border registration complexity:South Korea's MFDS pharmaceutical-grade silica certification requires 18-24 month biocompatibility testing timelines that delay market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Colloidal Silica Market |
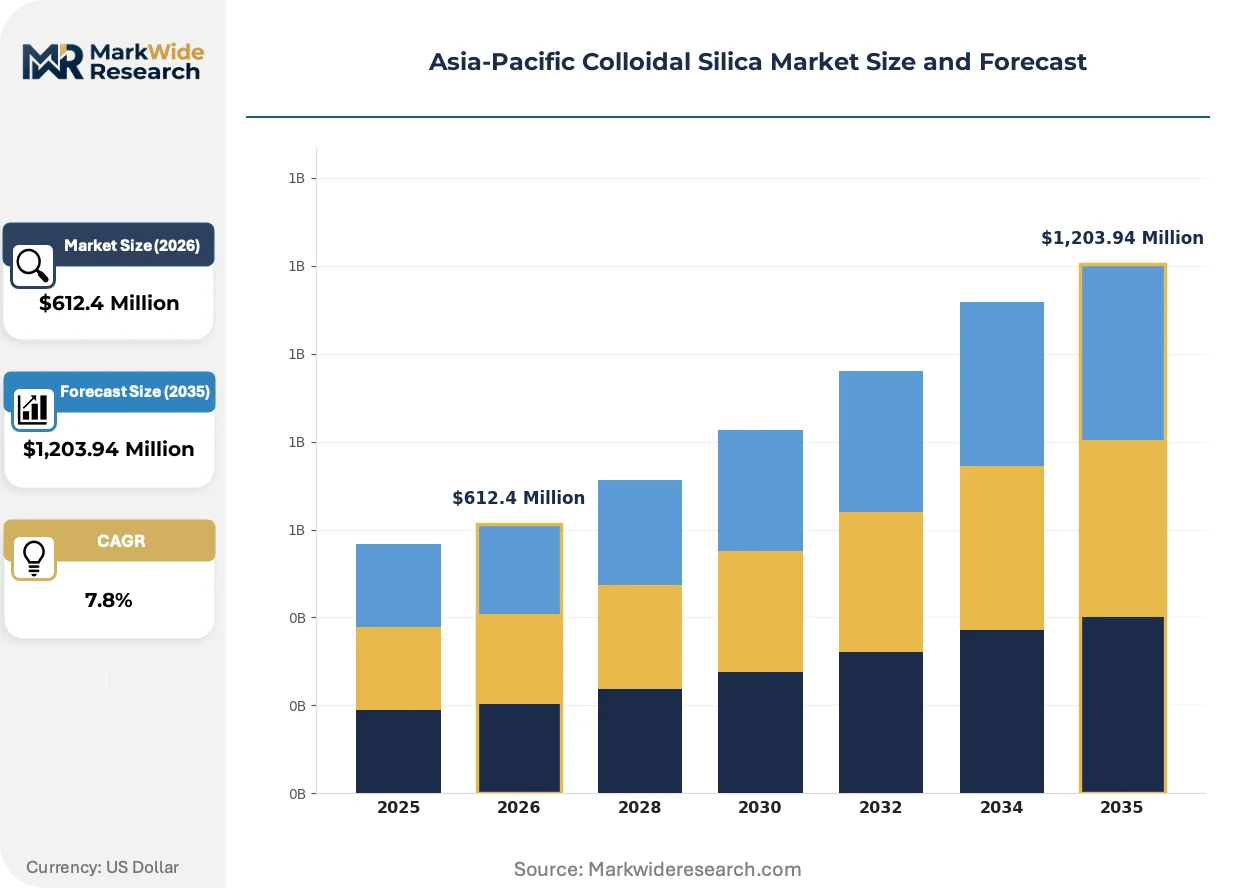
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkali-Stabilized, Acid-Stabilized, Surface-Modified, Aqueous Application: Paints, Adhesives, Coatings, Personal Care End User: Electronics, Textiles, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | W. R. Grace & Co., Nouryon, Ecolab, Evonik Industries AG, Nissan Chemical Corporation, Cabot Corporation, FUSO CHEMICAL Co., Ltd., Merck KGaA, Nyacol Nano Technologies Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Colloidal Silica Market Strategic Shifts
Colloidal silica manufacturing is undergoing process intensification as semiconductor-grade purity requirements collide with sustainability mandates, forcing technology choices between ion-exchange optimization and sol-gel reinvention.
Surface-modified colloidal silica with amino-functionalized coatings is converging with precision coating applications in display manufacturing. Panel fabricators in South Korea and Taiwan are adopting these grades at accelerating rates for anti-reflective layer deposition. This convergence is compressing the performance gap between commodity alkali-stabilized products and premium electronics grades.
China's SAMR administration of GB standards for industrial silica purity classifications is tightening allowable metal ion contamination thresholds. This regulatory tightening is disqualifying legacy sodium silicate-derived production for semiconductor end uses. Electronics-grade suppliers are responding by segregating production lines and implementing batch-level traceability systems.
Direct procurement contracts between colloidal silica producers and semiconductor foundries are displacing distributor-mediated supply in Taiwan and South Korea. Foundry technical teams now specify particle size distribution curves and surface chemistry parameters in master service agreements. This pattern is most visible in Hsinchu and Pyeongtaek manufacturing corridors where just-in-time slurry blending occurs adjacent to wafer fabs.
Asia-Pacific Colloidal Silica Market Segmentation
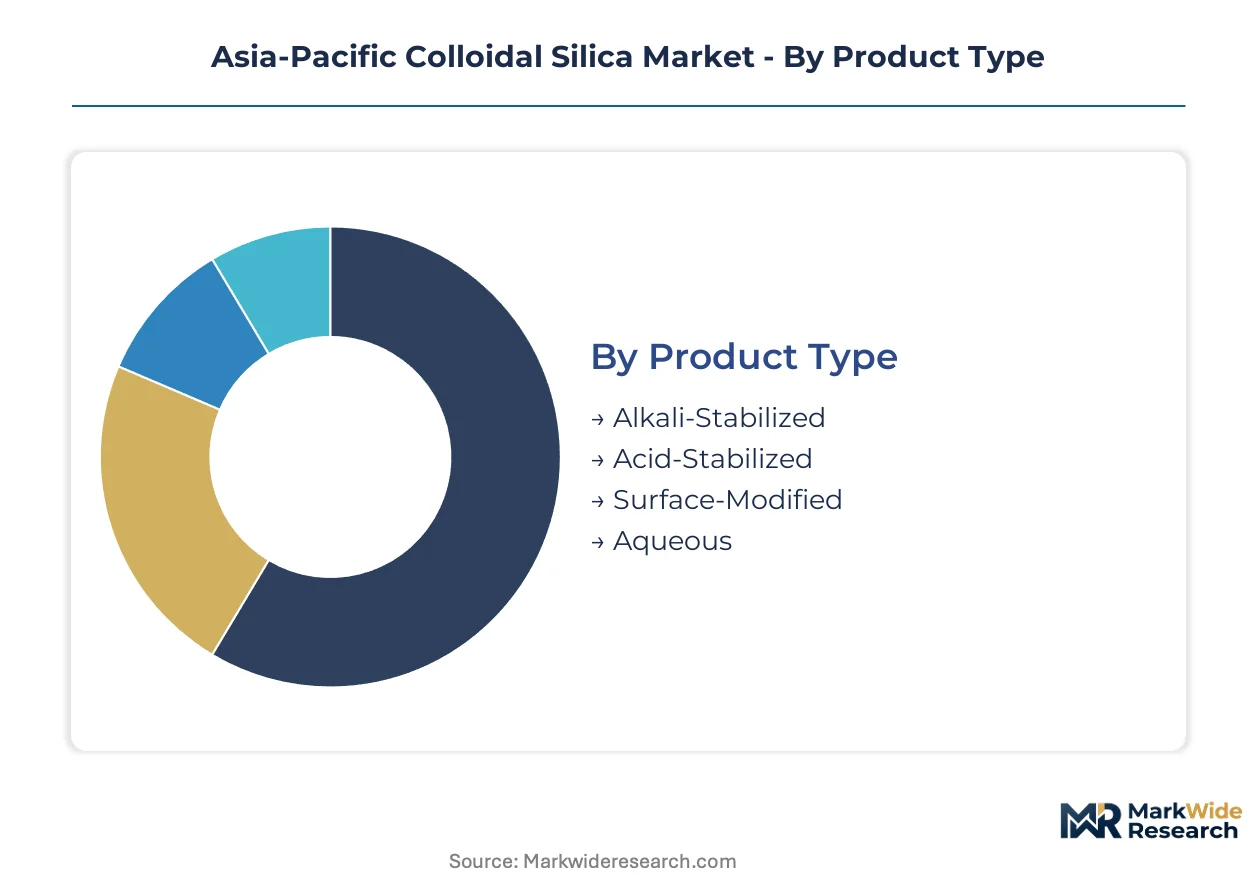
Segmentation in the Asia-Pacific colloidal silica market reveals how capital allocation, regulatory compliance, and end-use purity requirements fragment supply chains. Manufacturers must align production assets with specific grade specifications to serve semiconductor foundries, construction formulators, and pharmaceutical compounders simultaneously.
Product Type:
Capital intensity varies sharply across production technologies, with surface-modified grades demanding specialized functionalization reactors and cleanroom finishing infrastructure.
- Alkali-Stabilized:Sodium silicate-derived dispersions stabilized with hydroxide counterions dominate volume output. Construction and textile processors across China's eastern coastal provinces absorb the majority of regional alkali-stabilized supply for concrete densification and fabric finishing applications.
- Surface-Modified:Amino-functionalized and epoxy-coated particles require multi-stage surface chemistry operations in ISO Class environments. Taiwan and South Korean semiconductor foundries specify these grades for CMP slurry formulations where particle zeta potential directly controls polishing selectivity.
- Acid-Stabilized:Proton-stabilized sols serve precision coating formulators requiring acidic pH compatibility.
- Aqueous:Water-based dispersions displace solvent carriers under Japan's METI circular economy mandates and China's MEE environmental enforcement.
Alkali-stabilized formulations absorb the bulk of installed capacity; surface-modified grades are expanding most quickly.
Application:
Application segmentation tracks how colloidal silica functions as abrasive, binder, or rheology modifier across distinct formulation chemistries.
- Coatings:Anti-corrosion and anti-reflective layers in display manufacturing leverage particle size uniformity for optical clarity. South Korean panel fabricators in Gyeonggi Province specify sub-50nm grades for thin-film deposition processes.
- Adhesives:Silica nanoparticles function as thixotropic agents in structural bonding formulations. Japan's automotive adhesive compounders favor surface-modified grades for enhanced substrate wetting.
- Paints:Architectural and industrial coatings incorporate colloidal silica for scrub resistance and gloss retention.
- Personal Care:Cosmetic formulators exploit silica's matting and thickening properties in skin care and sun care products.
Coatings command the deepest technical specifications; adhesives are climbing fastest as electric vehicle battery assembly expands.
End User:
End-user segmentation exposes divergent purity thresholds, with electronics and pharmaceuticals imposing contamination limits orders of magnitude stricter than construction or textiles.
- Electronics:Semiconductor foundries and display manufacturers drive specification intensity. Taiwan's Hsinchu corridor and South Korea's Pyeongtaek cluster source electronics-grade silica through direct procurement contracts with batch-level traceability.
- Pharmaceuticals:Excipient and active ingredient applications require MFDS biocompatibility certification in South Korea and PMDA pharmaceutical-grade registration in Japan.
- Construction:Concrete admixture and refractory binder applications tolerate higher alkali content and broader particle distributions.
- Textiles:Fabric finishing and anti-slip treatments consume cost-optimized alkali-stabilized grades.
Electronics absorbs the majority of premium-grade capacity; pharmaceuticals is gaining share fastest as regional generic drug manufacturing scales.
Distribution Channel:
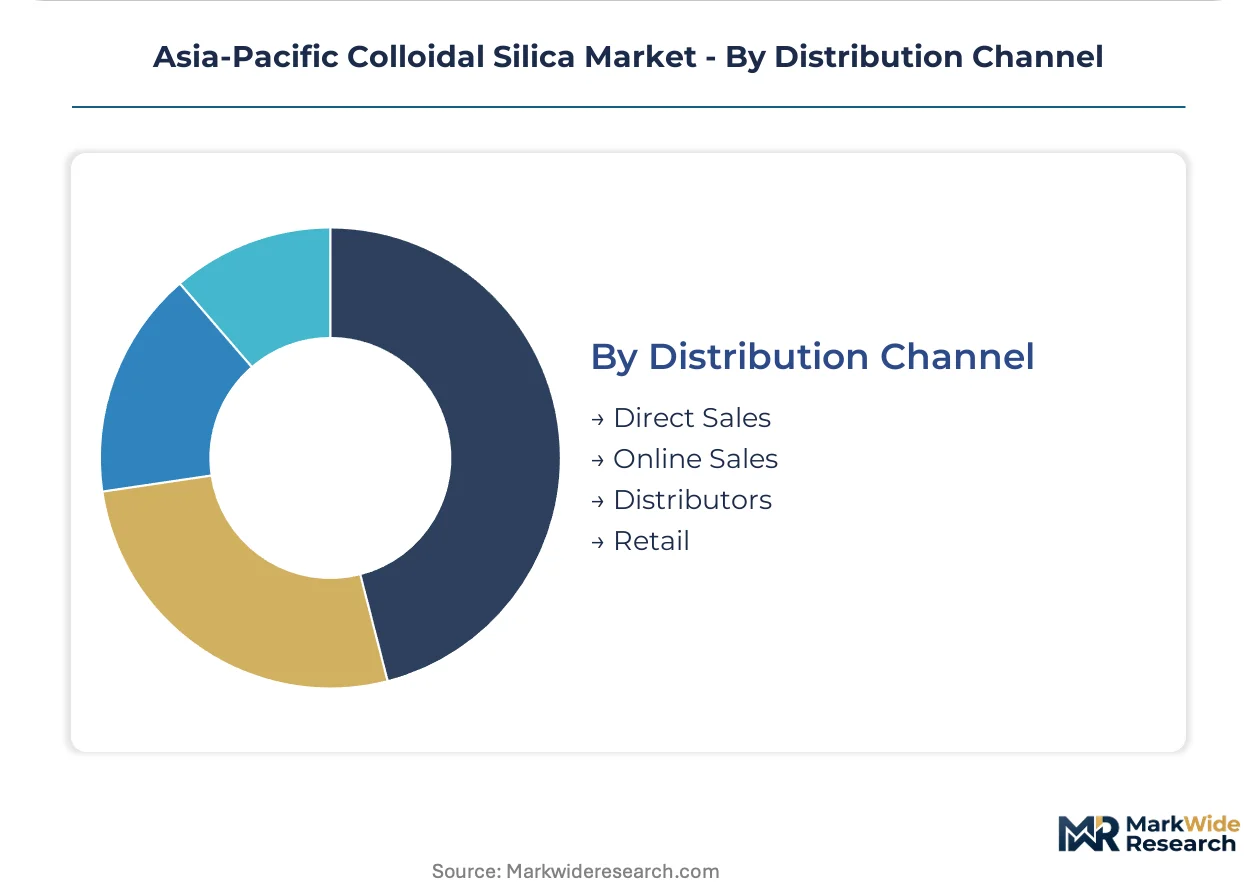
Channel segmentation reflects how technical complexity and volume scale determine whether producers sell directly or through intermediaries.
- Direct Sales:Semiconductor foundries and multinational coating formulators negotiate master service agreements specifying particle size distribution curves and surface chemistry parameters. This channel captures electronics-grade volume in Taiwan and South Korea.
- Distributors:Regional chemical distributors serve construction and textile mid-markets with standardized alkali-stabilized grades.
- Online Sales:E-procurement platforms gain traction for laboratory-scale quantities and sample requests.
- Retail:Limited to personal care and small-volume adhesive applications.
Direct sales dominates value concentration; distributor channels are expanding most quickly as Indian and Southeast Asian manufacturing clusters mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-Kobe's integrated sodium silicate corridor anchors electronics-grade colloidal silica supply across East Asia. This feedstock concentration shapes procurement patterns for semiconductor foundries throughout the region.
China
Shanghai and Suzhou manufacturing clusters consume alkali-stabilized grades for construction and textile applications while Hsinchu-serving traders stock electronics-grade inventory. GB standards administered by SAMR tighten metal ion thresholds for semiconductor end uses. Eastern coastal provinces from Jiangsu to Guangdong concentrate demand where electronics manufacturing dominates regional procurement.
Japan
Osaka-based integrated producers supply ion-exchange refined grades to domestic precision coating formulators and Taiwan semiconductor foundries. METI's circular economy roadmap incentivizes closed-loop silica recovery from polishing waste streams. The Kansai industrial corridor maintains captive sodium silicate-to-colloidal silica operations for electronics-grade output.
South Korea
Pyeongtaek and Yongin foundries specify surface-modified grades for advanced node CMP slurries as Samsung and SK Hynix expand capacity. MFDS pharmaceutical-grade certification requirements restrict import access for uncertified suppliers through biocompatibility testing mandates. Direct procurement contracts now displace distributor channels for high-purity volumes.
Taiwan
Hsinchu Science Park fabs source electronics-grade silica through master service agreements specifying particle size distribution parameters. The island's semiconductor ecosystem pulls premium-grade supply from Japanese and domestic blending operations. Cleanroom-grade logistics infrastructure requirements favor established suppliers with ISO Class 5-7 handling capabilities.
India
Gujarat and Tamil Nadu electronics manufacturing clusters under PLI scheme incentives attract colloidal silica suppliers to establish local blending capacity. BIS standards for industrial chemicals create compliance pathways for construction-grade applications. Regional distributors serve mid-market coatings and adhesives processors while semiconductor-grade volumes remain import-dependent.
Asia-Pacific Colloidal Silica Market Competitive Environment
Global majors compete with regional champions across ion-exchange technology and surface modification capabilities. The vendor base stratifies into three tiers: integrated sodium silicate producers with captive feedstock, specialized electronics-grade refiners, and regional distributors serving construction mid-markets. Dominant competitive moves include backward integration into sodium silicate production and direct procurement contracting with semiconductor foundries.
Within the integrated producer tier, Nissan Chemical Corporation and FUSO CHEMICAL Co., Ltd. anchor Japanese electronics-grade supply through Osaka-based operations. Evonik Industries AG occupies a position among surface-modified specialists competing via functionalized product lines. These three exemplify how technology specialization and geographic feedstock access determine competitive positioning across alkali-stabilized and premium-grade segments.
| Leading Market Players |
|---|
| W. R. Grace & Co. |
| Nouryon |
| Ecolab |
| Evonik Industries AG |
| Nissan Chemical Corporation |
| Cabot Corporation |
| FUSO CHEMICAL Co., Ltd. |
| Merck KGaA |
| Nyacol Nano Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundries in Taiwan and South Korea command electronics-grade colloidal silica through direct master service agreements, locking in contract-based long-term offtake pricing that insulates premium-tier suppliers from spot-market volatility in alkali-stabilized grades.
Pricing Analysis
Technical service bundling separates electronics-grade contracts from commodity transactions, with foundry agreements incorporating particle characterization protocols and cleanroom delivery guarantees as unbundled add-ons for construction-grade buyers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with surface-modified CMP slurry feedstock commanding substantial premiums over textile-finishing alkali-stabilized volumes. Cost compression in standard-tier construction applications is intensifying because Chinese sodium silicate input costs fluctuate with regional energy pricing. Construction formulators in China's eastern coastal provinces exhibit highest price sensitivity, while Taiwan semiconductor fabs prioritize batch-level traceability over unit economics.
Supply Chain Analysis
Specialized cleanroom technicians and ion-exchange process engineers concentrate in Japan's Osaka-Kobe corridor and South Korea's Yongin-Pyeongtaek cluster, constraining rapid capacity scaling for electronics-grade output. Manufacturing gravity centers on Japan, South Korea, and Taiwan, with sodium silicate feedstock, surface functionalization reagents, and ISO Class handling infrastructure serving as critical input dependencies. Single-source vulnerability pervades the Osaka-Kobe sodium silicate corridor, where integrated producers control captive feedstock for regional electronics-grade supply. Distribution runs through direct procurement channels for semiconductor foundries and regional chemical distributors for construction mid-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR-administered GB standards for nanomaterial purity classifications erect a cost-of-compliance barrier that favors incumbent suppliers with segregated production lines and batch traceability systems already operational.
For Market Incumbents: Anchor electronics-grade margins by deepening backward integration into sodium silicate production and securing direct procurement contracts with Taiwan and South Korean foundries expanding 3nm and 2nm capacity. Defensive positioning requires investment in sol-gel retrofitting capabilities to achieve sub-30nm monodispersity specifications that conventional ion-exchange processes cannot satisfy, neutralizing emerging surface-modification specialists. For New Entrants and Emerging Players: Sol-gel process intensification technologies offer entry pathways into premium CMP slurry feedstock supply without competing against entrenched Osaka-Kobe ion-exchange infrastructure. India's Gujarat and Tamil Nadu electronics manufacturing clusters under PLI scheme incentives represent the most penetrable geography, with local blending operations qualifying for domestic content requirements that exclude pure-import suppliers. Go-to-market execution should prioritize pharmaceutical-grade certification partnerships with South Korean MFDS to circumvent 18-24 month biocompatibility testing barriers. For Investors and Strategic Acquirers: The window for entry favors surface-modification technology specialists with functionalized silica capabilities applicable to lithium-ion battery electrode slurries and precision coating applications. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, with acquisition targets requiring GB/T nanomaterial certification pathways or established MFDS pharmaceutical-grade registrations. Watch for mandatory enforcement timelines on China's GB standards as the inflection indicator separating compliant first-movers from disqualified legacy producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply insulates electronics-grade margins from Chinese soda ash volatility and energy cost swings. |
| Surface Modification Technology Licensing | Functionalized particle capabilities unlock battery electrode and precision coating applications beyond semiconductor CMP. |
| GB/T Nanomaterial Certification Program | First-mover compliance with SAMR purity thresholds secures qualification for China's domestic semiconductor supply chain. |
| Direct Procurement Contracting | Master service agreements with Taiwan and South Korean foundries displace distributor channels and lock in volume commitments. |
| Closed-Loop Silica Recovery Operations | METI circular economy incentives reward certified recycled feedstock streams from semiconductor polishing waste. |
Study Parameters
Independent corroboration across plant managers at Japanese integrated producers, procurement leads at Taiwan semiconductor foundries, and distribution channel partners in China's eastern coastal provinces underwrites the qualitative findings in this study. Primary interviews with technical R&D directors specializing in ion-exchange and sol-gel processes were cross-referenced against secondary validation from customs and trade data, Japanese METI industrial statistics, Chinese SAMR regulatory filings, and South Korean MFDS certification records. Bottom-up capacity assessments and top-down demand modeling were reconciled through iterative triangulation.
Comparable-period anchoring to historical sodium silicate pricing cycles and semiconductor capital expenditure waves established the forecast window's baseline trajectory. The analytical framework models grade tier, end-use industry, and regional production hub segmentation throughout the forecast period, with CAGRs derived from production capacity buildout schedules and foundry technology node migration timelines. Forecast inputs incorporate METI circular economy policy implementation pace and SAMR GB standards enforcement thresholds.
Several conditions sit outside the modeled scope, including unannounced foundry capacity expansion decisions, abrupt shifts in sodium silicate feedstock availability, and accelerated regulatory harmonization between Chinese, Japanese, and South Korean nanomaterial frameworks. Forecasts reflect documented assumptions regarding technology node migration rates and cleanroom logistics infrastructure scaling. Material deviation in foundry capex commitments or GB standards enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Barium Borate Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
UV Stabilized Films Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Marine Mineral Complexes from Mediterranean Shells Market
Specialty Materials
Silicone Gel Market
Specialty Materials
Magnesium Fluoride Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Global Liquid Crystal Polymer (LCP) Films and Laminates Market
Specialty Materials
Global Graphic Film Market